
 Europe Autoimmune Disease Diagnostics Market | 2026-2036
Europe Autoimmune Disease Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Autoimmune Disease Diagnostics Market Insights
Modular assay panel design is decoupling instrument placement from reagent procurement across European diagnostic networks. Abbott Laboratories leverages its integrated immunoassay platform to anchor hospital laboratory contracts in France and Italy. Siemens Healthineers competes through decentralized analyzer deployment that sustains recurring consumable revenue streams. Bio-Rad Laboratories differentiates via specialized autoimmune quality controls that extend its influence beyond direct test manufacturing.
Europe autoimmune disease diagnostics encompasses laboratory and point-of-care technologies that detect autoantibodies, immune complexes, and inflammatory markers through immunochemical, molecular, and cell-based methods, typically requiring serum or plasma specimens processed within controlled temperature parameters. These systems serve rheumatologists, clinical immunologists, and primary care physicians in discriminating self-directed immune pathology from infectious or malignant mimics. ELISA and immunofluorescence methods occupy mature positions in high-throughput laboratory workflows, while next-generation sequencing and mass spectrometry segments attract investment as clinicians pursue multiplexed biomarker signatures for complex presentations like Sjögren's syndrome. Diagnostic laboratories capture the dominant end-user margin pool, though homecare settings emerge as a channel where microfluidics technology enables capillary blood sampling with reduced phlebotomy dependency.
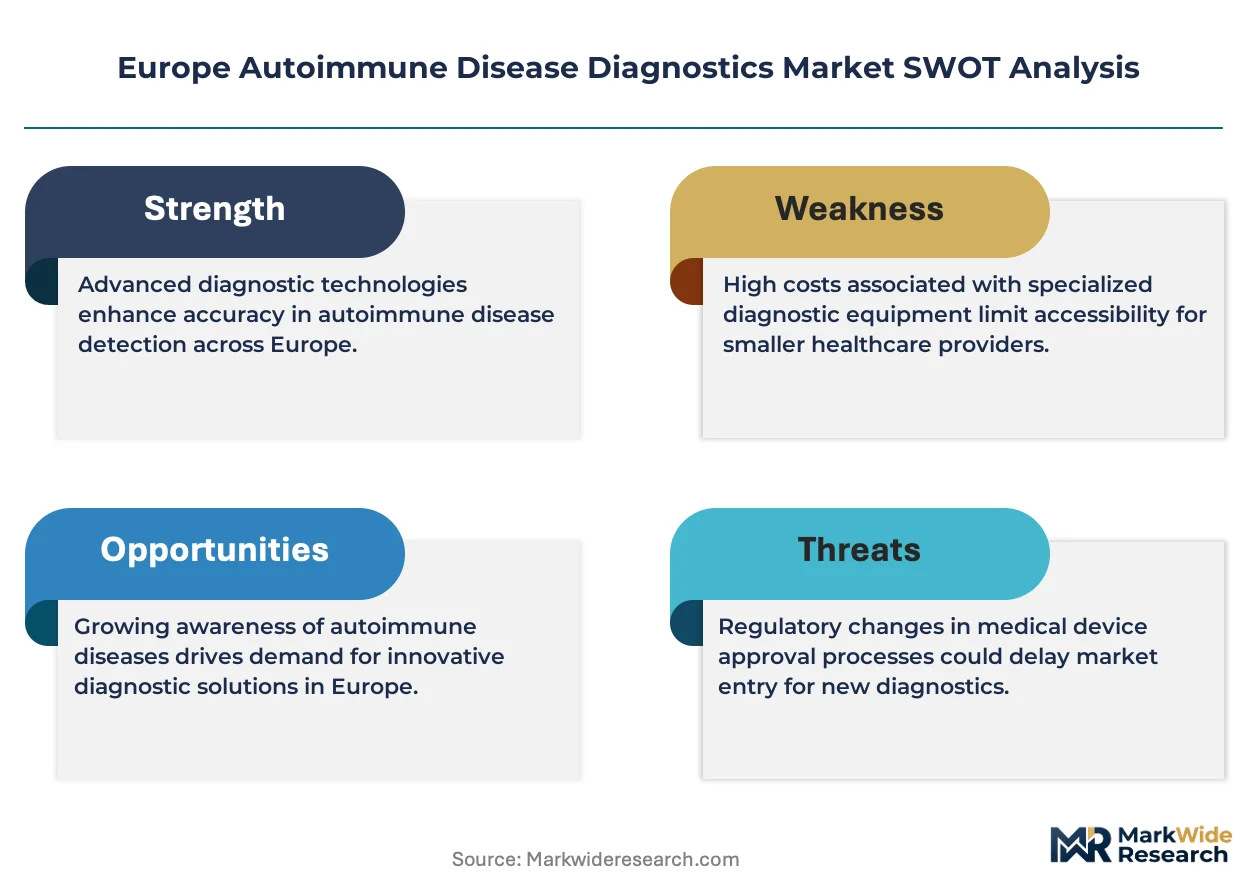
The EU In Vitro Diagnostic Regulation (IVDR) and EMA guidelines on companion diagnostics reshape product registration timelines and clinical evidence requirements for autoimmune test manufacturers seeking CE marking. France's ANSM and Germany's BfArM enforce national vigilance reporting that extends post-market surveillance obligations beyond initial conformity assessments. Stakeholders must monitor IVDR transition deadlines and notified body capacity constraints that determine which assay portfolios achieve sustained market access versus forced withdrawal.
Market Dynamics
The EU In Vitro Diagnostic Regulation is compressing commercialization timelines and forcing autoimmune test manufacturers to rebuild clinical evidence portfolios for legacy assays. Laboratories face portfolio rationalization decisions as notified body capacity constraints delay CE marking renewals.
Growth Catalysts
- IVDR compliance deadlines:Germany's BfArM enforcement of post-market surveillance obligations accelerates laboratory investment in validated autoimmune screening platforms. Diagnostic networks consolidate testing volumes to justify reagent rental economics.
- Rheumatology service expansion:France's hospital consolidation creates centralized autoimmune diagnostic hubs processing elevated systemic lupus erythematosus panel volumes. Regional laboratories capture economies of scale through automated immunofluorescence workflows.
- Multiplexed biomarker platforms:Mass spectrometry and next-generation sequencing convergence enables simultaneous autoantibody profiling for complex Sjögren's syndrome presentations. Academic medical centers in Italy pioneer integrated diagnostic algorithms.
Market Restraints
- Notified body bottleneck:IVDR transition deadlines strain conformity assessment capacity, forcing withdrawal of niche autoimmune assays from European markets. Smaller manufacturers lack resources for clinical performance studies.
- Reagent rental lock-in:Analyzer placement contracts with minimum volume commitments constrain laboratory flexibility to adopt competing platforms. Hospital procurement faces switching costs.
- Plasma specimen dependency:Cold chain logistics requirements limit point-of-care autoimmune testing expansion outside centralized laboratory networks. Capillary blood alternatives remain immature.
Strategic Opportunities
- Eastern European laboratory buildout:Poland and Romania invest in autoimmune diagnostic infrastructure as EU structural funds modernize healthcare systems. Greenfield facilities adopt latest immunoassay automation.
- Microfluidics-enabled home sampling:Reduced phlebotomy dependency opens chronic disease monitoring channels for rheumatoid arthritis patients. Regulatory pathways for self-collection devices clarify under IVDR.
- Companion diagnostic alignment:EMA guidelines on biologic therapy selection create demand for predictive autoantibody signatures. Pharmaceutical partnerships extend test utility beyond diagnosis into treatment guidance.
Industry Challenges
- IVDR technical documentation:Clinical evidence requirements for legacy ELISA assays demand retrospective studies that strain manufacturer archives. Analytical performance data gaps delay submissions.
- Specialized immunologist scarcity:Complex autoimmune case interpretation requires expertise concentrated in Western European academic centers. Telepathology networks attempt geographic redistribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Autoimmune Disease Diagnostics Market |
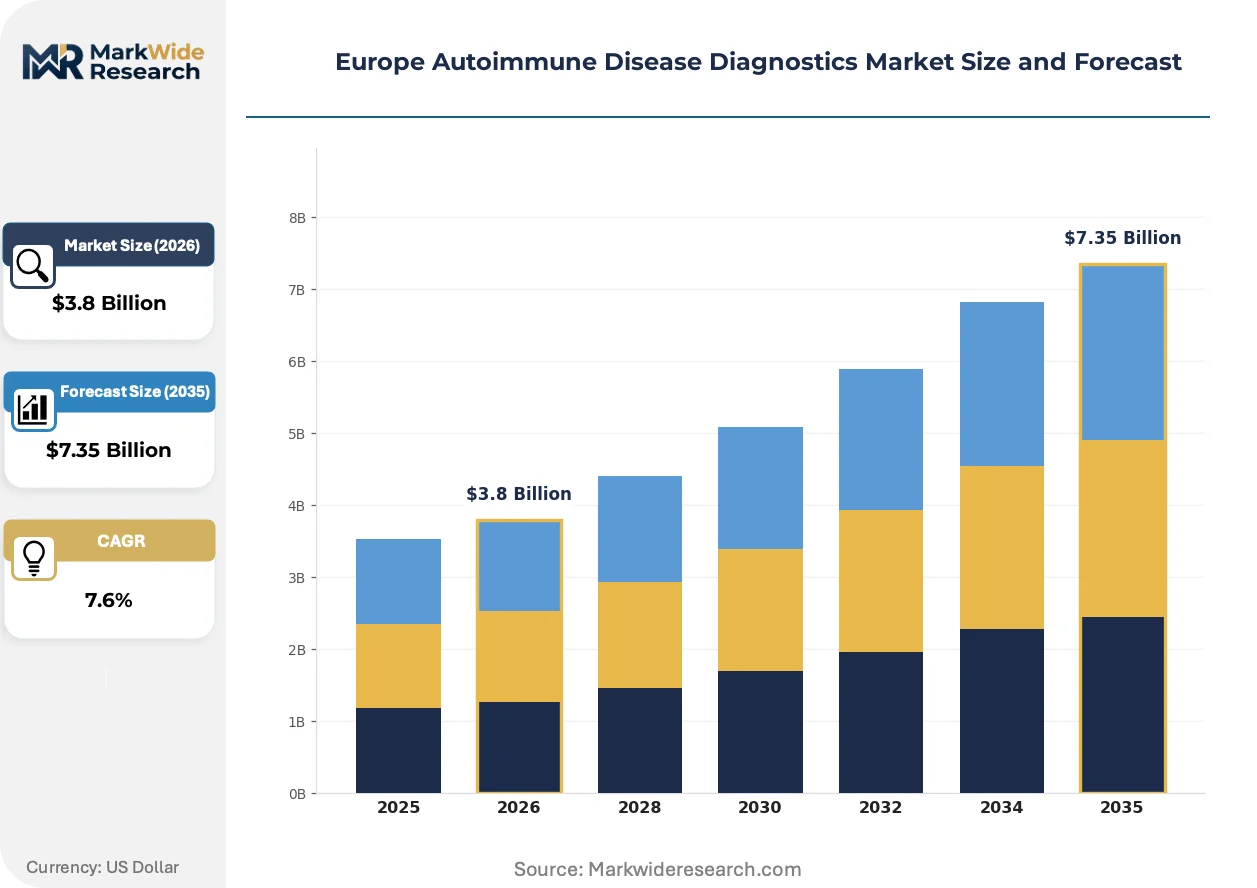
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA, Immunofluorescence, Agglutination Tests, Western Blot Indication: Rheumatoid Arthritis, Systemic Lupus Erythematosus, Multiple Sclerosis, Sjögren's Syndrome End User: Hospitals, Diagnostic Laboratories, Research Institutes, Homecare Settings Technology: Microfluidics, Genomics, Mass Spectrometry, Next-Generation Sequencing |
| Companies Covered | Abbott Laboratories, bioMérieux, Bio-Rad Laboratories, F. Hoffmann-La Roche, Thermo Fisher Scientific, Siemens Healthineers, Euroimmun AG, Trinity Biotech, Inova Diagnostics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Autoimmune Disease Diagnostics Market Trends and Innovations
Diagnostic platform architecture is converging toward modular reagent ecosystems that decouple instrument capital expenditure from consumable procurement flexibility. This structural shift enables laboratory networks to optimize assay menus without full platform replacement cycles.
Multiplexed autoantibody detection arrays are unifying previously discrete immunofluorescence and ELISA workflows into single-run comprehensive panels. Rheumatology departments in German university hospitals adopt these platforms to compress diagnostic odyssey timelines for undifferentiated connective tissue disease presentations. The technology is unifying laboratory economics by reducing repeat testing and enabling reflex algorithms that route complex cases directly to subspecialist interpretation.
France's ANSM and Germany's BfArM are tightening vigilance reporting requirements for autoimmune in vitro diagnostics under IVDR Article 83. Manufacturers must establish systematic post-market performance follow-up programs that capture real-world analytical sensitivity drift. High-volume systemic lupus erythematosus screening panels face enhanced scrutiny due to diagnostic consequence severity.
Hospital procurement departments are consolidating autoimmune testing contracts through multi-year reagent rental agreements that bundle analyzer placement with minimum volume commitments. France's hospital group purchasing organizations leverage scale to negotiate exclusive platform arrangements. This concentration is visible in the Ile-de-France and Bavaria regions where consolidated laboratory networks process regional autoimmune screening volumes.
Europe Autoimmune Disease Diagnostics Market Segmentation
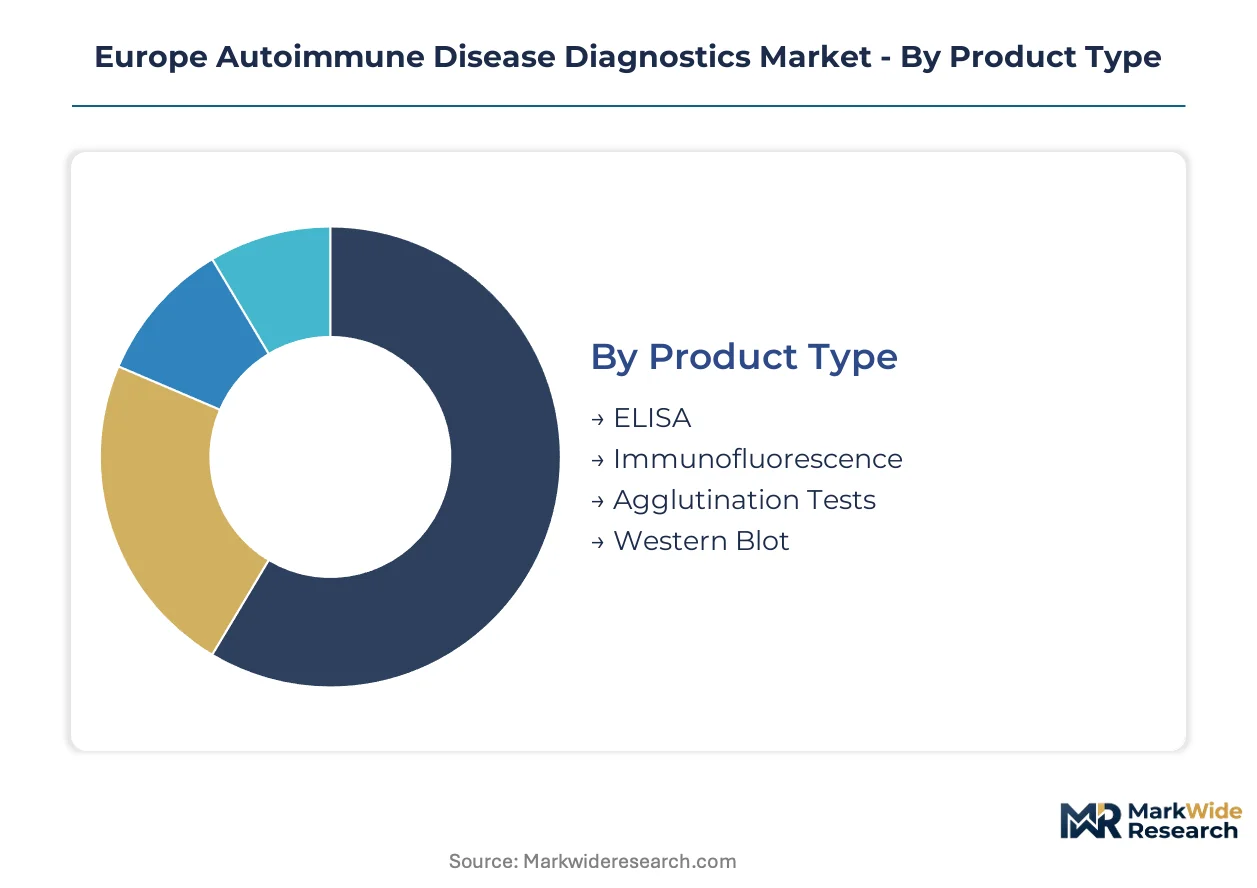
Autoimmune disease diagnostics in Europe fragment across multiple technical and operational dimensions that determine reimbursement pathways, regulatory scrutiny intensity, and procurement contract structures. Understanding these segment boundaries clarifies where IVDR compliance investments concentrate and which technology platforms capture laboratory capital expenditure cycles.
Product Type:
Standardized reagent formats dominate high-volume screening, while customizable panel configurations serve complex differential diagnosis requirements across European hospital networks.
- ELISA:Enzyme-linked immunosorbent assays deliver quantitative autoantibody titers with established analytical precision for rheumatoid factor and anti-CCP testing. German diagnostic laboratories deploy these platforms for standardized screening panels processed under BfArM vigilance reporting requirements.
- Immunofluorescence:Cell-based indirect immunofluorescence remains the reference standard for antinuclear antibody pattern interpretation, requiring specialized microscopy infrastructure and trained morphologists. French academic medical centers in Paris and Lyon maintain concentrated expertise hubs that handle complex systemic lupus erythematosus referrals from regional networks.
- Agglutination Tests:Latex agglutination methods provide rapid qualitative screening in resource-constrained settings.
- Western Blot:Confirmatory testing for specific autoantibody specificities follows positive screening results.
Most installed capacity flows through ELISA platforms. Expansion is steepest in immunofluorescence automation that reduces morphologist dependency.
Indication:
Prevalence variation and diagnostic consequence severity create tiered investment priorities across autoimmune disease categories.
- Rheumatoid Arthritis:Anti-cyclic citrullinated peptide and rheumatoid factor testing constitute the highest-volume autoimmune screening category in European primary care. Italian rheumatology networks process elevated panel volumes through centralized provincial laboratories.
- Systemic Lupus Erythematosus:Comprehensive autoantibody profiling for dsDNA, Sm, and phospholipid antibodies demands multiplexed platform capabilities. French hospital consolidation creates diagnostic hubs in Ile-de-France that capture regional referral volumes.
- Multiple Sclerosis:Cerebrospinal fluid oligoclonal banding and aquaporin-4 antibody testing require specialized neuroimmunology laboratory accreditation.
- Sjögren's Syndrome:SSA/Ro and SSB/La antibody detection serves complex differential diagnosis presentations.
Testing volumes concentrate in rheumatoid arthritis screening. Steepest expansion trajectory belongs to systemic lupus erythematosus multiplexed panels.
End User:
Capital intensity and regulatory compliance burden stratify market access across institutional settings.
- Hospitals:Inpatient and emergency departments require rapid turnaround autoimmune testing integrated with clinical decision support. Bavarian hospital networks consolidate testing through regional laboratory hubs that negotiate multi-year reagent rental contracts.
- Diagnostic Laboratories:Independent and hospital-affiliated laboratories capture the dominant margin pool through high-throughput automated workflows. Poland's expanding private laboratory sector adopts latest immunoassay platforms with EU structural fund support.
- Research Institutes:Academic medical centers pioneer next-generation sequencing and mass spectrometry applications for biomarker discovery.
- Homecare Settings:Microfluidics-enabled capillary blood collection devices emerge for chronic disease monitoring.
Diagnostic laboratories process the majority of test volumes. Homecare channels gain share fastest as IVDR clarifies self-collection device pathways.
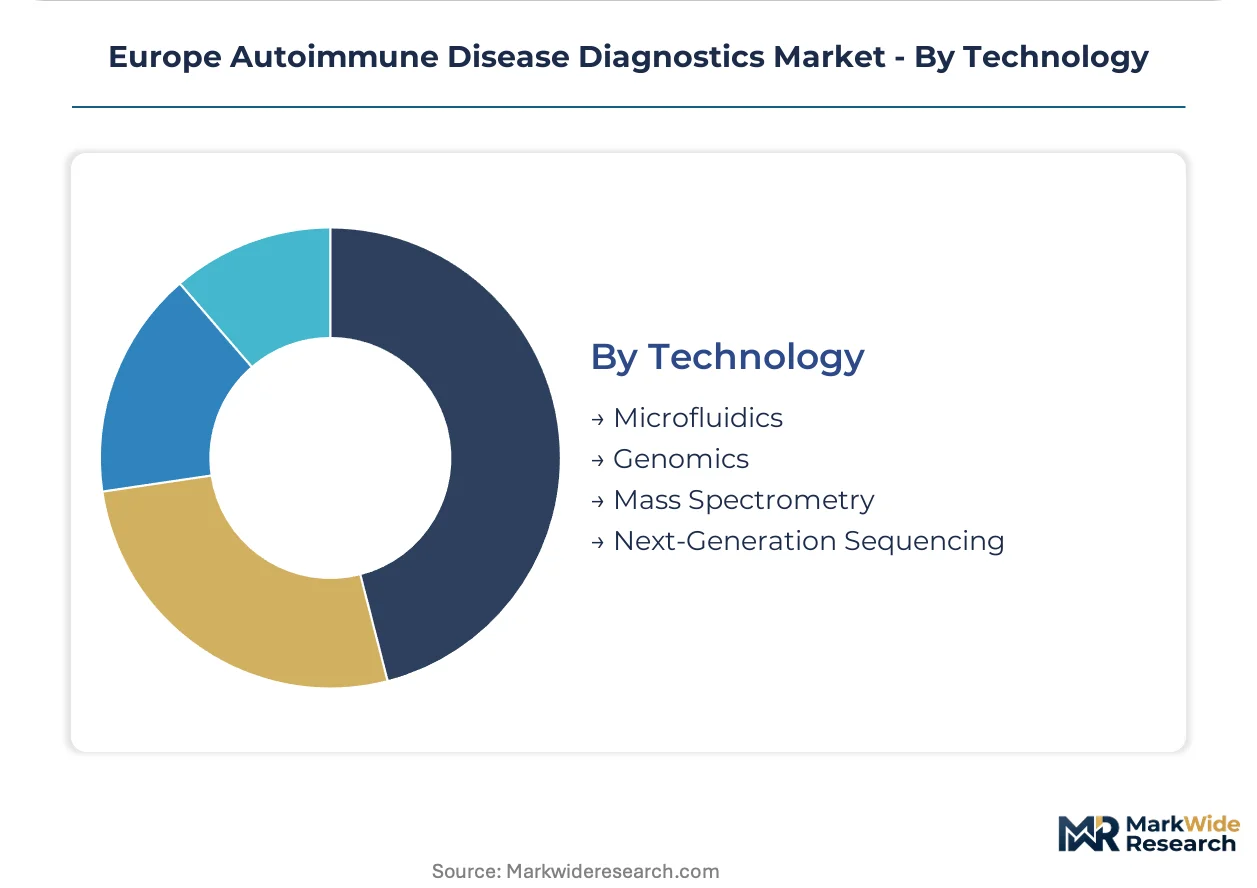
Technology:
Platform maturity and evidence requirements determine commercialization timelines under IVDR Article 83 post-market surveillance obligations.
- Microfluidics:Lab-on-chip devices enable point-of-care autoantibody detection with reduced specimen volume requirements. Italian research consortia pioneer integrated diagnostic algorithms combining microfluidic sample preparation with automated readout.
- Genomics:HLA typing and gene expression profiling extend diagnostic utility into pharmacogenomic guidance for biologic therapy selection.
- Mass Spectrometry:High-resolution autoantibody profiling converges with proteomics workflows in specialized reference laboratories.
- Next-Generation Sequencing:Multiplexed autoantigen discovery platforms attract academic investment for undifferentiated connective tissue disease characterization.
Microfluidics platforms attract the steepest R&D investment. Mass spectrometry expansion concentrates in German university hospital reference networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European autoimmune diagnostics industry traces its commercial roots to post-war Germany, where specialized immunoassay manufacturing scaled during the 1970s alongside the country's emerging laboratory equipment sector. France and the United Kingdom subsequently developed complementary diagnostic ecosystems centered on academic hospital networks. Contemporary market development reflects this tripartite foundation, with regulatory harmonization under IVDR now reshaping national competitive positions.
Germany
Bavarian hospital networks process elevated systemic lupus erythematosus screening volumes through consolidated regional laboratory hubs. BfArM vigilance reporting requirements under IVDR Article 83 accelerate investment in validated immunoassay platforms. The Munich-Stuttgart corridor anchors automated immunofluorescence manufacturing capacity serving Central European export markets.
France
Hospital consolidation in Île-de-France creates centralized autoimmune diagnostic hubs capturing regional referral volumes. ANSM enforcement of post-market surveillance obligations tightens performance documentation for legacy ELISA assays. Paris and Lyon maintain concentrated morphologist expertise pools handling complex connective tissue disease differentials.
Italy
Provincial rheumatology networks drive anti-CCP and rheumatoid factor screening demand through centralized public laboratory systems. Academic medical centers in Milan and Rome pioneer mass spectrometry convergence with proteomics workflows for Sjögren's syndrome characterization. Southern regions present underpenetrated expansion corridors for automated platform deployment.
United Kingdom
NHS pathology consolidation shifts autoimmune testing volumes toward regional hub laboratories in Greater Manchester and the West Midlands. MHRA post-Brexit regulatory alignment with IVDR technical standards extends conformity assessment timelines for domestic manufacturers. London teaching hospitals retain specialized neuroimmunology accreditation for multiple sclerosis diagnostic panels.
Poland
EU structural fund investments modernize diagnostic infrastructure across Warsaw and Kraków metropolitan laboratory networks. Private laboratory sector expansion adopts latest immunoassay automation platforms with reagent rental contract structures. Eastern European reference laboratory positioning attracts German and Austrian diagnostic manufacturers seeking lower-cost CE marking clinical study sites.
Europe Autoimmune Disease Diagnostics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across reagent rental contract structures and specialized quality control positioning. The vendor base clusters around three strategic archetypes: integrated platform manufacturers bundling analyzer placement with consumable procurement, specialized autoimmune assay developers focusing on multiplexed biomarker panels, and quality control specialists extending influence beyond direct test manufacturing. Dominant competitive moves include multi-year exclusive platform arrangements with hospital group purchasing organizations and backward integration into automated immunofluorescence imaging systems.
Among diversified diagnostic conglomerates, Abbott Laboratories and Siemens Healthineers occupy positions exemplifying integrated platform strategies across Western European laboratory networks. Bio-Rad Laboratories represents the specialized archetype, with its quality control and assay development positioning extending commercial reach beyond direct autoimmune test manufacturing. These three anchors illustrate how scale-driven reagent economics compete against specialized biomarker expertise in IVDR-compliant market access.
| Leading Market Players |
|---|
| Abbott Laboratories |
| bioMérieux |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Euroimmun AG |
| Trinity Biotech |
| Inova Diagnostics |
| Others |
Pricing and Supply Chain Analysis
Hospital group purchasing organization consolidation across France and Germany is compressing reagent rental contract terms and forcing manufacturers to absorb analyzer placement costs upfront, which redistributes pricing power toward high-volume laboratory networks and squeezes margins on legacy ELISA platforms.
Pricing Analysis
Reagent rental agreements bundling instrument placement with minimum volume commitments dominate European autoimmune diagnostics. Pricing stratifies across premium, standard, and economy tiers based on IVDR certification status and automation integration depth. Cost compression in economy-tier screening panels is intensifying because Polish and Romanian laboratories prioritize capital-light procurement. Academic medical centers in Paris and Munich exhibit lowest price sensitivity due to research funding overlays, while Eastern European private laboratories drive hardest bargain terms.
Supply Chain Analysis
Regional distribution centers in the Munich-Stuttgart corridor and Île-de-France operate hub-and-spoke patterns serving Central and Western European laboratory networks. Manufacturing concentrates in Germany, France, and Switzerland for immunoassay platforms and reagent production. Supply chains draw from monoclonal antibody suppliers in Belgium and the Netherlands, plus plastic consumables molded in Poland. Single-source vulnerability around specialized immunofluorescence substrates creates bottleneck exposure. Distribution runs through diagnostic distributors with cold-chain capabilities, though direct manufacturer-to-laboratory contracts are gaining share in consolidated networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe autoimmune disease diagnostics market functions as a stable compounder anchored by IVDR-mandated platform refresh cycles that guarantee recurring reagent demand regardless of economic cyclicality.
For Market Incumbents: Lock in exclusive multi-year reagent rental contracts with French hospital group purchasing organizations before IVDR transition deadlines force competitor portfolio withdrawals. Deepen backward integration into automated immunofluorescence imaging systems to capture morphologist-dependent testing margins. The notified body bottleneck threatens smaller manufacturers with forced market exit, creating absorption opportunities for scaled players with clinical evidence archives. For New Entrants and Emerging Players: Launch via microfluidics-enabled home sampling devices targeting rheumatoid arthritis chronic monitoring channels where IVDR regulatory pathways are clarifying. Poland and Romania present the most penetrable geographies due to EU structural fund infrastructure buildout and underdeveloped incumbent relationships. Partner with Italian academic medical centers for mass spectrometry convergence pilots that establish clinical credibility before commercial scale. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized autoimmune assay developers possessing IVDR-compliant multiplexed biomarker panels and pharmaceutical companion diagnostic partnerships. The five-to-ten year viability window favors platforms with demonstrated analytical performance under BfArM and ANSM vigilance reporting. Watch for EMA biologic therapy approval announcements as inflection indicators for predictive autoantibody signature demand.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Investment | BfArM vigilance requirements demand systematic post-market performance follow-up programs for sustained CE marking. |
| Hospital System Partnership | Exclusive platform arrangements with Île-de-France group purchasing organizations lock in multi-year reagent volumes. |
| Microfluidics Product Launch | Italian research consortia pioneer integrated diagnostic algorithms enabling capillary blood autoimmune monitoring. |
| Companion Diagnostic Alignment | EMA biologic therapy guidelines create demand for predictive autoantibody signatures extending test utility. |
| Eastern European Geographic Expansion | Poland's EU structural fund modernization creates greenfield laboratory adoption of latest immunoassay automation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with diagnostic laboratory directors, rheumatology department heads, IVD regulatory affairs specialists, and hospital procurement managers with secondary validation against EMA IVDR guidance documents, BfArM vigilance reporting databases, ANSM conformity assessment records, and hospital group purchasing organization contract disclosures. Bottom-up test volume modeling and top-down market sizing triangulated across the analysis window.
Historical reference periods anchored the projection horizon through documented installed base transitions and regulatory deadline impacts. Segmentation dimensions spanned product type, indication category, end-user setting, and technology platform maturity. CAGRs derived from test volume elasticity to rheumatology service expansion and IVDR compliance investment cycles. Modeled inputs included laboratory automation adoption curves and notified body capacity constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended IVDR transition delays or accelerated laboratory consolidation. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and reagent rental contract renewal rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
US in Vitro Diagnostics Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
Hepatitis E Diagnostic Tests Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market
Diagnostics
Global Non-Small Cell Lung Cancer Diagnostics Market
Diagnostics
Helicobacter Pylori (H. Pylori) Diagnostics Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Global Creatinine Measurement Market
Diagnostics
Artificial Intelligence in IVD Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Multiple Myeloma Diagnostics Market
Diagnostics
Global Women's Health Diagnostics Market
Diagnostics
Europe in Vitro Diagnostics (IVD) Market
Diagnostics
BNP and NT-Probnp Market