
 Global Lyme Disease Diagnostic Market | 2026-2036
Global Lyme Disease Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lyme Disease Diagnostic Market Foresight
Multiplex PCR and next-generation serological platforms is reconfiguring how laboratories detect Borrelia burgdorferi and co-infecting pathogens. Roche Diagnostics leverages its automated immunoassay infrastructure to sustain high-throughput screening in centralized labs across Europe and North America. Abbott Laboratories anchors its position through point-of-care connectivity that links rural clinics to reference laboratory networks. Bio-Rad Laboratories specializes in Western blot confirmation workflows that remain embedded in two-tier testing protocols mandated by major public health agencies.
Lyme disease diagnostics encompass laboratory and near-patient systems designed to detect antibodies against Borrelia burgdorferi sensu lato or amplify pathogen DNA from blood, serum, or cerebrospinal fluid, with sensitivity thresholds typically exceeding 85% in disseminated infection stages. These tools serve physicians confronting nonspecific early symptoms and epidemiologists tracking vector-borne disease expansion into temperate latitudes. PCR assays command premium positioning in differential diagnosis applications where coinfection with Anaplasma or Babesia complicates clinical presentation. Point-of-care testing deployment is gaining traction in endemic regions where timely antibiotic initiation depends on rapid turnaround outside centralized laboratory infrastructure.
The FDA governs premarket approval pathways for novel serological devices in the United States, while the EMA and national competent authorities enforce In Vitro Diagnostic Regulation performance standards across European member states. WHO surveillance guidelines further shape reporting consistency that drives epidemiological study demand and public procurement priorities. Stakeholders must monitor evolving regulatory science around direct detection methods as agencies reassess two-tier algorithm requirements.
Market Dynamics
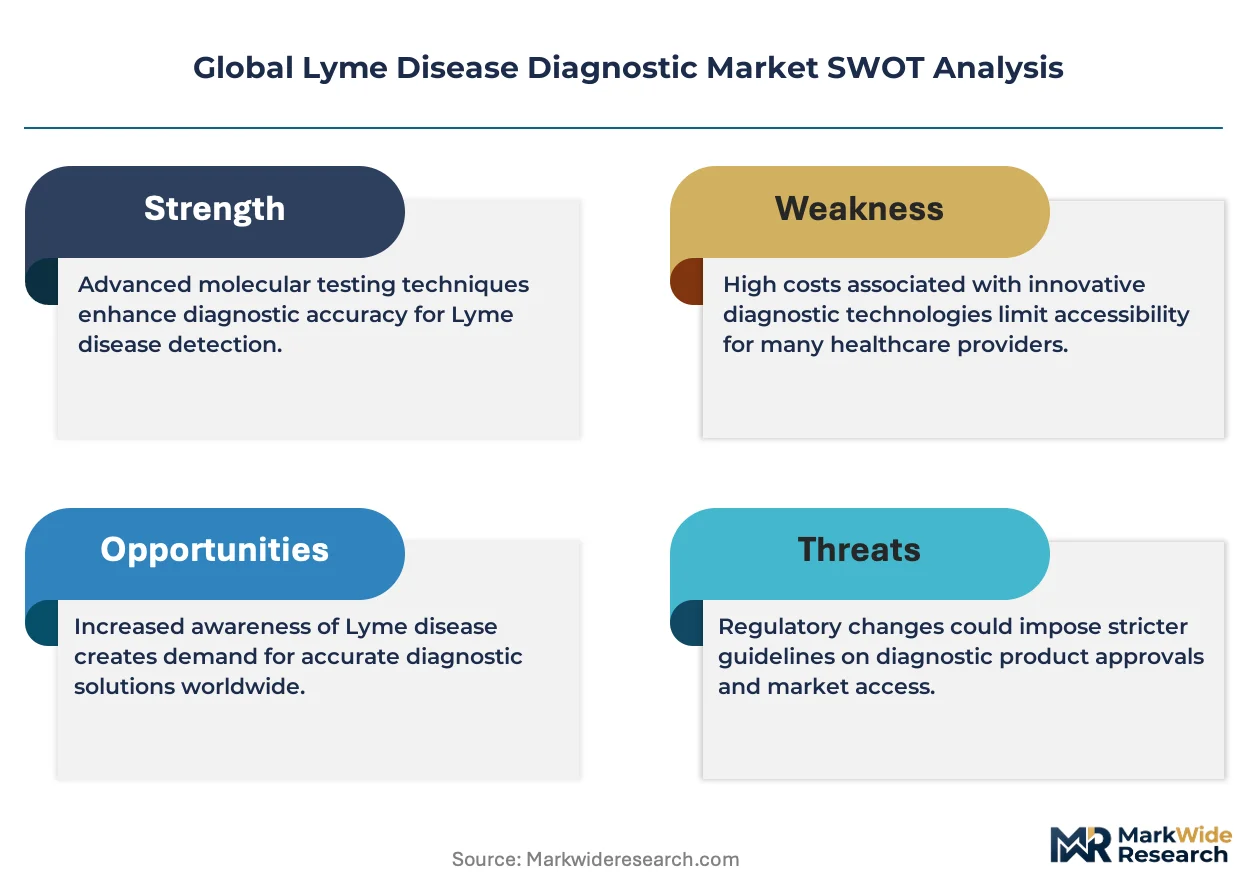
Multiplex PCR platforms are compressing diagnostic timelines from days to hours, forcing laboratories to retire legacy serological workflows and retrain technical staff across endemic regions.
Growth Catalysts
- CDC two-tier testing mandates:Federal guidelines in the United States sustain demand for Western blot confirmation assays, embedding specific manufacturers into public health procurement pipelines.
- Climate-driven vector expansion:Ixodes scapularis habitat migration into upper Midwest and Northeastern states expands addressable patient populations for early-detection testing.
- Real-time PCR sensitivity gains:Assay detection thresholds now reach 10-100 copies per milliliter, enabling bloodstream diagnosis before antibody seroconversion occurs.
Market Restraints
- Reimbursement compression:CMS coding revisions for molecular pathogen panels reduce per-test compensation, squeezing margins on high-sensitivity platforms.
- Antigenic variability:Borrelia burgdorferi sensu lato strain diversity across Eurasian populations degrades serological assay specificity, generating false-negative rates in imported cases.
- Specialized technician scarcity:Molecular diagnostics certification requirements limit laboratory expansion in rural endemic counties where demand concentrates.
Strategic Opportunities
- CSRD-aligned sustainability reporting:European laboratory networks now prioritize reagent suppliers with verified cold-chain carbon footprints, creating procurement advantages for regional manufacturers.
- Point-of-care rural deployment:Connectivity-integrated rapid immunoassays address antibiotic initiation delays in Appalachian and Upper Peninsula clinic networks.
- Tick-borne pathogen multiplexing:Combined Anaplasma-Babesia-Borrelia panels capture differential diagnosis demand from infectious disease specialists managing complex presentations.
Industry Challenges
- IVDR technical documentation:European Union performance study requirements for novel serological devices extend approval timelines by 18-24 months versus predecessor directives.
- Laboratory information system integration:Disparate HL7 FHIR implementations between reference laboratories and electronic health record vendors fragment result reporting workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lyme Disease Diagnostic Market |
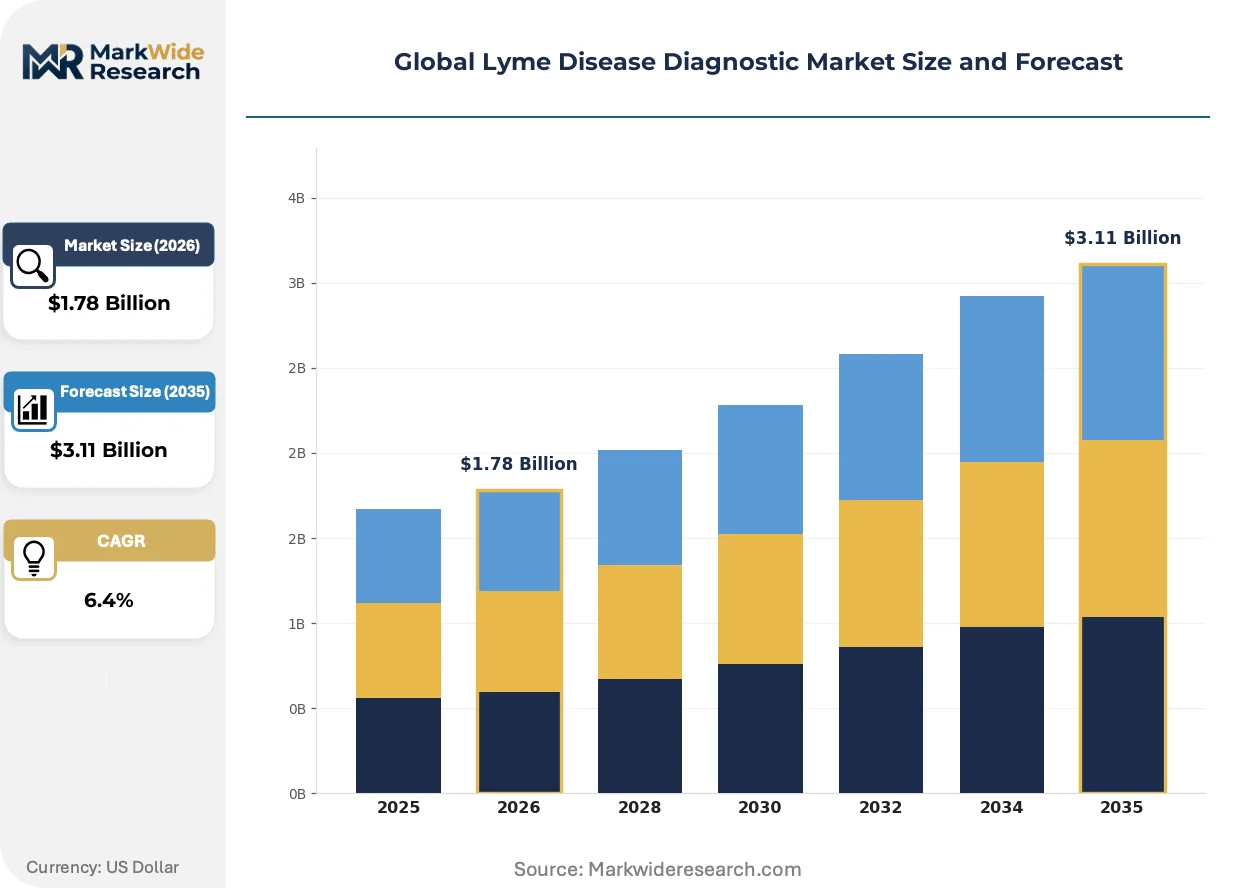
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $3.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Immunoassay, Western Blot, PCR Assay, Immunofluorescence Assay, ELISA Application: Early Detection, Post-Treatment Monitoring, Differential Diagnosis, Epidemiological Studies End User: Clinical Laboratories, Research Institutes, Hospitals, Blood Banks, Diagnostic Centers Deployment: Point-of-Care Testing, Centralized Labs, Mobile Diagnostic Units, Home Collection Kits |
| Companies Covered | Bio-Rad Laboratories, Thermo Fisher Scientific, Roche Diagnostics, T2 Biosystems, Abbott Laboratories, DiaSorin, Oxford Immunotec, bioMérieux, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lyme Disease Diagnostic Market Shifts & Advancements
Diagnostic workflows are fragmenting across centralized reference laboratories, regional hospital networks, and ambulatory point-of-care sites, each demanding purpose-built assay formats with incompatible throughput specifications.
Next-generation sequencing is migrating from research-only applications into clinical confirmation workflows for atypical Borrelia strains. Specialty reference laboratories in Germany and the Netherlands have adopted targeted amplicon sequencing to resolve serological indeterminates. This migration from conventional PCR is compressing the addressable market for standalone nucleic acid tests while expanding service-based revenue models.
The FDA's 2024 revised Lyme disease diagnostic guidance encourages direct detection method development, reducing reliance on two-tier serological algorithms. Device manufacturers now prioritize blood-based PCR platforms over immunoassay investments. Early-stage developers targeting United States premarket approval are reallocating clinical study resources toward bloodstream pathogen load quantification.
Rural primary care physicians are consolidating diagnostic purchasing through integrated delivery networks rather than independent laboratory relationships. This consolidation favors vendors offering combined instrument-reagent-service contracts with remote technical support. The Upper Midwest and Northeastern United States exhibit the most pronounced channel concentration, where hospital-affiliated clinics now account for majority test volume.
Global Lyme Disease Diagnostic Market Segmentation
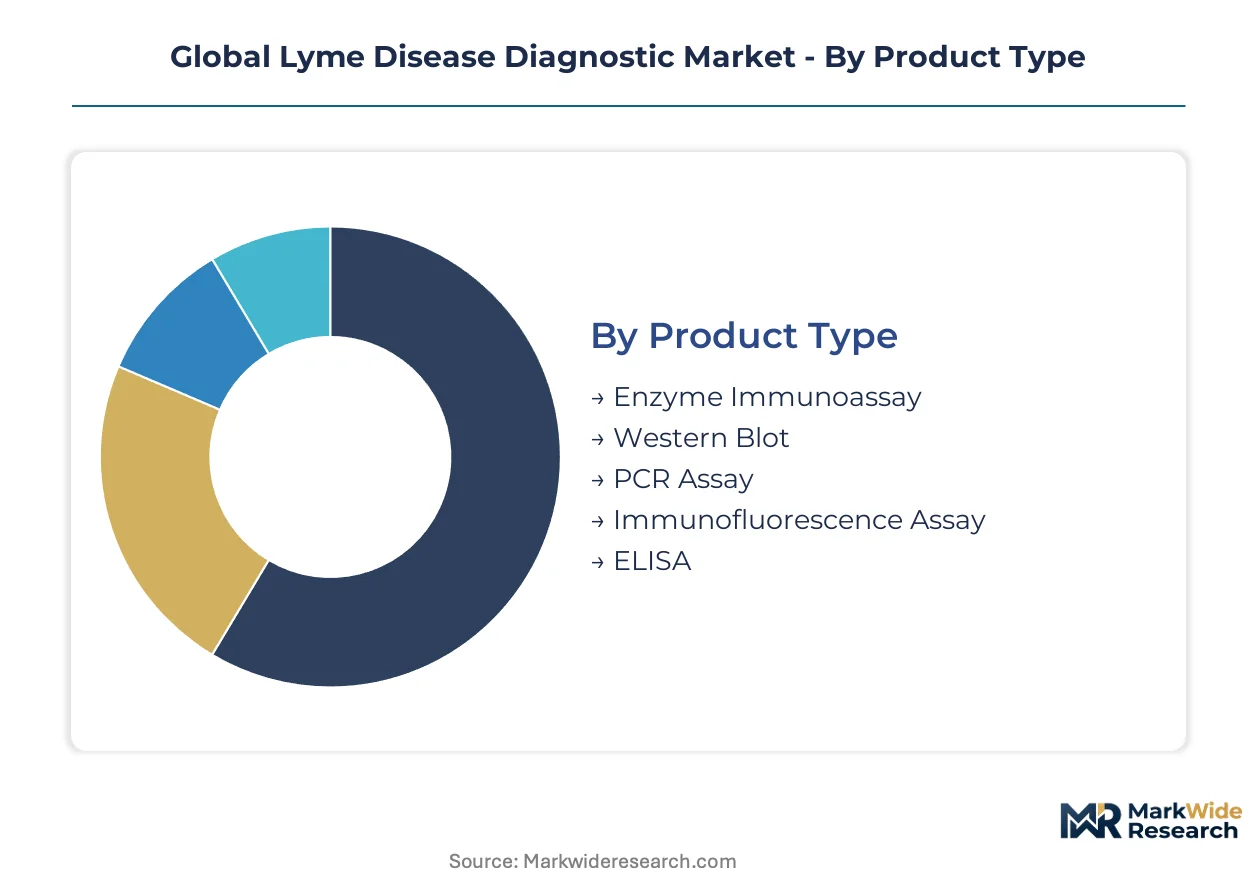
Diagnostic workflows fragment across testing modalities and care settings, each demanding distinct assay formats, throughput specifications, and technical support intensity. Understanding segment boundaries clarifies procurement patterns and reveals where equipment-reagent bundling creates vendor lock-in.
Product Type:
After-sales service intensity varies sharply across platforms, with automated systems requiring field engineering contracts and manual assays depending on telephone support.
- PCR Assay:Real-time amplification platforms detect Borrelia DNA at 10-100 copies per milliliter sensitivity, enabling pre-seroconversion diagnosis. Demand concentrates in German and Dutch reference laboratories managing complex differential cases. FDA guidance revisions are accelerating blood-based platform development.
- Western Blot:Confirmatory immunoblotting remains embedded in CDC-mandated two-tier algorithms, requiring specialized technician interpretation. United States public health procurement pipelines sustain manufacturer positions despite longer turnaround times.
- Enzyme Immunoassay:High-throughput screening workhorses in centralized laboratory networks.
- Immunofluorescence Assay:Labor-intensive microscopy-based confirmation for atypical presentations.
- ELISA:Cost-effective initial screening deployed across high-volume hospital laboratories.
By volume, Enzyme Immunoassay leads. By growth pace, PCR Assay is ahead.
Application:
Cost tier stratification separates premium-priced molecular confirmation from commoditized screening, with reimbursement codes determining viable price points.
- Differential Diagnosis:Multiplex panels detecting Anaplasma, Babesia, and Borrelia simultaneously command premium positioning where coinfection complicates clinical presentation. Infectious disease specialists in Northeastern United States hospital networks drive procurement. PCR sensitivity gains are compressing serological algorithm reliance.
- Early Detection:Rapid immunoassays targeting immunoglobulin M antibodies within 2-4 weeks of tick exposure. Appalachian clinic networks prioritize point-of-care formats enabling same-day antibiotic initiation.
- Post-Treatment Monitoring:Serological persistence tracking for persistent symptom evaluation.
- Epidemiological Studies:Standardized surveillance assays supporting public health reporting requirements.
By installed base, Early Detection dominates. By expansion trajectory, Differential Diagnosis is climbing the fastest.
End User:
Customer type determines purchasing authority, with integrated delivery networks consolidating formerly independent laboratory relationships.
- Clinical Laboratories:High-throughput facilities processing thousands of specimens daily, requiring automated immunoassay infrastructure with remote monitoring capabilities. United States and German networks are expanding molecular testing capacity. CSRD-aligned sustainability reporting now influences European reagent procurement.
- Hospitals:Acute care settings demanding STAT turnaround for emergency department presentations. Upper Midwest hospital-affiliated clinics now account for majority test volume in endemic regions.
- Research Institutes:Next-generation sequencing adoption for atypical strain characterization.
- Blood Banks:Donor screening protocols preventing transfusion-associated transmission.
- Diagnostic Centers:Independent reference laboratories competing on turnaround time.
By test volume, Clinical Laboratories lead. By connectivity investment, Hospitals are gaining share fastest.
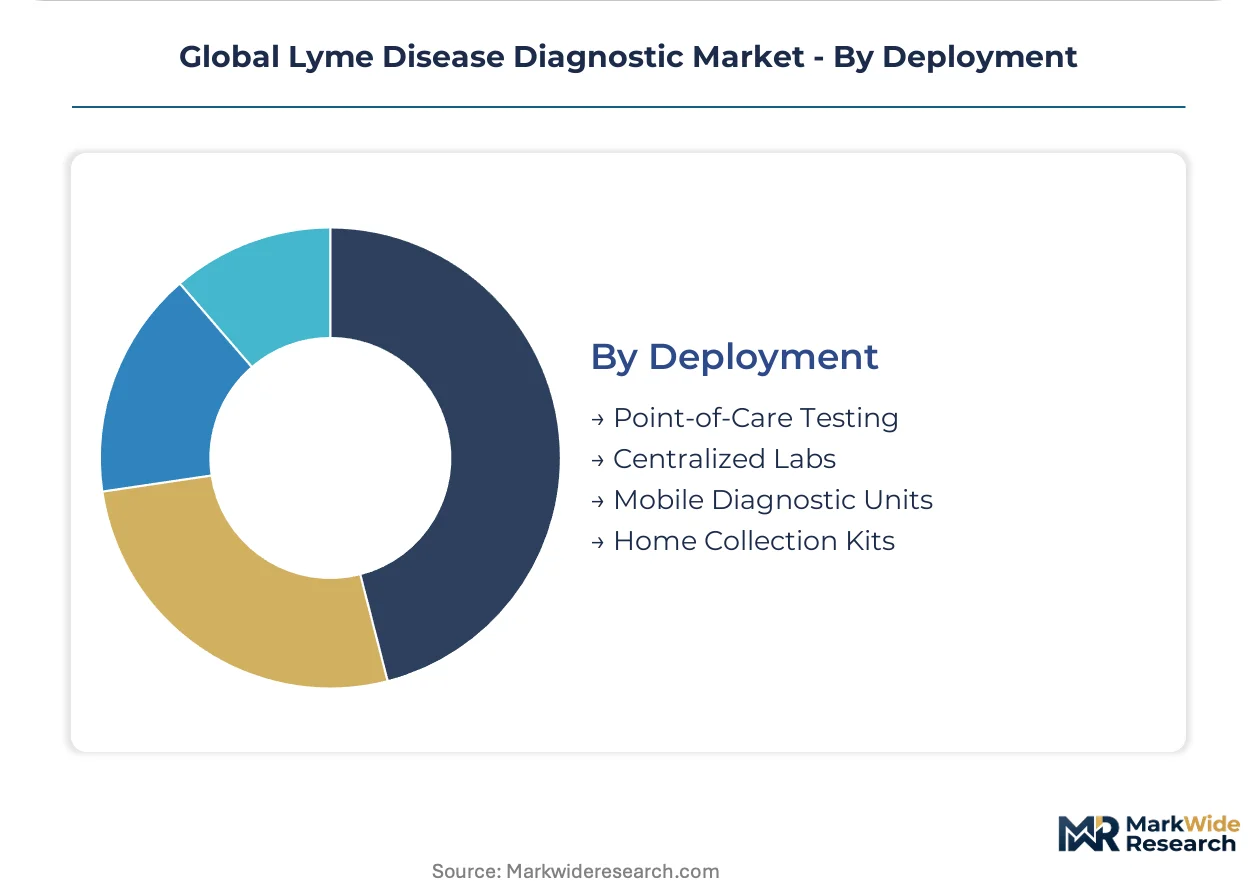
Deployment:
Supply concentration in centralized manufacturing creates distribution challenges for temperature-sensitive reagents reaching dispersed point-of-care sites.
- Centralized Labs:Reference facilities achieving economies of scale through automated batch processing. German and Dutch specialty laboratories have adopted targeted amplicon sequencing for serological indeterminates. Consolidation favors vendors offering combined instrument-reagent-service contracts.
- Point-of-Care Testing:Connectivity-integrated rapid immunoassays linking rural clinics to laboratory networks. Appalachian and Upper Peninsula deployment addresses antibiotic initiation delays outside centralized infrastructure.
- Mobile Diagnostic Units:Seasonal outreach programs following vector expansion patterns.
- Home Collection Kits:Direct-to-consumer specimen collection with mail-back laboratory processing.
By revenue concentration, Centralized Labs lead. By deployment expansion, Point-of-Care Testing shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks in the United States and Germany concentrate procurement authority for high-throughput diagnostic platforms, while specialized reference laboratories in the Netherlands and Switzerland drive adoption of advanced molecular confirmation workflows.
United States
Hospital-affiliated clinics across the Upper Midwest and Northeastern states now process majority test volumes as Ixodes scapularis habitat expands. FDA premarket approval pathways govern novel serological device commercialization, with 2024 guidance revisions encouraging direct detection method development. The Appalachian clinic network prioritizes point-of-care connectivity to address antibiotic initiation delays outside centralized laboratory infrastructure.
Germany
Specialty reference laboratories in Munich and Hamburg have adopted targeted amplicon sequencing for serological indeterminates, compressing timelines for atypical strain characterization. EMA and national competent authorities enforce In Vitro Diagnostic Regulation performance standards that extend approval timelines for novel devices. CSRD-aligned sustainability reporting now influences reagent procurement decisions across German laboratory networks.
Netherlands
Research-intensive diagnostic facilities in Rotterdam and Amsterdam drive validation studies for multiplex PCR platforms detecting Borrelia burgdorferi alongside Anaplasma and Babesia coinfections. Dutch national health authorities coordinate surveillance reporting consistency that shapes public procurement priorities for standardized assays. The country's centralized laboratory infrastructure supports rapid turnaround for differential diagnosis applications.
Switzerland
Swissmedic regulates diagnostic device performance standards for laboratories serving cross-border patient populations from France, Germany, and Italy. Basel-area research institutes collaborate with clinical networks on next-generation sequencing migration into routine confirmation workflows. The country's precision medicine orientation favors premium-positioned molecular platforms over commoditized screening formats.
United Kingdom
London and Southeast England hospital networks maintain high-throughput enzyme immunoassay screening capacity while evaluating PCR-based alternatives to two-tier algorithms. UK health technology assessment processes determine reimbursement eligibility for novel diagnostic modalities. Regional variation in Lyme disease incidence between Scottish Highlands and Southern England creates fragmented demand patterns for testing services.
Global Lyme Disease Diagnostic Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments where integrated delivery networks consolidate formerly independent laboratory relationships. Automated immunoassay infrastructure providers and molecular diagnostics specialists occupy distinct strategic tiers, with the former emphasizing service-reagent bundling and the latter prioritizing sensitivity specifications. Three archetypes dominate: diversified life science conglomerates with diagnostic divisions, pure-play molecular diagnostics firms, and regional reagent specialists. Competitive intensity centers on M&A activity targeting point-of-care connectivity capabilities and strategic partnerships linking rural clinic networks to reference laboratory infrastructure.
Among diversified diagnostics conglomerates, Roche Diagnostics and Abbott Laboratories exemplify channel-control archetypes through automated infrastructure and point-of-care connectivity investments respectively. Bio-Rad Laboratories occupies a specialist position exemplifying Western blot confirmation workflows embedded in public health procurement pipelines. These three entities represent contrasting strategic postures: scale-driven platform provision, decentralized network integration, and regulatory-mandated confirmation specialization.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Thermo Fisher Scientific |
| Roche Diagnostics |
| T2 Biosystems |
| Abbott Laboratories |
| DiaSorin |
| Oxford Immunotec |
| bioMérieux |
| QIAGEN |
| Others |
Supply & Pricing Matrix
Reagent manufacturing concentration in Germany and the Netherlands concentrates margin capture upstream, while downstream clinical laboratories in the United States face compressed reimbursement rates that force vendor consolidation around bundled service contracts.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate PCR assay supply agreements between European reagent manufacturers and North American laboratory networks. Price differentiation hinges on FDA premarket approval tier and after-sales field engineering intensity, with automated platforms commanding service-bundled premiums. Pricing pressure stems from CMS coding revisions for molecular pathogen panels that reduce per-test compensation. Hospital-affiliated clinics exhibit highest price sensitivity due to integrated delivery network volume consolidation, while specialty reference laboratories in Germany show lowest sensitivity given premium positioning for complex differential cases.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for thermal cycler components and fluorescence detection modules. Manufacturing concentrates in Germany, the United States, and Switzerland for precision optical components, while plastic consumables and buffer reagents draw from Chinese and Indian chemical suppliers. Single-source vulnerability persists for specialized polymerases and fluorescent probe chemistries. Distribution runs through cold-chain logistics networks serving temperature-sensitive reagents, with regional distribution hubs in Chicago, Rotterdam, and Singapore anchoring fulfillment to endemic regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat defensive story where CDC two-tier testing mandates embed specific manufacturers into public health procurement pipelines, creating switching costs that protect incumbent positions.
For Market Incumbents: Harden regulatory entrenchment through accelerated FDA submissions for blood-based PCR platforms ahead of guidance implementation. Deepen backward integration into fluorescent probe chemistry to offset raw material cost volatility. Defend against point-of-care connectivity specialists by embedding remote monitoring capabilities into existing automated infrastructure. For New Entrants and Emerging Players: Establish a beachhead in Appalachian point-of-care networks where antibiotic initiation delays create demand for rapid immunoassays outside centralized laboratory reach. Target rural clinic procurement consolidation through integrated delivery network partnerships rather than independent laboratory relationships. Lead with connectivity-integrated platforms that link peripheral sites to reference laboratory networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed molecular diagnostics firms holding CE-marked multiplex platforms awaiting FDA validation. Long-term viability centers on regulatory science alignment as agencies reassess two-tier algorithm requirements. Watch for FDA direct detection guidance implementation velocity as inflection indicator for serological-to-molecular modality shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Blood-Based PCR | Aligns development pipelines with 2024 guidance encouraging direct detection methods. |
| CE Marking Pathway Under IVDR | Addresses extended approval timelines through early performance study investment. |
| Hospital System Partnership | Captures test volume consolidation in Upper Midwest and Northeastern endemic regions. |
| Software Companion Development | Resolves HL7 FHIR integration fragmentation between laboratories and EHR vendors. |
| Reimbursement Strategy | Navigates CMS coding revisions for molecular pathogen panel compensation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with infectious disease specialists, clinical laboratory directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EMA technical documentation, CDC surveillance databases, and CMS reimbursement coding records. Bottom-up test volume modeling triangulated against top-down market sizing across manufacturer revenue disclosures.
Calibration against historical sensitivity improvement curves and regulatory approval timelines anchored the analytical framework. Segmentation dimensions spanned testing modality, application purpose, end-user facility type, and deployment setting. CAGRs were derived from trend extrapolation moderated by reimbursement compression effects and vector expansion epidemiology. Forecast inputs incorporated PCR sensitivity threshold trajectories and two-tier algorithm policy evolution.
Sensitivities concentrate around FDA guidance implementation pace, IVDR performance study completion rates, and climate-driven habitat expansion velocity. Forecasts reflect documented assumptions about serological-to-molecular modality substitution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
Mycoplasma Diagnostics Market
Diagnostics
Johne's Disease Diagnostics Market
Diagnostics
Influenza Diagnostics Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Middle East and Africa HIV Diagnosis and Treatment Market
Diagnostics
Neuro-Auto-Immune Disease Diagnostics Market
Diagnostics
Rapid RNA Testing Kits Market
Diagnostics
Global Hemostasis Diagnostics Market
Diagnostics
Population Screening Market
Diagnostics
Infectious Disease Point-Of-Care (POC) Diagnostics Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
Liver Function Tests Market
Diagnostics
Complement C3 ELISA Kits Market
Diagnostics
Veterinary Molecular Diagnostics Market