
 Viral Antigens Market | 2026-2036
Viral Antigens Market Size, Share, and Industry Trends Forecast 2026-2036
Viral Antigens Market Outlook
CE marking under the EU In Vitro Diagnostic Regulation is unwinding the competitive landscape for viral antigen suppliers, forcing smaller manufacturers to either invest in clinical evidence generation or exit the European market entirely. Thermo Fisher Scientific leverages its end-to-end control over raw material sourcing and finished assay production to sustain margin resilience across cyclical procurement budgets. Bio-Rad Laboratories anchors its position through deep specialization in quality control reagents for blood-banking and transplant diagnostics. Abbott Laboratories competes by integrating viral antigen production with its installed base of automated immunoassay platforms.
Viral antigens are purified or recombinant protein structures derived from pathogenic viruses, typically produced through mammalian cell culture, baculovirus expression systems, or chemical synthesis, and are employed as capture or detection reagents in immunoassays, vaccine potency testing, and serological surveillance. Recombinant antigens now dominate supply contracts due to their lot-to-lot consistency and elimination of biosafety level-3 handling requirements, while peptide antigens occupy a premium niche in epitope-mapping and customized serology panels. Diagnostics applications command the largest revenue share among application segments, though vaccine development represents the fastest-expanding demand pool as mRNA and viral-vector platforms require extensive antigen characterization.
The FDA's quality system regulation and the EU IVDR's performance evaluation requirements are elevating documentation burdens for viral antigen manufacturers, effectively filtering market access toward entities with established regulatory affairs infrastructure. China's NMPA has accelerated its review pathways for domestically produced diagnostic raw materials, redirecting procurement patterns for Asia-Pacific supply chains. Stakeholders must monitor how evolving harmonization efforts between FDA and EMA on companion diagnostic frameworks reshape antigen qualification standards and competitive positioning.
Market Dynamics
Recombinant protein expression systems are displacing mammalian cell culture as the dominant production modality for viral antigens, compressing batch-to-batch variability while eliminating biosafety level-3 containment costs that previously constrained supplier entry.
Growth Catalysts
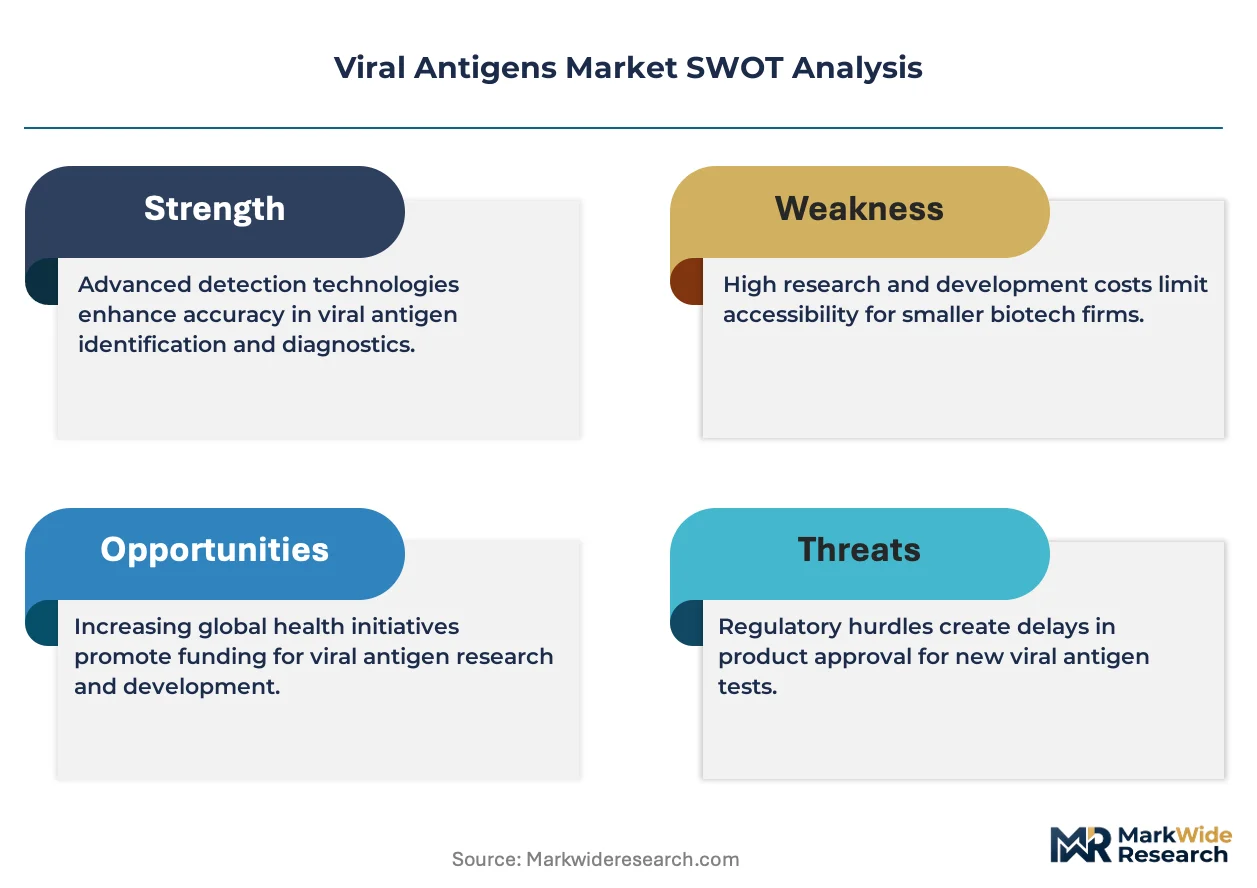
- EU In Vitro Diagnostic Regulation:The IVDR's performance evaluation requirements are accelerating consolidation toward manufacturers with established clinical evidence infrastructure, filtering out undercapitalized competitors and expanding contract volumes for qualified suppliers.
- mRNA vaccine platforms:Viral-vector and nucleic acid vaccine developers require extensive antigen characterization for potency assays, creating sustained demand for high-purity recombinant proteins across preclinical through commercial stages.
- Diagnostic laboratory consolidation:Large reference labs in the United States and Germany are centralizing procurement for respiratory and vector-borne pathogen panels, favoring antigen suppliers with scalable lot-release capacity.
Market Restraints
- Fetal bovine serum price volatility:Mammalian cell culture-dependent manufacturers face input cost instability as serum supply concentrates in South American and New Zealand sourcing regions with climate-sensitive collection cycles.
- CE marking documentation burden:The IVDR's expanded technical file requirements impose fixed compliance costs that disproportionately burden mid-tier antigen producers without dedicated regulatory affairs divisions.
- Peptide synthesis substitution:Solid-phase peptide synthesis for epitope-specific serology panels is capturing niche applications previously served by full-length recombinant antigens, compressing addressable market scope in customized diagnostics.
Strategic Opportunities
- China NMPA domestic material pathways:Accelerated review timelines for locally produced diagnostic raw materials are redirecting Asia-Pacific procurement toward indigenous suppliers with captive biomanufacturing infrastructure.
- Automated immunoassay integration:Antigen suppliers capturing positions within closed-system analyzer workflows gain switching cost advantages as laboratories standardize on platform-locked reagent contracts.
- CRISPR-edited cell lines:Gene-edited expression systems combining enhanced glycosylation control with synthetic biology yield optimization represent white space for differentiated antigen performance claims.
Industry Challenges
- Regulatory affairs talent scarcity:Qualified professionals capable of navigating FDA quality system regulations and IVDR performance evaluation requirements command premium compensation, constraining smaller manufacturers' compliance scaling.
- Multi-year certification timelines:CE marking under IVDR class D rules for infectious disease antigens extends validation cycles to 18-24 months, delaying revenue recognition for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viral Antigens Market |
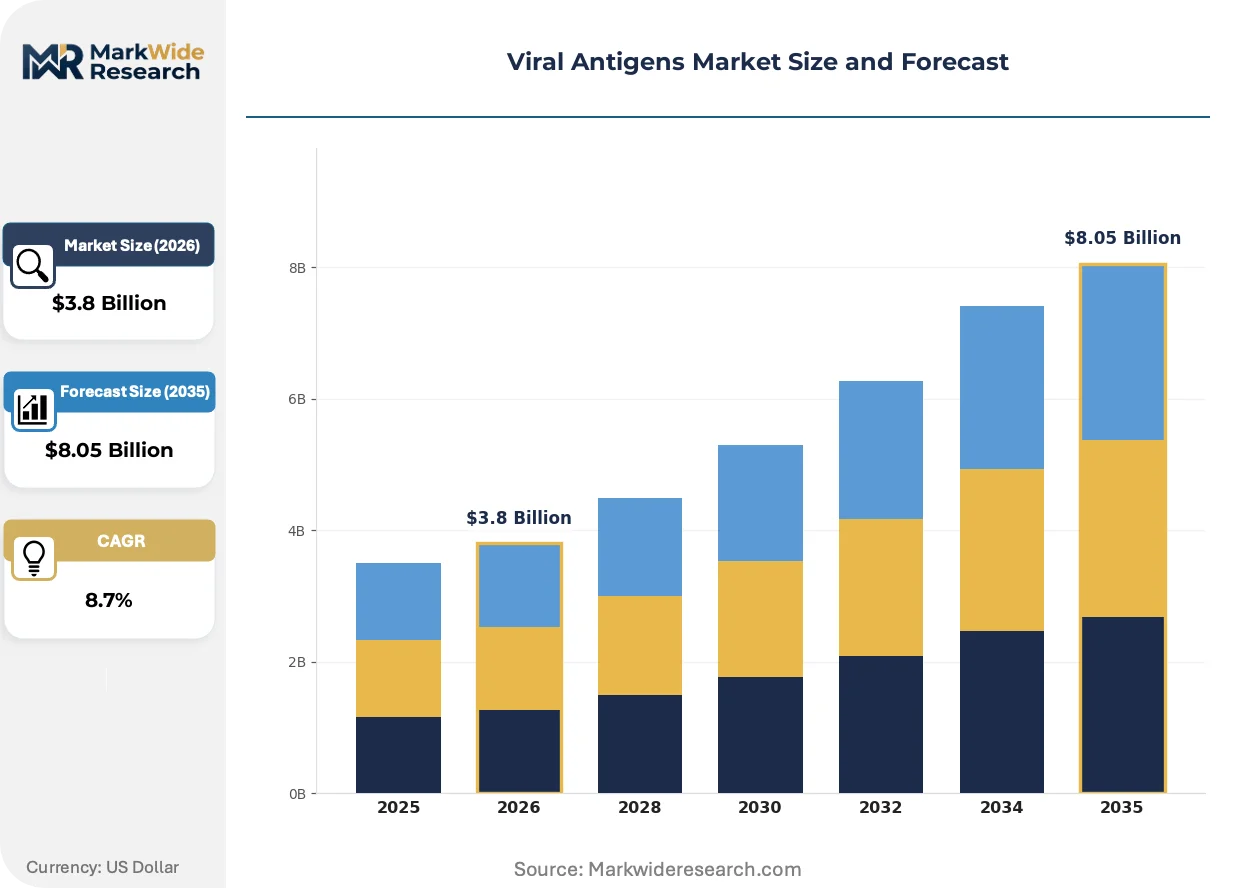
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Antigens, Synthetic Antigens, Whole Virus, Peptide Antigens Application: Diagnostics, Research, Vaccine Development, Therapeutic Use End User: Academic Institutions, Diagnostic Laboratories, Pharmaceutical Companies, Biotechnology Firms Delivery Mode: Liquid Format, Lyophilized Format, Nasal Spray, Injectable |
| Companies Covered | F. Hoffmann-La Roche AG, Abbott Laboratories, Bio-Rad Laboratories, Thermo Fisher Scientific, DiaSorin, Merck KGaA, bioMerieux SA, Creative Diagnostics, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viral Antigens Market Strategic Shifts
Antigen production technology is fragmenting into parallel tracks optimized for speed versus fidelity, with each pathway attracting distinct buyer segments and reshaping competitive differentiation criteria across the supply base.
Baculovirus expression systems are bifurcating the recombinant antigen market between rapid-turnaround insect cell platforms and higher-fidelity mammalian alternatives. Contract research organizations serving vaccine developers favor baculovirus speed for early-stage characterization, while blood-banking diagnostics insist on mammalian glycosylation patterns. This technical schism is compressing pricing power for undifferentiated suppliers caught between performance tiers.
China's NMPA has instituted expedited review pathways for domestically manufactured diagnostic raw materials, redirecting procurement flows toward indigenous biomanufacturing clusters in Suzhou and Shanghai. Multinational antigen suppliers must now establish local production or joint venture structures to maintain access to Asia-Pacific volume. The policy shift is accelerating technology transfer agreements as foreign manufacturers seek qualification under domestic material designation rules.
Reference laboratories are consolidating antigen procurement through multi-year sole-source agreements that bundle reagent supply with instrument placement and assay development services. This channel compression displaces traditional distributor networks in the United States and Germany, where large health system integrated delivery networks now negotiate directly with antigen manufacturers. The model concentrates purchasing power among fewer buyers while raising barriers for specialty suppliers lacking service integration capabilities.
Viral Antigens Market Segmentation
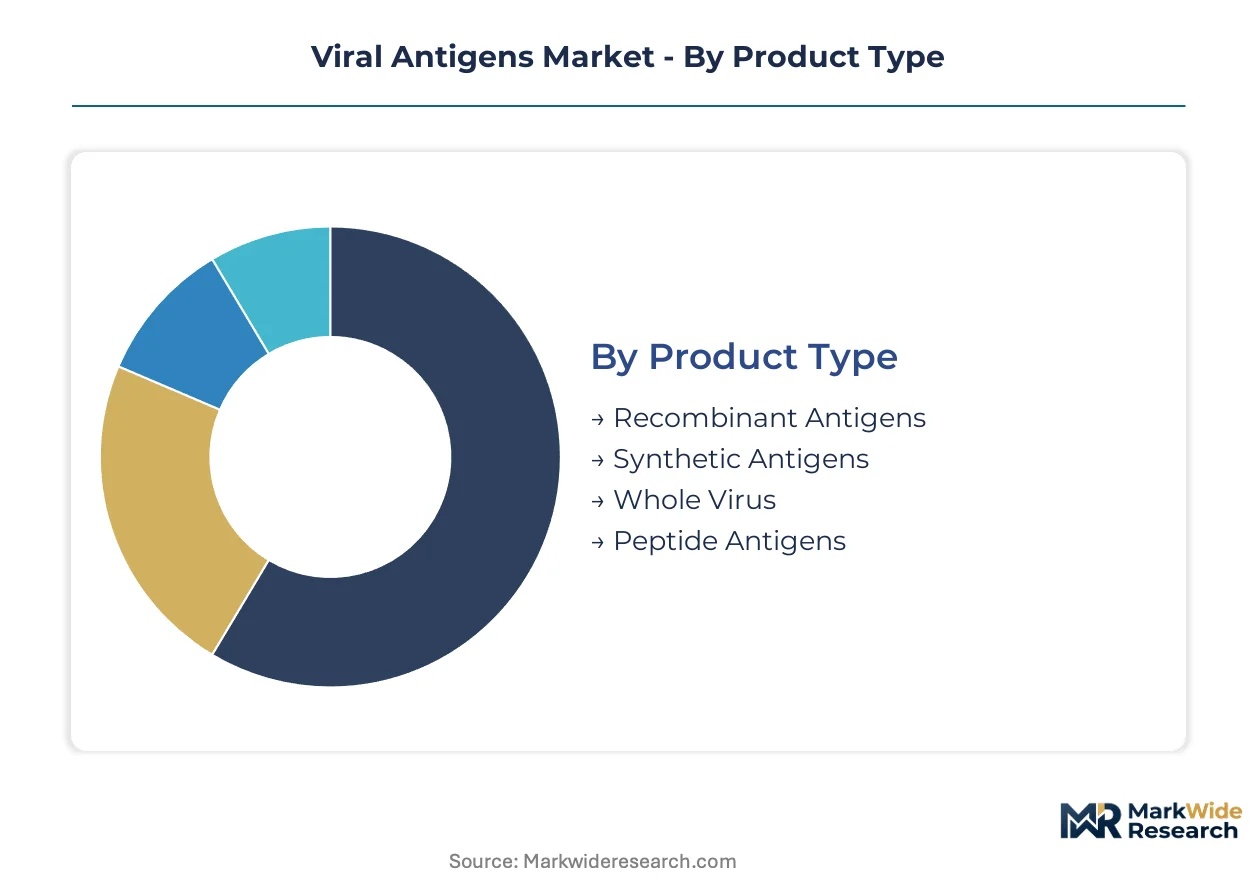
Margin concentration in viral antigens follows production complexity and regulatory qualification tiers rather than raw volume. Suppliers must map segment-specific certification requirements to avoid stranded capacity in non-compliant product lines.
Product Type:
Margin pools concentrate in recombinant formats where lot-to-lot consistency commands pricing premiums over variable-yield alternatives.
- Recombinant Antigens:Purified proteins expressed through baculovirus or mammalian cell systems deliver standardized glycosylation patterns essential for FDA and EMA diagnostic submissions. Diagnostic laboratories in the United States and Germany are consolidating procurement contracts around recombinant supply to minimize assay drift.
- Synthetic Antigens:Solid-phase peptide synthesis enables epitope-specific serology panels with precise amino acid positioning for autoimmune and infectious disease differentiation. Contract research organizations in China are scaling peptide capacity to serve domestic IVD developers under NMPA accelerated review pathways.
- Whole Virus:Live-attenuated or inactivated viral particles retain native conformational epitopes for vaccine potency testing.
- Peptide Antigens:Short-chain synthetic fragments occupy niche positions in customized serology and epitope-mapping applications.
Recombinant Antigens holds installed capacity. Synthetic Antigens is rotating up the share rankings.
Application:
Volume concentration tracks diagnostic laboratory procurement centralization, while value concentration follows vaccine platform characterization demands.
- Diagnostics:Immunoassay capture and detection reagents for respiratory, vector-borne, and sexually transmitted pathogen panels dominate procurement volumes. Reference laboratories in Germany and the United States are enforcing sole-source reagent contracts tied to automated platform placements.
- Vaccine Development:Potency assay antigens for mRNA and viral-vector platforms require extensive preclinical through commercial-stage characterization. Developers in China are sourcing recombinant proteins locally to qualify under NMPA domestic material designations.
- Research:Academic and institutional procurement for serological surveillance and mechanistic studies.
- Therapeutic Use:Antigen-specific immunotherapy and tolerization approaches in development pipelines.
Diagnostics commands the revenue base. Vaccine Development is expanding most quickly as nucleic acid platforms advance through clinical stages.
End User:
Procurement sophistication separates institutional buyers with captive regulatory affairs capacity from price-sensitive academic purchasers.
- Diagnostic Laboratories:Large reference labs and health system integrated delivery networks negotiate multi-year reagent contracts bundling supply with instrument service. Procurement centralization in the United States and Germany is displacing traditional distributor intermediaries.
- Pharmaceutical Companies:Vaccine developers require antigen characterization across potency, stability, and immunogenicity dimensions. mRNA platform sponsors are vertically integrating antigen production to secure supply chain control.
- Academic Institutions:Research universities and public health institutes with grant-funded procurement cycles.
- Biotechnology Firms:Emerging developers with outsourced manufacturing and lean regulatory infrastructure.
Diagnostic Laboratories anchors the demand structure. Pharmaceutical Companies is gaining share fastest through vaccine pipeline expansion.
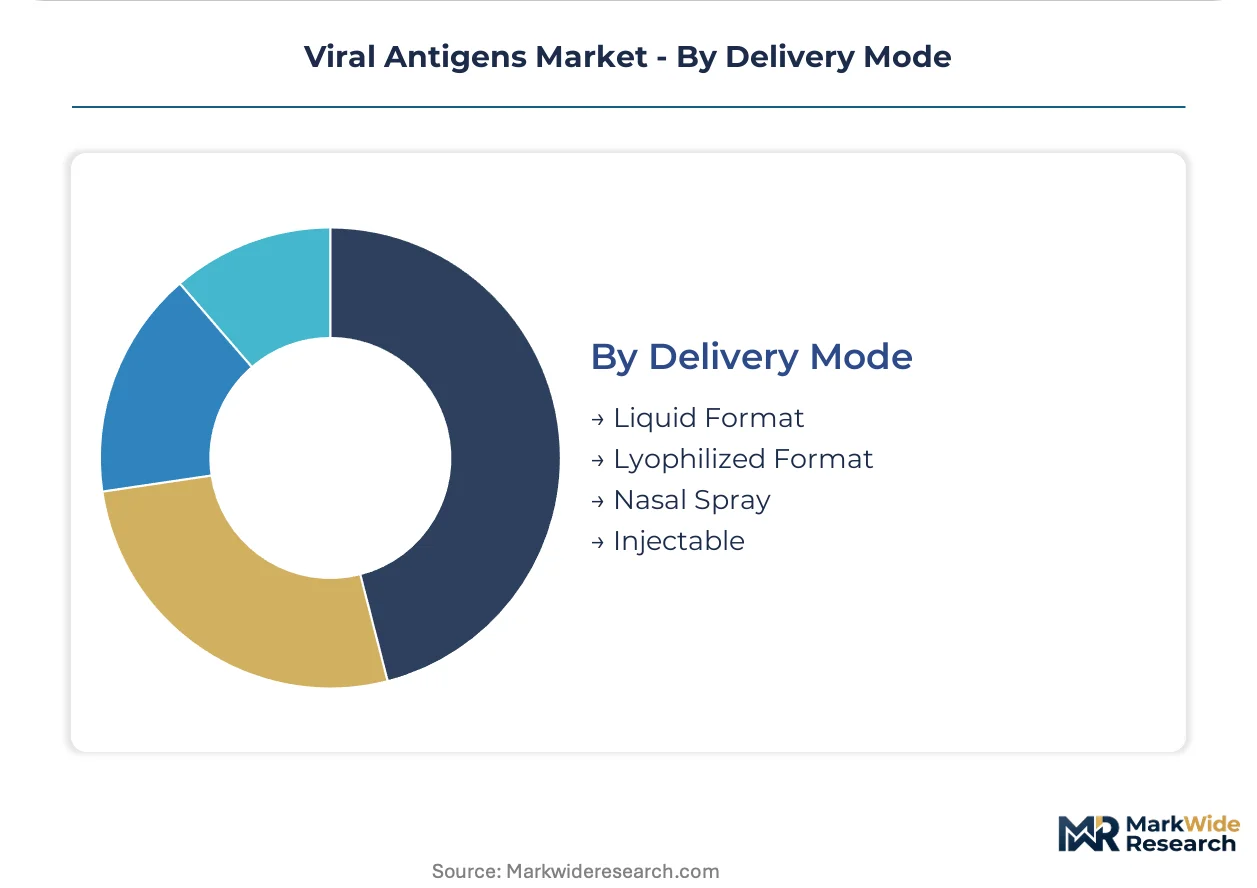
Delivery Mode:
Stability requirements and cold chain economics determine format selection across end-use segments.
- Liquid Format:Ready-to-use reagents in buffered solutions minimize preparation time for high-throughput diagnostic workflows. Reference laboratories in the United States prefer liquid antigens for automated immunoassay integration.
- Lyophilized Format:Freeze-dried products eliminate cold chain dependency for distribution to resource-limited settings and long-term storage applications. Suppliers serving Asia-Pacific markets are expanding lyophilization capacity to reduce logistics complexity.
- Nasal Spray:Mucosal delivery formats for vaccine development and immunotherapy research.
- Injectable:Parenteral formulations for therapeutic and specific vaccine applications.
Liquid Format dominates current throughput. Lyophilized Format is climbing the fastest as point-of-care and distributed testing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic biomanufacturing incentives across major economies are redirecting procurement flows and reshaping qualification requirements for viral antigen suppliers. The United States, Germany, and China concentrate capacity expansion through targeted regulatory acceleration and capital deployment programs. Regional divergence in approval timelines is fragmenting competitive positioning across jurisdictions.
United States
Diagnostic laboratory consolidation and reference lab procurement centralization drive contract volumes toward suppliers with scalable lot-release infrastructure. FDA quality system regulation enforcement elevates documentation burdens that filter market access toward established regulatory affairs divisions. The Greater Boston and San Francisco Bay Area biotech clusters host concentrated antigen characterization capacity serving vaccine developers and diagnostic manufacturers.
Germany
Large health system integrated delivery networks negotiate multi-year sole-source reagent contracts bundling supply with instrument placement and assay development services. CE marking under EU IVDR class D rules for infectious disease antigens extends validation cycles, compressing revenue recognition timelines for new product introductions. The Rhine-Ruhr and Munich metropolitan regions anchor blood-banking diagnostic manufacturing with captive quality control reagent production.
China
NMPA accelerated review pathways for domestically produced diagnostic raw materials redirect Asia-Pacific procurement toward indigenous biomanufacturing infrastructure. Suzhou and Shanghai industrial clusters scale recombinant protein expression capacity to qualify under domestic material designation rules. Technology transfer agreements proliferate as foreign manufacturers seek qualification under local production requirements.
Japan
PMDA streamlined review processes for companion diagnostic frameworks align antigen qualification standards with evolving harmonization efforts between FDA and EMA. Tokyo and Osaka metropolitan areas concentrate automated immunoassay platform manufacturing that locks in reagent supply relationships. Domestic pharmaceutical sponsors vertically integrate antigen production to secure supply chain control for mRNA platform characterization.
United Kingdom
Post-Brexit regulatory divergence from EU IVDR creates parallel qualification pathways that strain regulatory affairs capacity across supplier organizations. The Oxford-Cambridge arc and London metropolitan region maintain serological surveillance and academic research procurement for mechanistic studies. Blood transfusion services enforce stringent quality control reagent specifications that favor mammalian glycosylation patterns.
Viral Antigens Market Competitive Environment
Listed leaders compete with private specialists across regulatory qualification infrastructure and captive biomanufacturing scale. The supplier base stratifies into three tiers: diversified life science conglomerates with end-to-end control over raw material sourcing, mid-cap diagnostic reagent specialists with deep vertical integration into quality control applications, and emerging contract manufacturers serving regional NMPA qualification pathways. Consolidation accelerates through multi-year sole-source reagent contracts and joint venture structures for domestic material designation access.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify scale-driven positioning through integrated raw material-to-finished-assay control. Abbott Laboratories anchors the diagnostic platform-locked segment with automated immunoassay ecosystem integration. Among specialized reagent manufacturers, Bio-Rad Laboratories occupies a position in blood-banking and transplant diagnostic quality control, while Roche and bioMerieux represent European-based qualification-heavy archetypes navigating IVDR performance evaluation requirements. Merck KGaA sits within the chemical-and-life-science hybrid structure serving vaccine potency testing applications.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| Abbott Laboratories |
| Bio-Rad Laboratories |
| Thermo Fisher Scientific |
| DiaSorin |
| Merck KGaA |
| bioMerieux SA |
| Creative Diagnostics |
| Danaher Corporation |
| Others |
Value Chain & Pricing Dynamics
CE marking under the EU In Vitro Diagnostic Regulation gates both supplier qualification and price differentiation simultaneously, compressing margin pools toward manufacturers with dedicated clinical evidence infrastructure while filtering out competitors unable to absorb fixed compliance costs.
Pricing Analysis
Certification level creates the primary spread across the viral antigen supply base. Three-tier pricing structure across premium, standard, and economy levels reflects IVDR performance evaluation status, FDA master file documentation, and lot-to-lot consistency guarantees. Pricing pressure stems from peptide synthesis substitution in epitope-specific serology panels, compressing addressable scope for full-length recombinant suppliers. Academic institutions exhibit highest price sensitivity due to grant-funded procurement cycles, while large reference laboratories in Germany and the United States prioritize qualification over unit cost.
Supply Chain Analysis
The United States and Germany anchor high-value diagnostic reagent manufacturing, while China scales recombinant protein expression capacity to serve NMPA domestic material pathways. Production draws from fetal bovine serum sourced through South American and New Zealand collection cycles, baculovirus expression systems, and CRISPR-edited mammalian cell lines. Single-source vulnerability concentrates in serum supply regions with climate-sensitive collection patterns. Distribution runs through multi-year sole-source contracts bundling reagent supply with instrument placement, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The viral antigens market sits in early-cycle expansion as mRNA and viral-vector vaccine platforms multiply characterization demands across preclinical through commercial stages.
For Market Incumbents: Compound platform-locked positions through automated immunoassay ecosystem integration and captive biomanufacturing scale in Suzhou or Shanghai to qualify under NMPA domestic material rules. IVDR performance evaluation requirements threaten mid-tier competitors lacking clinical evidence infrastructure; backward integration into gene-edited expression systems secures glycosylation control differentiation. For New Entrants and Emerging Players: Lead with CRISPR-edited cell line development services for vaccine sponsors requiring enhanced glycosylation optimization, targeting contract research organizations in China seeking rapid-turnaround characterization. NMPA accelerated review pathways for locally produced diagnostic raw materials represent the most penetrable entry point; technology transfer partnerships with foreign manufacturers seeking domestic qualification offer the clearest go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across recombinant antigen production as mammalian cell culture infrastructure and IVDR compliance capabilities concentrate value capture. Five-to-ten year viability favors specialized reagent manufacturers with blood-banking quality control positions or regional NMPA qualification structures. The signal to watch is consolidation velocity among mid-tier suppliers unable to sustain 18-24 month CE marking timelines under IVDR class D rules.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Performance Evaluation Investment | CE marking under EU IVDR class D rules filters market access toward qualified suppliers with clinical evidence infrastructure. |
| NMPA Domestic Material Qualification | Accelerated review pathways in China redirect Asia-Pacific procurement toward indigenous biomanufacturing clusters. |
| Automated Immunoassay Integration | Platform-locked reagent contracts with closed-system analyzers create switching cost advantages in reference laboratories. |
| CRISPR-Edited Expression System Development | Gene-edited cell lines combining glycosylation control with synthetic biology yield optimization enable differentiated performance claims. |
| Multi-Year Sole-Source Contracting | Bundled reagent supply with instrument placement concentrates purchasing power among large health system integrated delivery networks. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with diagnostic laboratory procurement directors, vaccine development executives, regulatory affairs leads at IVD manufacturers, and quality control managers at blood-banking facilities. Secondary validation drew from FDA 510(k) filings, EMA IVDR technical documentation, NMPA domestic material designation records, and hospital procurement database extracts. Bottom-up segment sizing triangulated against top-down industry revenue estimates across recombinant antigen, synthetic antigen, and whole virus product categories.
Across the analysis window, the forecast framework modeled volume and value trajectories by product type, application segment, end-user category, and delivery mode. CAGRs were derived from regression analysis against vaccine pipeline advancement rates, diagnostic laboratory consolidation patterns, and regulatory approval velocity. Industry-specific inputs included mRNA platform characterization demand curves, IVDR certification timeline distributions, and NMPA review pathway throughput metrics.
The analysis sits within stated boundaries; outcomes outside sustained vaccine platform investment or IVDR harmonization progress would require recalibration. Forecasts reflect assumptions about regulatory enforcement consistency, serum supply stability, and peptide synthesis substitution rates in customized serology. Recalibration cycles align with material shifts in EU IVDR implementation guidance and NMPA domestic material policy revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Animal Diagnostics Market
Diagnostics
Multiplex Molecular Diagnostics Market
Diagnostics
Global Urinalysis Market
Diagnostics
Middle East and Africa Liver Cancer Diagnostics Market
Diagnostics
Autoimmunity Immunoassay Market
Diagnostics
Epilepsy Diagnosis and Treatment Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
LDL Test Market
Diagnostics
Netherlands in-Vitro Diagnostics Market
Diagnostics
Mexico in-Vitro Diagnostics Market
Diagnostics
Middle East and Africa HIV Diagnosis and Treatment Market
Diagnostics
Infectious Respiratory Disease Diagnostics Market
Diagnostics
Direct Fluorescent Antibody Test Kits Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
Cervical Cancer Diagnostic Tests Market
Diagnostics
Sperm Count Test Market