
 Global Cell Based Assays Market | 2026-2036
Global Cell Based Assays Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cell Based Assays Market Foresight
Live-cell imaging substrates and label-free detection materials are rebalancing capital allocation across assay platforms. Thermo Fisher Scientific leverages its consumables scale to dominate reagent supply for high-content screening workflows. Danaher Corporation sustains instrumentation leadership through integrated fluorescence and luminescence detection architectures. Lonza Group AG specializes in primary cell sourcing that anchors its position in physiologically relevant toxicology applications.
Cell based assays are analytical procedures using living cells as experimental models to measure biological responses, typically quantifying parameters such as cell viability, proliferation, signal transduction, or protein expression through optical readouts including fluorescence intensity, luminescence emission, or impedance shifts. These systems serve pharmaceutical and biotechnology industries by enabling predictive efficacy and safety profiling of drug candidates prior to animal studies and clinical trials. Reagents and kits capture the largest share of product-type revenue due to recurring purchase cycles tied to screening volume, while high-content screening represents the fastest-expanding assay technology segment as multiparametric imaging displace single-readout methods. Software platforms remain the highest-margin category despite smaller absolute revenue, since data analysis and image informatics command premium pricing relative to commoditized consumables.
FDA guidelines on physiologically relevant toxicity testing and EMA's emphasis on alternative methods under REACH both mandate greater reliance on living-cell models over biochemical surrogates, directly expanding compliant assay demand. China's NMPA alignment with ICH standards and Japan's PMDA adoption of organoid-based safety data further harmonize cross-border product requirements for multinational kit and instrument suppliers. Stakeholders must monitor evolving regulatory acceptance of complex 3D spheroid and organoid formats against traditional monolayer assays, as this determination will reshape platform investment priorities and competitive differentiation across the vendor landscape.
Market Dynamics
FDA toxicity testing mandates are compressing biochemical assay lifecycles while contract research organizations scale high-content screening infrastructure across three continents. This regulatory-hardware convergence is redistributing capital toward living-cell platforms and away from legacy endpoint detection systems.
Growth Catalysts
- ICH-aligned harmonization:China's NMPA adoption of international safety standards accelerates cross-border kit validation and reduces duplicate testing protocols for multinational pharmaceutical sponsors.
- Organoid-based safety submissions:Japan's PMDA acceptance of 3D tissue data for IND filings expands addressable assay demand beyond traditional monolayer formats into complex model systems.
- REACH alternative method mandates:ECHA's emphasis on reducing animal testing under European chemicals regulation creates compliant demand for human-derived cell models in toxicology workflows.
Market Restraints
- Primary cell supply concentration:Donor tissue sourcing networks cluster in the United States and Switzerland, creating geographic vulnerability for physiologically relevant assay manufacturers.
- Specialized skill scarcity:Image informatics and multiparametric data analysis expertise concentrates in Boston and Basel, inflating labor costs for contract research scaling.
- Biochemical assay installed base:Existing fluorescence plate reader infrastructure in mid-tier pharmaceutical laboratories delays full platform conversion despite regulatory pressure.
Strategic Opportunities
- India CDMO buildout:Contract development organizations in Hyderabad and Bangalore are constructing high-content screening capacity to capture redirected Western pharmaceutical outsourcing.
- AI-image analysis convergence:Machine learning classification of phenotypic signatures reduces manual annotation burden and accelerates hit-to-lead timelines for discovery teams.
- Microphysiological system integration:Multi-organ chip platforms address FDA calls for systemic toxicity prediction beyond single-cell-type readouts.
Industry Challenges
- 3D assay standardization gaps:Spheroid and organoid protocols lack inter-laboratory reproducibility metrics, complicating regulatory submission packages and cross-site validation.
- Legacy LIMS integration friction:High-content imaging data formats conflict with established pharmaceutical data architecture, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cell Based Assays Market |
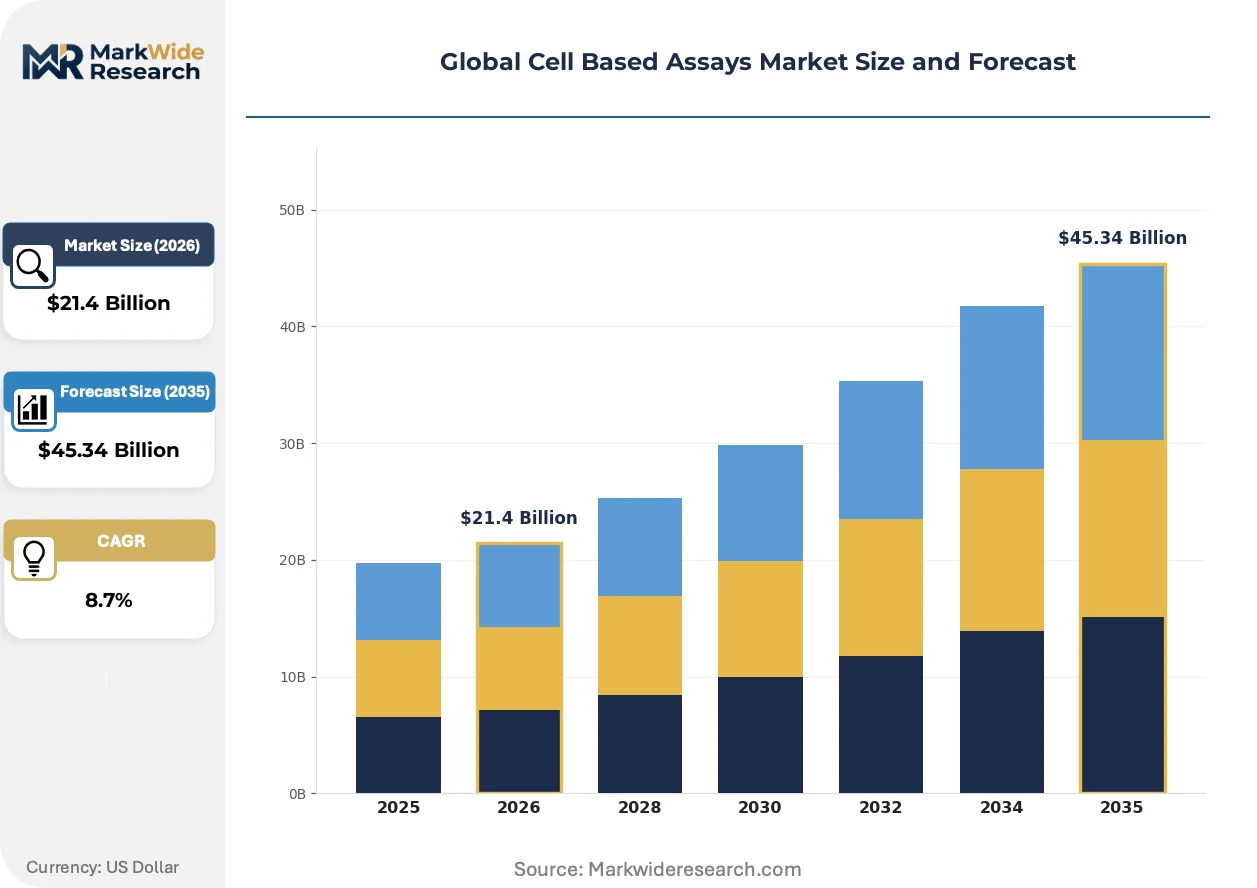
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $45.34 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Kits, Software Platforms, Consumables Assay Technology: Fluorescence, Luminescence, Colorimetric, High-Content Screening, Impedance-Based Application Area: Drug Discovery, Toxicology Testing, Genomics, Proteomics, Immunology End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher Corporation, Merck KGaA, BD, Bio-Rad Laboratories, Inc., Agilent Technologies, Inc., Lonza Group AG, Charles River Laboratories, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cell Based Assays Market Shifts & Advancements
Label-free detection modalities and live-cell imaging substrates are converging to displace endpoint fluorescence in high-throughput workflows. This hardware-software recombination is compressing assay timelines while expanding parameter resolution.
Impedance-based monitoring systems track cellular responses through electrical property shifts without fluorescent reporters or dye loading steps. Large pharmaceutical discovery groups in New Jersey and Basel are deploying these platforms for continuous kinetic profiling. The technology is expanding into toxicity screening applications previously dominated by labor-intensive manual microscopy.
REACH alternative method mandates and FDA Modernization Act 2.0 provisions are codifying living-cell model acceptance for regulatory submissions. European chemical registrants now face explicit animal testing reduction targets, while US IND sponsors gain explicit permission to submit non-animal safety data. Toxicology service providers in Germany and the Netherlands are restructuring capacity toward compliant human cell systems.
Pharmaceutical procurement teams are unbundling instrument hardware from reagent supply contracts to secure pricing leverage. This purchasing pattern shift fragments vendor lock-in strategies that previously coupled detection platforms to proprietary consumable streams. The practice is most visible among mid-cap biotechnology companies in Cambridge and South San Francisco negotiating high-content screening deployments.
Global Cell Based Assays Market Segmentation
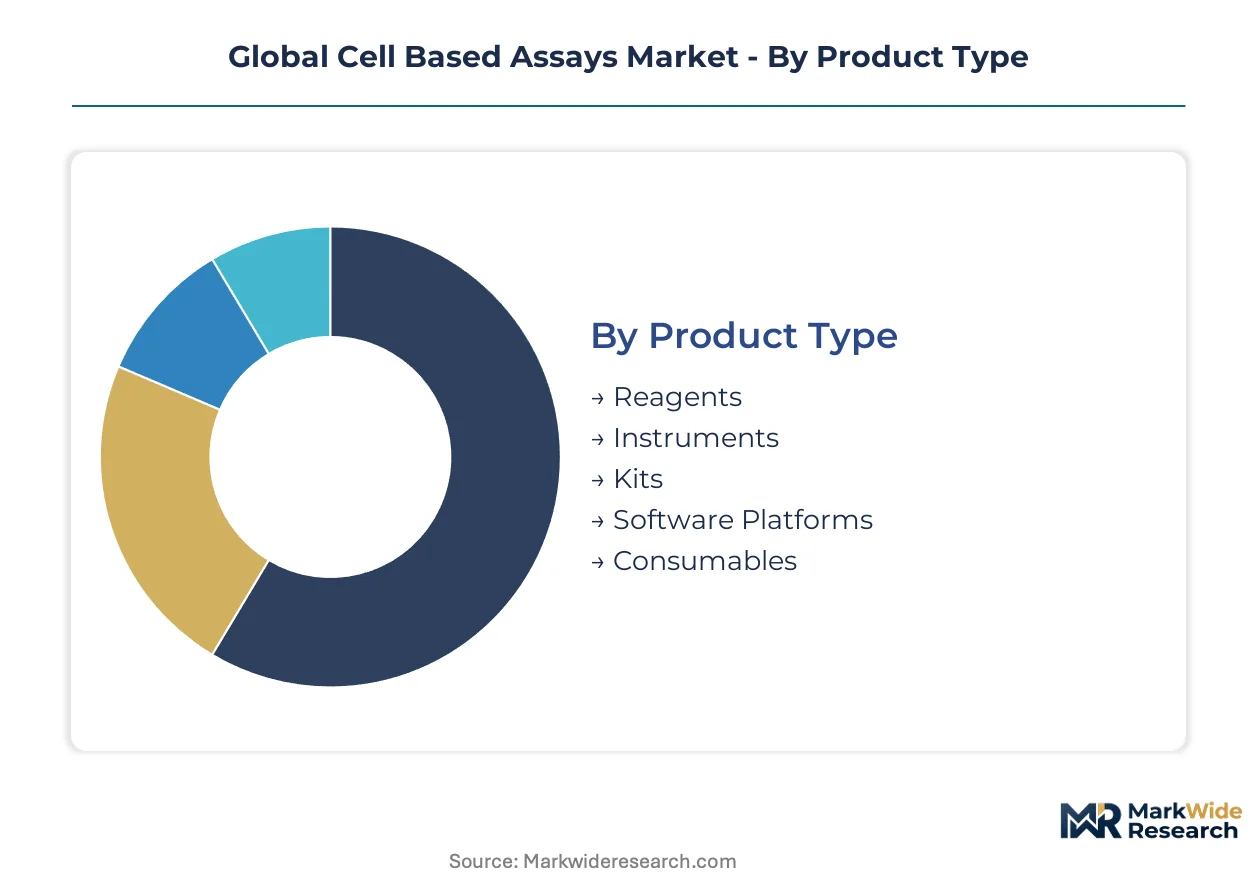
Cell-based assay segmentation reflects divergent integration models across pharmaceutical workflows. Standalone instrument platforms anchor capital-intensive screening operations, while embedded reagent-consumable systems drive recurring revenue streams through high-throughput repetition cycles.
Product Type:
Integration depth varies sharply: reagents and consumables embed directly into daily screening workflows, while instruments and software function as standalone infrastructure investments.
- Reagents:Biochemical formulations including reporter dyes, cell culture media supplements, and detection substrates enable fluorescent and luminescent readouts. Demand concentrates in Cambridge, Massachusetts and Basel, Switzerland, where high-throughput screening facilities consume bulk volumes under recurring procurement contracts tied to compound library sizes.
- Instruments:Automated liquid handlers, plate readers, and imaging systems constitute capital equipment with 5-7 year replacement cycles. Pharmaceutical companies in New Jersey and Germany's Rhine-Main region prioritize multi-mode detection platforms that consolidate fluorescence, luminescence, and imaging capabilities into single footprints.
- Kits:Pre-formulated assay packages reduce protocol development time for standardized applications.
- Software Platforms:Image analysis and data management tools command premium pricing through subscription models.
- Consumables:Microplates, cell culture vessels, and disposable tips represent high-volume, low-margin recurring purchases.
Reagents lead volumes today; software platforms are gaining share fastest.
Assay Technology:
Cost tier stratification separates premium multiparametric imaging from economy colorimetric endpoints, with mid-tier luminescence and impedance systems capturing expanding toxicology applications.
- High-Content Screening:Multiparametric imaging platforms capture subcellular resolution across thousands of cells per well, enabling phenotypic profiling beyond single-readout biochemical assays. Contract research organizations in China and Germany are scaling this capacity to meet FDA demands for physiologically relevant toxicity data.
- Impedance-Based:Label-free electrical monitoring tracks cell adhesion, proliferation, and cytotoxicity without dye loading or phototoxicity artifacts. Large pharmaceutical discovery groups in New Jersey deploy these systems for continuous kinetic profiling previously requiring labor-intensive manual microscopy.
- Fluorescence:Mature detection modality with extensive installed base across mid-tier laboratories.
- Luminescence:High-sensitivity ATP and reporter gene assays dominate cytotoxicity and signal transduction workflows.
- Colorimetric:Economy-tier endpoint detection for routine viability assays in resource-constrained settings.
Fluorescence leads volumes today; high-content screening is climbing the fastest.
Application Area:
Application maturity determines vendor positioning: drug discovery commands integrated platform sales, while emerging immunology applications favor specialized kit suppliers.
- Drug Discovery:Lead optimization and target validation workflows consume the broadest assay technology portfolio, from primary screening biochemical formats to complex disease model systems. Biotechnology firms in South San Francisco and Cambridge prioritize high-content phenotypic screening to reduce late-stage attrition rates.
- Toxicology Testing:Regulatory-compliant safety profiling demands human-derived cell models replacing animal studies under FDA Modernization Act provisions. Service providers in Germany and the Netherlands are restructuring capacity toward REACH-compliant cell-based hazard assessment.
- Genomics:CRISPR screening and gene expression analysis applications.
- Proteomics:Protein-protein interaction and post-translational modification assays.
- Immunology:Immune cell activation and cytokine profiling for cell therapy development.
Drug discovery leads volumes today; toxicology testing shows the steepest expansion trajectory.
End User:
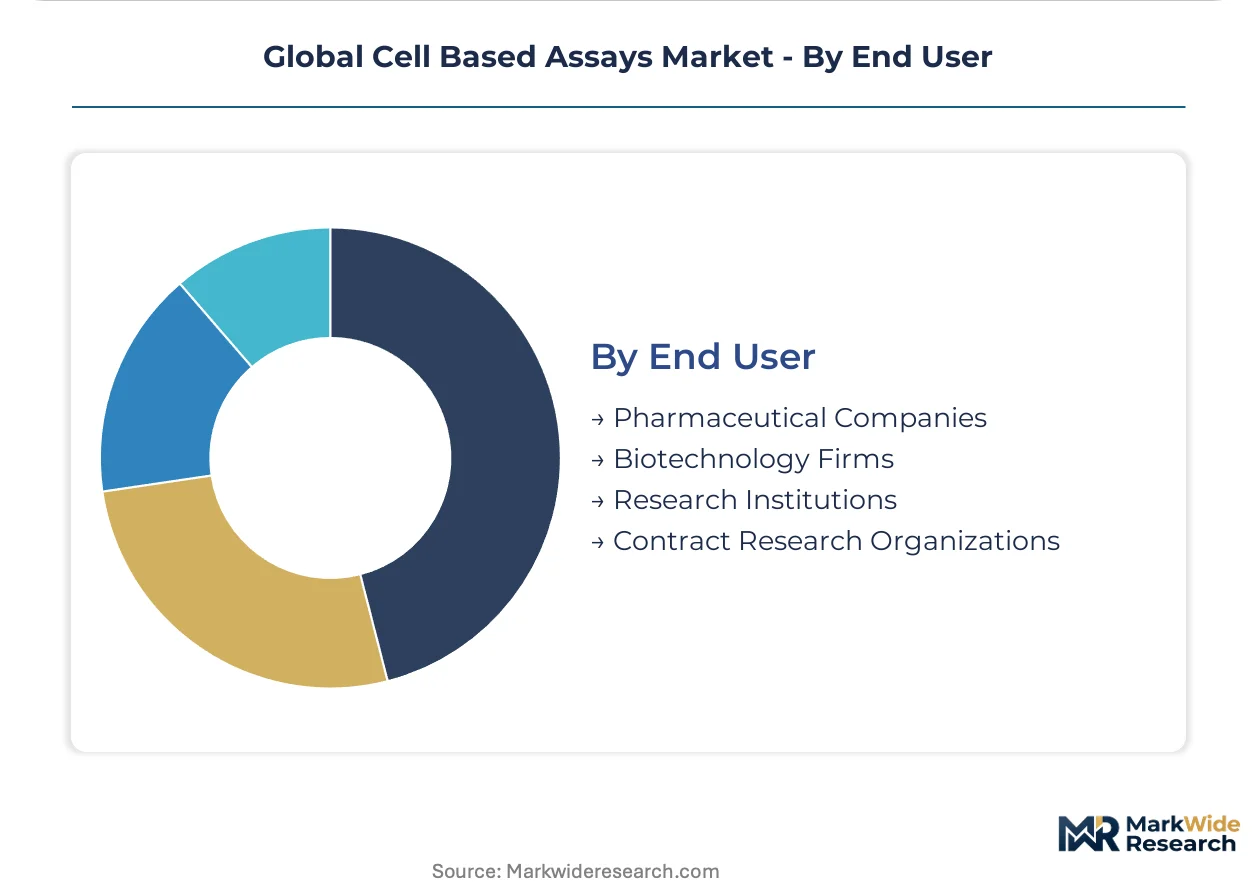
Customer type dictates procurement leverage: pharmaceutical majors unbundle hardware from reagent contracts, while contract research organizations seek bundled platform-discount structures.
- Pharmaceutical Companies:Internal discovery and safety assessment groups operate high-throughput infrastructure with dedicated automation engineering teams. Mid-cap biotechnology companies in Cambridge and South San Francisco increasingly decouple instrument purchases from proprietary consumable streams to secure pricing leverage.
- Contract Research Organizations:Externalized screening capacity scales across three continents to capture redirected pharmaceutical outsourcing. CDMO buildouts in Hyderabad and Bangalore are constructing high-content screening infrastructure to serve Western sponsor demand.
- Biotechnology Firms:Resource-constrained innovators favor flexible kit-based solutions over capital-intensive platform investments.
- Research Institutions:Academic laboratories prioritize modular, publication-validated assay formats with minimal technical support requirements.
Pharmaceutical companies lead volumes today; contract research organizations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston and Basel anchor pharmaceutical discovery demand, while contract research infrastructure scales across three continents to capture redirected outsourcing flows.
United States
FDA toxicity testing mandates compress biochemical assay lifecycles and accelerate living-cell platform procurement. The FDA Modernization Act 2.0 explicitly permits non-animal safety data submissions for IND filings. New Jersey pharmaceutical discovery groups deploy multi-mode detection platforms for continuous kinetic profiling.
Germany
ECHA's REACH alternative method mandates create compliant demand for human-derived cell models in toxicology workflows. The country's national pharmaceutical regulator aligns with EMA emphasis on reducing animal testing. Rhine-Main region pharmaceutical companies prioritize consolidated fluorescence and luminescence detection capabilities.
China
NMPA alignment with ICH safety standards accelerates cross-border kit validation for multinational sponsors. The national medical products regulator harmonizes international standards to reduce duplicate testing protocols. Contract research organizations in Shanghai and Suzhou scale high-content screening infrastructure to serve Western demand.
Japan
PMDA acceptance of organoid-based safety data for IND filings expands assay demand beyond traditional monolayer formats. The national pharmaceutical regulator explicitly recognizes 3D tissue data in regulatory submissions. Tokyo and Osaka pharmaceutical clusters invest in complex model systems for systemic toxicity prediction.
India
Contract development organizations construct high-content screening capacity to capture redirected Western pharmaceutical outsourcing. CDSCO alignment with international safety standards facilitates export-oriented kit manufacturing. Hyderabad and Bangalore CDMO buildouts target high-throughput screening service contracts from European and North American sponsors.
Global Cell Based Assays Market Competitive Landscape
Capacity expansion dominates the current landscape as contract research organizations scale high-content screening infrastructure across three continents. The vendor base separates into instrumentation specialists, reagent-scale suppliers, and integrated platform providers. Three strategic archetypes define competitive positioning: consumables-dominant players leveraging recurring purchase cycles, detection-technology specialists commanding capital equipment replacement decisions, and cell-sourcing experts anchoring physiologically relevant toxicology applications. M&A activity and geographic expansion represent the dominant competitive moves as participants seek to unbundle hardware from reagent contracts.
Among United States-based diversified conglomerates, Thermo Fisher Scientific Inc. exemplifies consumables-scale positioning through reagent supply dominance. Danaher Corporation occupies the instrumentation leadership tier through integrated detection architectures. Swiss-domiciled Lonza Group AG represents the cell-sourcing specialist archetype, anchoring primary cell supply networks for toxicology applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Merck KGaA |
| BD |
| Bio-Rad Laboratories, Inc. |
| Agilent Technologies, Inc. |
| Lonza Group AG |
| Charles River Laboratories |
| Promega Corporation |
| Others |
Supply & Pricing Matrix
Pharmaceutical procurement teams unbundling instrument hardware from reagent supply contracts are forcing consumables suppliers toward volume-based pricing models and away from bundled platform premiums. This purchasing pattern shift fragments vendor lock-in strategies that previously coupled detection platforms to proprietary consumable streams, compressing margins on standalone reagent kits while elevating price transparency across the vendor landscape.
Pricing Analysis
Input-cost pass-through from primary cell sourcing and specialized detection substrates shapes pricing dynamics across assay tiers. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified human-derived cell systems from research-grade alternatives and basic biochemical formulations. Pricing pressure stems from mid-cap biotechnology companies in Cambridge and South San Francisco negotiating aggressive volume discounts for high-content screening deployments. Contract research organizations exhibit highest price sensitivity due to thin service margins, while pharmaceutical majors prioritize regulatory compliance over unit cost.
Supply Chain Analysis
China's NMPA domestic-content preferences and India's PLI scheme for medical devices are redirecting kit manufacturing toward local production hubs. Supply concentrates in the United States for primary cell sourcing, Switzerland for GMP-compliant tissue networks, and China for bulk reagent formulation. The chain draws from fluorescent reporter dyes, cell culture media supplements, and specialized microplates as critical inputs. Single-source vulnerability clusters around donor tissue networks in Boston and Basel. Distribution runs through direct vendor relationships with large pharmaceutical accounts and tiered distributor networks serving mid-tier laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EMA-aligned regulatory acceptance in Germany and the Netherlands commands premium pricing against cost-optimized kit production in India and China.
For Market Incumbents: Deploy consumables-scale leverage to defend reagent market share against emerging platform-agnostic suppliers. Thermo Fisher Scientific and Danaher Corporation should deepen captive supply of primary cell sourcing networks to offset donor tissue concentration risk in the United States and Switzerland. Incumbents must accelerate AI-image analysis integration to neutralize software platform commoditization threats from specialized informatics entrants.
For New Entrants and Emerging Players: FDA Modernization Act 2.0 in the United States opens a window for organoid-based assay specialists to capture toxicology testing demand shifting away from animal models. White-space targets include impedance-based detection systems for continuous kinetic profiling and microphysiological system integration for multi-organ chip platforms. New entrants should prioritize service-based revenue models with contract research organizations in Hyderabad and Bangalore over capital-intensive instrument manufacturing.
For Investors and Strategic Acquirers: Asymmetric upside sits with cell-sourcing specialists possessing GMP-certified donor networks and 3D spheroid protocol libraries. Long-term viability hinges on regulatory acceptance trajectories for complex model systems against traditional monolayer assays. Acquisition targets should demonstrate validated interoperability with established pharmaceutical LIMS architectures. The critical signal to watch is PMDA expansion of organoid-based safety data acceptance beyond current IND filing categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Primary Cell Sourcing Network Expansion | GMP-certified donor tissue networks in Switzerland anchor physiologically relevant toxicology positioning. |
| AI-Image Analysis Platform Integration | Machine learning phenotypic classification accelerates hit-to-lead timelines for discovery teams. |
| Microphysiological System Development | Multi-organ chip platforms address FDA systemic toxicity prediction mandates beyond single-cell readouts. |
| High-Content Screening Infrastructure Scale-Up | CDMO buildouts in Hyderabad capture redirected Western pharmaceutical outsourcing flows. |
| Regulatory Compliance Certification Investment | REACH alternative method validation opens European toxicology service contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, high-content screening facility directors, and contract research organization procurement managers with secondary validation. Sources included FDA Modernization Act implementation guidance, EMA alternative method validation databases, NMPA ICH alignment announcements, ClinicalTrials.gov assay technology tags, and SEC 10-K disclosures from diversified life sciences conglomerates. Bottom-up reagent volume modeling and top-down instrument replacement cycle analysis were triangulated against regional regulatory filing trends.
Segment-weighting approaches distributed value across product type, assay technology, application area, and end user dimensions, with additional stratification by regional regulatory cluster alignment. CAGRs were derived from instrument replacement cycle analysis, reagent consumption per screening campaign, and outsourcing penetration trajectories. Forecast inputs incorporated high-content screening capacity buildout announcements, primary cell donor network expansion plans, and AI-image analysis adoption curves across pharmaceutical discovery groups.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt shifts in regulatory acceptance of 3D spheroid formats or sustained primary cell supply disruptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Cell Separation Market
Biomedical Technology
Global Glycomics/Glycobiology Market
Biomedical Technology
Cell Proliferation Assay Market
Biomedical Technology
3D Cell Culture Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Global Automated Cell Cultures Market
Biomedical Technology
Blood Brain Barrier Technologies Market
Biomedical Technology
Global Protein Crystallization and Crystallography Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Global Transfection Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
Global Expression Vectors Market
Biomedical Technology
In Vitro Protein Expression Market
Biomedical Technology
High-End Cellomics Market
Biomedical Technology
Live Cell RNA Detection Market
Biomedical Technology
Immunoprecipitation Market