
 Live Cell Analysis System Market | 2026-2036
Live Cell Analysis System Market Size, Share, and Industry Trends Forecast 2026-2036
Live Cell Analysis System Market Analytics
Deep learning-powered image segmentation is tilting live cell analysis from endpoint assays toward continuous, label-free monitoring workflows. Thermo Fisher Scientific leverages its CellInsight platform to anchor high-content screening positions in pharmaceutical accounts. Danaher Corporation sustains competitive density through Leica Microsystems' confocal systems and Sartorius AG's cell counting portfolio. Carl Zeiss AG differentiates through lattice light-sheet architectures that extend temporal resolution for developmental biology applications.
Live cell analysis systems comprise integrated microscopy, cytometry, and computational platforms that capture kinetic cellular behaviors across minutes to weeks using environmental control chambers maintaining temperature, humidity, and gas composition. These instruments serve primary functions in quantifying cell proliferation, migration, and morphological dynamics for therapeutic validation and basic mechanistic studies. Fluorescence microscopes occupy the largest installed base among product types, though image analyzers are gaining fastest in gene expression workflows requiring multiplexed reporter quantification. Time-lapse imaging dominates technology adoption in stem cell research, while automatic digital imaging commands premium positioning in contract research organizations seeking throughput scalability.
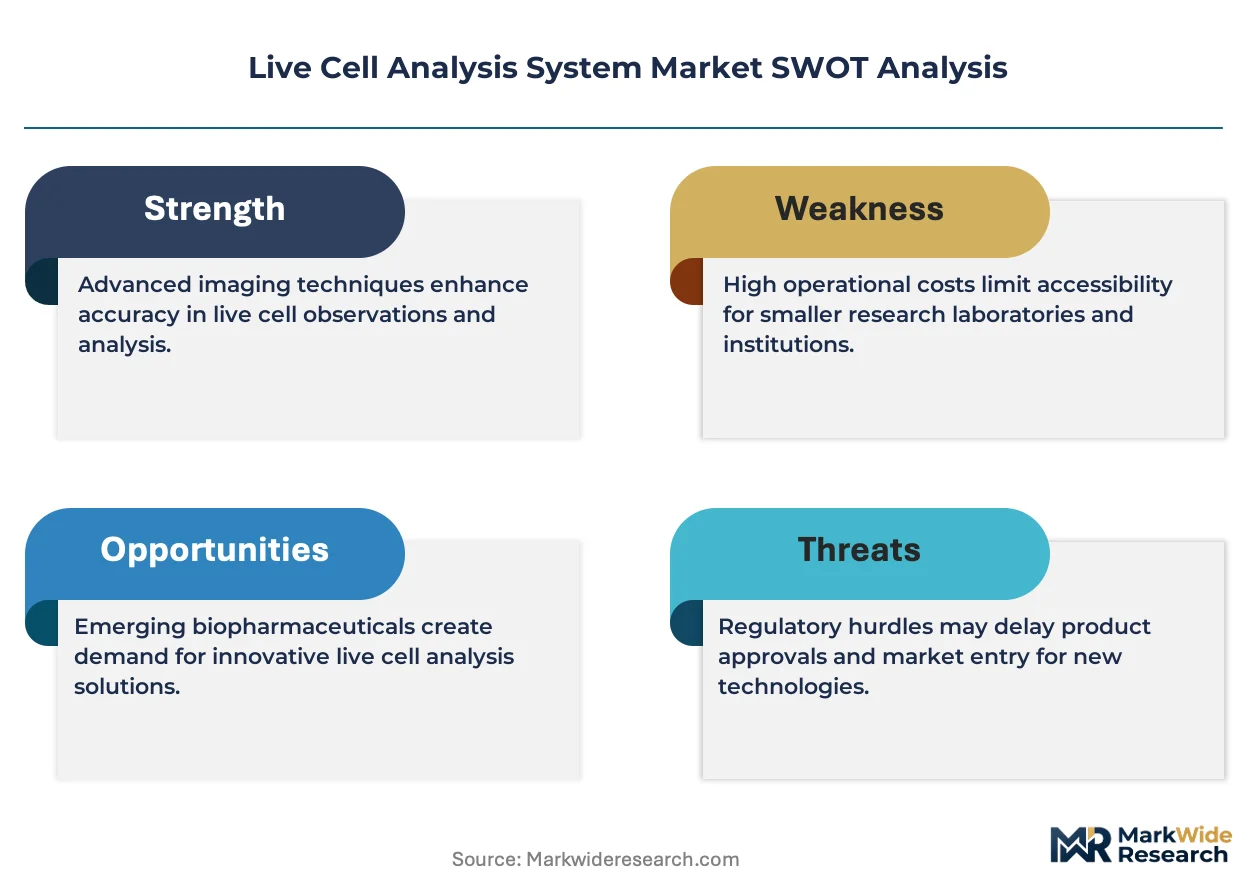
FDA 21 CFR Part 11 compliance requirements shape software validation burdens for pharmaceutical end users selecting live cell platforms, while EMA's ICH Q5D guidelines on cell substrate qualification drive documentation standards for biologics developers. ISO 13485 certification pressures instrument manufacturers serving clinical translation pathways, particularly in cell therapy quality control applications. Stakeholders must weigh regulatory validation costs against the analytical depth each technology tier delivers for their intended therapeutic or research modality.
Market Dynamics
Deep learning architectures are compressing assay development timelines from weeks to days, forcing incumbent platform vendors to reengineer software stacks around neural inference engines rather than traditional image processing pipelines.
Growth Catalysts
- ICH Q5D Guidelines:EMA's cell substrate qualification mandates drive biologics developers toward validated live cell platforms for documentation of cell line stability across manufacturing campaigns.
- AI-Enabled Phenotypic Screening:Pharmaceutical toxicology departments deploy convolutional neural networks to extract morphometric signatures from label-free time-lapse sequences, replacing endpoint viability assays.
- German Research Infrastructure:Max Planck Institutes and Fraunhofer centers anchor instrument procurement density, creating reference-site effects that accelerate adoption across European contract research networks.
Market Restraints
- Fluorophore Cost Volatility:Specialized live-cell compatible dyes derived from rare earth complexes face supply concentration in Chinese processing facilities, creating input cost instability for multiplexed imaging workflows.
- FDA 21 CFR Part 11 Validation Burden:Pharmaceutical end users absorb six-figure software validation costs per instrument deployment, extending sales cycles and depressing replacement frequency.
- Optical Throughput Limitations:Confocal architectures remain physically constrained by photon budget tradeoffs, capping temporal resolution for high-density multiwell applications.
Strategic Opportunities
- India Biologics Manufacturing:CDSCO's tightening cell substrate documentation requirements for biosimilar filings create first-mover advantage for validated platform vendors establishing local application support.
- Organ-on-Chip Convergence:Integration of live cell imagers with microfluidic tissue models enables longitudinal toxicity readouts that static endpoint assays cannot capture.
- Cell Therapy Quality Control:ISO 13485-certified instruments command premium positioning in GMP-compliant potency release workflows for CAR-T and iPSC-derived therapeutics.
Industry Challenges
- Computational Microscopy Talent Scarcity:Core facilities struggle to recruit image analysis specialists fluent in both biological assay design and GPU-accelerated pipeline optimization.
- Legacy LIMS Integration Friction:Proprietary data formats from closed-platform vendors resist extraction into enterprise data lakes, forcing custom API development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Live Cell Analysis System Market |
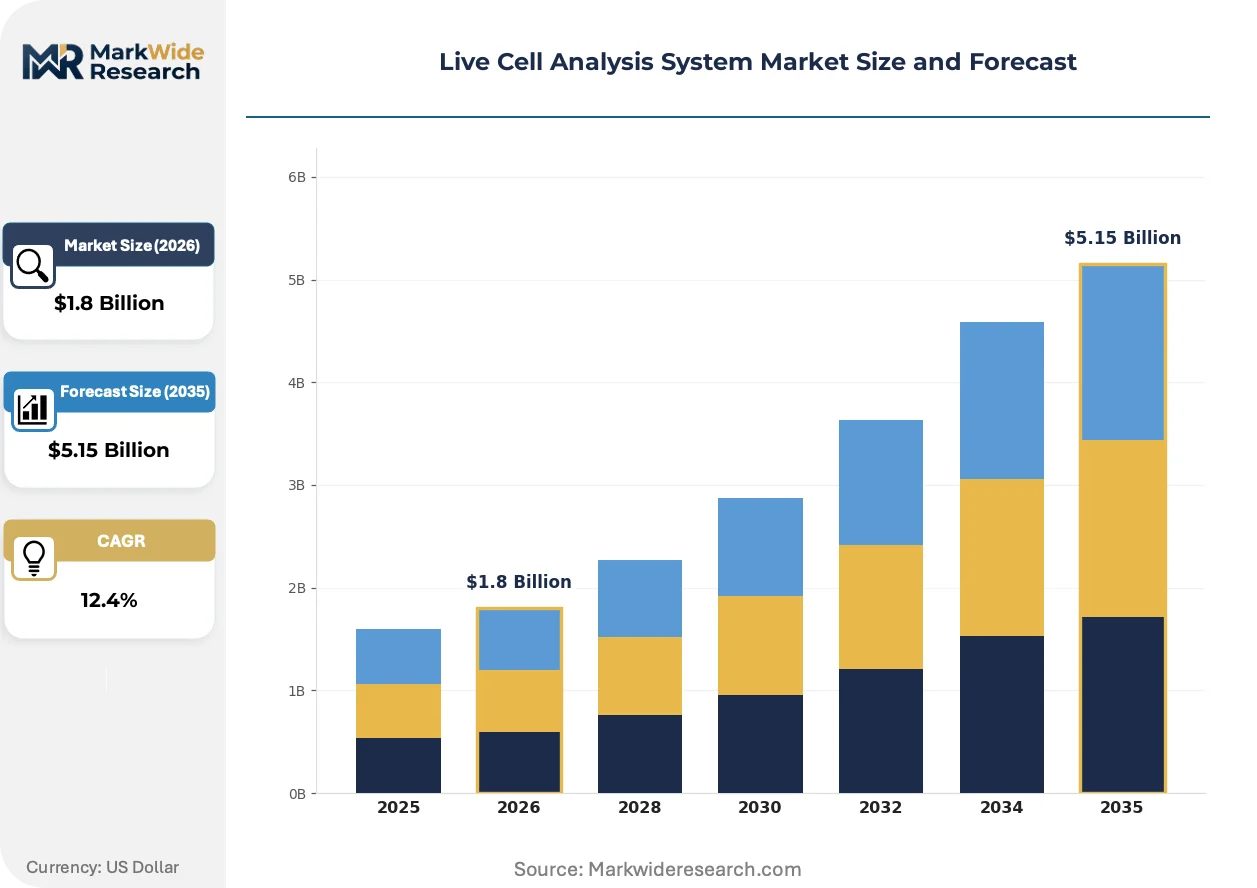
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescence Microscopes, Cell Counters, Image Analyzers, Flow Cytometers Technology: Time-Lapse Imaging, Automatic Digital Imaging, Image Cytometry, Multi-Cell Analysis End User: Academic Institutes, Pharmaceutical Companies, Contract Research Organizations, Biotechnology Firms Application: Cell Viability, Drug Discovery, Gene Expression, Stem Cell Research |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher Corporation, Carl Zeiss AG, Sartorius AG, Agilent Technologies, Leica Microsystems, Nikon Corporation, PerkinElmer Inc., Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Live Cell Analysis System Market Evolving Landscape
Instrument architectures are bifurcating between closed turnkey systems for routine screening and open programmable platforms enabling assay customization, with software modularity becoming the primary competitive differentiator.
Lattice light-sheet microscopy is hybridizing developmental biology workflows by extending imaging duration from hours to days without phototoxicity. Embryology departments at major research universities adopt these systems for lineage tracing experiments. The technology is compressing the temporal resolution gap between confocal point-scanning and widefield methods, enabling capture of rapid morphogenetic events previously inaccessible to longitudinal observation.
EMA's Medical Device Regulation (MDR) reclassification of automated cell analysis instruments is tightening clinical translation pathways for in-vitro diagnostic applications. Manufacturers must now maintain technical documentation and post-market surveillance systems previously exempt under the Medical Device Directive. Cell therapy quality control laboratories in Germany and the Netherlands face the steepest compliance ramps as they scale toward commercial manufacturing.
Core facility directors are unbundling capital acquisition from service contracts, negotiating instrument placement with reagent pull-through agreements rather than traditional lease structures. This procurement evolution concentrates purchasing authority with procurement departments rather than principal investigators. The shift is most visible in US academic medical centers where shared instrumentation grant funding has flattened.
Live Cell Analysis System Market Segmentation
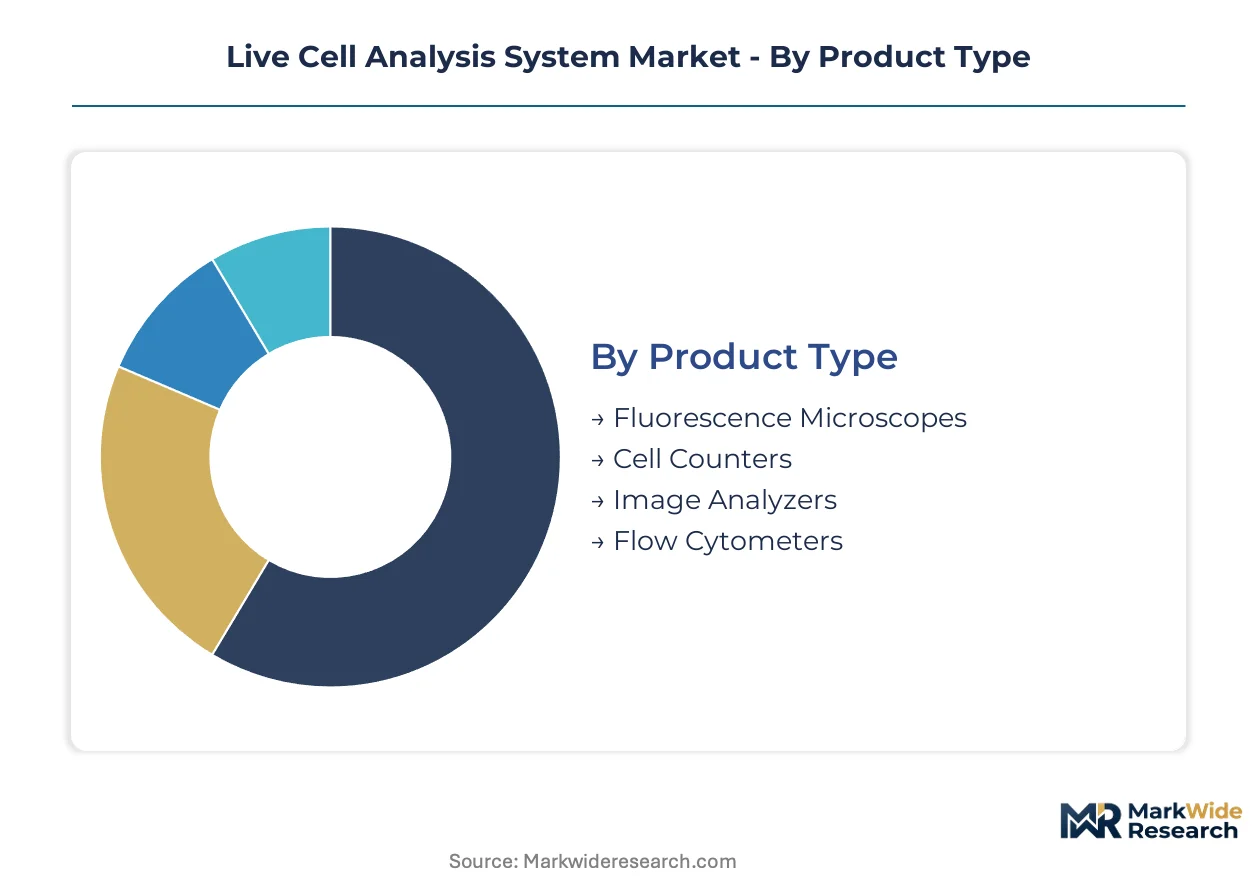
Live cell analysis systems serve heterogeneous workflows spanning basic research through GMP manufacturing, making granular segmentation essential for matching platform specifications to environmental control, throughput, and compliance requirements. Each dimension reveals distinct procurement patterns, from fluorescence microscopy dominance in academic core facilities to automated imaging acceleration in pharmaceutical toxicology departments.
Product Type:
Cost tier differentiation separates capital-intensive integrated platforms from modular benchtop instruments, with reagent pull-through economics reshaping procurement structures across end-use categories.
- Fluorescence Microscopes:These systems combine epifluorescence or confocal optical paths with environmental chambers maintaining temperature, humidity, and gas composition for longitudinal observation. Pharmaceutical companies in Germany deploy these for real-time drug toxicity screening under EMA ICH Q5D documentation requirements. The installed base concentrates in academic core facilities and biologics manufacturing quality control laboratories.
- Image Analyzers:Computational platforms integrating high-resolution sensors with GPU-accelerated segmentation algorithms for multiplexed reporter quantification. Demand is concentrating in gene expression workflows at Max Planck Institutes and Fraunhofer centers, where AI-driven image analysis replaces manual counting. These systems command premium positioning where throughput scalability outweighs capital intensity.
- Cell Counters:Benchtop instruments providing rapid viability and density measurements for routine culture monitoring.
- Flow Cytometers:Fluidics-based platforms enabling single-cell multiparameter analysis with live cell sorting capabilities.
Fluorescence microscopes command the established base. The steepest expansion runs through image analyzers.
Technology:
Application requirements determine temporal resolution needs, with developmental biology workflows demanding extended duration capture and pharmaceutical screening prioritizing multiwell throughput.
- Time-Lapse Imaging:Sequential frame acquisition at intervals from minutes to hours, enabling kinetic quantification of proliferation and migration without endpoint disruption. Stem cell research departments at German universities anchor adoption, leveraging lattice light-sheet extensions that stretch observation windows from hours to days without phototoxicity.
- Automatic Digital Imaging:Robotic plate handling with software-driven autofocus and exposure optimization for unattended high-content screening. Contract research organizations seeking throughput scalability drive procurement, particularly in European networks referencing Fraunhofer center validation protocols.
- Image Cytometry:Microscopy-based multiparameter analysis combining morphometric and fluorescence intensity readouts.
- Multi-Cell Analysis:Parallel tracking of individual cells within heterogeneous populations for lineage tracing applications.
Time-lapse imaging retains dominance in basic research settings. Automatic digital imaging is climbing the fastest in commercial screening workflows.
End User:
Customer type determines validation burden and procurement authority, with pharmaceutical accounts absorbing FDA 21 CFR Part 11 compliance costs and academic facilities prioritizing shared instrumentation grant structures.
- Pharmaceutical Companies:Integrated drug discovery and toxicology departments scaling live cell platforms for phenotypic screening and cell substrate qualification documentation. These end users absorb six-figure software validation costs per deployment, extending sales cycles but generating recurring reagent revenue streams.
- Academic Institutes:Core facilities and principal investigator laboratories unbundling capital acquisition from service contracts, negotiating placement agreements with procurement departments rather than traditional leases. Max Planck Institutes anchor instrument density with reference-site effects accelerating adoption across European contract research networks.
- Contract Research Organizations:Service providers prioritizing throughput scalability and regulatory documentation for client biologics programs.
- Biotechnology Firms:Cell therapy developers requiring ISO 13485-certified instruments for GMP-compliant potency release workflows.
Academic institutes maintain the deepest installed base. Pharmaceutical companies are gaining share fastest as biologics manufacturing scales.
Application:
Workflow maturity varies by therapeutic modality, with cell viability established as routine quality control and gene expression workflows accelerating through multiplexed reporter advances.
- Drug Discovery:Phenotypic screening and toxicity profiling across therapeutic programs, where convolutional neural networks extract morphometric signatures from label-free sequences. AI-enabled workflows are compressing assay development timelines from weeks to days, forcing platform vendors to reengineer software stacks around neural inference engines.
- Stem Cell Research:Longitudinal monitoring of pluripotency maintenance and directed differentiation, requiring environmental stability across days to weeks. Embryology departments at major research universities adopt lattice light-sheet systems for lineage tracing experiments previously inaccessible to continuous observation.
- Cell Viability:Routine proliferation and apoptosis quantification for culture optimization and quality control.
- Gene Expression:Multiplexed reporter quantification for pathway analysis and mechanistic studies.
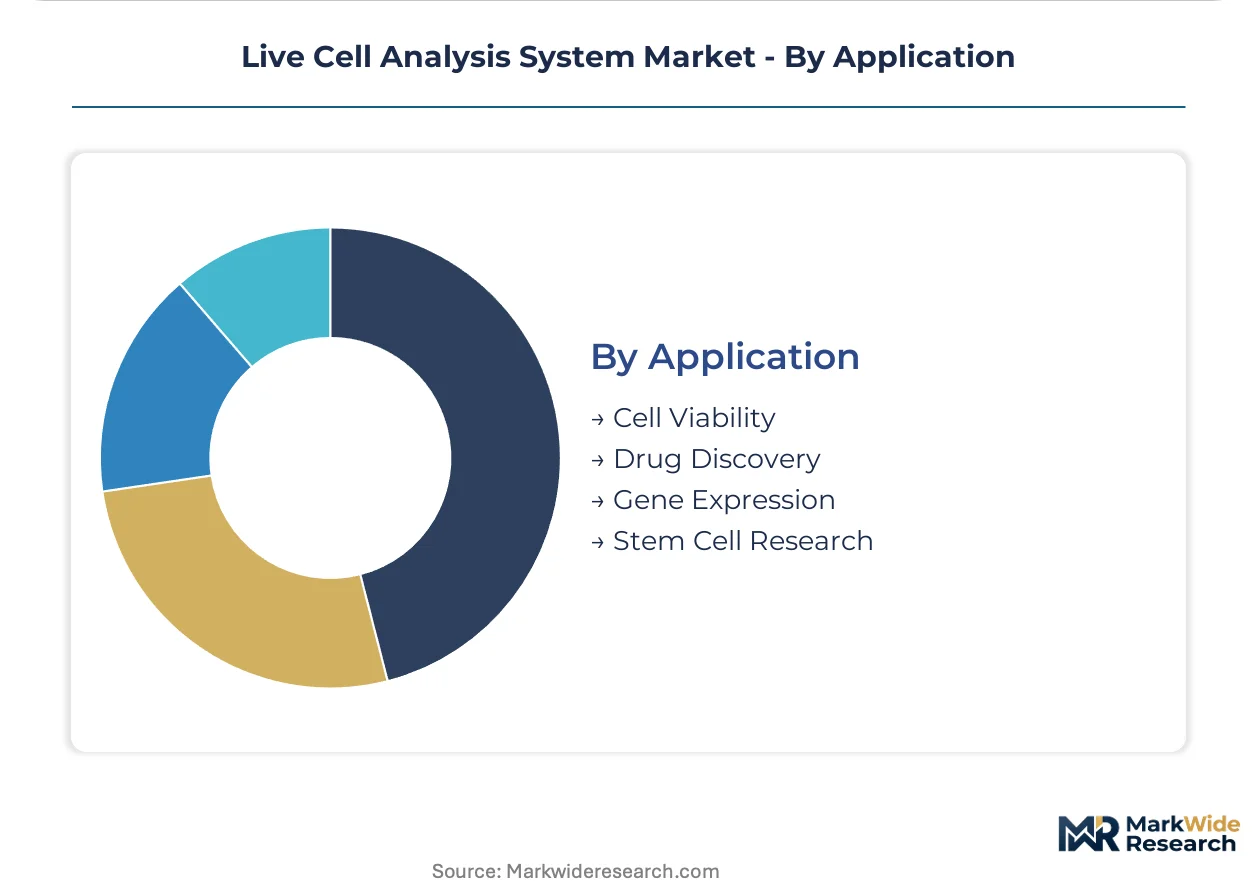
Cell viability applications command the established base. Drug discovery is expanding most quickly as pharmaceutical toxicology departments displace endpoint assays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a substantial live cell analysis instrument trade surplus, exporting confocal and light-sheet systems to biologics manufacturers across Europe and Asia while importing specialized image analysis software modules from US developers. The United States absorbs the largest absolute import volume of environmental control chambers and automated plate handlers. China's domestic production of benchtop cell counters is displacing Korean and Japanese imports in Southeast Asian markets.
United States
FDA 21 CFR Part 11 compliance requirements drive pharmaceutical toxicology departments toward validated platforms with extensive software documentation. The National Institutes of Health maintains shared instrumentation grant programs that fund core facility acquisitions at academic medical centers. Greater Boston anchors procurement density with reference-site effects accelerating adoption across contract research networks in the Research Triangle and San Francisco Bay Area.
Germany
EMA ICH Q5D guidelines on cell substrate qualification mandate live cell documentation for biologics manufacturing campaigns. The country's national pharmaceutical regulator enforces stringent post-market surveillance for automated cell analysis instruments under MDR reclassification. Bavaria concentrates instrument development with lattice light-sheet architectures emerging from research partnerships between Munich universities and optical engineering clusters.
China
NMPA tightening of cell therapy manufacturing documentation creates demand for ISO 13485-certified quality control platforms. The national medical products administration aligns with ICH guidelines for biologics substrate qualification. Yangtze River Delta biotech parks in Shanghai and Suzhou anchor procurement for CAR-T manufacturing facilities scaling toward commercial production.
Japan
PMDA guidelines on regenerative medicine products require longitudinal cell characterization data for iPSC-derived therapeutic approvals. METI funding programs support domestic development of AI-driven image analysis algorithms to reduce dependence on US software imports. Kansai region universities in Osaka and Kyoto maintain deep installed bases of time-lapse systems for stem cell research applications.
India
CDSCO tightening of cell substrate documentation requirements for biosimilar filings creates first-mover opportunities for validated platform vendors. The national pharmaceutical regulator mandates stability data across manufacturing campaigns for biologics license applications. Karnataka's biotech corridor in Bangalore anchors instrument procurement with contract manufacturing organizations scaling toward export markets.
Live Cell Analysis System Market Competitive Landscape
On the supply side, the industry is bifurcated between diversified life science conglomerates with full-stack microscopy portfolios and specialized imaging technology firms with narrow optical expertise. Platform vendors compete through software modularity rather than hardware differentiation, with neural inference engines replacing traditional image processing pipelines as the primary value anchor. Two strategic archetypes dominate: integrated system providers bundling environmental control with computational analysis, and modular component suppliers enabling assay customization. Consolidation pressure is intensifying through strategic partnerships between instrument manufacturers and AI software developers, alongside geographic expansion into emerging biologics manufacturing markets.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc., Danaher Corporation, and Carl Zeiss AG occupy positions exemplifying contrasting competitive vectors. Thermo Fisher Scientific Inc. represents the integrated platform archetype with bundled high-content screening and environmental control capabilities. Danaher Corporation sits within the multi-brand holding structure, aggregating confocal microscopy and cell counting assets across operating subsidiaries. Carl Zeiss AG anchors the precision optics tier, with lattice light-sheet architectures extending temporal resolution for developmental biology applications previously inaccessible to continuous observation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Carl Zeiss AG |
| Sartorius AG |
| Agilent Technologies |
| Leica Microsystems |
| Nikon Corporation |
| PerkinElmer Inc. |
| Olympus Corporation |
| Others |
Value Network & Pricing Analysis
Rare earth complex processing concentration in Chinese facilities anchors fluorophore cost volatility, pushing margin pools toward instrument vendors with captive dye formulation capabilities and long-term pharmaceutical service contracts.
Pricing Analysis
Pharmaceutical toxicology departments anchor tiered pricing stratification across premium GMP-compliant platforms, standard research-grade systems, and economy benchtop units. Price differentiation hinges on FDA 21 CFR Part 11 validation documentation depth and ISO 13485 certification status. Pricing pressure intensifies in the standard tier as modular open-platform vendors undercut integrated system premiums. Academic core facilities exhibit highest price sensitivity due to shared instrumentation grant funding constraints, while cell therapy manufacturers absorb premium positioning for GMP-compliant quality control workflows.
Supply Chain Analysis
Export-control restrictions on GPU-accelerated inference engines and high-resolution scientific CMOS sensors limit component flows from US and Japanese suppliers to Chinese instrument assemblers. Manufacturing concentration spans Germany for precision optics, Japan for scientific sensors, and China for environmental control chamber fabrication. Supply chain risk centers on single-source vulnerability for specialized live-cell compatible fluorophores derived from rare earth complexes. Distribution runs through direct field service organizations for pharmaceutical accounts and academic core facility grant administrators for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Live cell analysis is crossing into platform economics as AI inference engines and modular software architectures create winner-take-most dynamics around ecosystem interoperability and assay protocol standardization.
For Market Incumbents: Pre-empt modular open-platform encroachment by acquiring GPU-accelerated segmentation software specialists and embedding neural inference engines into legacy hardware footprints. Deepen backward integration into fluorophore formulation to neutralize Chinese rare earth supply volatility. Lock pharmaceutical accounts through reagent pull-through contracts that raise switching costs for validated assay protocols. For New Entrants and Emerging Players: Mid-market contract research organizations in India and Southeast Asia represent the most penetrable entry point, where CDSCO tightening of biosimilar documentation requirements outpaces established vendor application support capacity. Target gene expression workflow segments where image analyzer demand accelerates fastest and incumbent software stacks lag in multiplexed reporter quantification. Lead with SaaS-tiered pricing and API-first architectures that bypass legacy LIMS integration friction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed imaging software firms holding FDA-validated algorithm libraries but lacking instrument manufacturing scale. Five-to-ten year viability hinges on convergence with organ-on-chip and cell therapy quality control workflows rather than displacement by label-free alternatives. Watch for lattice light-sheet patent expirations as inflection signal for optical architecture commoditization.| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Stack Acquisition | Neural inference engines replace traditional image processing as primary value anchor in pharmaceutical accounts. |
| Fluorophore Backward Integration | Captive dye formulation neutralizes Chinese rare earth supply concentration and stabilizes input costs. |
| Organ-on-Chip Partnership | Microfluidic tissue model integration enables longitudinal toxicity readouts beyond static endpoint assays. |
| GMP Certification Investment | ISO 13485 compliance unlocks premium positioning in CAR-T and iPSC-derived therapeutic quality control. |
| India Application Support Expansion | CDSCO tightening of biosimilar filings creates first-mover advantage for validated platform vendors. |
Research Methodology
A spread of perspectives from pharmaceutical toxicology directors, academic core facility managers, biomedical imaging software engineers, and cell therapy manufacturing quality control leads converged on the working assumptions. Primary fieldwork combined structured interviews with instrument procurement officers at Max Planck Institutes and Fraunhofer centers alongside regulatory affairs specialists at EMA-notified bodies. Secondary validation drew from FDA 510(k) clearances for automated cell analysis devices, EMA ICH Q5D guideline documentation, and ISO 13485 certification registries. Bottom-up sizing of installed instrument bases triangulated against top-down pharmaceutical R&D spending allocations across the analysis window.
Demand-supply balance modeling anchored forecasts across product type, technology modality, end-user category, and application workflow dimensions. Segmentation incorporated environmental control chamber specifications, computational analysis throughput tiers, and regulatory validation burden levels. CAGRs derived from instrument replacement cycle analysis, biologics manufacturing capacity expansion pipelines, and AI-enabled assay adoption curves. Forecast inputs included pharmaceutical toxicology department phenotypic screening budgets and stem cell research grant funding trajectories.
Practitioners should monitor EMA Medical Device Regulation enforcement intensity, Chinese rare earth export licensing shifts, and FDA guidance on AI-enabled cell analysis algorithm validation for early signals. Forecasts reflect assumptions around continued pharmaceutical outsourcing to contract research organizations and sustained German research infrastructure investment. Material shifts in ICH Q5D documentation stringency or GPU semiconductor trade restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Europe Biobanks Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Austria Flow Cytometry Market
Biomedical Technology
Global Protein Crystallization Market
Biomedical Technology
Fluorescence in-Situ Hybridization Probe Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Global Biomarker Technologies Market
Biomedical Technology
Europe Proteomics Market
Biomedical Technology
Neuro Immunoassay Market
Biomedical Technology
Latin America Flow Cytometry Market
Biomedical Technology
Live Cell RNA Detection Market
Biomedical Technology
Global Biosimulation Market
Biomedical Technology
Cell Cycle Analysis Market
Biomedical Technology
America Cell Counting Market
Biomedical Technology
Global Primary Cell Culture Market
Biomedical Technology
BOD Incubator Market