
 High-End Cellomics Market | 2026-2036
High-End Cellomics Market Size, Share, and Industry Trends Forecast 2026-2036
High-End Cellomics Market Outlook
High-resolution image cytometry paired with AI-driven phenotype analysis is tilting the technology stack toward fully automated, closed-loop cellomics platforms. Thermo Fisher Scientific leverages its vertically integrated reagent-to-software portfolio to control pricing in high-content screening workflows. Danaher Corporation sustains competitive density across flow cytometry and cell manipulation through its Beckman Coulter and Molecular Devices operating companies. Bio-Rad Laboratories specializes in analytical-grade image cytometry instruments for academic core facilities.
High-end cellomics encompasses integrated hardware-software systems for quantitative, multiparametric cellular analysis at single-cell resolution, typically operating at submicron optical resolution with throughput exceeding 10,000 wells per day in 1536-format microplates. Its primary commercial purpose is to compress compound screening timelines in pharmaceutical pipelines while generating mechanistic toxicity and efficacy data prior to animal studies. Imaging systems and automated workstations capture the largest installed base, though high-content screening technology generates disproportionate margin pools due to recurring software licensing and assay development services. Contract research organizations represent the fastest-growing end-user category as pharma outsources target validation and lead optimization workflows.
The FDA enforces 21 CFR Part 11 electronic records integrity standards that shape instrument validation protocols for drug discovery customers, while the EPA's Good Laboratory Practice regulations extend to environmental toxicity screening applications. In Europe, the EMA's ICH Q5D guidelines on cell substrate qualification and the EU AI Act's risk classification for diagnostic algorithms are tightening documentation requirements for AI-integrated cellomics platforms. Stakeholders must monitor how evolving regulatory frameworks for AI-assisted biological interpretation reshape competitive requirements for software validation and audit trails.
Market Dynamics
AI-driven phenotype analysis is digitizing cell-based drug discovery workflows, compressing compound screening timelines from months to weeks while forcing instrument vendors to rearchitect software stacks for real-time biological interpretation.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records validation requirements for drug discovery workflows are mandating instrument upgrades across pharmaceutical R&D facilities.
- Contract research organizations:Pharma outsourcing of target validation and lead optimization workflows is expanding the addressable installed base for automated screening platforms.
- Single-cell resolution imaging:Submicron optical systems operating at 10,000+ wells per day are replacing lower-throughput legacy cytometry in toxicology pipelines.
Market Restraints
- Specialized optical components:Precision lens assemblies and sCMOS sensors concentrate supply among Japanese and German component specialists, creating input cost volatility.
- Assay development services:Recurring high-margin service revenue pools are captured by incumbent vendors with captive reagent portfolios, raising switching costs for new entrants.
- EU AI Act risk classification:Diagnostic algorithm documentation requirements are tightening compliance timelines for AI-integrated platform launches in European markets.
Strategic Opportunities
- Environmental toxicity screening:EPA Good Laboratory Practice regulations are extending cellomics applications beyond pharma into chemical safety assessment workflows.
- Academic core facilities:Analytical-grade image cytometry demand is rising in university research infrastructure funded by national biotechnology initiatives.
- Cloud-native software architectures:Remote instrument control and distributed data analysis are enabling subscription-based revenue models independent of hardware refresh cycles.
Industry Challenges
- Computational biology expertise:Shortage of personnel trained in both microscopy hardware and machine learning model deployment is constraining platform utilization rates.
- Legacy LIMS integration:Proprietary data formats from established vendors create friction when connecting new instruments to existing laboratory information management systems.
- Multi-site validation protocols:FDA audit trail requirements for distributed screening networks are extending deployment timelines for enterprise-scale installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-End Cellomics Market |
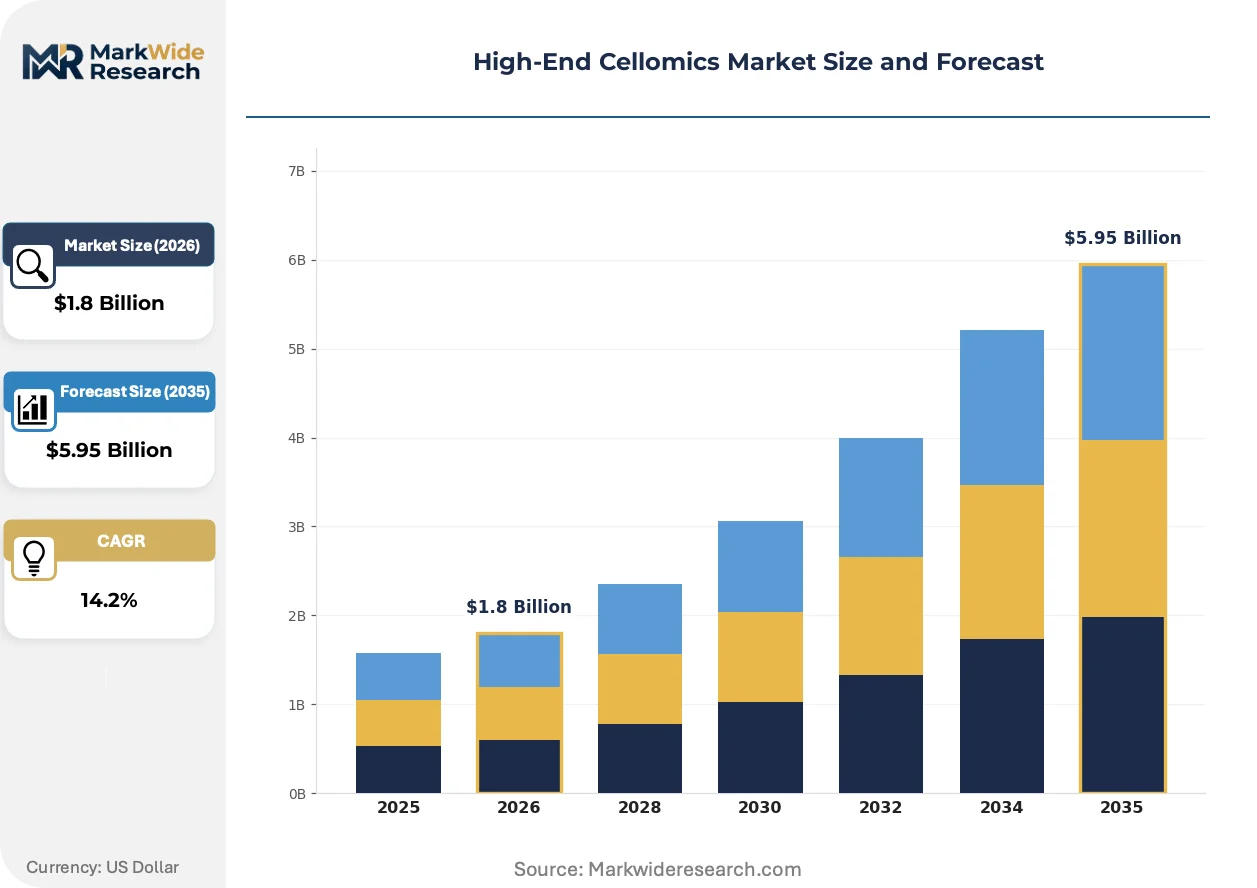
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Flow Cytometry, Cell Manipulation Tools, Automated Workstations Application: Drug Discovery, Diagnostic Applications, Personalized Medicine, Basic Research Technology: Confocal Microscopy, High-Content Screening, Image Cytometry, Bioinformatics End User: Pharmaceutical Companies, Academic Research Institutes, Biotech Firms, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher Corporation, Becton, Dickinson and Company, PerkinElmer Inc., Sartorius AG, Agilent Technologies Inc., Bio-Rad Laboratories, Yokogawa Electric Corporation, Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-End Cellomics Market Strategic Shifts
Closed-loop automation is redefining competitive requirements in cellomics, merging hardware control, image acquisition, and phenotypic inference into unified platforms that minimize human intervention across multi-day screening campaigns.
Confocal spinning-disk microscopy combined with GPU-accelerated deconvolution is digitizing subcellular structure quantification for high-content screening workflows. Mid-tier pharmaceutical discovery groups are adopting these systems at replacement-cycle pace, bypassing traditional widefield instruments. The technology is digitizing morphological endpoint collection, enabling direct comparison across compound libraries without batch staining variability.
EMA ICH Q5D guidelines on cell substrate qualification are tightening documentation requirements for master cell bank characterization in European biologics development. Manufacturers must now trace genetic stability across extended passage numbers with higher-resolution analytical evidence. Cellomics platform vendors serving contract development and manufacturing organizations are responding by embedding automated karyotyping modules into standard screening configurations.
Instrument-as-a-service contracting is displacing capital purchase models in mid-size biotech discovery operations. Leasing arrangements bundled with assay development support and predictive maintenance are capturing budget-constrained customers previously served by refurbished equipment brokers. This financing shift is most visible in United States coastal clusters where venture-funded startups prioritize operational expenditure flexibility over balance-sheet asset ownership.
High-End Cellomics Market Segmentation
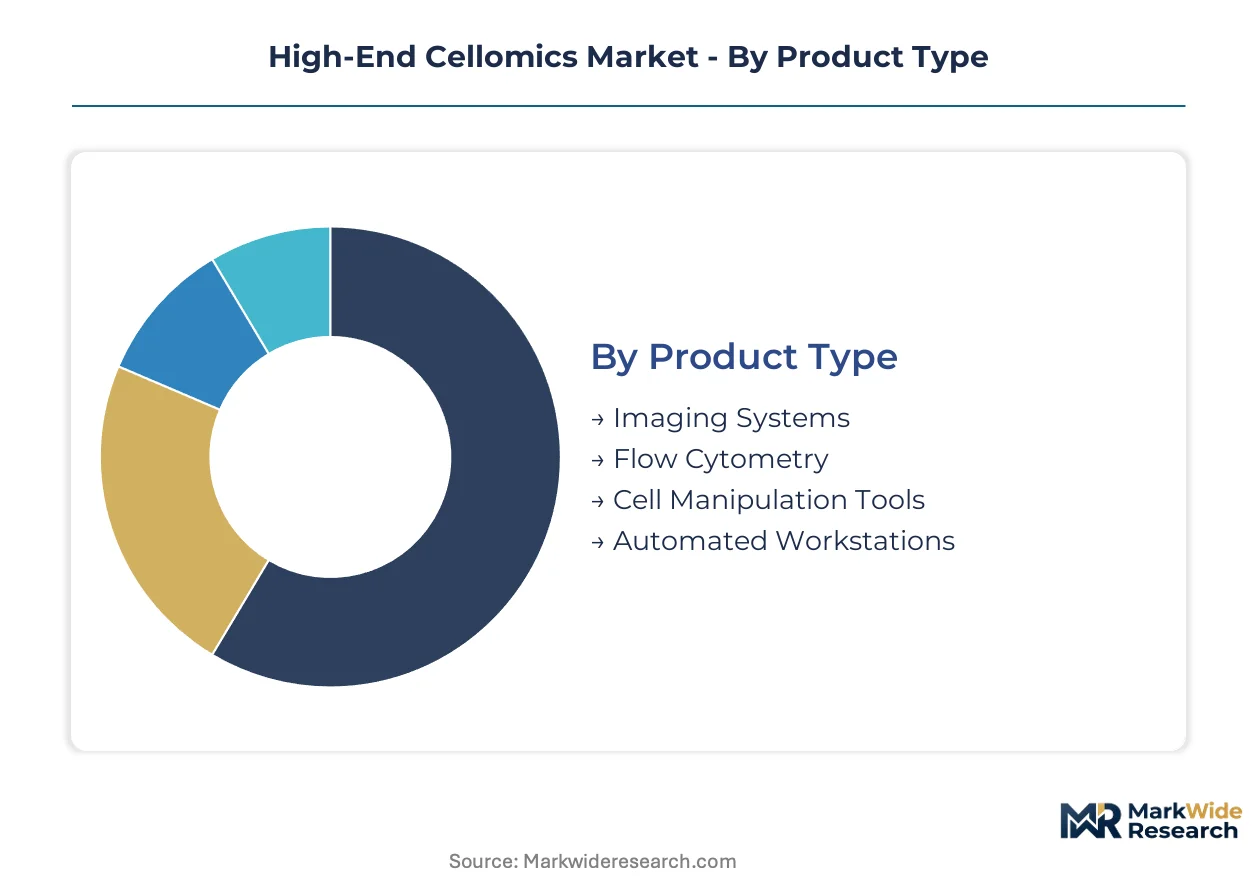
Segmentation in high-end cellomics reveals how hardware refresh cycles, software licensing models, and outsourcing patterns create divergent revenue streams across the value chain. Understanding these divisions illuminates where capital concentrates versus where recurring service revenue accumulates.
Product Type:
Imaging systems and automated workstations turn over on 5-7 year replacement cycles, while flow cytometry platforms and cell manipulation tools refresh more slowly at 8-10 year intervals.
- Imaging Systems:Confocal spinning-disk and widefield microscopes with submicron optical resolution dominate pharmaceutical screening facilities. Boston and San Diego biotech clusters drive procurement of these platforms for high-throughput compound libraries.
- Automated Workstations:Integrated liquid handling and plate management systems operating at 10,000+ wells per day compress screening timelines from months to weeks. Contract research organizations represent the fastest-expanding customer base as pharma outsources target validation workflows.
- Flow Cytometry:Analytical-grade cell sorting instruments for immunophenotyping and rare cell detection.
- Cell Manipulation Tools:Micromanipulators and microinjection systems for single-cell isolation and CRISPR editing workflows.
Imaging systems anchor the volume base while automated workstations gain share at the steepest rate.
Application:
Cost tier separation is pronounced: drug discovery commands premium pricing for validated screening protocols, while basic research operates on constrained capital budgets with extended procurement cycles.
- Drug Discovery:Compound screening and lead optimization workflows requiring FDA 21 CFR Part 11 electronic records validation. Pharmaceutical companies in the United States concentrate demand for mechanistic toxicity data prior to animal studies.
- Basic Research:Academic core facilities funded by national biotechnology initiatives purchase analytical-grade instruments. University infrastructure grants in the United States prioritize image cytometry for cell biology departments.
- Diagnostic Applications:Clinical-grade cellomics for hematology and oncology biomarker detection.
- Personalized Medicine:Patient-derived cell models for precision therapy selection and companion diagnostic development.
Drug discovery commands the largest revenue pool while personalized medicine climbs the fastest as cell therapy pipelines mature.
Technology:
Margin concentration varies sharply: high-content screening generates disproportionate software licensing and assay development services revenue, while bioinformatics operates on lower-margin service contracts.
- High-Content Screening:Multi-parametric cellular analysis platforms integrating hardware control with AI-driven phenotype analysis. The FDA's 21 CFR Part 11 requirements tighten compliance standards for electronic records in these workflows.
- Confocal Microscopy:Spinning-disk systems with GPU-accelerated deconvolution digitize subcellular structure quantification. Mid-tier pharmaceutical groups adopt these at replacement-cycle pace, bypassing legacy widefield instruments.
- Image Cytometry:Quantitative single-cell analysis for academic core facilities and biotech discovery groups.
- Bioinformatics:Cloud-native data analysis and machine learning model deployment for distributed screening networks.
High-content screening dominates margin capture while bioinformatics expands most quickly through subscription-based remote access models.
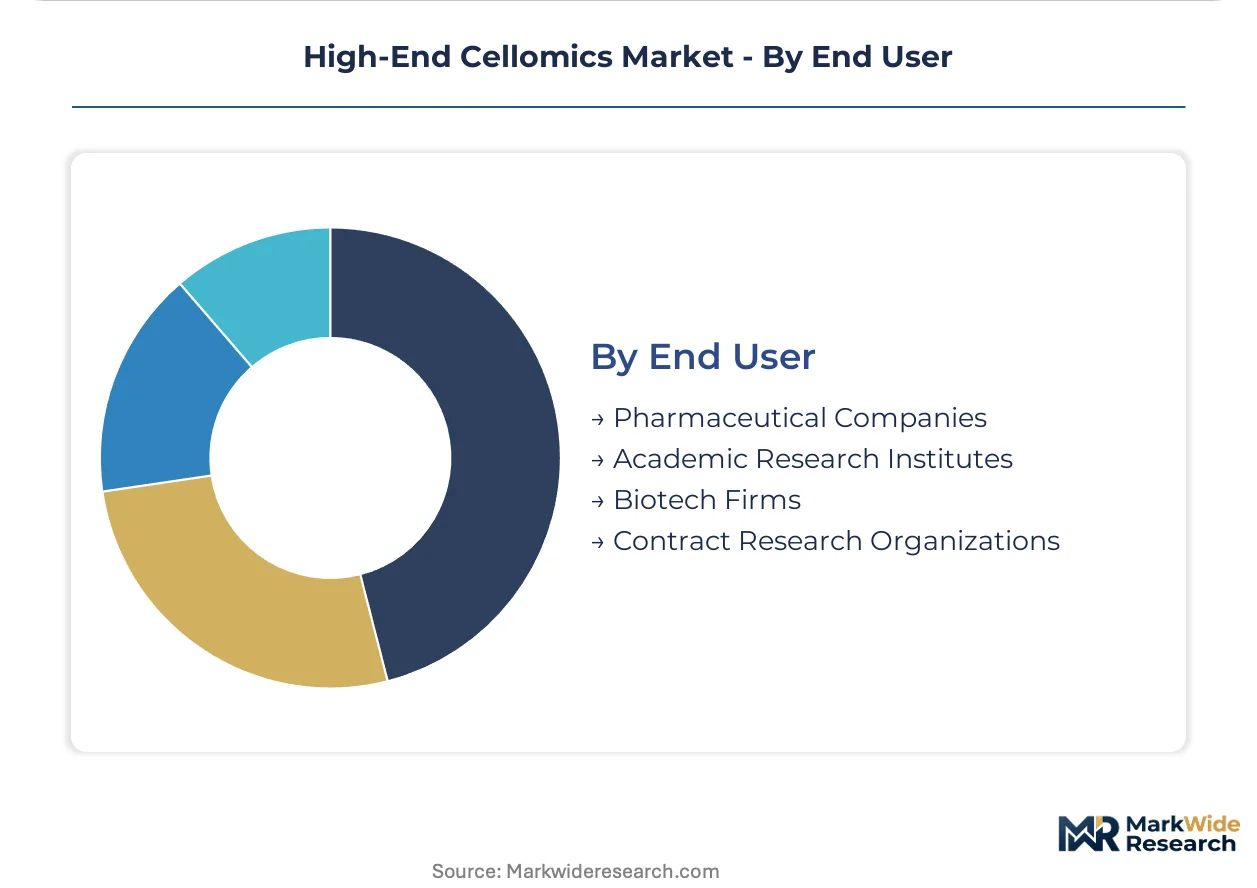
End User:
Customer type determines contract structure: pharmaceutical companies purchase through capital budgets with multi-year service agreements, while biotech firms increasingly favor instrument-as-a-service leasing for operational expenditure flexibility.
- Pharmaceutical Companies:Enterprise-scale installations across distributed screening networks requiring FDA audit trail validation. Multi-site deployment protocols extend timelines but secure long-term captive revenue for incumbent vendors.
- Contract Research Organizations:Outsourced target validation and lead optimization workflows expand the addressable installed base for automated platforms. CROs in the United States coastal clusters prioritize throughput density to serve multiple pharma clients simultaneously.
- Academic Research Institutes:National biotechnology initiative funding drives analytical-grade image cytometry procurement for university core facilities.
- Biotech Firms:Venture-funded startups favor leasing arrangements bundled with assay development support over balance-sheet asset ownership.
Pharmaceutical companies anchor the installed base while contract research organizations capture the steepest expansion trajectory as outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese precision optical component specialists export lens assemblies and sCMOS sensors to United States pharmaceutical screening facilities, creating a transatlantic supply corridor for high-resolution cellomics hardware.
United States
Boston and San Diego biotech clusters drive procurement of automated high-content screening platforms for mechanistic toxicity workflows. FDA 21 CFR Part 11 electronic records validation requirements mandate instrument upgrades across pharmaceutical R&D facilities. Massachusetts and California coastal markets concentrate venture-funded startup demand for instrument-as-a-service leasing arrangements.
Germany
Precision optical component manufacturing anchors supply-side capacity for submicron lens assemblies used in confocal spinning-disk systems. EMA ICH Q5D guidelines on cell substrate qualification tighten documentation requirements for master cell bank characterization. Baden-Württemberg and Bavaria host specialized component fabricators serving global instrument OEMs.
Japan
sCMOS sensor and precision motion control specialists supply critical inputs for high-throughput automated workstations. METI industrial technology programs fund next-generation image cytometry development for pharmaceutical applications. Tokyo-Osaka corridor concentrates electronics component manufacturing for export to North American and European markets.
Switzerland
Contract development and manufacturing organizations expand automated karyotyping module adoption for biologics cell line qualification. Swissmedic biologics licensing requirements align with EMA genetic stability documentation standards. Basel-Zurich biotech corridor drives demand for integrated hardware-software cellomics platforms.
China
National biotechnology initiative funding expands academic core facility procurement of analytical-grade image cytometry instruments. NMPA pharmaceutical registration reform accelerates adoption of automated screening platforms for domestic drug discovery. Shanghai and Beijing research institutes prioritize high-content screening technology for compound library evaluation.
High-End Cellomics Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated life science conglomerates with captive reagent portfolios and multi-decade installed base relationships. Tiered competitive structure separates full-stack platform vendors from specialized component suppliers and regional service integrators. Strategic archetypes include reagent-to-software integrators, precision optical specialists, and cloud-native analytics providers. Dominant competitive moves encompass backward integration into consumables manufacturing and geographic expansion through distributor partnerships in Asia-Pacific markets.
Among United States-based conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify the vertically integrated archetype controlling pricing across high-content screening workflows. Yokogawa Electric Corporation represents Japanese precision engineering capabilities in optical subsystem supply. These three anchors illustrate how market position depends on portfolio breadth spanning hardware instrumentation, consumables, and software licensing revenue streams.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Becton, Dickinson and Company |
| PerkinElmer Inc. |
| Sartorius AG |
| Agilent Technologies Inc. |
| Bio-Rad Laboratories |
| Yokogawa Electric Corporation |
| Bruker Corporation |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in precision optical component manufacturing across Japan and Germany is forcing instrument OEMs to accept extended lead times and volume commitments, compressing margins for mid-tier cellomics platform vendors while amplifying pricing power for vertically integrated conglomerates with captive supply arrangements.
Pricing Analysis
Current-generation confocal spinning-disk systems command a 40-60% premium over prior-generation widefield instruments, while next-generation AI-integrated platforms with automated phenotype inference are priced at subscription-SaaS tiers bundling hardware, software licensing, and assay development services. Price differentiation rests on FDA 21 CFR Part 11 validation certification and captive reagent portfolio depth. Cost compression in mid-tier analytical-grade instruments is intensifying because contract research organizations prioritize throughput density over optical performance. Academic core facilities funded by national biotechnology initiatives exhibit highest price sensitivity, while pharmaceutical companies in Boston and San Diego clusters demonstrate lowest sensitivity due to compressed compound screening timeline requirements.
Supply Chain Analysis
Supplier-financing facilities extended by German and Japanese precision optical specialists are becoming standard terms for United States-based instrument OEMs purchasing submicron lens assemblies and sCMOS sensors. Manufacturing capacity concentrates in Baden-Württemberg and Bavaria for precision optics, Tokyo-Osaka corridor for sensor and motion control electronics, and Massachusetts and California for final system integration and software development. Critical inputs include precision lens assemblies, sCMOS sensors, and automated liquid handling modules. Single-source vulnerability in sCMOS sensor supply creates structural risk given concentration among Japanese component specialists. Distribution runs through direct enterprise sales teams for pharmaceutical customers and distributor partnerships serving academic core facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The talent pipeline bridging microscopy hardware engineering and machine learning model deployment is constraining platform utilization rates across customer segments, creating asymmetric returns for vendors who solve this capability-scarcity gap through training programs or acquisition of computational biology specialists.
For Market Incumbents: Entrench market position by embedding automated karyotyping modules into standard screening configurations to capture EMA ICH Q5D-driven demand from contract development and manufacturing organizations, and by extending assay development service revenue through backward integration into consumables manufacturing. Cloud-native software architectures from emerging analytics providers threaten recurring licensing revenue streams; defend by accelerating subscription-based remote access model deployment ahead of hardware refresh cycles. For New Entrants and Emerging Players: China's national biotechnology initiative funding for academic core facilities represents the most penetrable geography, with analytical-grade image cytometry procurement running ahead of domestic vendor supply capacity. Target university research infrastructure grants in Shanghai and Beijing with instrument-as-a-service leasing bundled with computational biology training. Bypass entrenched pharmaceutical relationships by serving biotech firm demand for operational expenditure flexibility over capital purchase models. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with captive reagent portfolios and multi-decade installed base relationships in pharmaceutical screening facilities. Long-term viability across the analysis window favors full-stack platform vendors over specialized component suppliers given consolidation pressure from vertically integrated life science conglomerates. Watch FDA audit trail requirement tightening for distributed screening networks as the inflection signal for enterprise-scale installation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Assay Development Service Expansion | Captures high-margin recurring revenue from pharmaceutical outsourcing of lead optimization workflows. |
| Cloud-Native Software Architecture Migration | Enables subscription-based revenue models decoupled from hardware replacement cycles for biotech customers. |
| Automated Karyotyping Module Integration | Addresses EMA ICH Q5D genetic stability documentation requirements for European biologics development. |
| Instrument-as-a-Service Leasing Programs | Captures venture-funded startup demand in Boston and San Diego coastal clusters prioritizing OpEx flexibility. |
| Computational Biology Training Program Development | Alleviates personnel shortage constraining platform utilization rates across customer segments. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, biomedical engineers at academic core facilities, and GPO contracts managers; and secondary validation through FDA 21 CFR Part 11 guidance documents, EMA ICH Q5D guidelines, SEC 10-K filings from publicly traded life science conglomerates, and national biotechnology initiative funding disclosures. Bottom-up and top-down triangulation cross-validated segment-level demand estimates against aggregate pharmaceutical R&D expenditure patterns.
Forecast inputs considered product type replacement cycles, software licensing model transitions, and outsourcing pattern acceleration across the analysis window. Segmentation dimensions modeled include hardware instrumentation versus consumables and services, drug discovery versus basic research versus diagnostic applications, high-content screening versus confocal microscopy versus image cytometry technologies, and pharmaceutical company versus contract research organization versus academic institute end users. CAGRs were derived from installed base growth projections weighted by average selling price evolution and recurring revenue attachment rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native analytics providers or precision optical component specialists integrating downstream into full platforms would shift outcomes. Macroeconomic contraction in venture funding for biotech startups, regulatory delay in AI-assisted diagnostic algorithm frameworks, or technological breakthrough in label-free imaging modalities would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Bacteriophage Market
Biomedical Technology
Orthobiological Products Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
Global RNA-Interference (Rnai) Market
Biomedical Technology
Single Cell Multiomics Market
Biomedical Technology
Austria Flow Cytometry Market
Biomedical Technology
Tissue Clearing Market
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
Southern Blotting Market
Biomedical Technology
Global Serological Transplant Diagnostics Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Middle East and Africa Exosome Research Products Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
Human Reproductive Technologies Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market