
 Global Protein Crystallization and Crystallography Market | 2026-2036
Global Protein Crystallization and Crystallography Market Size, Share, and Industry Trends Forecast 2026-2036
Global Protein Crystallization and Crystallography Market Foresight
The capability gap between automated crystallization platform builders and manual kit suppliers is collapsing as software-defined workflows commoditize mid-range instrumentation. Bruker Corporation sustains its position through R&D intensity in high-brilliance X-ray sources. Rigaku Corporation leverages its geographic dominance across Asian academic consortia. Hampton Research specializes in consumables chemistry that anchors recurring revenue streams.
Protein crystallization and crystallography encompasses the production of ordered protein crystals and their analysis via diffraction methods to resolve three-dimensional atomic structures at resolutions typically below 2.5 angstroms. The field serves as the primary experimental route for structure-guided drug design, enabling rational optimization of small-molecule binding affinity. X-ray diffractometers occupy the mature revenue core where replacement cycles and detector upgrades sustain margin pools. Cryo-electron microscopy is displacing traditional crystallography for membrane protein targets, fastest-growing among structural biology modalities. Automation platforms concentrate demand from pharmaceutical companies seeking throughput gains in fragment-based screening campaigns.
FDA structural chemistry requirements for biologic approval shape demand for validated crystallographic data packages among drug discovery end users. EPA and REACH frameworks govern solvent handling in crystallization facilities, driving automation adoption to reduce hazardous reagent exposure. ISO 17025 accreditation standards for analytical laboratories filter market access for instrument vendors. Stakeholders must monitor how neutron crystallography investments at national facilities in the United States, United Kingdom, and Japan reshape regional service capabilities.
Market Dynamics
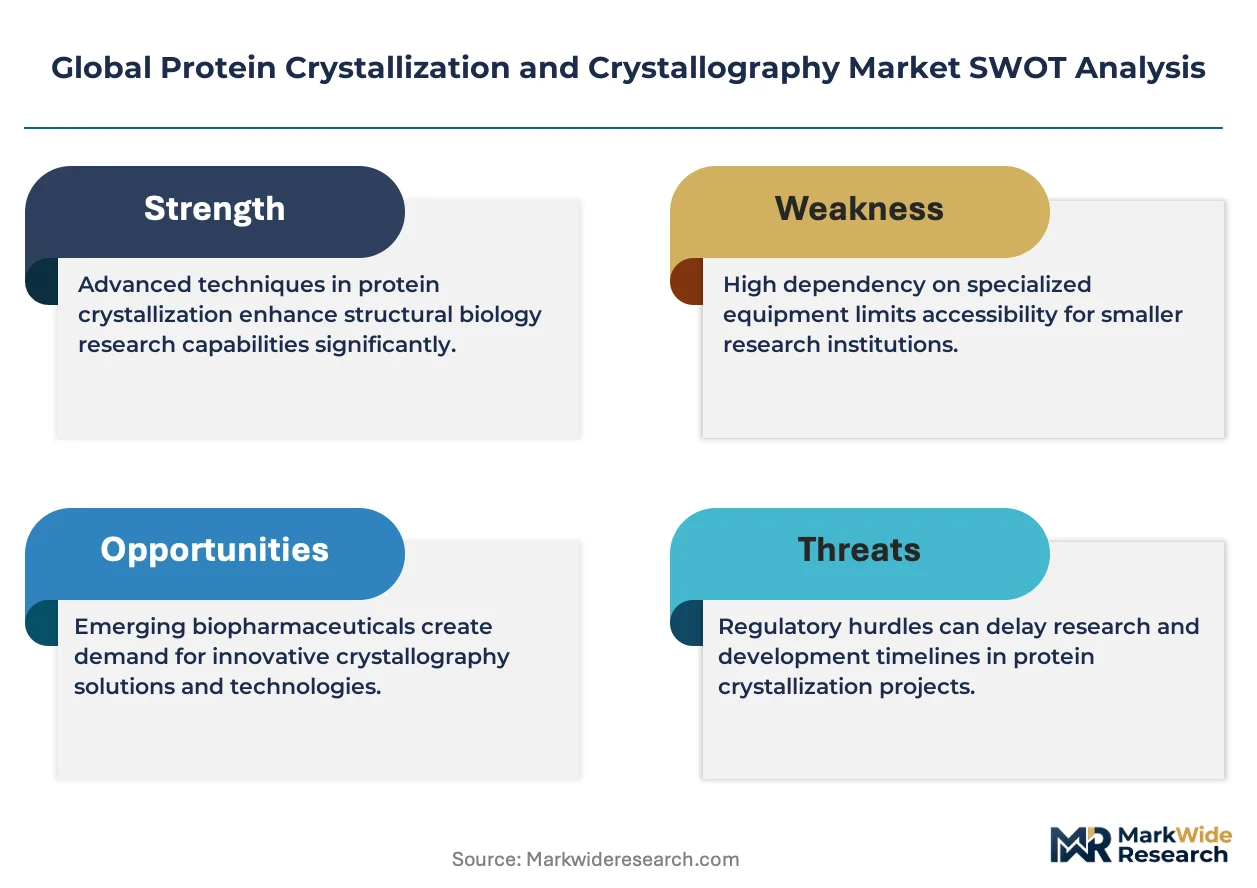
Cryo-electron microscopy technology is compressing the addressable market for traditional X-ray crystallography while simultaneously expanding structural biology's total serviceable base through previously intractable membrane protein targets.
Growth Catalysts
- FDA structural chemistry mandates:Biologic approval pathways now require validated crystallographic data packages, forcing pharmaceutical companies to maintain internal crystallography capabilities or secure contracted services.
- Fragment-based screening throughput demands:Automation platforms enable pharmaceutical fragment libraries to be processed at scales manual workflows cannot match, concentrating equipment procurement among large-cap drug developers.
- Japan's national synchrotron investments:SPring-8 and Photon Factory upgrades anchor regional research ecosystems, sustaining detector replacement cycles and beamline instrumentation demand.
Market Restraints
- Helium supply concentration:Cryogenic cooling systems for X-ray detectors and sample preparation depend on helium sourcing concentrated in Qatar, Algeria, and Russia, exposing operations to geopolitical supply shocks.
- Cryo-EM capital intensity:Single-particle cryo-electron microscopes require facility investments exceeding traditional crystallography suites by an order of magnitude, freezing out mid-tier academic institutions.
- REACH solvent governance:European crystallization facilities face escalating compliance costs for handling hazardous precipitants and cryoprotectants, compressing margin pools for manual kit suppliers.
Strategic Opportunities
- India's structural biology infrastructure gap:National laboratories and emerging biotech clusters in Bangalore and Hyderabad lack integrated crystallization-to-beamline workflows, creating service and equipment whitespace.
- AI-driven structure prediction convergence:DeepMind's AlphaFold outputs are driving demand for experimental validation services, positioning crystallography as a confirmation layer rather than a discovery engine.
- Cloud-based diffraction data analysis:Remote processing pipelines enable smaller institutions to access high-performance computing without local infrastructure, opening subscription revenue models for software vendors.
Industry Challenges
- Crystallographer talent scarcity:Academic training programs have not kept pace with industry demand for specialists who bridge hardware operation, software pipelines, and structural interpretation.
- ISO 17025 accreditation timelines:Analytical laboratories face 12-18 month certification cycles for crystallographic services, delaying contract research market entry and revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Protein Crystallization and Crystallography Market |
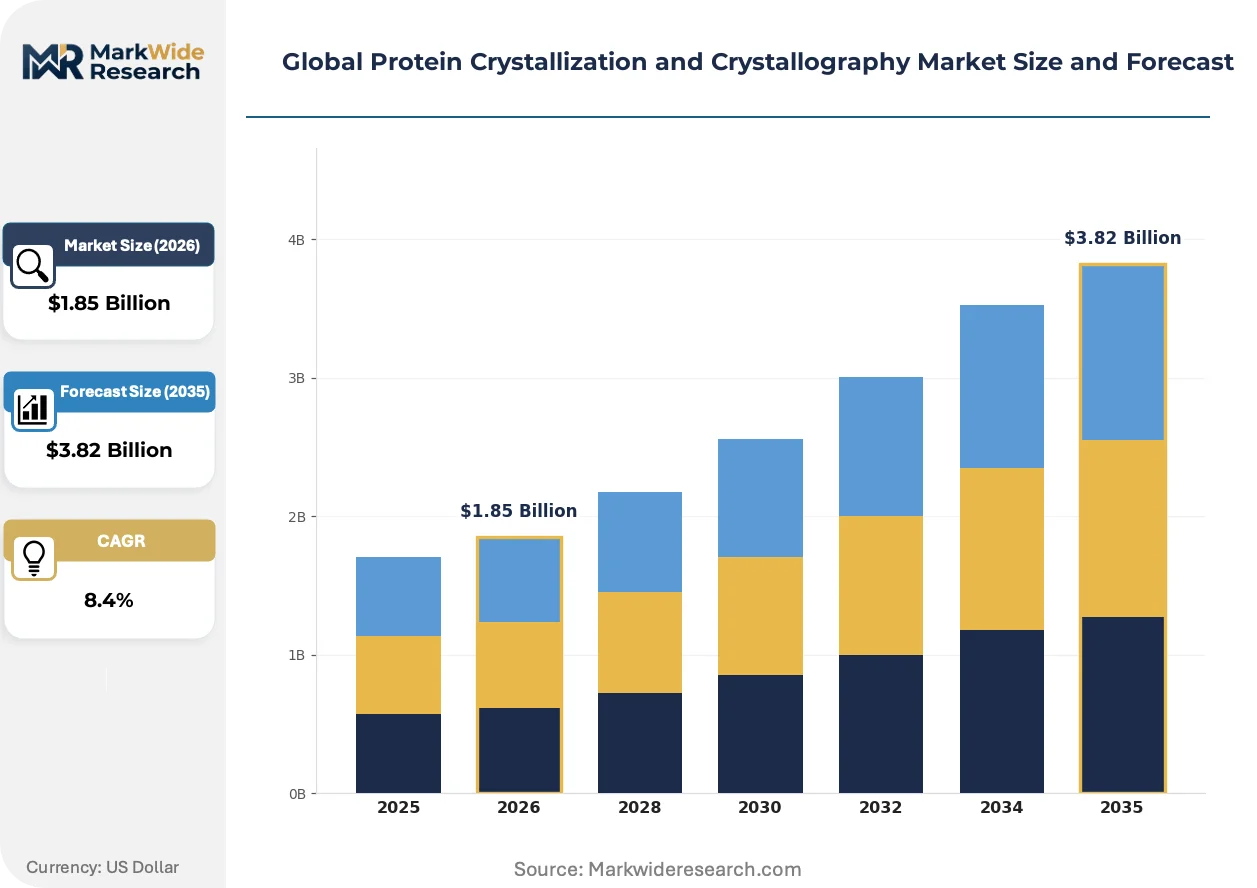
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
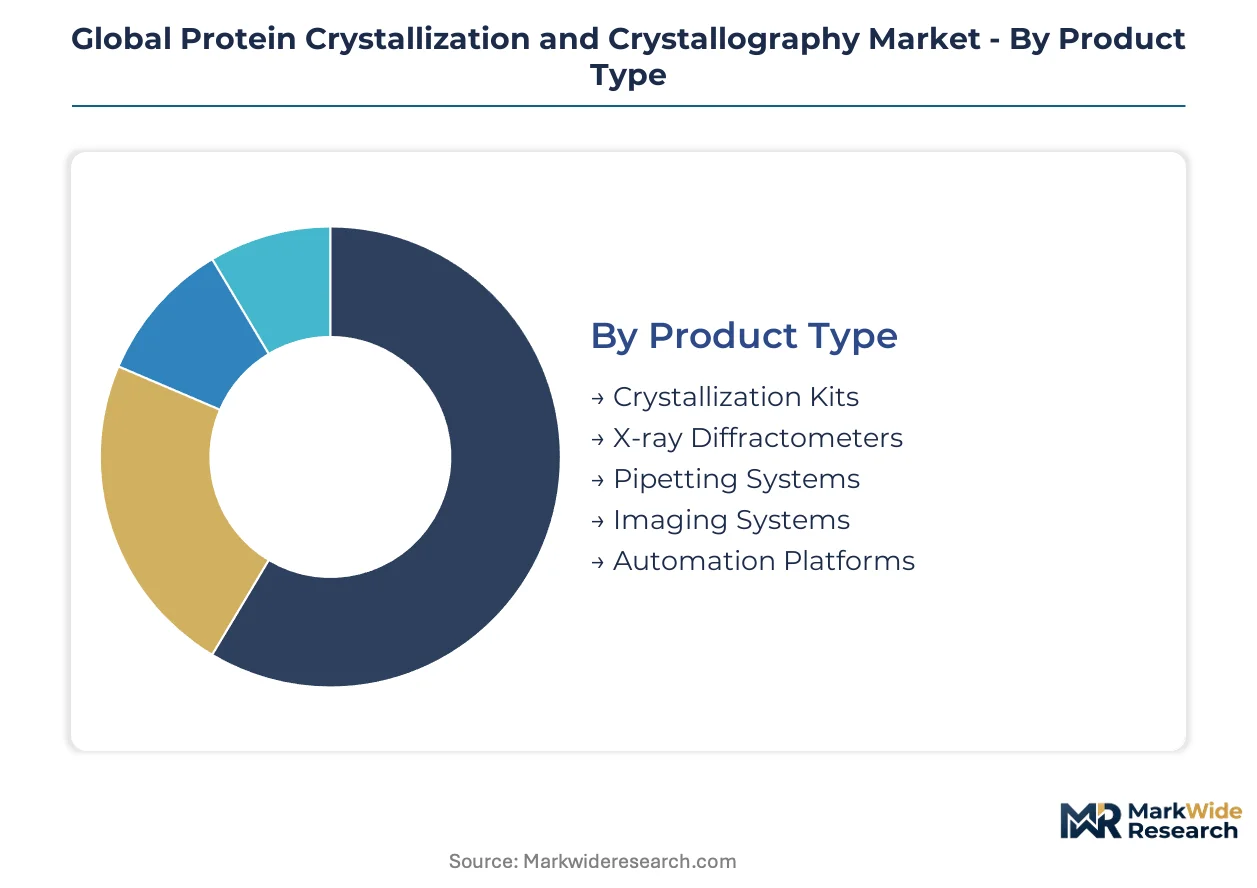
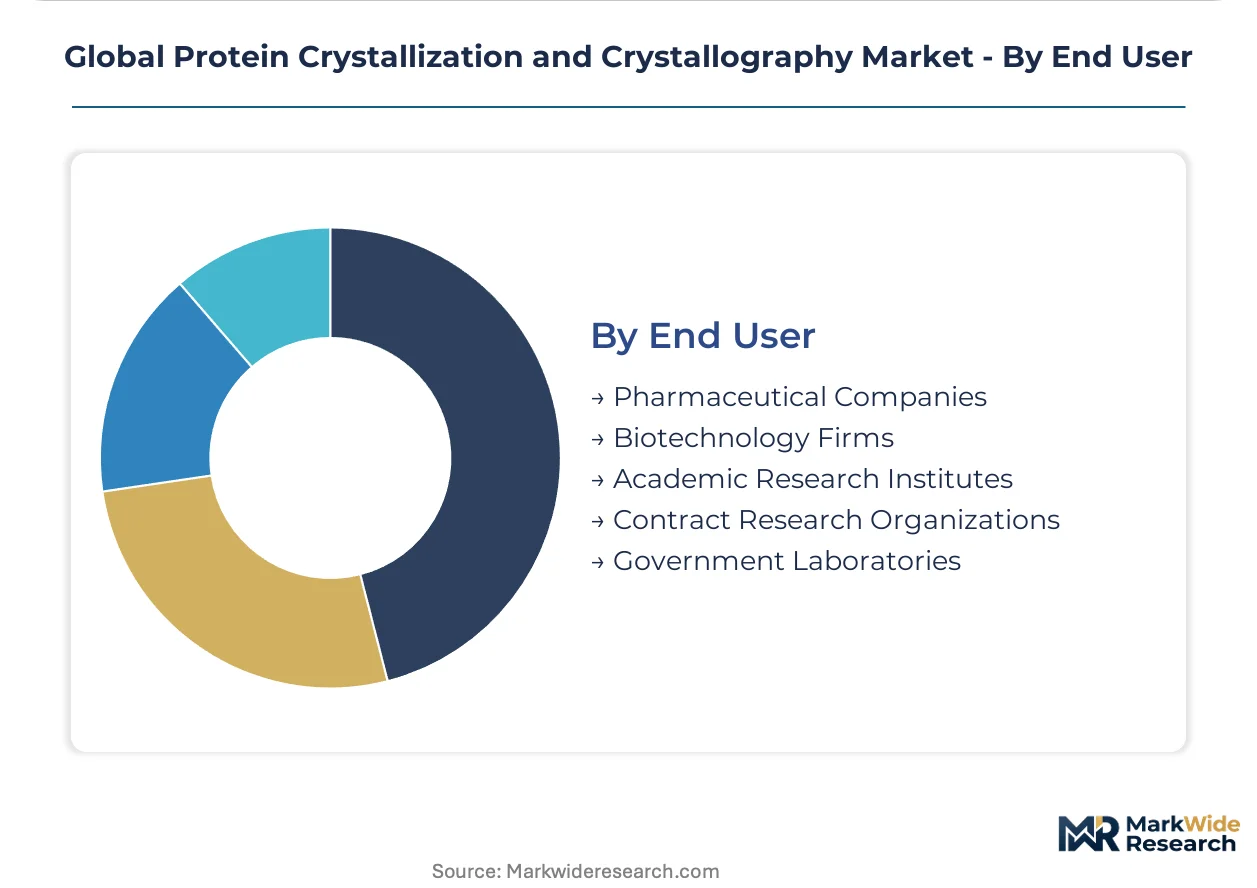
| Segmentation | Product Type: Crystallization Kits, X-ray Diffractometers, Pipetting Systems, Imaging Systems, Automation Platforms Technology: X-ray Crystallography, Cryo-Electron Microscopy, Neutron Crystallography, NMR Spectroscopy, Electron Diffraction Application: Drug Discovery, Enzyme Engineering, Structural Biology, Vaccine Development, Agrochemical Research End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research Institutes, Contract Research Organizations, Government Laboratories |
| Companies Covered | Rigaku Corporation, Bruker Corporation, Hampton Research, Jena Bioscience GmbH, Formulatrix, Molecular Dimensions, MiTeGen, QIAGEN, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Protein Crystallization and Crystallography Market Shifts & Advancements
Software-defined workflows and detector hardware advances are compressing the capability gap between elite national facilities and mid-tier research institutions, redistributing competitive advantage toward integrated platform vendors.
Microfluidic crystallization chips are miniaturizing sample consumption from microliter to nanoliter scales while preserving diffraction quality. Contract research organizations serving pharmaceutical clients have adopted these chips to reduce precious protein consumption during high-throughput screening campaigns. The technology is miniaturizing the economic threshold for crystallization trials, enabling academic laboratories with limited protein expression capacity to pursue targets previously reserved for well-capitalized industrial programs.
REACH authorization requirements for hazardous crystallization reagents are forcing European facilities to automate solvent handling and waste management. The regulation accelerates capital expenditure cycles for automation platforms while disadvantaging manual kit suppliers dependent on open-bench workflows. German and Swiss contract research organizations have responded by consolidating crystallization operations into centralized automated facilities rather than distributed benchtop setups.
Pharmaceutical procurement departments now unbundle instrument purchases from service contracts and consumables supply, compressing vendor pricing power across the equipment lifecycle. Large-cap drug developers in the United States negotiate multi-year reagent supply agreements independent of hardware vendors, eroding the recurring revenue moats that historically protected crystallization consumables specialists. This pattern is most visible among Boston and San Francisco biotech clusters where procurement centralization has advanced furthest.
Global Protein Crystallization and Crystallography Market Segmentation
Segmentation reveals how regulatory requirements, technology substitution patterns, and procurement centralization reshape vendor positioning across distinct customer workflows and compliance environments.
Product Type:
FDA structural chemistry mandates for biologic approvals create divergent compliance burdens across hardware categories, with validated automation platforms commanding premium positioning against basic consumables.
- Crystallization Kits:Manual screening reagents and sparse matrix formulations remain the entry point for academic laboratories with limited capital budgets. REACH solvent governance in Europe compresses margins as facilities automate hazardous reagent handling, favoring kit suppliers with integrated safety documentation over commodity chemical vendors.
- X-ray Diffractometers:High-brilliance X-ray sources with photon-counting detectors anchor revenue pools at national synchrotron facilities and pharmaceutical structural biology departments. Detector replacement cycles at Japan's SPring-8 and the United States' Advanced Photon Source sustain demand for incremental hardware upgrades even as cryo-EM displaces some protein crystallography workflows.
- Pipetting Systems:Liquid handling robotics for crystallization trial preparation concentrate procurement among high-throughput pharmaceutical fragment screening programs.
- Imaging Systems:UV-visible and crossed-polarized light microscopes for crystal detection serve distributed academic installations with limited automation requirements.
- Automation Platforms:Integrated crystallization-to-imaging workflows enable pharmaceutical companies to meet FDA validation standards for biologic structural data packages.
Established volume favors X-ray Diffractometers; emerging adoption favors Automation Platforms.
Technology:
Cost tier differentiation separates capital-intensive modalities requiring facility-scale infrastructure from benchtop methods accessible to mid-tier institutions.
- X-ray Crystallography:Mature diffraction methods using synchrotron or laboratory X-ray sources deliver atomic resolution below 2.5 angstroms for soluble protein targets. Beamline investments at Germany's DESY and Switzerland's SLS sustain regional service ecosystems, though helium supply concentration for cryogenic cooling creates operational vulnerability.
- Cryo-Electron Microscopy:Single-particle cryo-EM resolves membrane protein structures previously intractable to crystallization, expanding structural biology's total addressable target space. Capital requirements exceeding traditional crystallography suites by an order of magnitude restrict installation to well-funded pharmaceutical headquarters and elite national facilities in the United States, United Kingdom, and Japan.
- Neutron Crystallography:Complementary scattering methods for hydrogen atom visualization concentrate at government-funded facilities with limited commercial access.
- NMR Spectroscopy:Solution-state structural analysis serves smaller proteins and dynamic conformational studies in academic medicinal chemistry programs.
- Electron Diffraction:Microcrystal diffraction methods for nanoscale samples gain traction for natural product and peptide targets in specialized academic laboratories.
Revenue concentration sits with X-ray Crystallography; steepest expansion trajectory belongs to Cryo-Electron Microscopy.
Application:
Customer type determines throughput requirements and validation standards, with pharmaceutical procurement centralization favoring integrated platform vendors over point solutions.
- Drug Discovery:Structure-guided design campaigns for small-molecule and biologic candidates drive demand for validated crystallographic data packages. Fragment-based screening throughput requirements concentrate automation procurement among large-cap drug developers in Boston and San Francisco clusters.
- Structural Biology:Fundamental research programs at academic institutes and national laboratories generate methodological innovation and trained specialist pipelines. AlphaFold validation services are repositioning experimental crystallography as a confirmation layer rather than primary discovery engine.
- Enzyme Engineering:Industrial biocatalysis programs leverage crystallographic data for active site redesign in pharmaceutical and agrochemical manufacturing.
- Vaccine Development:Antigen structure determination supports immunogen design for emerging infectious disease targets.
- Agrochemical Research:Crop protection chemistry programs apply structural biology for herbicide and fungicide target validation.
Procurement scale favors Drug Discovery; methodological innovation favors Structural Biology.
End User:
Geography and institutional scale determine access to national synchrotron facilities and capital for facility-scale instrumentation.
- Pharmaceutical Companies:Internal structural biology capabilities satisfy FDA biologic approval requirements while supporting fragment-based screening at industrial scale. Procurement departments unbundle instrument purchases from service contracts, compressing vendor pricing power across the equipment lifecycle.
- Academic Research Institutes:Distributed installations at universities depend on remote synchrotron access and cloud-based data processing to compensate for limited local infrastructure. Microfluidic crystallization chips are miniaturizing economic thresholds for crystallization trials.
- Biotechnology Firms:Emerging drug developers in Bangalore and Hyderabad lack integrated crystallization-to-beamline workflows, creating service whitespace for contract research providers.
- Contract Research Organizations:Centralized automated facilities in Germany and Switzerland consolidate distributed European operations to manage REACH compliance costs.
- Government Laboratories:National synchrotron and neutron facilities anchor regional research ecosystems and sustain detector replacement demand.
Equipment revenue concentrates in Pharmaceutical Companies; service expansion concentrates in Contract Research Organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor instrument manufacturers in Japan and Germany while consumables chemistry flows from specialized suppliers in the United States and Switzerland. National synchrotron facility investments anchor regional research ecosystems and sustain detector replacement demand across mature markets.
United States
FDA structural chemistry mandates for biologic approvals drive pharmaceutical procurement of validated automation platforms. The EPA governs hazardous solvent handling in crystallization facilities, accelerating automation adoption. Boston and San Francisco biotech clusters concentrate fragment-based screening demand among large-cap drug developers.
Germany
DESY and European XFEL beamline investments sustain regional detector upgrade cycles and instrumentation demand. REACH authorization requirements for crystallization reagents force facilities to automate solvent handling and waste management. Swiss and German contract research organizations consolidate operations into centralized automated facilities.
Japan
SPring-8 and Photon Factory upgrades anchor the regional research ecosystem and sustain beamline instrumentation procurement. METI coordinates national synchrotron investments that concentrate structural biology capability. Tokyo and Osaka academic consortia drive liquid handling robotics demand for high-throughput crystallization screening.
India
National laboratories and emerging biotech clusters in Bangalore and Hyderabad lack integrated crystallization-to-beamline workflows, creating service whitespace. CDSCO biologic approval pathways are evolving toward structural data requirements. The PLI scheme for pharmaceuticals incentivizes domestic structural biology infrastructure buildout.
United Kingdom
Diamond Light Source operations sustain detector replacement demand and regional service capabilities. Neutron crystallography investments at ISIS Neutron and Muon Source reshape complementary scattering access. Cambridge and Oxford structural biology programs generate specialist talent pipelines for contract research providers.
Global Protein Crystallization and Crystallography Market Competitive Landscape
Concentration sits with diversified analytical instrument manufacturers and specialized consumables chemistry suppliers. The vendor base spans three tiers: integrated platform builders, point-solution instrument makers, and reagent kit specialists. Strategic archetypes include synchrotron-anchored detector suppliers, pharmaceutical automation integrators, and recurring-revenue consumables providers. Competitive moves center on unbundling procurement negotiations and consolidating European operations to manage REACH compliance costs.
Within the diversified instrument tier, Rigaku Corporation and Bruker Corporation exemplify scale-driven positioning across X-ray source and detector portfolios. Hampton Research occupies a specialist position in consumables chemistry that anchors recurring revenue streams. These three entities represent the spectrum from capital-intensive hardware platforms to reagent-driven business models.
| Leading Market Players |
|---|
| Rigaku Corporation |
| Bruker Corporation |
| Hampton Research |
| Jena Bioscience GmbH |
| Formulatrix |
| Molecular Dimensions |
| MiTeGen |
| QIAGEN |
| Agilent Technologies |
| Others |
Supply & Pricing Matrix
Ninety-day lead times for photon-counting X-ray detectors from Japan concentrate pricing power among synchrotron-anchored suppliers while compressing margins for distributors holding safety stock. This inventory dynamic reinforces the premium commanded by vendors with captive production of high-brilliance sources, particularly as pharmaceutical procurement departments unbundle hardware from service contracts.
Pricing Analysis
Configured-to-order pricing for validated automation platforms commands spreads exceeding standard crystallization kits by factors tied to FDA compliance documentation and ISO 17025 certification tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by detector resolution and software integration depth, with pharmaceutical companies showing lowest price sensitivity due to biologic approval mandates. Cost compression in manual reagent kits intensifies because REACH compliance adds documentation overhead that commodity chemical vendors cannot absorb. Academic laboratories represent the most price-sensitive segment, driving demand for microfluidic chips that reduce per-trial protein consumption.
Supply Chain Analysis
Port congestion at Yokohama and Hamburg elevates inbound logistics costs for helium-dependent cryogenic cooling systems sourced from Qatar and Algeria. Detector manufacturing concentrates in Japan, Germany, and the United States, with sapphire sensor substrates and specialized scintillator crystals drawing from limited qualified suppliers. Single-source vulnerability sits with Qatar's helium concentration for cryogenic sample preparation. Distribution runs through national synchrotron facility procurement offices and pharmaceutical central purchasing departments, bypassing traditional laboratory supply distributors for high-value instrumentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Detector replacement cycles at aging synchrotron facilities signal cyclical recovery as beamline upgrades accelerate through national science budgets in Japan, Germany, and the United States.
For Market Incumbents: Consolidate European crystallization operations into centralized automated facilities to absorb REACH compliance costs that manual kit suppliers cannot shoulder. Deepen backward integration into high-brilliance X-ray source manufacturing to defend margin pools against unbundling procurement patterns at large-cap pharmaceutical developers. Cryo-EM displacement of traditional crystallography for membrane protein targets represents the primary substitution threat requiring portfolio rebalancing toward integrated platform solutions. For New Entrants and Emerging Players: Cloud-based diffraction data processing services present the most penetrable white-space as mid-tier academic institutions lack local high-performance computing infrastructure. India's structural biology infrastructure gap in Bangalore and Hyderabad offers geographic entry with lower competitive density than saturated Boston and San Francisco clusters. A subscription revenue model for remote structure validation against AlphaFold predictions provides defensible positioning without capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified analytical instrument conglomerates where crystallography divisions lack strategic fit with core life science portfolios. Long-term viability hinges on positioning experimental validation as a confirmation layer for AI structure prediction rather than competing as a primary discovery engine. The signal to watch is CDSCO pathway evolution toward structural data requirements for biologic approvals in India, which would replicate FDA demand drivers in an underpenetrated geography.| Strategic Initiative | Industry Significance |
|---|---|
| Beamline Detector Upgrade Program | SPring-8 and Advanced Photon Source investments sustain replacement demand for photon-counting hardware. |
| Cloud-Based Data Processing Partnership | Remote computing access enables smaller institutions to participate in fragment-based screening campaigns. |
| Microfluidic Chip Manufacturing Scale-Up | Nanoliter-scale consumption reduces protein requirements for academic laboratories with limited expression capacity. |
| Helium Recovery System Deployment | Cryogenic cooling infrastructure at European facilities mitigates supply concentration risk from Qatar and Algeria. |
| AlphaFold Validation Service Launch | Experimental confirmation layer positions crystallography as essential infrastructure for AI structure prediction. |
Research Methodology
Cross-validation between primary interviews with structural biology department heads, synchrotron beamline managers, and pharmaceutical procurement directors anchors the qualitative findings against secondary sources including FDA biologic approval filings, CDSCO regulatory pathway documentation, and national synchrotron facility capital expenditure disclosures. Bottom-up triangulation aggregates equipment procurement patterns and consumables consumption rates, while top-down validation cross-checks against METI, DESY, and DOE science budget allocations. SEC filings from diversified analytical instrument manufacturers provide revenue segmentation benchmarks.
Sensitivity analysis around helium supply disruption scenarios and cryo-EM adoption curves tests forecast robustness across the projection horizon. Segmentation dimensions modeled include technology modality, end-user institutional type, application workflow, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and consumables attach-rate modeling, with specific inputs from fragment-based screening throughput requirements and biologic approval pathway structural data mandates.
Underlying assumptions cover sustained national synchrotron facility funding, stable helium supply chains, and gradual AI structure prediction adoption without experimental validation displacement, with deviation risk concentrated in geopolitical supply shocks and regulatory pathway acceleration in emerging markets. Recalibration cycles align with material shifts in FDA structural chemistry guidance, CDSCO biologic approval evolution, and national science budget appropriations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Needle Based Biopsy Guns Market
Biomedical Technology
Asia-Pacific Exosome Research Products Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Human Biobanking Ownership Market
Biomedical Technology
Global Exosome Research Products Market
Biomedical Technology
Latin America Digital Biology Market
Biomedical Technology
Cell Proliferation Assay Market
Biomedical Technology
Global Transfection Market
Biomedical Technology
Glycomics Market
Biomedical Technology
Global RNA-Interference (Rnai) Market
Biomedical Technology
Global Automated Cell Cultures Market
Biomedical Technology
Reverse Transcriptase Enzymes Market
Biomedical Technology
North America Proteomics Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
Global Neuroscience Antibodies and Assays Market
Biomedical Technology
France Flow Cytometry Market