
 Blood Brain Barrier Technologies Market | 2026-2036
Blood Brain Barrier Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Brain Barrier Technologies Market Analysis
A capital-intensity divergence between platform-scale biopharmas and focused blood-brain barrier specialists is redrawing competitive boundaries in this space. F. Hoffmann-La Roche Ltd. leverages its deep antibody engineering infrastructure to sustain discovery pipelines against neurodegenerative targets. Denali Therapeutics Inc. anchors its position through proprietary transport vehicle technology that dominates receptor-mediated crossing mechanisms. Pfizer Inc. competes by extending manufacturing scale into lipid nanoparticle formulations optimized for central nervous system penetration.
Blood brain barrier technologies encompass engineered platforms that enable therapeutic molecules to traverse the selectively permeable endothelial membrane separating circulating blood from brain extracellular fluid, typically requiring molecular weights below 400 Da or active transport facilitation via receptor binding or transient tight junction modulation. These systems serve the primary commercial purpose of unlocking previously undruggable neurological targets by achieving therapeutic concentrations in brain parenchyma. Nanocarrier platforms lead current revenue contribution due to established manufacturing infrastructure, while ultrasound-mediated disruption represents the fastest-expanding technology segment as focused transcranial systems advance through late-stage clinical validation. Drug delivery systems command the deepest margin pools owing to recurring consumable architectures and companion diagnostic requirements.
FDA orphan drug designations and EMA PRIME eligibility criteria are accelerating demand for blood-brain barrier-enabled therapies by compressing development timelines and extending market exclusivity for neurological indications. The EU AI Act and evolving FDA guidance on computational modeling for drug-device combination products are reshaping preclinical validation requirements and market access pathways for microfluidic and bioengineered platforms. Stakeholders must monitor how regulatory convergence on real-world evidence standards for CNS drug approval reshapes investment priorities across platform technologies.
Market Dynamics
Ultrasound-mediated blood-brain barrier disruption is compressing development timelines and redrawing competitive boundaries as focused transcranial systems advance through Phase III validation, forcing nanocarrier incumbents to defend manufacturing scale advantages against device-enabled delivery paradigms.
Growth Catalysts
- FDA Accelerated Approval:The FDA's orphan drug designation pathway compresses clinical timelines for neurological indications, pulling investment toward glioblastoma and Alzheimer's programs that require blood-brain barrier penetration.
- Japan's Neuro-Oncology Clustering:Concentrated demand from specialized centers in Tokyo and Osaka creates pull-through for receptor-mediated transport vehicle technologies in Asia-Pacific markets.
- Lipid Nanoparticle Scale-Up:Established biopharma manufacturing infrastructure for mRNA delivery is repurposing toward central nervous system applications, lowering unit economics for brain-penetrating formulations.
Market Restraints
- Receptor Heterogeneity:Patient-to-patient variability in transferrin receptor expression limits predictability of receptor-mediated transport, constraining addressable populations for platform technologies.
- Focused Ultrasound Capital Requirements:Magnetic resonance-guided transcranial systems demand specialized neuroradiology infrastructure that concentrates adoption in tertiary academic medical centers.
- EMA Device-Drug Combination Scrutiny:Evolving guidance on computational modeling requirements for microfluidic platforms extends preclinical validation timelines and raises regulatory friction costs.
Strategic Opportunities
- Germany's AI Act Alignment:Early compliance with EU AI Act requirements for algorithmic drug-device combinations positions vendors for streamlined market access across European neuro-oncology networks.
- Pediatric Neurology Extension:Orphan indications in rare lysosomal storage disorders represent underpenetrated application space where blood-brain barrier technologies unlock enzyme replacement efficacy.
- Real-World Evidence Integration:FDA guidance on digital biomarkers for CNS drug approval creates regulatory tailwind for platforms that combine delivery systems with companion diagnostic monitoring.
Industry Challenges
- Neuropharmacology Talent Scarcity:The specialized skill set spanning blood-brain barrier biology, device engineering, and regulatory strategy concentrates in Boston and Basel, constraining expansion velocity.
- Multi-Site Clinical Coordination:Blood-brain barrier trials require synchronized imaging protocols across neuro-oncology centers, complicating patient recruitment and data integrity.
- IP Fragmentation Across Modalities:Patent thickets covering tight junction modulators, receptor ligands, and ultrasound parameters create licensing complexity for combination product developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Brain Barrier Technologies Market |
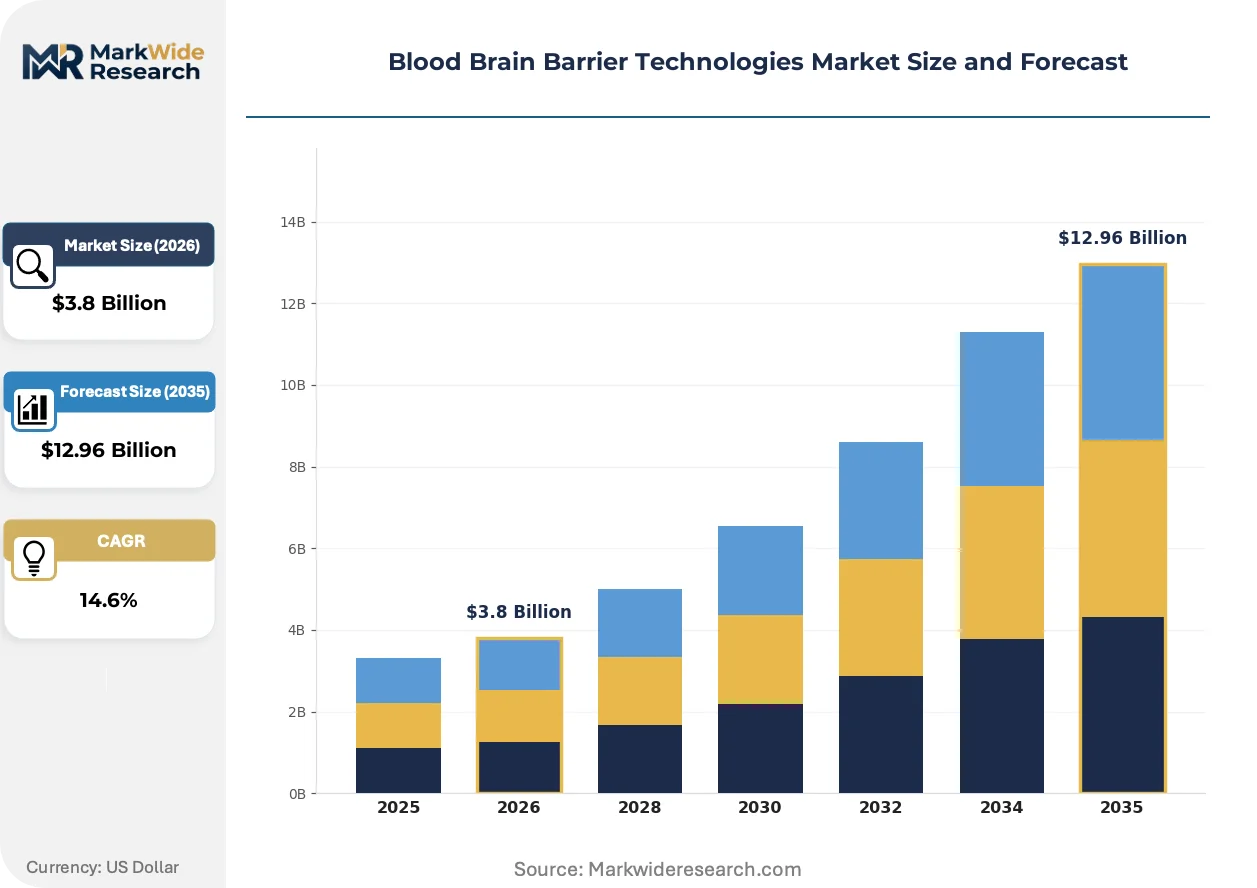
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Receptors, Nanocarriers, Biopharmaceuticals, Drug Delivery Systems Technology: Chemical Modifications, Bioengineering, Microfluidics, Ultrasound Application: Neuroscience Research, Cancer Therapy, Neurological Disorders, Drug Development End User: Pharmaceutical Companies, Research Institutions, Hospitals, Contract Research Organizations |
| Companies Covered | F. Hoffmann-La Roche Ltd., Denali Therapeutics Inc., Pfizer Inc., Eli Lilly and Company, Bristol-Myers Squibb Company, Teva Pharmaceutical Industries Ltd., Bioasis Technologies Inc., Angiochem Inc., JCR Pharmaceuticals Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Brain Barrier Technologies Market Emerging Trajectories
Convergence between device-enabled disruption and molecular engineering is collapsing the traditional trade-off between delivery precision and therapeutic payload capacity, opening modalities previously excluded from neurological drug development.
Focused ultrasound with microbubble contrast is supplanting passive nanocarrier diffusion as the dominant mechanism for achieving therapeutic brain concentrations in solid tumors. Neuro-oncology centers at MD Anderson, Heidelberg, and Tokyo University Hospital are adopting these systems at pace, with installed base doubling across 2023-2024. This shift is supplanting the historical reliance on liposomal encapsulation, compressing addressable market share for pure-play nanotechnology vendors and forcing integrated platform strategies.
The EU AI Act's risk classification framework for medical device software is reshaping preclinical validation requirements for computational models predicting blood-brain barrier permeability. Industrial consequence includes mandatory documentation of training data provenance and algorithmic transparency for any AI-assisted patient selection tool. Microfluidic platform developers in Germany and the Netherlands are responding by embedding regulatory affairs functions earlier in R&D, with several consortia pooling validation datasets to defray compliance costs.
Neuro-oncology procurement is consolidating around integrated delivery-and-monitoring contracts that bundle device placement, imaging, and therapeutic administration under single-site accountability. Academic medical centers in the United States and Japan are displacing traditional fee-for-service arrangements with episode-based pricing for glioblastoma treatment protocols. This restructuring is most visible in National Cancer Institute-designated centers, where purchasing committees now evaluate total cost-of-treatment rather than device capital expenditure alone.
Blood Brain Barrier Technologies Market Segmentation
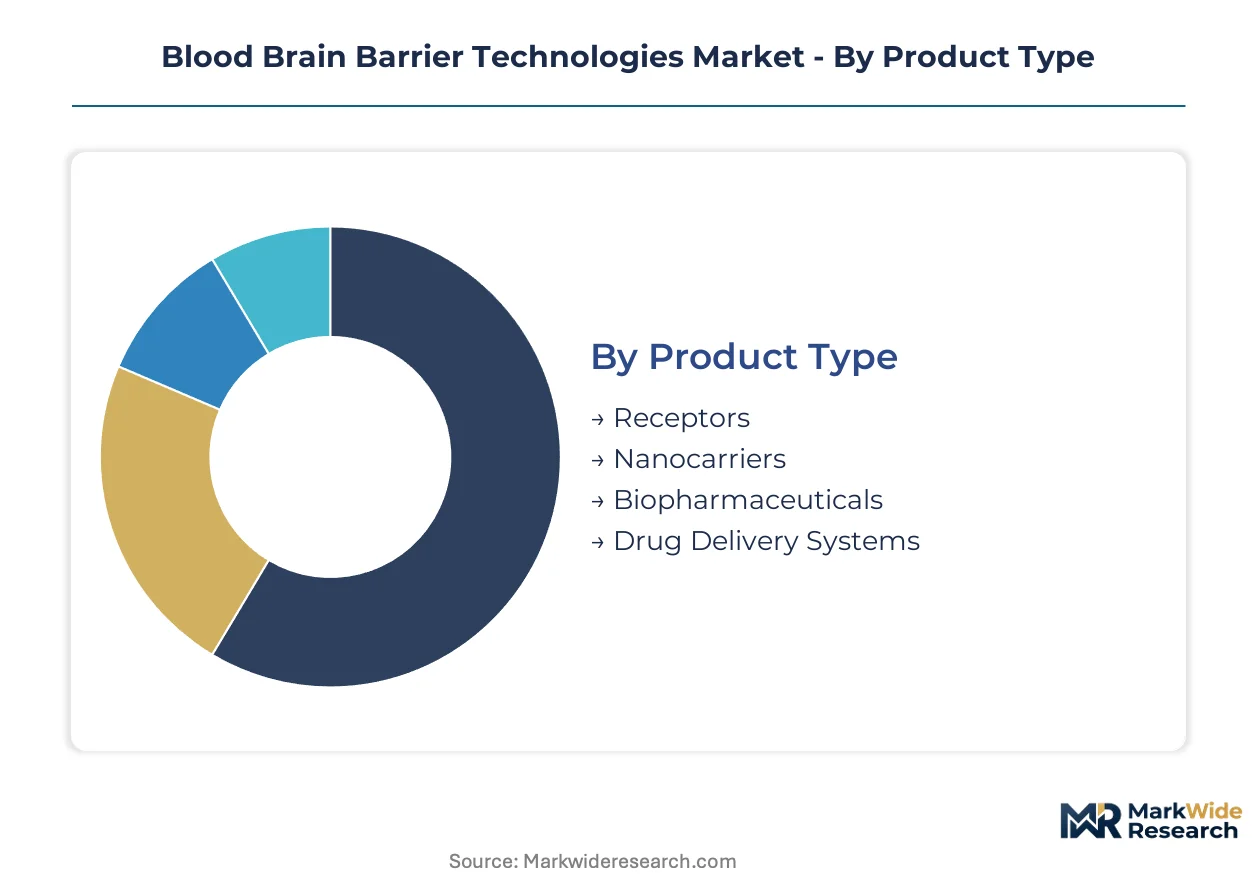
Segmentation in blood-brain barrier technologies reveals how regulatory pathways, manufacturing infrastructure, and clinical validation requirements create divergent commercial trajectories across platform types. Understanding these divisions exposes where capital concentrates and where emerging modalities threaten incumbent positions.
Product Type:
FDA device-drug combination guidance and EMA PRIME eligibility criteria create divergent approval economics across molecular and systems-based platforms, favoring technologies with established regulatory precedent.
- Drug Delivery Systems:Engineered architectures combining active transport facilitation with companion diagnostic monitoring command premium positioning through recurring consumable revenue streams. Demand concentrates in National Cancer Institute-designated centers across the United States where episode-based procurement bundles device placement with therapeutic administration.
- Nanocarriers:Lipid-based and polymeric encapsulation systems leverage repurposed mRNA manufacturing infrastructure to achieve production scale, though focused ultrasound disruption is compressing addressable share in solid tumor applications. German and Dutch microfluidic specialists are embedding regulatory affairs earlier to defray EU AI Act compliance costs.
- Receptors:Transferrin receptor-mediated transport vehicles face predictability constraints from patient-to-patient expression variability.
- Biopharmaceuticals:Antibody engineering platforms from established biopharma infrastructure target neurodegenerative indications with accelerated FDA orphan pathways.
Established volume favors nanocarriers; emerging adoption favors drug delivery systems.
Technology:
Capital intensity and site-of-care requirements stratify adoption across academic medical centers versus community oncology networks, with magnetic resonance infrastructure acting as a gating factor.
- Ultrasound:Focused transcranial systems with microbubble contrast achieve therapeutic brain concentrations through transient tight junction modulation without molecular engineering. Heidelberg and Tokyo University Hospital installations doubled across recent periods, displacing passive diffusion methods in glioblastoma protocols.
- Bioengineering:Receptor ligand optimization and transport vehicle engineering dominate discovery pipelines at Boston and Basel talent clusters, constraining expansion velocity due to specialized skill scarcity.
- Chemical Modifications:Small-molecule permeability enhancement through structural alteration remains constrained by the 400 Da molecular weight threshold for passive diffusion.
- Microfluidics:Computational modeling platforms face extended preclinical timelines from evolving EMA guidance on algorithmic transparency and training data provenance documentation.
Ultrasound is climbing the fastest; bioengineering retains deepest incumbent investment.
Application:
Clinical trial design complexity and patient recruitment economics concentrate platform development in indications with compressed regulatory timelines and reimbursed diagnostic pathways.
- Cancer Therapy:Glioblastoma multiforme drives immediate revenue concentration through orphan drug designation pull-through, with MD Anderson and Heidelberg centers adopting integrated delivery-and-monitoring contracts that bundle imaging with therapeutic administration.
- Neurological Disorders:Alzheimer's programs attract platform-scale biopharma investment despite historical failure rates, as FDA accelerated approval pathways extend market exclusivity for blood-brain barrier-enabled modalities.
- Neuroscience Research:Academic procurement cycles and grant-dependent funding limit commercial velocity relative to therapeutic applications.
- Drug Development:Contract research utilization spans preclinical validation through Phase I, with multi-site imaging protocol synchronization complicating data integrity.
Oncology applications command current margin pools; neurological disorder platforms carry longest development horizons.
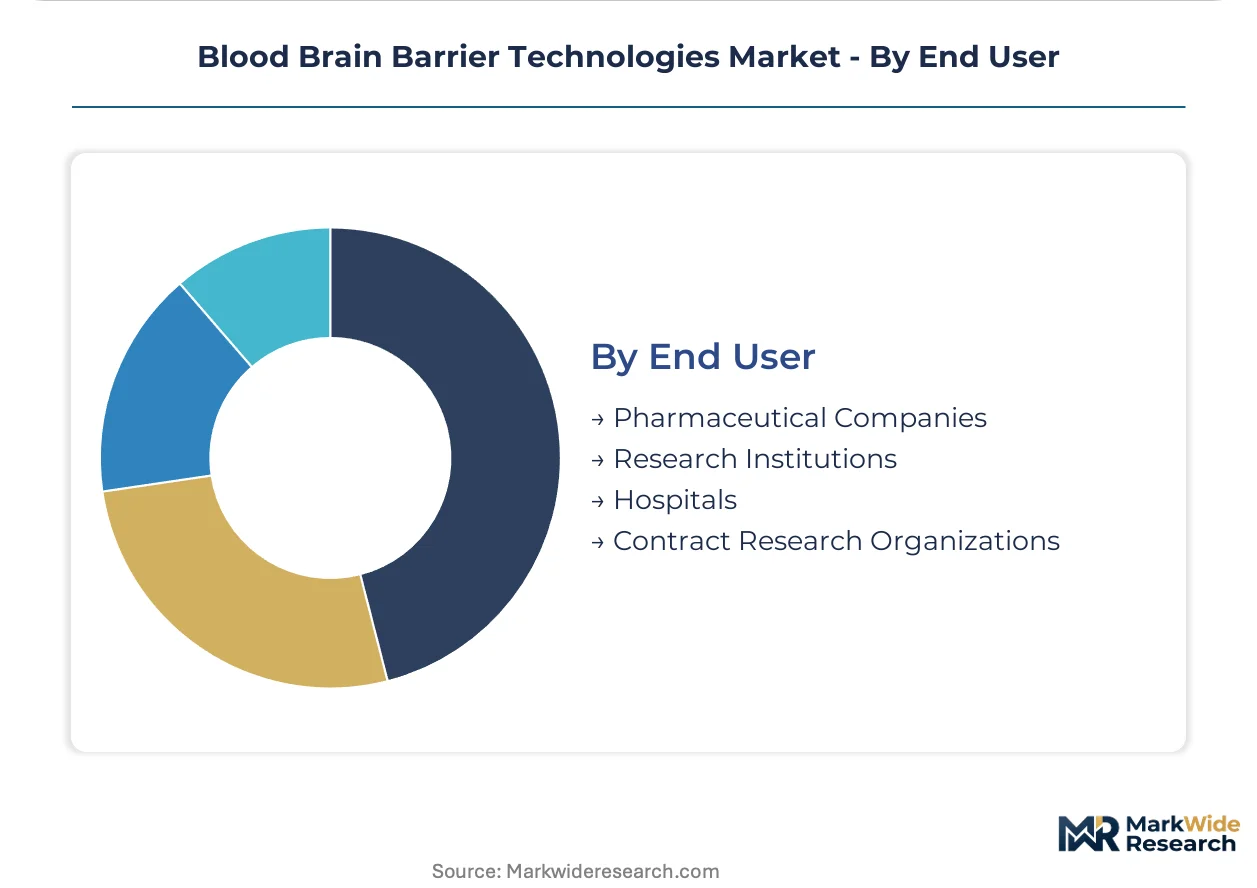
End User:
Purchasing authority and reimbursement mechanisms determine whether technologies penetrate through capital equipment committees or therapeutic formulary decisions.
- Pharmaceutical Companies:Internal antibody engineering and lipid nanoparticle scale-up capabilities drive captive platform development, with Roche and Pfizer extending manufacturing infrastructure toward central nervous system applications.
- Hospitals:Tertiary academic medical centers in the United States, Germany, and Japan concentrate magnetic resonance-guided system adoption due to neuroradiology infrastructure requirements.
- Research Institutions:Grant-funded neuroscience programs prioritize reproducibility and publication velocity over regulatory throughput.
- Contract Research Organizations:Multi-site trial coordination capabilities address the synchronization challenges of blood-brain barrier protocol standardization.
Pharmaceutical investment favors integrated platform control; hospital procurement favors episode-based accountability structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for blood-brain barrier technologies concentrates in the United States and Japan, where tertiary neuro-oncology centers command premium reimbursement, while German and Swiss markets prioritize cost-efficiency in episode-based procurement frameworks.
United States
Orphan drug designation pathways and FDA accelerated approval pull investment toward glioblastoma and Alzheimer's programs. The National Cancer Institute network bundles device placement with therapeutic administration under episode-based contracts. MD Anderson and other designated centers drive concentrated demand for magnetic resonance-guided focused ultrasound systems.
Germany
EMA PRIME eligibility and EU AI Act compliance requirements reshape preclinical validation for algorithmic drug-device combinations. Heidelberg University Hospital anchors European adoption of focused transcranial systems, with installed base expansion displacing passive nanocarrier diffusion in neuro-oncology protocols.
Japan
METI industrial policy and PMDA streamlined pathways for neurological orphan drugs accelerate platform development. Tokyo and Osaka specialized centers create pull-through for receptor-mediated transport vehicle technologies, with Tokyo University Hospital doubling system installations across recent periods.
Switzerland
Swissmedic alignment with EMA device-drug combination guidance supports Basel-centered antibody engineering infrastructure. The country's pharmaceutical manufacturing ecosystem extends lipid nanoparticle scale-up capabilities toward central nervous system applications, lowering unit economics for brain-penetrating formulations.
United Kingdom
MHRA post-Brexit regulatory convergence with FDA real-world evidence standards creates tailwind for platforms combining delivery systems with companion diagnostic monitoring. London and Cambridge neurodegenerative research clusters concentrate specialized talent spanning blood-brain barrier biology and regulatory strategy.
Blood Brain Barrier Technologies Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with platform-scale biopharmas commanding manufacturing scale while specialized blood-brain barrier innovators dominate receptor-mediated transport mechanisms. The market structure consolidates around three tiers: integrated pharmaceutical conglomerates with captive antibody engineering, focused biotechnology specialists with proprietary delivery platforms, and device-enabled disruption vendors advancing through late-stage clinical validation. Dominant competitive moves include strategic partnerships bridging molecular engineering with neuroradiology infrastructure, and geographic expansion into Japan's concentrated neuro-oncology clusters.
Within the integrated pharmaceutical tier, F. Hoffmann-La Roche Ltd. and Pfizer Inc. occupy positions defined by manufacturing infrastructure extension into central nervous system applications. Denali Therapeutics Inc. exemplifies the focused biotechnology archetype, anchoring competitive positioning through proprietary transport vehicle technology. These three companies represent the strategic spectrum from scale-driven platform control to specialized mechanism dominance.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Denali Therapeutics Inc. |
| Pfizer Inc. |
| Eli Lilly and Company |
| Bristol-Myers Squibb Company |
| Teva Pharmaceutical Industries Ltd. |
| Bioasis Technologies Inc. |
| Angiochem Inc. |
| JCR Pharmaceuticals Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
FDA device-drug combination guidance gates both supplier qualification and price differentiation simultaneously, compressing margins for nanocarrier vendors unable to demonstrate integrated delivery-and-monitoring capabilities while rewarding ultrasound-mediated platforms with episode-based procurement premiums.
Pricing Analysis
Configured-to-order pricing for magnetic resonance-guided focused ultrasound systems commands three-to-five-fold premiums over standard nanocarrier formulations. Pricing stratifies across premium, standard, and economy tiers based on FDA breakthrough device designation status and companion diagnostic bundling. Cost compression in nanocarrier segments is intensifying because repurposed mRNA manufacturing infrastructure floods supply. Academic medical centers exhibit lowest price sensitivity due to episode-based accountability structures, while community oncology networks face capital constraints.
Supply Chain Analysis
United States and Switzerland anchor biopharmaceutical manufacturing infrastructure for lipid nanoparticle scale-up, while Germany and Japan concentrate microfluidic platform engineering. Production draws from specialized neuroradiology equipment fabrication in the United States, precision ultrasound transducer manufacturing in Japan, and recombinant protein production in Switzerland. Single-source vulnerability concentrates in transferrin receptor ligand supply from Basel-centered antibody engineering clusters. Distribution runs through National Cancer Institute-designated centers and specialized neuro-oncology networks rather than broad hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in blood-brain barrier technologies hinge on interoperability between molecular engineering and device-enabled delivery, with ultrasound-microbubble convergence collapsing traditional modality boundaries and forcing ecosystem-wide repositioning.
For Market Incumbents: Compound manufacturing scale advantages through captive lipid nanoparticle capacity additions in Switzerland and backward integration into microbubble contrast supply. Lock in episode-based procurement contracts at MD Anderson and Heidelberg before emerging ultrasound-device vendors achieve installed base critical mass. Prioritize FDA breakthrough device designation investment to defend pricing premiums against nanocarrier commoditization. For New Entrants and Emerging Players: FDA accelerated approval fast-tracks for orphan neurological indications offer the most penetrable regulatory pathway for receptor-mediated transport vehicles. Target Japan's Tokyo-Osaka neuro-oncology cluster where METI industrial policy creates procurement pull-through for novel platforms. Enter through pediatric lysosomal storage disorder applications where enzyme replacement efficacy gaps remain unaddressed by incumbent nanocarrier systems. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across ultrasound-mediated delivery sub-segments as magnetic resonance infrastructure standardizes, while bioengineering platforms face sustained high capital requirements from specialized Boston-Basel talent scarcity. Five-to-ten year viability favors device-drug combination developers with late-stage clinical validation over pure-play molecular engineering targets. Monitor FDA real-world evidence guidance finalization as the critical signal for platform valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III validation of focused ultrasound systems at Heidelberg and Tokyo University Hospital displaces passive nanocarrier protocols. |
| Regulatory Approval Pathway | FDA breakthrough device designation compresses review timelines for ultrasound-microbubble combinations in glioblastoma indications. |
| Manufacturing Scale-Up | Lipid nanoparticle capacity expansion in Switzerland lowers unit economics for brain-penetrating formulations targeting Alzheimer's. |
| Strategic Partnership | Neuroradiology infrastructure alliances bundle device placement with therapeutic administration under single-site accountability. |
| Pipeline Diversification | Extension into pediatric neurology applications unlocks enzyme replacement efficacy for rare lysosomal storage disorders. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Drug development executives, regulatory affairs leads, formulary directors, and neuroradiology department heads provided operational perspective across the United States, Germany, and Japan. Bottom-up segment sizing triangulates against top-down expenditure analysis from national health system accounts.
Segmentation dimensions modeled span technology platform, application indication, end-user archetype, and regional regulatory cluster across the projection horizon. CAGRs derive from patent filing trajectory analysis, clinical trial enrollment velocity, and installed base expansion patterns for focused ultrasound systems. Forecast inputs incorporate EMA PRIME eligibility conversion rates and FDA orphan drug designation pathway throughput.
Decision-makers should treat outputs as directional under assumptions of sustained FDA accelerated approval pathway integrity and stable EU AI Act implementation timelines; material deviation would warrant model refresh. Recalibration cycles align with material shifts in regulatory guidance finalization and breakthrough device designation award patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Ligases Enzyme Market
Biomedical Technology
Global Protein Crystallization and Crystallography Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Automated Cell Biology Systems Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
Cell Isolation Market
Biomedical Technology
Imaging Biomarkers Market
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
Global Neuroscience Antibodies and Assays Market
Biomedical Technology
Global Automated Cell Cultures Market
Biomedical Technology
Cell Cycle Analysis Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Global Cell Counting Market
Biomedical Technology
Lipid Transfer Proteins Market
Biomedical Technology
Europe Exosome Research Products Market
Biomedical Technology
Live Cell Analysis System Market