
 Cell Proliferation Assay Market | 2026-2036
Cell Proliferation Assay Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Proliferation Assay Market Analytics
Biotechnology firms are unwinding the historical dominance of academic laboratories in cell proliferation assay procurement. Thermo Fisher Scientific leverages its microplate reader and reagent bundling to sustain installed-base loyalty across pharmaceutical quality control labs. Lonza Group AG anchors its position through specialized contract testing services that integrate proprietary luminescent assay chemistries. Danaher Corporation competes via Beckman Coulter's flow cytometry platforms, which dominate high-throughput screening environments.
Cell proliferation assays quantify metabolic activity, DNA synthesis, or ATP concentration to measure living cell population dynamics, typically employing tetrazolium salts, resazurin dyes, or BrdU/EdU incorporation with detection thresholds in the nanomolar range. Fluorescent assays lead the product type landscape due to their multiplexing compatibility with high-content imaging systems, while label-free assays represent the fastest-expanding segment as impedance-based and live-cell imaging technologies displace endpoint methods in chronic toxicity studies. Automated workstations command the technology margin pool by reducing manual variability in 384- and 1536-well formats.
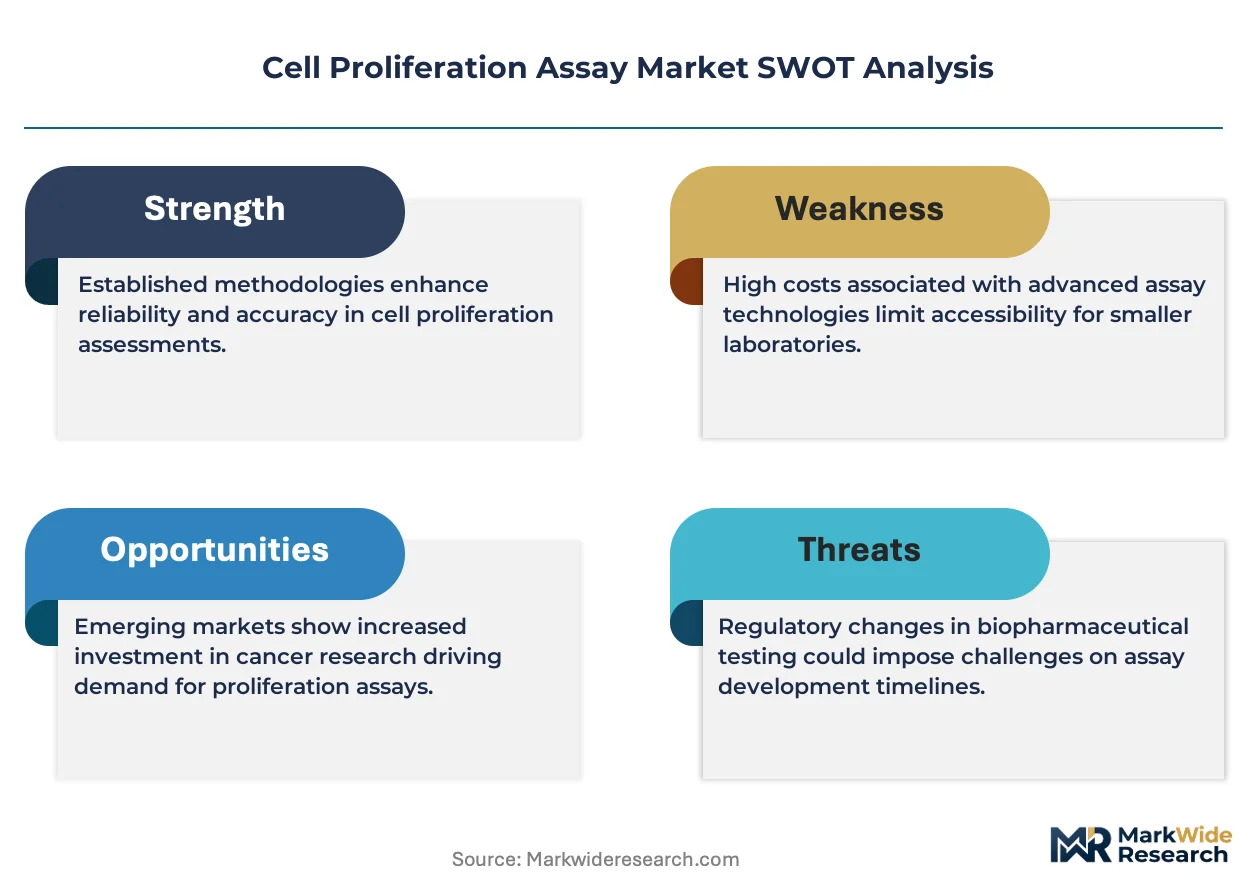
FDA's evolving guidance on ICH Q5D cell substrate qualification and EMA's MDR-driven emphasis on analytical comparability for biosimilars shape assay standardization requirements across regulated development pipelines. ISO 10993 biocompatibility testing protocols and OECD Test Guideline 471 further extend demand into medical device and chemical safety assessment sectors. Stakeholders must monitor how AI-enabled image analysis tools reshape instrument purchasing criteria and reagent volume forecasts.
Market Dynamics
CRISPR-based screening workflows are multiplying across academic and biotech laboratories, forcing assay manufacturers to reconfigure reagent portfolios for gene-editing compatibility while FDA and EMA tighten potency validation standards for cell-based biologics.
Growth Catalysts
- FDA ICH Q5D Guidance:The agency's cell substrate qualification requirements are mandating proliferation assays for viral vector characterization, expanding reagent volumes in gene therapy manufacturing.
- High-content imaging convergence:Multiplexing demand from pharmaceutical toxicology departments is pulling fluorescent assay chemistries into 384-well automated workflows.
- Boston-San Diego biotech clustering:Geographic concentration of cell therapy developers is sustaining localized instrument procurement and technical service contracts.
Market Restraints
- Luminescent substrate cost volatility:Firefly and Renilla luciferase reagent supply depends on specialized fermentation capacity concentrated among three contract manufacturers.
- Endpoint method displacement friction:Impedance-based and live-cell imaging platforms require capital-intensive hardware upgrades that smaller CROs cannot absorb.
- EMA MDR analytical comparability:Biosimilar developers face extended validation timelines for proliferation-based potency assays, compressing project economics.
Strategic Opportunities
- India's CDSCO biologics pathway:The regulator's emerging biosimilar approval framework lacks established proliferation assay standards, creating first-mover standardization potential.
- AI-enabled image analysis:Machine learning tools for colony counting and confluence measurement are converging with cloud-based data platforms to enable decentralized assay interpretation.
- ISO 10993 medical device testing:Biocompatibility protocols for implantable devices are extending proliferation assay demand beyond pharmaceutical applications.
Industry Challenges
- Flow cytometry technician scarcity:BrdU/EdU incorporation assays require specialized gating expertise that contract labs struggle to recruit in competitive labor markets.
- Legacy LIMS integration:Automated plate readers generate data formats incompatible with established laboratory information management systems, forcing middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Proliferation Assay Market |
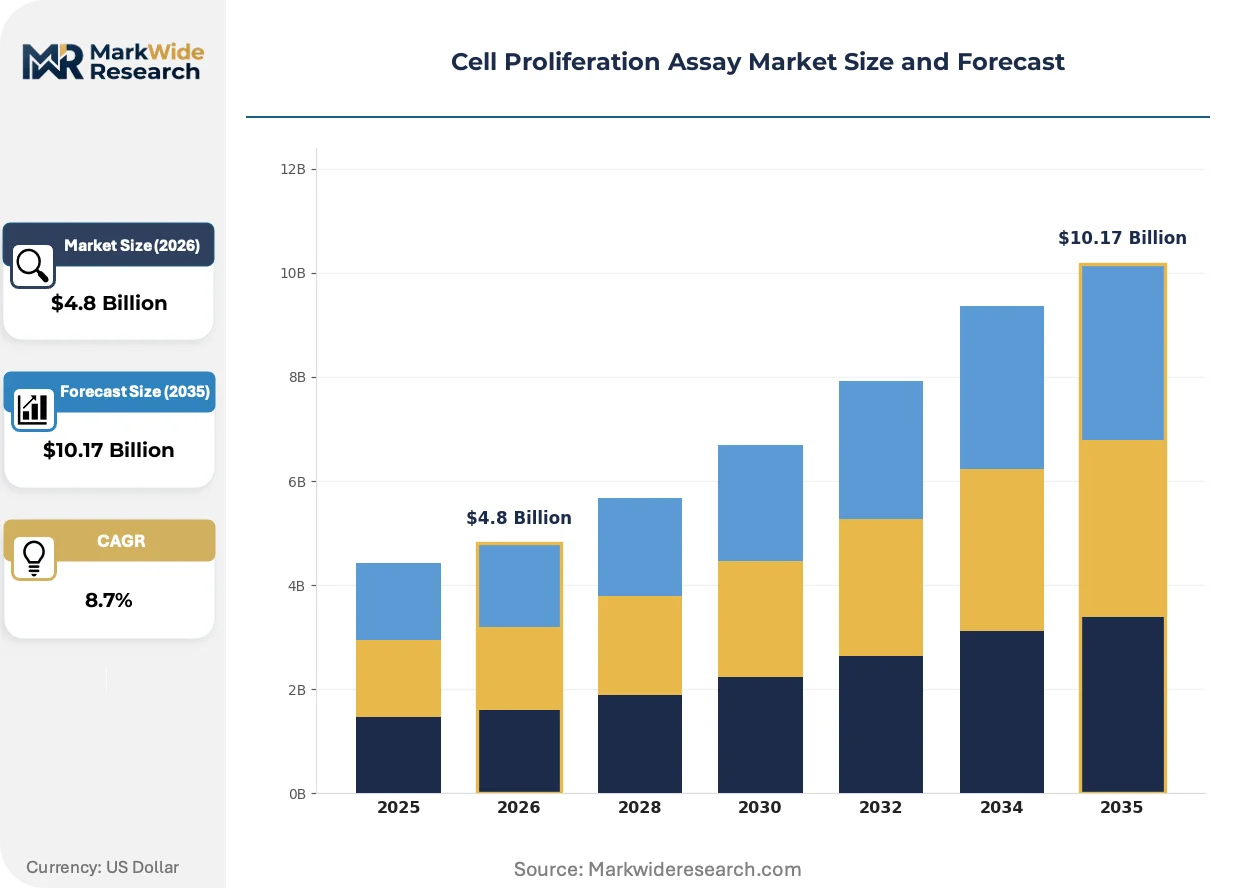
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescent Assays, Colorimetric Assays, Luminescent Assays, Label-free Assays Technology: Microplate Reader, Flow Cytometry, Imaging Systems, Automated Workstations End User: Academic Research Institutions, Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations Application: Drug Discovery, Cancer Research, Toxicology Studies, Stem Cell Research |
| Companies Covered | Merck KGaA, Thermo Fisher Scientific Inc., Bio-Rad Laboratories Inc., Becton, Dickinson and Company, Agilent Technologies Inc., Danaher Corporation, Lonza Group AG, Charles River Laboratories, PerkinElmer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Proliferation Assay Market Evolving Landscape
Label-free detection technologies are actively reshaping competitive positioning by eliminating dye-dependent artifacts in long-duration toxicity studies. Three developments are compressing the traditional reagent-instrument bundling model.
Impedance-based real-time cell analysis is fragmenting the endpoint assay market by enabling continuous monitoring without sample destruction. Pharmaceutical toxicology departments are adopting xCELLigence and similar platforms for chronic exposure studies. This displacement is compressing tetrazolium salt and resazurin reagent volumes in 96-well formats while expanding hardware service contract values.
REACH chemical safety assessment extensions are mandating proliferation endpoints for skin sensitization and ocular irritation alternatives to animal testing. European cosmetic and industrial chemical manufacturers must now validate in vitro methods under ECHA guidance. Contract testing organizations in Germany and the Netherlands are scaling capacity for the OECD Test Guideline 471 compliant protocols.
Assay-as-a-service contracting is displacing capital purchase models among mid-sized biotechnology firms. CROs including Charles River and Eurofins are unbundling instrument access from reagent supply, charging per-plate fees with embedded technical support. This consumption pattern is most visible in the United Kingdom and Switzerland where biotech venture funding concentrates on asset-light development strategies.
Cell Proliferation Assay Market Segmentation
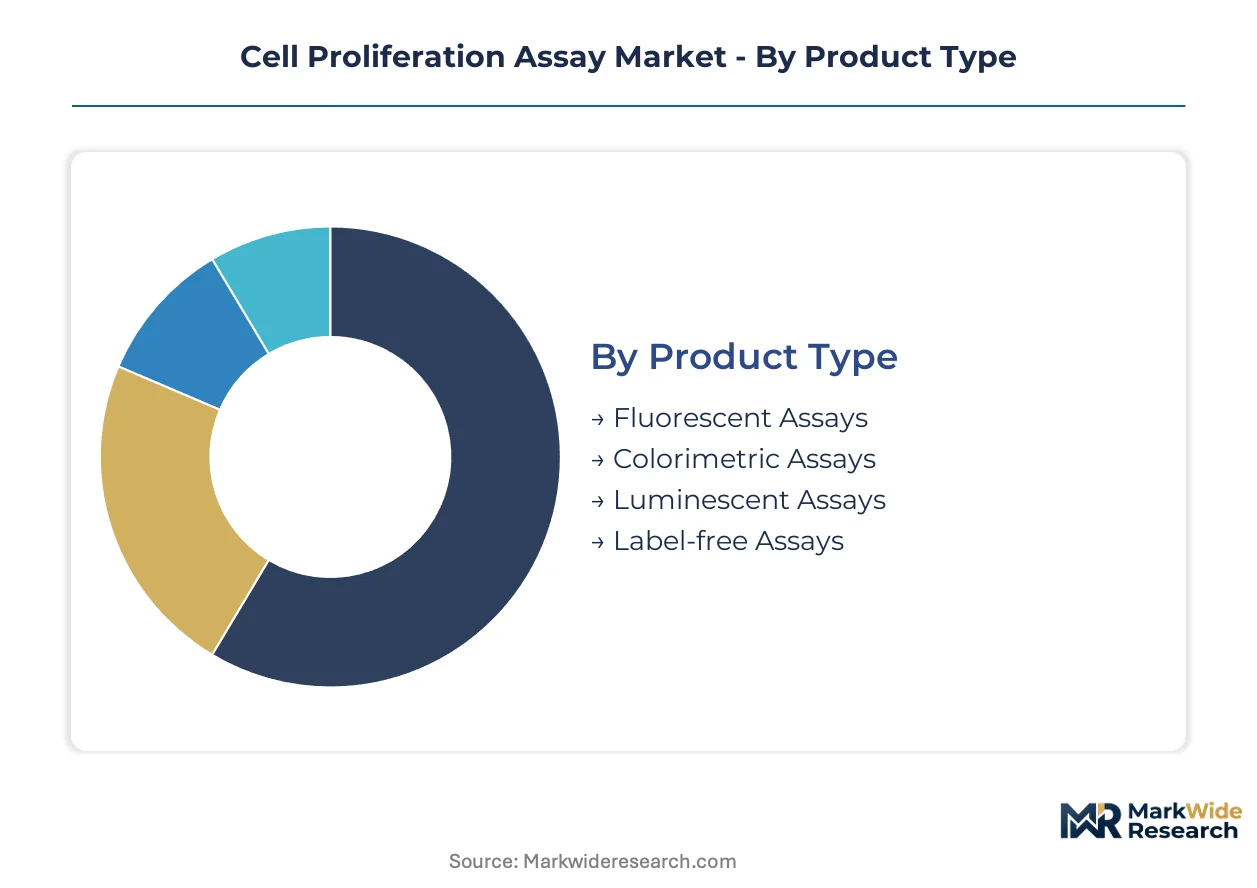
Cell proliferation assay segmentation reflects divergent regulatory validation requirements across pharmaceutical manufacturing, academic research, and contract testing environments. Product type and technology choices carry direct implications for FDA ICH Q5D compliance, EMA MDR biosimilar characterization, and OECD Test Guideline 471 chemical safety protocols.
Product Type:
FDA potency assay guidance and EMA analytical comparability standards create tiered validation burdens that reshape reagent procurement patterns across detection chemistries.
- Fluorescent Assays:These assays employ resazurin dyes and DNA-binding fluorophores with nanomolar detection thresholds. Pharmaceutical toxicology departments in Germany and Switzerland are concentrating procurement for multiplexed high-content imaging workflows, driven by REACH chemical safety assessment mandates.
- Label-free Assays:Impedance-based and live-cell imaging technologies eliminate dye-dependent artifacts in chronic toxicity studies. Biotechnology firms in Boston and San Diego are accelerating adoption for gene therapy viral vector characterization, displacing endpoint methods in 96-well formats.
- Colorimetric Assays:Tetrazolium salt reduction methods (MTT, XTT, WST-1) remain staples in academic laboratories with limited capital budgets for instrumentation upgrades.
- Luminescent Assays:ATP quantification via firefly luciferase chemistry dominates high-throughput screening for drug discovery applications, though substrate supply volatility constrains contract manufacturer flexibility.
Established volume favors fluorescent chemistries; emerging adoption favors label-free platforms.
Technology:
Capital intensity and throughput requirements stratify instrument procurement across automated 384-well workflows and specialized flow cytometry environments.
- Automated Workstations:Integrated plate handling and liquid dispensing systems reduce manual variability in high-density formats. Contract research organizations in the United Kingdom and Switzerland are prioritizing per-plate service contracting over capital purchase, compressing upfront instrument revenue while expanding recurring service margins.
- Flow Cytometry:Beckman Coulter platforms dominate BrdU/EdU incorporation assays requiring specialized gating expertise. Academic research institutions face technician recruitment constraints that limit capacity expansion despite NIH funding growth.
- Microplate Reader:Bundled reagent-instrument packages sustain installed-base loyalty in pharmaceutical quality control labs with established SOP validation.
- Imaging Systems:High-content analysis platforms integrate with fluorescent assay chemistries for multiparametric toxicity assessment under ISO 10993 biocompatibility protocols.
Hardware margins concentrate in automated workstations; capability scarcity sits with flow cytometry technical staffing.
End User:
Procurement authority is shifting from academic laboratories toward biotechnology firms with asset-light development strategies and outsourced validation requirements.
- Biotechnology Firms:CRISPR-based screening workflows are multiplying across Boston and San Diego clusters, forcing assay manufacturers to reconfigure reagent portfolios for gene-editing compatibility. These firms favor assay-as-a-service contracting to preserve venture capital for therapeutic asset development.
- Contract Research Organizations:Charles River and Eurofins are scaling OECD Test Guideline 471 compliant capacity for European cosmetic and industrial chemical manufacturers. Per-plate pricing with embedded technical support is displacing capital purchase models among mid-sized clients.
- Academic Research Institutions:NIH funding trajectories sustain instrument and reagent consumption, though budget constraints favor colorimetric methods over capital-intensive label-free platforms.
- Pharmaceutical Companies:Quality control labs maintain validated SOPs with bundled microplate reader and reagent supply, prioritizing regulatory consistency over technology migration.
Procurement volume anchors in pharmaceutical quality control; contract flexibility expands most quickly in biotechnology outsourcing.
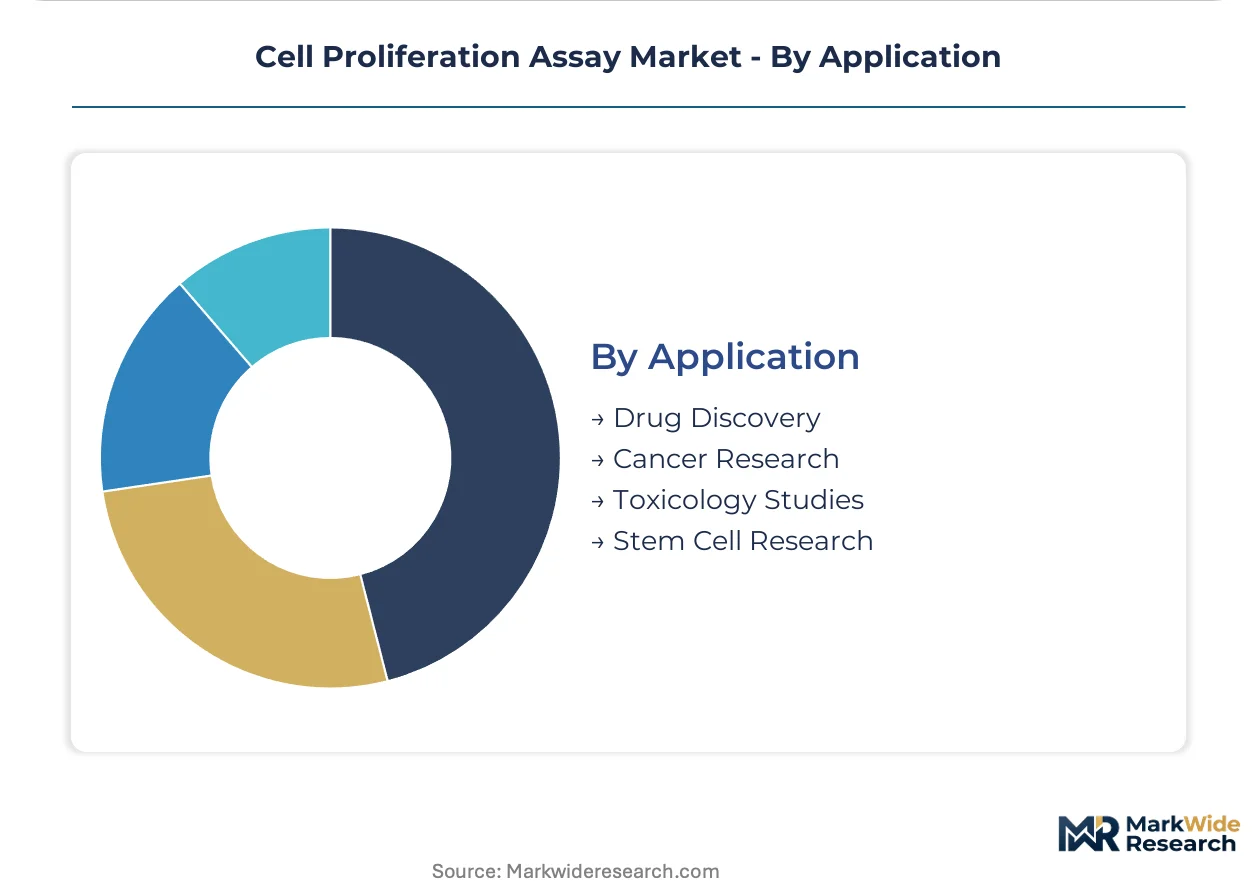
Application:
Regulatory endpoint requirements vary sharply across therapeutic development stages and safety assessment protocols.
- Drug Discovery:High-throughput screening demands luminescent ATP assays and automated workstation integration. Multiplexing requirements from pharmaceutical toxicology departments are pulling fluorescent chemistries into 384-well formats.
- Toxicology Studies:REACH extensions and ECHA guidance mandate proliferation endpoints for skin sensitization alternatives. European contract testing organizations in Germany and the Netherlands are validating impedance-based methods for chronic exposure assessment.
- Cancer Research:BrdU/EdU incorporation assays with flow cytometry detection dominate cell cycle analysis in academic and biotech laboratories.
- Stem Cell Research:Label-free impedance monitoring enables continuous pluripotency assessment without sample destruction, climbing fastest in gene therapy manufacturing support.
Validation burden concentrates in toxicology studies; technical innovation favors stem cell and gene therapy applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biotechnology firms and contract research organizations concentrate procurement authority across four distinct national markets, each shaped by divergent regulatory timelines and funding architectures.
United States
NIH funding trajectories and venture capital deployment sustain instrument consumption across Boston and San Diego biotech clusters. FDA ICH Q5D guidance on cell substrate qualification mandates proliferation assays for viral vector characterization in gene therapy manufacturing. The Greater Boston metropolitan area anchors contract testing capacity expansion as CDMOs scale to meet potency validation requirements.
Germany
REACH chemical safety assessment extensions drive demand for OECD Test Guideline 471 compliant proliferation endpoints in cosmetic and industrial chemical screening. ECHA guidance on skin sensitization alternatives validates impedance-based methods for chronic exposure studies. Contract testing organizations in the Cologne-Düsseldorf corridor scale capacity to serve European cosmetic manufacturers.
United Kingdom
Assay-as-a-service contracting displaces capital purchase models among mid-sized biotechnology firms pursuing asset-light development strategies. MHRA alignment with EMA biosimilar standards maintains analytical comparability requirements for proliferation-based potency assays. The Cambridge-Oxford-London golden triangle concentrates CRISPR screening workflow adoption and reagent procurement.
India
CDSCO's emerging biologics approval pathway lacks established proliferation assay standards, creating first-mover standardization opportunities for assay manufacturers. Government PLI scheme incentives for pharmaceutical manufacturing attract CDMO investment in analytical testing infrastructure. Hyderabad and Bangalore clusters expand contract research capacity to serve domestic and export biologics developers.
Switzerland
Swissmedic's stringent biologics characterization standards enforce rigorous validation protocols for proliferation-based potency assays. Roche and Novartis manufacturing footprints sustain demand for high-throughput screening platforms in Basel and Zurich metropolitan areas. Per-plate service contracting models from CROs align with venture-funded biotech preferences for operational flexibility.
Cell Proliferation Assay Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with integrated reagent-instrument portfolios. Market structure concentrates around three to five holding companies controlling multiple assay technology brands. Strategic archetypes include bundled solution providers, specialized contract testing services, and platform-agnostic reagent suppliers. Dominant competitive moves encompass reagent portfolio reconfiguration for CRISPR compatibility and middleware development for legacy LIMS integration.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify instrument-reagent bundling strategies that sustain installed-base loyalty across pharmaceutical quality control environments. Lonza Group AG occupies a distinct position through specialized contract testing services that integrate proprietary chemistries with manufacturing support. Merck KGaA anchors the European reagent supply vector with fermentation-dependent substrate production capabilities.
| Leading Market Players |
|---|
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories Inc. |
| Becton, Dickinson and Company |
| Agilent Technologies Inc. |
| Danaher Corporation |
| Lonza Group AG |
| Charles River Laboratories |
| PerkinElmer Inc. |
| Others |
Value Network & Pricing Analysis
FDA ICH Q5D cell substrate qualification requirements gate both reagent supplier qualification and price differentiation across pharmaceutical quality control tiers, compressing margins for non-validated chemistries while sustaining premiums for GMP-compliant assay bundles.
Pricing Analysis
Cost-plus contracts with luciferase substrate indexation dominate luminescent assay procurement, tying ATP quantification kit prices to fermentation input volatility. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated bundles from research-grade reagents and academic colorimetric staples. Pricing pressure stems from assay-as-a-service contracting that unbundles instrument access from per-plate fees. Biotechnology firms exhibit highest price sensitivity as venture-funded developers prioritize asset-light outsourcing over capital-intensive platform ownership.
Supply Chain Analysis
Just-in-time inventory strategies prevail among automated workstation manufacturers serving high-throughput screening environments, while contract research organizations maintain strategic stockpiles of firefly luciferase substrates to buffer fermentation supply volatility. Supply concentrates in the United States for microplate reader instrumentation, Germany for impedance-based platform components, and Switzerland for high-content imaging systems. Critical dependencies include specialized fermentation capacity for luciferase production, optical sensor arrays for label-free detection, and precision liquid handling modules. Single-source vulnerability concentrates in luciferase substrate supply among three contract manufacturers. Distribution runs through direct instrument-reagent bundling for pharmaceutical quality control labs and per-plate service contracting for mid-sized biotechnology firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among contract research organizations as mid-sized biotechnology firms fragment procurement authority through assay-as-a-service outsourcing, compressing reagent manufacturers' direct sales margins.
For Market Incumbents: Shield installed-base loyalty by deepening GMP validation documentation for FDA ICH Q5D compliance and securing exclusive substrate fermentation contracts to lock out substitute suppliers. The priority lever rests on backward integration into luciferase production capacity to neutralize supply volatility threats from contract manufacturers. For New Entrants and Emerging Players: Anchor in India's CDSCO biologics pathway where proliferation assay standards remain undefined, targeting domestic CDMOs scaling analytical testing infrastructure under PLI scheme incentives. White-space opportunity concentrates in impedance-based platform service contracting for chronic toxicity studies, with go-to-market traction through per-plate pricing models that match venture-funded biotech preferences for operational flexibility. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across label-free assay platforms as cloud-based AI image analysis tools reduce hardware dependency for decentralized assay interpretation. Long-term viability favors platform-agnostic reagent suppliers with CRISPR-compatible portfolio breadth over instrument-dependent bundling models. Acquisition targets should demonstrate validated middleware for legacy LIMS integration. The signal to watch is CDSCO's publication of definitive proliferation assay standards, which will trigger consolidation among first-mover standardization claimants.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR-Compatible Reagent Portfolio Expansion | Gene therapy developers in Boston and San Diego clusters require validated chemistries for edited cell line screening. |
| Middleware Development for Legacy LIMS Integration | Automated plate reader data formats force technical solutions that reduce customer switching costs. |
| Assay-as-a-Service Platform Launch | Per-plate contracting aligns with UK and Swiss biotech venture funding concentration on asset-light strategies. |
| GMP Validation Investment for ICH Q5D Compliance | FDA guidance on viral vector characterization mandates proliferation assays in gene therapy manufacturing pipelines. |
| AI-Enabled Image Analysis Partnership | Machine learning tools for colony counting reshape instrument purchasing criteria and reagent volume forecasts. |
Research Methodology
The analysis maps fluorescent assay chemistries, label-free detection platforms, luminescent ATP quantification methods, and colorimetric tetrazolium reduction assays, each validated through primary interviews with drug development executives, regulatory affairs leads at biotechnology firms, contract research organization procurement directors, and academic laboratory managers. Secondary validation draws from FDA guidance documents, EMA MDR implementation reports, OECD Test Guideline 471 protocols, and NIH funding disbursement records. Bottom-up reagent volume estimates triangulate against top-down instrument installation base calculations.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models product type, technology platform, end-user segment, and application area dimensions alongside regional regulatory cluster variations. CAGRs derive from segment-specific growth drivers including CRISPR screening workflow expansion, REACH chemical safety assessment mandates, and EMA biosimilar analytical comparability requirements. Forecast inputs incorporate NIH appropriations trajectories, venture capital deployment patterns in Boston and San Diego biotech clusters, and CDSCO biologics pathway development timelines.
Material uncertainties — regulatory guidance revisions, luciferase substrate supply disruptions, and AI image analysis tool adoption rates — sit outside the modeled envelope. Forecasts reflect assumptions about continued FDA and EMA potency assay standardization without anticipating fundamental methodological shifts. Practitioners should keep alternative scenarios live as India's CDSCO standardization timeline and REACH chemical safety assessment enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Southern Blotting Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Liquid Biopsy Market
Biomedical Technology
Europe Proteomics Market
Biomedical Technology
Northern Blotting Market
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
Nucleic Acid Aptamers Market
Biomedical Technology
Automated Cell Biology Systems Market
Biomedical Technology
Global Cell Dissociation Market
Biomedical Technology
Exosomes Market
Biomedical Technology
Cell Analysis Market
Biomedical Technology
Cell Separation Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
Latin America Flow Cytometry Market
Biomedical Technology
Europe Exosome Research Products Market
Biomedical Technology
Austria Flow Cytometry Market