
 Cell Separation Market | 2026-2036
Cell Separation Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Separation Market Intelligence
The EU Medical Device Regulation is restructuring the cost-of-entry calculus for cell separation instrument manufacturers serving European laboratories. Miltenyi Biotec leverages its integrated magnetic bead platform to sustain dominance in automated cell sorting workflows. Thermo Fisher Scientific anchors its position through captive supply of flow cytometry reagents and instruments. BD competes across hospital and pharmaceutical end users with a full portfolio spanning reagents, kits, and analytical hardware.
Cell separation encompasses the isolation of specific cell populations from heterogeneous biological samples using physical, immunological, or microfluidic methods, typically achieving purity thresholds above 95% for downstream genomic or proteomic analysis. Magnetic bead separation leads the technology landscape due to established protocol standardization and scalability, while microfluidics represents the fastest-growing segment as labs miniaturize workflows and reduce sample volumes. Reagents command the largest margin pool within product types because consumable repurchase cycles generate recurring revenue streams that instruments alone cannot match.
The FDA governs cell separation devices used in clinical diagnostics through 510(k) and PMA pathways, while the EPA regulates manufacturing facility emissions for reagent production sites. ISO 13485 certification shapes supplier qualification criteria for pharmaceutical companies integrating separation steps into GMP-compliant cell therapy manufacturing. Stakeholders must monitor evolving cell therapy guidance documents from both FDA and EMA as autologous treatment pipelines expand and drive demand for closed-system separation technologies.
Market Dynamics
The EU Medical Device Regulation is compressing manufacturer margins while academic research institutes accelerate procurement of automated separation platforms, creating a bifurcation between clinical-grade and research-grade supply chains.
Growth Catalysts
- Cell therapy manufacturing:Autologous treatment pipelines at pharmaceutical companies are expanding demand for closed-system separation technologies that meet GMP compliance standards.
- ISO 13485 certification:Supplier qualification criteria for cell therapy manufacturing are standardizing procurement decisions across contract manufacturing organizations.
- Boston biotech cluster:Concentrated venture funding and research infrastructure in Massachusetts is driving instrument deployment density unmatched by other metropolitan regions.
Market Restraints
- Rare earth magnet supply:Neodymium price volatility and Chinese export controls on processed magnetic materials create input cost instability for bead-based separation systems.
- EU MDR conformity assessment:Extended notified body capacity constraints and documentation burdens are delaying product registrations for European market entry.
- Flow cytometry substitution:Multi-parameter cell analysis platforms with integrated sorting functions are capturing budget allocations previously directed to standalone separation instruments.
Strategic Opportunities
- Microfluidics-miniaturization convergence:Labs reducing sample volumes below 100 microliters are creating white space for chip-based separation technologies that magnetic bead platforms cannot address.
- San Diego biotech corridor:Emerging cell therapy startups in Southern California represent underpenetrated demand relative to established Boston and Bay Area clusters.
- Closed-system automation:Regulatory guidance from FDA and EMA on contamination control is mandating hardware upgrades that favor integrated platform vendors.
Industry Challenges
- Cross-functional talent scarcity:Cell separation workflow optimization requires hybrid expertise in immunology, microfluidics engineering, and regulatory affairs that academic training programs rarely produce.
- Legacy instrument integration:Pharmaceutical manufacturers with existing flow cytometry infrastructure face technical friction retrofitting new separation modules into validated quality systems.
- Reagent lot-to-lot variability:Antibody-coated magnetic bead consistency across manufacturing batches complicates protocol standardization for multi-site clinical trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Separation Market |
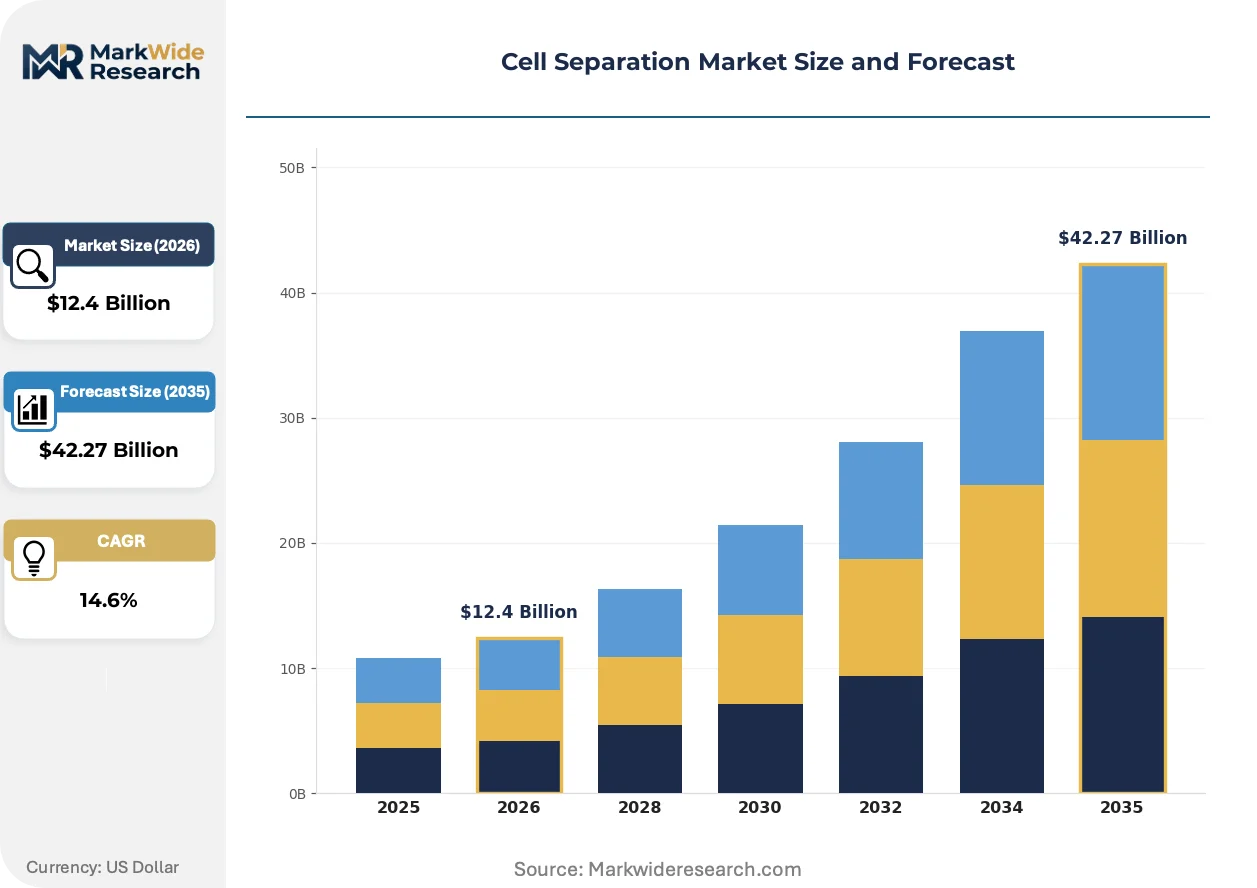
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $42.27 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Magnetic Bead Separation, Filtration, Microfluidics, Flow Cytometry Application: Clinical Diagnostics, Drug Discovery, Stem Cell Research, Cancer Research End User: Academic Research Institutes, Hospitals, Pharmaceutical Companies, Biotechnology Firms Product Type: Cells, Reagents, Instruments, Kits |
| Companies Covered | Miltenyi Biotec, Merck KGaA, Thermo Fisher Scientific, Terumo Corporation, Bio-Rad Laboratories, BD (Becton Dickinson), STEMCELL Technologies, Corning, Danaher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Separation Market Strategic Shifts & Innovations
Workflow miniaturization and regulatory pressure on contamination control are reshaping instrument architecture, while procurement centralization at large research institutions is compressing vendor negotiation cycles.
Microfluidic chip-based separation is overtaking conventional magnetic bead methods in single-cell genomics workflows. Academic core facilities and precision medicine institutes are adopting these platforms to reduce sample input requirements from milliliters to microliters. The technology is overtaking incumbent methods by eliminating centrifugation steps that damage fragile cell populations.
REACH chemical authorization requirements in Europe are restricting fluorophore and surfactant chemistries used in reagent formulations. Manufacturers must reformulate buffer compositions or source alternative compounds to maintain market access. The regulation most impacts reagent suppliers serving clinical diagnostic applications where substance documentation requirements are strictest.
Consolidated procurement at multi-site research institutes is displacing decentralized laboratory purchasing. University of California and Harvard Medical School systems now negotiate enterprise licenses for separation platforms across dozens of affiliated labs. This concentration is most visible in the United States, where National Institutes of Health funding consolidation has centralized capital equipment decisions at institutional cores rather than individual principal investigators.
Cell Separation Market Segmentation
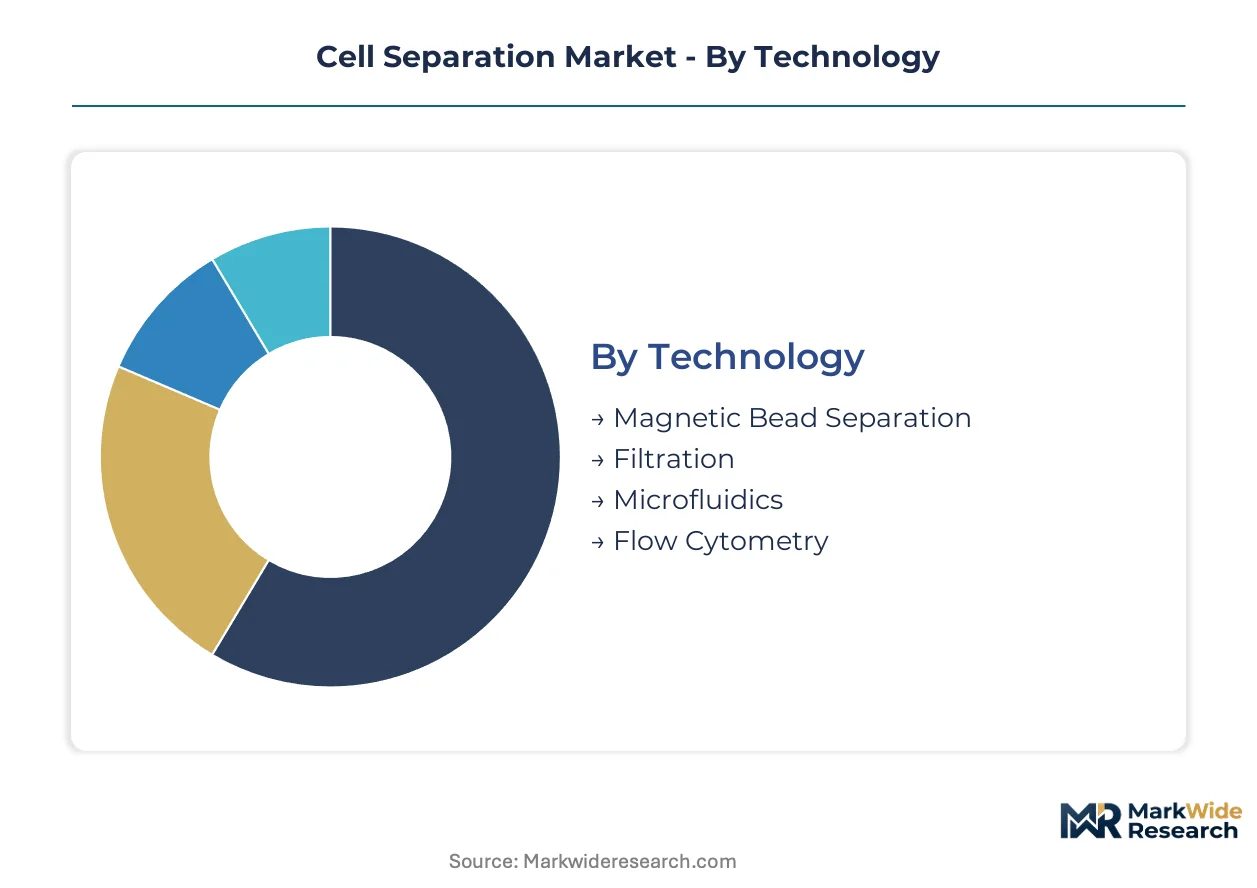
Cell separation workflows fragment across four distinct taxonomies that rarely overlap in procurement decisions. Technology selection locks laboratories into specific reagent ecosystems, while end-user type determines regulatory compliance burdens and capital allocation authority.
Technology:
Customization intensity spans from plug-and-play magnetic platforms to fully bespoke microfluidic architectures requiring cleanroom fabrication partnerships.
- Magnetic Bead Separation:Iron oxide nanoparticles coated with target-specific antibodies enable batch processing of 10^7 cells per run with minimal operator training. Pharmaceutical manufacturing facilities in Germany and Massachusetts standardize on this modality for GMP-compliant cell therapy production, though neodymium supply constraints from Chinese export licensing create raw material vulnerability.
- Microfluidics:Photolithographically etched channels achieve label-free separation via deterministic lateral displacement or inertial focusing, reducing sample volumes below 50 microliters. Precision medicine institutes in Boston and San Diego deploy these systems for single-cell genomics where centrifugation-induced apoptosis compromises downstream RNA integrity.
- Filtration:Membrane-based size exclusion separates cell populations based on physical dimensions rather than surface markers. Academic core facilities favor this approach for primary tissue dissociation where antibody epitope availability is unknown.
- Flow Cytometry:Fluorescence-activated cell sorting combines analytical characterization with physical separation, capturing multi-parameter data during the sort process. Hospital clinical laboratories integrate these platforms for diagnostic immunophenotyping where regulatory validation of antibody panels already exists.
Most installed capacity flows through Magnetic Bead Separation. Expansion is steepest in Microfluidics.
Application:
Volume concentration follows funding allocation patterns across NIH, pharmaceutical R&D budgets, and hospital capital cycles.
- Clinical Diagnostics:FDA-cleared separation workflows isolate circulating tumor cells or fetal cells from maternal blood for non-invasive testing. Hospital networks in the United States concentrate procurement through centralized laboratory service agreements that mandate 510(k)-cleared instrumentation.
- Drug Discovery:High-throughput separation of primary hepatocytes or immune cell subsets supports toxicity screening and target validation. Contract research organizations in the United Kingdom and Switzerland absorb capacity for pharmaceutical clients seeking to externalize cell-based assay development.
- Stem Cell Research:Pluripotent and adult stem cell isolation demands gentle separation protocols preserving colony-forming potential. Academic institutes with dedicated stem cell cores in California and Massachusetts drive instrument specification toward low-shear technologies.
- Cancer Research:Tumor-infiltrating lymphocyte extraction and circulating tumor cell enrichment enable immuno-oncology biomarker studies. Biotechnology firms cluster around the National Cancer Institute-funded research corridors in Maryland and Texas.
Procurement volume concentrates in Clinical Diagnostics. Funding velocity peaks in Cancer Research.
End User:
Buying authority structures diverge sharply between centralized institutional procurement and distributed principal investigator decision-making.
- Academic Research Institutes:Multi-site university systems negotiate enterprise licenses for separation platforms across dozens of affiliated laboratories. The University of California and Harvard Medical School systems have displaced decentralized purchasing with consolidated core facility models.
- Pharmaceutical Companies:Autologous cell therapy manufacturing demands closed-system separation technologies meeting FDA and EMA contamination control guidance. Novartis and Bristol Myers Squibb facilities in New Jersey and Massachusetts anchor demand for GMP-validated instrumentation.
- Hospitals:Clinical diagnostic applications require FDA-cleared devices with established quality control protocols. Hospital network consolidation in the United States has shifted purchasing authority to regional laboratory directors rather than individual pathologists.
- Biotechnology Firms:Emerging cell therapy startups in San Diego and Cambridge lack capital for full GMP suites, creating demand for flexible research-grade platforms with upgrade pathways. Venture-funded companies prioritize speed-to-clinic over regulatory completeness in initial procurement.
Revenue concentration sits with Pharmaceutical Companies. Account expansion rates are highest in Biotechnology Firms.
Product Type:
Margin architecture inverts between capital equipment with long replacement cycles and consumables with quarterly repurchase obligations.
- Reagents:Antibody-coated magnetic beads and fluorescent labels generate recurring revenue streams through lot-to-lot consistency requirements that lock laboratories into single-supplier relationships. REACH chemical authorization in Europe now restricts fluorophore chemistries, forcing reformulation investments.
- Instruments:Automated separation platforms command six-figure price points with seven-to-ten-year depreciation schedules. ISO 13485 certification shapes supplier qualification for pharmaceutical manufacturing integration.
- Kits:Pre-formulated buffer and bead combinations reduce protocol development time for non-specialist laboratories. Academic core facilities favor kit-based workflows to minimize training burden for rotating graduate students.
- Cells:Isolated primary cell populations and cell lines serve as both separation inputs and downstream products for contract manufacturing organizations. Cryopreserved cell inventories require cold chain logistics that concentrate supply in regions with established biobank infrastructure.
Margin capture concentrates in Reagents. Revenue expansion is accelerating fastest in Kits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized workforce concentrations in cell biology and microfluidics engineering anchor geographic demand patterns across major biopharma clusters. Talent pipelines from MIT, Stanford, and ETH Zurich feed directly into regional instrument development ecosystems. Regulatory divergence between FDA and EMA pathways shapes where manufacturers prioritize clinical-grade product launches.
United States
FDA 510(k) clearance pathways and PMA requirements govern clinical diagnostic instrument deployments across hospital networks. The Boston biotech cluster concentrates venture-funded cell therapy startups demanding GMP-compliant closed-system separation platforms. San Diego's emerging corridor attracts precision medicine institutes miniaturizing workflows below 100 microliters.
Germany
EU Medical Device Regulation conformity assessments and notified body capacity constraints delay product registrations for European market entry. Baden-Württemberg hosts pharmaceutical manufacturing facilities standardizing on magnetic bead modalities for autologous cell therapy production. REACH chemical authorization requirements force reagent reformulation investments for fluorophore-dependent workflows.
China
NMPA medical device registration rules and dual carbon goals reshape manufacturing facility emissions compliance for reagent production sites. Yangtze River Delta biopharma parks attract domestic cell therapy developers seeking localized supply chains. Shanghai-based contract research organizations absorb capacity for international pharmaceutical clients externalizing assay development.
Switzerland
Swissmedic guidance on contamination control and ISO 13485 certification standards shape supplier qualification for GMP-compliant manufacturing. Basel anchors demand from Novartis facilities requiring validated instrumentation integration. Zurich precision medicine institutes drive adoption of microfluidic platforms preserving fragile cell populations during single-cell genomics workflows.
United Kingdom
MHRA post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment burdens for instrument manufacturers. London-Southeast research corridors concentrate academic core facilities negotiating enterprise licenses across multi-site university systems. Oxford-Cambridge biotech clusters prioritize speed-to-clinic procurement over regulatory completeness in initial platform selection.
Cell Separation Market Key Industry Players
The competitive structure tilts toward integrated platform vendors commanding captive reagent ecosystems. Market concentration reflects high switching costs between magnetic bead and microfluidic technology modalities. Three archetypes dominate: diversified life science conglomerates with captive supply chains, specialized magnetic bead platform developers, and emerging microfluidic chip fabricators. Competitive moves center on strategic partnerships for cleanroom fabrication capacity and portfolio diversification into closed-system automation.
Among Germany-based platform developers, Miltenyi Biotec and Merck KGaA occupy positions anchoring the magnetic bead technology vector. Thermo Fisher Scientific represents the diversified conglomerate archetype with integrated flow cytometry and reagent supply chains. These three entities exemplify how geographic proximity to pharmaceutical manufacturing clusters in Massachusetts and Baden-Württemberg shapes competitive positioning.
| Leading Market Players |
|---|
| Miltenyi Biotec |
| Merck KGaA |
| Thermo Fisher Scientific |
| Terumo Corporation |
| Bio-Rad Laboratories |
| BD (Becton Dickinson) |
| STEMCELL Technologies |
| Corning |
| Danaher |
| Others |
Cost & Logistics Intelligence
Pharmaceutical manufacturing facilities in New Jersey and Massachusetts concentrate procurement authority for GMP-validated separation platforms, anchoring a contract-based pricing model where multi-year service agreements bundle instruments, reagents, and validation support into single negotiated packages.
Pricing Analysis
Bundled service contracts dominate enterprise procurement while unbundled transactional purchases persist in academic settings. Pricing stratifies across premium GMP-certified systems, standard research-grade platforms, and economy-tier refurbishment programs. Cost compression in the economy tier is intensifying because Chinese magnetic bead suppliers are penetrating Western markets with lower-cost alternatives. Academic core facilities exhibit highest price sensitivity, whereas pharmaceutical autologous therapy manufacturers prioritize compliance over unit cost.
Supply Chain Analysis
Direct-to-pharmaceutical channels handle hyperscale buyer demand for closed-system automation, while distributor networks serve fragmented academic laboratories. Manufacturing concentrates in Germany, the United States, and China. Neodymium magnet supply draws from Chinese processing facilities, antibody production rests on mammalian cell culture capacity in North America and Europe, and microfluidic chip fabrication centers on cleanroom partnerships in Massachusetts and Baden-Württemberg. Single-source vulnerability in rare earth magnet supply creates structural exposure to export licensing disruptions. Distribution runs through specialized life science distributors with field application scientist support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell separation functions as a stable compounder anchored by recurring reagent consumption cycles that outpace instrument replacement demand, with autologous cell therapy manufacturing expansion providing durable top-line support.
For Market Incumbents: Deploy captive reagent ecosystems to lock pharmaceutical customers into multi-year consumable contracts. Magnetic bead platform developers must secure alternative neodymium supply agreements outside Chinese export controls. Incumbents should accelerate ISO 13485 certification investments to preempt EU MDR compliance gaps that emerging microfluidic competitors exploit. For New Entrants and Emerging Players: Contract research organizations represent the most accessible channel partner type for microfluidic chip-based platforms lacking established brand recognition. San Diego biotechnology startups offer underpenetrated white space relative to saturated Boston and Bay Area clusters. Single-cell genomics workflows present the most penetrable application segment, with chip-based separation displacing centrifugation-damaged samples. For Investors and Strategic Acquirers: Diversified life science conglomerates are the most active acquirer in this space, seeking microfluidic capabilities to complement magnetic bead portfolios. The investment horizon reads as favorable for platforms with regulatory clearance pathways in both FDA and EMA jurisdictions. Watch for FDA draft guidance on closed-system contamination control as the inflection signal accelerating pharmaceutical upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Fabrication Partnership | Microfluidic chip suppliers secure capacity with MIT-adjacent foundries to meet precision medicine institute demand. |
| Reagent Portfolio Diversification | Magnetic bead vendors expand antibody coating chemistries to address REACH-restricted fluorophore formulations. |
| GMP Validation Pathway Investment | Research-grade platform developers pursue ISO 13485 certification to access Novartis and Bristol Myers Squibb facilities. |
| Enterprise License Negotiation | Instrument manufacturers structure multi-site agreements with University of California and Harvard Medical School systems. |
| Closed-System Automation Development | Hardware vendors integrate separation modules with contamination control features mandated by FDA and EMA guidance. |
Research Approach
Bottom-up pharmaceutical and academic procurement modeling reconciled against top-down instrument shipment tracking forms the analytical core. Primary interviews with biomedical engineers, GPO contracts managers, cell therapy manufacturing directors, and core facility directors combined with secondary validation from FDA 510(k) filings, EMA MDR submissions, NIH RePORTER funding databases, and hospital procurement records. Triangulation between demand-side capital allocation patterns and supply-side manufacturing capacity data ensures cross-verification.
Historical trendline analysis of magnetic bead and microfluidic platform deployments established baseline penetration rates across the projection horizon. Segmentation dimensions modeled include technology modality, regulatory certification tier, end-user type, and geographic biotech cluster concentration. CAGRs were derived from fitted growth curves adjusted for EU MDR implementation delays and cell therapy pipeline expansion trajectories. Forecast inputs incorporate neodymium price volatility indices and academic NIH funding allocation shifts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese rare earth export policy and FDA guidance timing on closed-system requirements. Projections reflect assumptions regarding sustained autologous therapy investment and stable regulatory pathways. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Global Ligation Market
Biomedical Technology
Ontogenetic Market
Biomedical Technology
Bone Marrow Aspirate Concentrates (BMAC) Market
Biomedical Technology
Rat and Mouse Model Market
Biomedical Technology
France Flow Cytometry Market
Biomedical Technology
America Cell Counting Market
Biomedical Technology
Global Neuroscience Antibodies and Assays Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
Multiplex Biomarker Imaging Market
Biomedical Technology
Global Plant Stem Cell Market
Biomedical Technology
Pyrosequencing Market
Biomedical Technology
Digital Biology Market
Biomedical Technology
Global Organoids Market
Biomedical Technology
Blood Brain Barrier Technologies Market
Biomedical Technology
Cell Cryopreservation Market