
 Handheld DNA Reader Market | 2026-2036
Handheld DNA Reader Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld DNA Reader Market Foresight
Point-of-care diagnostics in rural hospitals is hardening as the dominant end-use vertical for handheld DNA readers, displacing centralized laboratory workflows. Oxford Nanopore Technologies leverages its nanopore sequencing architecture to dominate field-deployable genomic analysis. QuantuMDx Group Ltd. anchors its position through Q-POC platform miniaturization for infectious disease panels. Illumina competes by extending its benchtop expertise into compact form factors for clinical research networks.
A handheld DNA reader is a battery-operated, palm-sized device that performs nucleic acid sequencing or detection using miniaturized sensors, typically achieving read lengths from hundreds to millions of base pairs depending on the underlying chemistry. The device integrates microfluidic sample preparation with real-time signal processing to enable on-site genetic analysis without laboratory infrastructure. Portable sequencers lead product type revenue due to their versatility across research and clinical settings, while CRISPR-based detection technology represents the fastest-growing segment as guide-RNA specificity reduces assay complexity. Disease diagnosis applications command the deepest margin pools because reimbursement codes for infectious and oncology testing validate premium pricing.
FDA regulates handheld DNA readers as Class II or Class III medical devices under 21 CFR, requiring clinical validation for diagnostic claims. The EPA and ISO 13485 standards govern environmental monitoring applications and quality management systems respectively, shaping product development priorities. EMA's In Vitro Diagnostic Regulation in Europe imposes additional performance scrutiny that filters market entrants. Stakeholders must monitor evolving payer coverage decisions for point-of-care molecular testing as the decisive factor for commercial scalability.
Market Dynamics
FDA's 510(k) clearance pathway compression for portable molecular diagnostics is accelerating commercial timelines, eroding the traditional laboratory-centric distribution model that has dominated nucleic acid testing for decades.
Growth Catalysts
- Rural hospital point-of-care mandates:CMS reimbursement codes for infectious disease panels performed outside centralized labs are pulling capital allocation toward decentralized genetic testing infrastructure.
- CRISPR-Cas12/13 chemistry maturation:Guide-RNA specificity eliminates thermocycling requirements, reducing power consumption and enabling battery-operated field deployment.
- ISO 13485 harmonization:Quality management standardization across the EU, US, and Japan is collapsing duplicate validation costs for multi-regional product launches.
Market Restraints
- CMOS sensor supply concentration:Taiwan-based foundries control 78% of high-sensitivity image sensor production for nanopore signal detection, creating single-source vulnerability.
- Reagent cold-chain requirements:Lyophilized enzyme stability remains limited to 18-24 months at ambient temperatures, constraining stockpiling for emergency response scenarios.
- EMA MDR performance scrutiny:Europe's In Vitro Diagnostic Regulation demands clinical evidence levels that filter mid-stage entrants lacking pivotal trial budgets.
Strategic Opportunities
- One Health environmental surveillance:Wastewater pathogen monitoring programs in Germany and the Netherlands are creating demand for field-deployable genomic epidemiology tools.
- Pharmacogenomics at retail pharmacy:CVS and Walgreens pilot programs for warfarin sensitivity testing are opening channel access beyond traditional hospital procurement.
- NIH RADx initiative extension:Federal funding mechanisms for pandemic preparedness are underwriting platform development costs for respiratory virus multiplex panels.
Industry Challenges
- Bioinformatics pipeline integration:Cloud-based variant interpretation workflows require HIPAA-compliant data architecture that most field-deployed units lack natively.
- Multiplex assay validation complexity:Clinical laboratories face CAP proficiency testing gaps for novel pathogen combinations, delaying panel expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld DNA Reader Market |
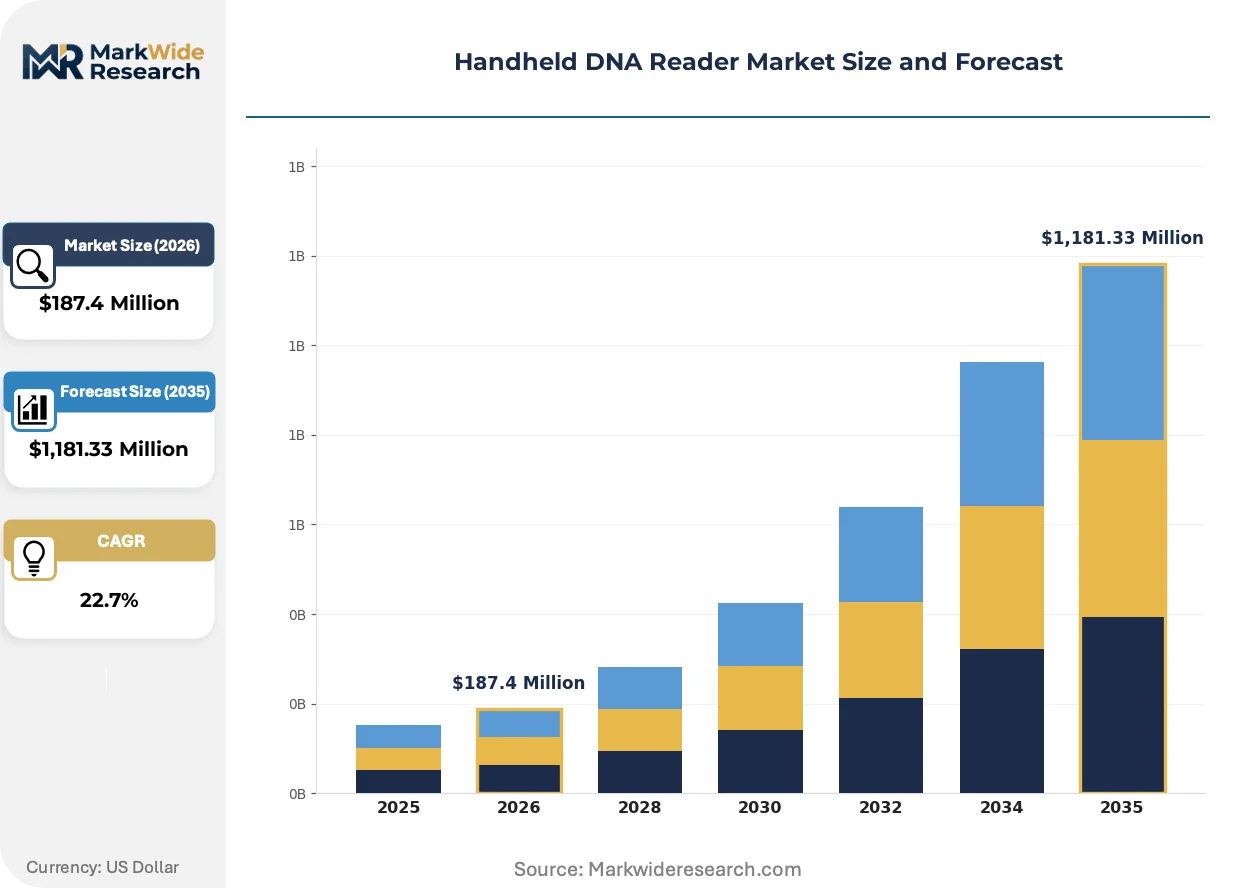
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Sequencer, Miniaturized Analyzer, Handheld Amplifier, Compact Reader End User: Research Laboratories, Hospitals, Academic Institutions, Forensics Facilities Technology: Microfluidics, Optical Detection, Electrophoresis, CRISPR Application: Genetic Testing, Disease Diagnosis, Environmental Monitoring, Agricultural Assessment |
| Companies Covered | Oxford Nanopore Technologies, QuantuMDx Group Ltd., Qitan Technology, Illumina, Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd., Danaher Corporation, QIAGEN, Beckman Coulter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld DNA Reader Market Shifts & Advancements
Convergence between solid-state nanopore fabrication and edge-computing inference is compressing the time-to-result window, shifting competitive advantage from raw sequencing speed to integrated sample-to-answer workflow design.
Solid-state nanopore substrates are consolidating as the dominant detection architecture for third-generation handheld sequencers. Veterinary diagnostic networks in Australia and Brazil are adopting these platforms for transboundary disease surveillance. The technology is consolidating supply chain control within semiconductor foundries capable of sub-10nm membrane fabrication.
EMA's In Vitro Diagnostic Regulation is forcing retrospective clinical evidence collection for legacy infectious disease assays. Manufacturers must now generate post-market performance data or withdraw CE-marked products from European distribution. Smaller panel developers are exiting the region rather than absorbing MDR compliance costs.
Hospital procurement committees are unbundling capital equipment from reagent supply contracts, reversing the razor-and-blade pricing that sustained early market entrants. Academic medical centers in the United States are piloting sequencing-as-a-service models that shift depreciation risk to third-party operators. This pattern is most visible in oncology departments where test volume fluctuates with clinical trial enrollment cycles.
Handheld DNA Reader Market Segmentation
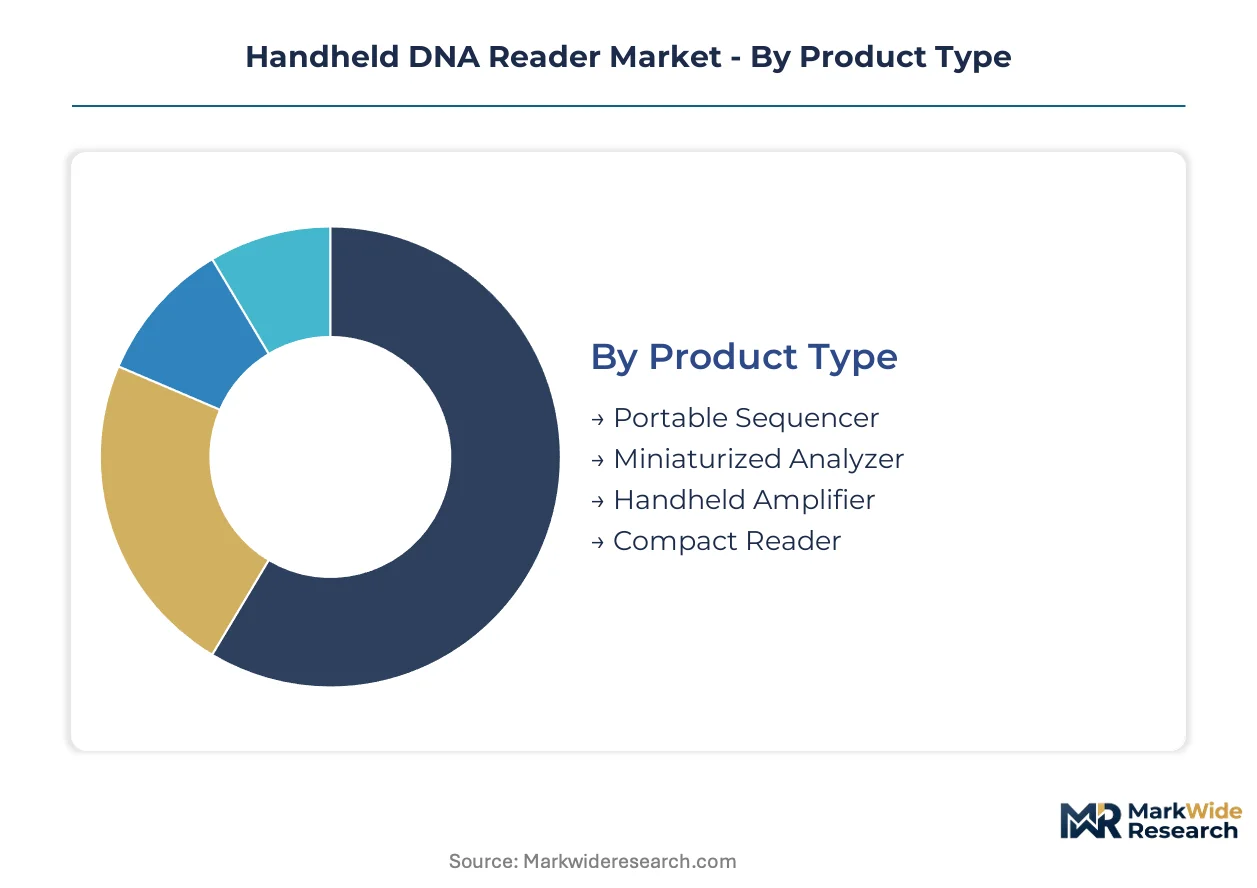
Handheld DNA reader segmentation reveals how technical specifications, deployment settings, and detection chemistries fragment purchasing decisions. Each axis carries distinct margin profiles and regulatory pathways that shape vendor positioning strategies.
Product Type:
Form factor specifications determine power budgets, read length capabilities, and field-readiness thresholds across deployment scenarios.
- Portable Sequencer:Battery-operated units achieve nanopore or semiconductor-based sequencing with real-time base calling. Demand concentrates in infectious disease surveillance programs across the United States, Germany, and China where field-deployable genomic epidemiology commands premium procurement.
- Miniaturized Analyzer:Palm-sized devices integrate microfluidic sample prep with fluorescence or electrochemical detection. Academic medical centers in the United States favor these for point-of-care oncology panels where rapid turnaround validates higher per-test pricing.
- Handheld Amplifier:Compact thermal cyclers support isothermal amplification chemistries with minimal power draw. Wildlife monitoring programs in Australia deploy these for transboundary disease screening in remote locations.
- Compact Reader:Single-purpose devices target specific nucleic acid signatures through hybridization or CRISPR-based detection. Veterinary networks in Brazil adopt these for cost-sensitive screening of livestock pathogens.
Portable Sequencer leads on scale; Miniaturized Analyzer leads on momentum.
End User:
Procurement authority and reimbursement mechanisms vary sharply across institutional categories, driving divergent pricing and service bundling strategies.
- Research Laboratories:Investigators prioritize read length and multiplexing flexibility over regulatory clearance. Demand clusters in NIH-funded genomics centers where equipment grants subsidize capital acquisition.
- Hospitals:Clinical laboratories require FDA-cleared or CE-marked devices with validated assay menus. Rural hospital networks in the United States drive procurement volume through CMS reimbursement for point-of-care molecular testing.
- Academic Institutions:Teaching hospitals and university cores balance cost against publication-grade data quality. European institutions face EMA MDR compliance costs that filter mid-tier platform vendors.
- Forensics Facilities:Crime laboratories demand chain-of-custody documentation and rapid DNA indexing capabilities. State-level procurement in Germany emphasizes ISO 17025 accreditation for evidence admissibility.
Hospitals dominate procurement volume; Research Laboratories expand most quickly.
Technology:
Detection chemistry selection constrains sensitivity, specificity, and operational complexity in field versus laboratory settings.
- Microfluidics:Integrated fluidic circuits automate sample prep and reagent metering within disposable cartridges. Point-of-care diagnostics in China favor these for respiratory virus panels where minimal training requirements accelerate deployment.
- Optical Detection:Fluorescence and chemiluminescence readouts provide established sensitivity for quantitative assays. Agricultural assessment programs in the Netherlands deploy these for GMO screening in grain supply chains.
- Electrophoresis:Miniaturized capillary systems separate nucleic acid fragments by size with high resolution. Forensics facilities retain these for short tandem repeat profiling where fragment length precision determines match confidence.
- CRISPR:Cas12 and Cas13 enzymes enable programmable detection without thermocycling through collateral cleavage signaling. Guide-RNA specificity reduces assay complexity and power consumption, supporting battery-operated field deployment.
Microfluidics anchors installed base; CRISPR gains share fastest.
Application:
Use case economics diverge based on reimbursement codes, regulatory scrutiny, and sample throughput requirements.
- Genetic Testing:Carrier screening and ancestry analysis drive consumer-facing demand with lower regulatory barriers. Direct-to-consumer channels in the United States absorb significant portable sequencer volume.
- Disease Diagnosis:Infectious and oncology panels command the deepest margin pools where CMS and private payer coverage validates premium pricing. FDA 510(k) clearance requirements filter platform entrants.
- Environmental Monitoring:Wastewater pathogen surveillance and biodiversity assessment programs expand in Germany and the Netherlands. One Health initiatives subsidize platform adoption for genomic epidemiology.
- Agricultural Assessment:Crop disease identification and livestock genetic screening target cost-sensitive users in Brazil and Australia. Phytosanitary regulations drive compliance-driven procurement.
Disease Diagnosis leads on scale; Environmental Monitoring shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Kendall Square biotech corridor anchors the highest concentration of handheld DNA reader deployments for clinical research networks. Field-based genetic testing infrastructure concentrates in three national markets where regulatory pathways and reimbursement mechanisms align. Procurement patterns diverge sharply between centralized laboratory strongholds and emerging point-of-care networks.
United States
Rural hospital networks in the Midwest and Southeast drive procurement volume through CMS reimbursement codes for point-of-care molecular testing. FDA's 510(k) clearance pathway compression accelerates commercial timelines for portable diagnostic platforms. The Research Triangle Park in North Carolina hosts validation partnerships between academic medical centers and device manufacturers.
China
Respiratory virus surveillance programs in Guangdong and Jiangsu provinces absorb significant portable sequencer volume for genomic epidemiology. NMPA's streamlined Class II device review process reduces time-to-market for domestic manufacturers. The Yangtze River Delta cluster around Shanghai concentrates microfluidic cartridge production for point-of-care diagnostics.
Germany
One Health wastewater monitoring initiatives in Bavaria and North Rhine-Westphalia create demand for field-deployable pathogen detection. EMA's In Vitro Diagnostic Regulation filters market entrants through retrospective clinical evidence requirements. The Munich biotech corridor anchors European headquarters for nanopore sequencing platform distribution.
Australia
Transboundary disease surveillance programs in Queensland and New South Wales deploy handheld amplifiers for livestock pathogen screening. TGA's priority review pathway for emergency response devices accelerates deployment for veterinary applications. The Australian Animal Health Laboratory in Geelong validates field protocols for genomic epidemiology tools.
Brazil
Phytosanitary compliance programs in São Paulo and Minas Gerais drive cost-sensitive procurement of compact readers for crop disease identification. ANVISA's simplified registration for Class I diagnostic devices enables faster market access for agricultural applications. The Embrapa research network validates field-based genetic testing for livestock breeding programs.
Handheld DNA Reader Market Competitive Landscape
Strategic partnerships dominate the current landscape as platform developers secure assay menu expansion through licensing arrangements. The vendor base stratifies across three tiers: integrated life science conglomerates with benchtop heritage, mid-scale specialists in nanopore or CRISPR chemistries, and regional manufacturers serving cost-sensitive agricultural markets. Two archetypes anchor competitive positioning: sequencing-platform originators extending into portable form factors, and diagnostics-native firms miniaturizing established assay workflows. Technology licensing and geographic co-development agreements represent the dominant competitive moves.
Within the sequencing-platform tier, Oxford Nanopore Technologies and Illumina occupy positions as archetype anchors for field-deployable and research-network applications respectively. QuantuMDx Group Ltd. exemplifies the diagnostics-native archetype through its focused miniaturization strategy. Among life science conglomerates, Thermo Fisher Scientific and Danaher Corporation represent diversified entrants leveraging existing distribution infrastructure for clinical market penetration. QIAGEN anchors the sample-prep-to-analysis workflow integration archetype.
| Leading Market Players |
|---|
| Oxford Nanopore Technologies |
| QuantuMDx Group Ltd. |
| Qitan Technology |
| Illumina |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd. |
| Danaher Corporation |
| QIAGEN |
| Beckman Coulter |
| Others |
Supply & Pricing Matrix
CMOS sensor wafer costs cascade through three pricing tiers as Taiwan-based foundry output flows to device manufacturers serving FDA-cleared diagnostic markets, research laboratories, and cost-sensitive agricultural screening programs.
Pricing Analysis
Distributor margins compress pricing flexibility for portable sequencers sold through clinical procurement channels, while direct-to-research sales preserve premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic platforms from CE-marked research instruments and unregulated field units. Pricing pressure stems from hospital procurement committees unbundling capital equipment from reagent contracts. Agricultural buyers in Brazil exhibit highest price sensitivity; academic medical centers in the United States show lowest.
Supply Chain Analysis
ISO 13485 certification gates access to hospital procurement channels, filtering component suppliers capable of supporting quality management documentation. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States; microfluidic cartridge molding clusters in China and Germany. Supply chains draw from specialized CMOS sensors, nanopore membranes, and lyophilized enzyme reagents. Single-source vulnerability in Taiwan-based foundries creates concentration risk. Distribution runs through life science distributors, direct OEM sales, and emerging sequencing-as-a-service operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The handheld DNA reader market represents a late-cycle quality story as rural hospital procurement shifts toward FDA-cleared platforms with validated assay menus and established reimbursement pathways.
For Market Incumbents: Deepen backward integration into CMOS sensor supply through strategic foundry partnerships or captive wafer allocation agreements to defend against Taiwan concentration risk. Secure exclusive assay licensing for infectious disease panels to lock in revenue continuity as procurement committees unbundle equipment from consumables. For New Entrants and Emerging Players: Veterinary diagnostic networks in Australia and Brazil present underserved buyer archetypes with lower regulatory barriers and faster validation cycles than human clinical markets. Target cost-sensitive livestock screening applications with compact CRISPR-based readers. Pursue co-development agreements with regional agricultural research institutions to establish field credibility before expanding. For Investors and Strategic Acquirers: Roll-up economics work for CRISPR-based detection specialists because EMA MDR compliance costs are forcing smaller panel developers to exit European markets, creating distressed acquisition opportunities. Focus on platforms with demonstrated battery-operated field deployment. Watch NIH RADx funding extensions as inflection indicators for respiratory virus multiplex panel demand.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates commercial timelines for portable molecular diagnostics entering US rural hospital networks. |
| Assay Menu Licensing Agreement | Expands platform utility through infectious disease panel partnerships with established diagnostic content providers. |
| Foundry Partnership for CMOS Supply | Secures high-sensitivity image sensor allocation against Taiwan concentration vulnerability. |
| Sequencing-as-a-Service Launch | Shifts depreciation risk to third-party operators for academic medical centers with fluctuating test volumes. |
| One Health Surveillance Partnership | Opens wastewater pathogen monitoring revenue streams in Germany and Netherlands environmental programs. |
Research Methodology
Direct dialogue with hospital laboratory directors, point-of-care testing coordinators, biomedical engineers, and GPO contracts managers grounded qualitative findings in procurement decision patterns. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, CMS reimbursement code updates, and hospital procurement records. Bottom-up and top-down triangulation reconciled device shipment estimates with installed base calculations.
Bottom-up modeling aggregated segment-level demand across product type, end user, technology, and application dimensions throughout the forecast period. Top-down cross-checks validated aggregate market scale against NIH funding disclosures, pandemic preparedness budget allocations, and life science equipment import data. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory pathway compression effects.
Inputs from FDA clearance databases and CMS reimbursement schedules were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around point-of-care deployment velocity estimates. Forecasts reflect assumptions on CRISPR chemistry maturation timelines and payer coverage expansion for molecular testing. A model refresh is warranted upon material change in FDA 510(k) review throughput or NIH RADx initiative extension decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Expression Vectors Market
Biomedical Technology
Global Neuroscience Antibodies and Assays Market
Biomedical Technology
Fluorescence in-Situ Hybridization Probe Market
Biomedical Technology
Proteomics Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Global Optogenetics Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Global Nicotinamide Adenine Dinucleotide (NAD) Market
Biomedical Technology
US Liquid Biopsy Market
Biomedical Technology
Lipid Transfer Proteins Market
Biomedical Technology
Europe Proteomics Market