
 In Vitro Protein Expression Market | 2026-2036
In Vitro Protein Expression Market Size, Share, and Industry Trends Forecast 2026-2036
In Vitro Protein Expression Market Outlook
German bioprocessing equipment suppliers is hardening capacity constraints for high-purity reagent-grade raw materials. Thermo Fisher Scientific leverages its vertically integrated supply chain from plasmid synthesis to finished expression kits. Merck KGaA anchors European demand through its dominance in GMP-compliant cell-free lysate production. Bio-Rad Laboratories competes on instrumentation-integrated workflows that shorten optimization cycles for contract research users.
In vitro protein expression comprises cell-free and cell-based systems that synthesize functional proteins outside living organisms using purified RNA polymerases, ribosomes, and energy-regeneration enzymes in buffered reactions, typically yielding microgram-to-milligram quantities within hours for structural biology and therapeutic candidate validation. Expression systems command the largest revenue pool due to recurring kit purchases, while cell-free technology leads growth trajectory because of its open-reaction architecture enabling non-natural amino acid incorporation and toxic protein production impossible in live cells. Services segment margins concentrate in custom construct design and high-throughput screening contracts where pharmaceutical clients outsource entire validation pipelines.
FDA oversight of cell-derived reagents used in diagnostic assays shapes purity documentation requirements, while EMA's ATMP classification guidelines influence how gene therapy developers qualify expression-derived viral vector components. ISO 13485 certification pressures kit manufacturers serving IVD clients to implement batch-release traceability systems. Stakeholders must monitor evolving pharmacopeial standards for endotoxin limits in cell-free lysates as regulatory convergence between US and European compendia tightens qualification thresholds for clinical-grade material.
Market Dynamics
Continuous-flow microfluidic reactor technology is compressing reaction volumes from milliliter to microliter scales while tightening yield consistency, forcing kit manufacturers to redesign consumable architectures around cartridge-based formats.
Growth Catalysts
- NIH Funding Priorities:The National Institutes of Health directs substantial grant capital toward rapid therapeutic protein screening platforms, accelerating cell-free system adoption among academic structural biology labs.
- Non-Natural Amino Acid Incorporation:Open-reaction cell-free architectures enable site-specific incorporation of synthetic amino acids impossible in living cells, expanding addressable protein design space for antibody-drug conjugate developers.
- Boston-San Diego CRO Clustering:Dense contract research organization concentration along these coastal corridors generates localized demand spikes for high-throughput expression validation services.
Market Restraints
- GMP-Compliant Lysate Scarcity:European supply of clinical-grade cell-free lysates concentrates among a handful of German producers, creating single-source vulnerability for viral vector component manufacturers.
- Endotoxin Documentation Burden:
- Live Cell Substitution:CHO and HEK293 transient expression systems retain cost advantages for milligram-to-gram protein quantities, limiting cell-free penetration in downstream bioprocessing.
Strategic Opportunities
- India CDMO Expansion:Contract development and manufacturing organizations in Hyderabad and Bangalore seek cell-free platforms to bypass biosafety level containment requirements for toxic protein classes.
- ISO 13485-Certified Kit Channels:In vitro diagnostic manufacturers face batch-release traceability mandates, opening premium positioning for expression system suppliers with certified quality management systems.
- AI-Assisted Construct Design:Machine learning tools for codon optimization and solubility prediction are converging with automated liquid handling, collapsing optimization cycles from weeks to days.
Industry Challenges
- Cell-Free Biochemistry Expertise Gap:Fewer than two hundred academic labs worldwide maintain deep competency in lysate preparation and energy system tuning, constraining talent pipelines for commercial scale-up.
- Plasmid Supply Chain Reconfiguration:GMP-grade plasmid DNA for therapeutic applications requires dedicated manufacturing suites, forcing expression kit vendors to qualify alternative raw material sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Vitro Protein Expression Market |
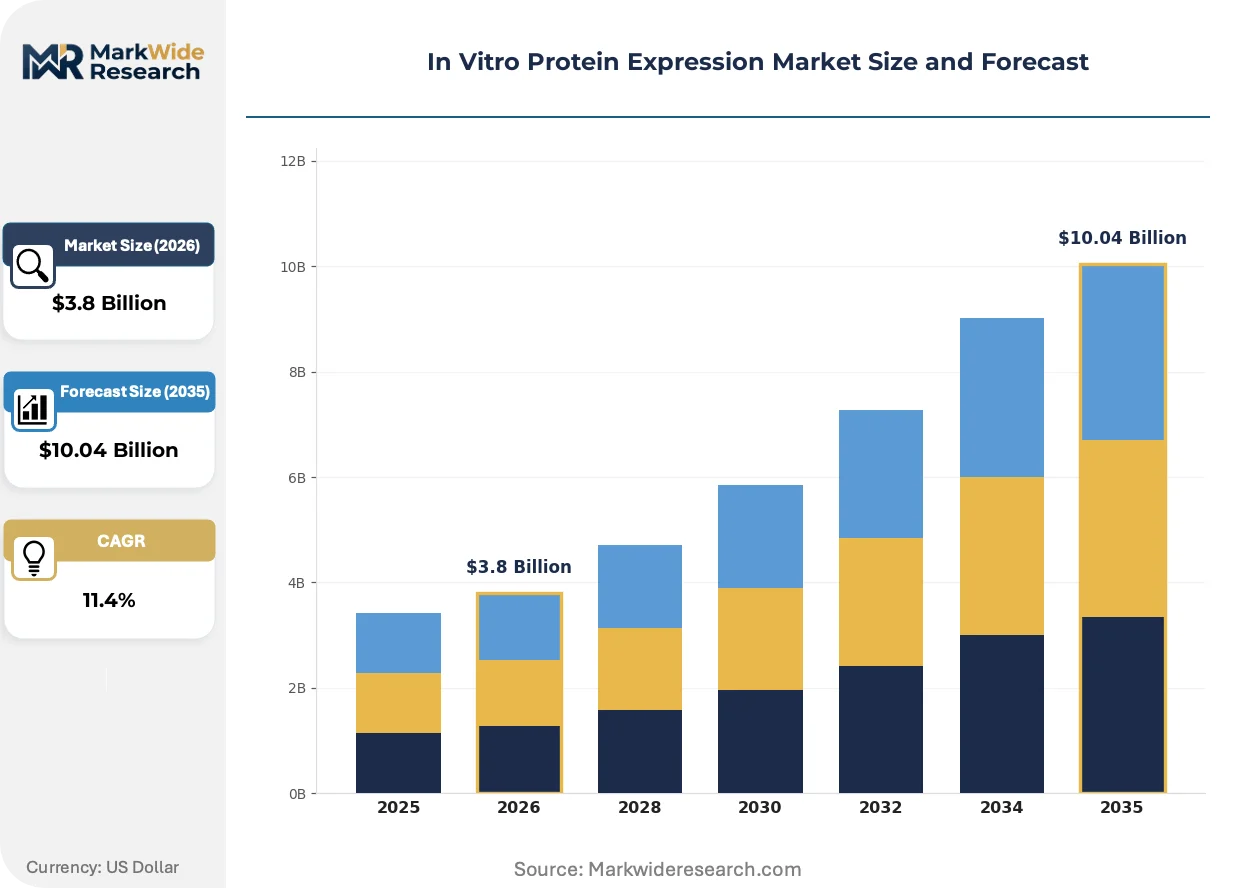
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Expression Systems, Kits, Reagents, Services Application: Drug Development, Vaccine Production, Gene Therapy, Diagnostics Technology: Cell-free Systems, Microbial Systems, Mammalian Systems, Yeast Systems End User: Biotechnology Companies, Pharmaceutical Companies, Academic Institutions, Research Organizations |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Bio-Rad Laboratories, Agilent Technologies, Promega Corporation, New England Biolabs, QIAGEN, Lonza, Takara Bio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Vitro Protein Expression Market Strategic Shifts
Microfluidic integration and artificial intelligence are compressing design-build-test cycles for protein engineering, while regulatory convergence between US and European pharmacopeia tightens material qualification standards.
Continuous-flow microfluidic reactors with integrated real-time monitoring are modularizing the protein expression workflow into discrete, automatable unit operations. Pharmaceutical discovery groups at major biopharmaceutical firms now specify droplet-based or chip-based systems for primary screening campaigns. This modularity is modularizing the vendor landscape itself, enabling point-solution specialists to capture value previously concentrated in integrated kit suppliers.
EMA's evolving ATMP classification guidelines for gene therapy components are forcing expression-derived viral vector manufacturers to re-validate cell-free lysate sourcing against tightened endotoxin and residual DNA specifications. The industrial consequence is a bifurcation between research-grade and clinical-grade material streams, with the latter commanding three-fold pricing premiums. European viral vector developers are responding by locking multi-year supply agreements with GMP-certified lysate producers.
Biopharmaceutical procurement teams are consolidating expression service contracts under platform agreements that bundle construct design, high-throughput screening, and downstream analytics. This purchasing concentration is displacing transactional project-by-project engagement with contract research organizations. The shift is most visible in the United States, where top-twenty pharmaceutical firms now maintain preferred vendor panels of fewer than five cell-free service providers.
In Vitro Protein Expression Market Segmentation
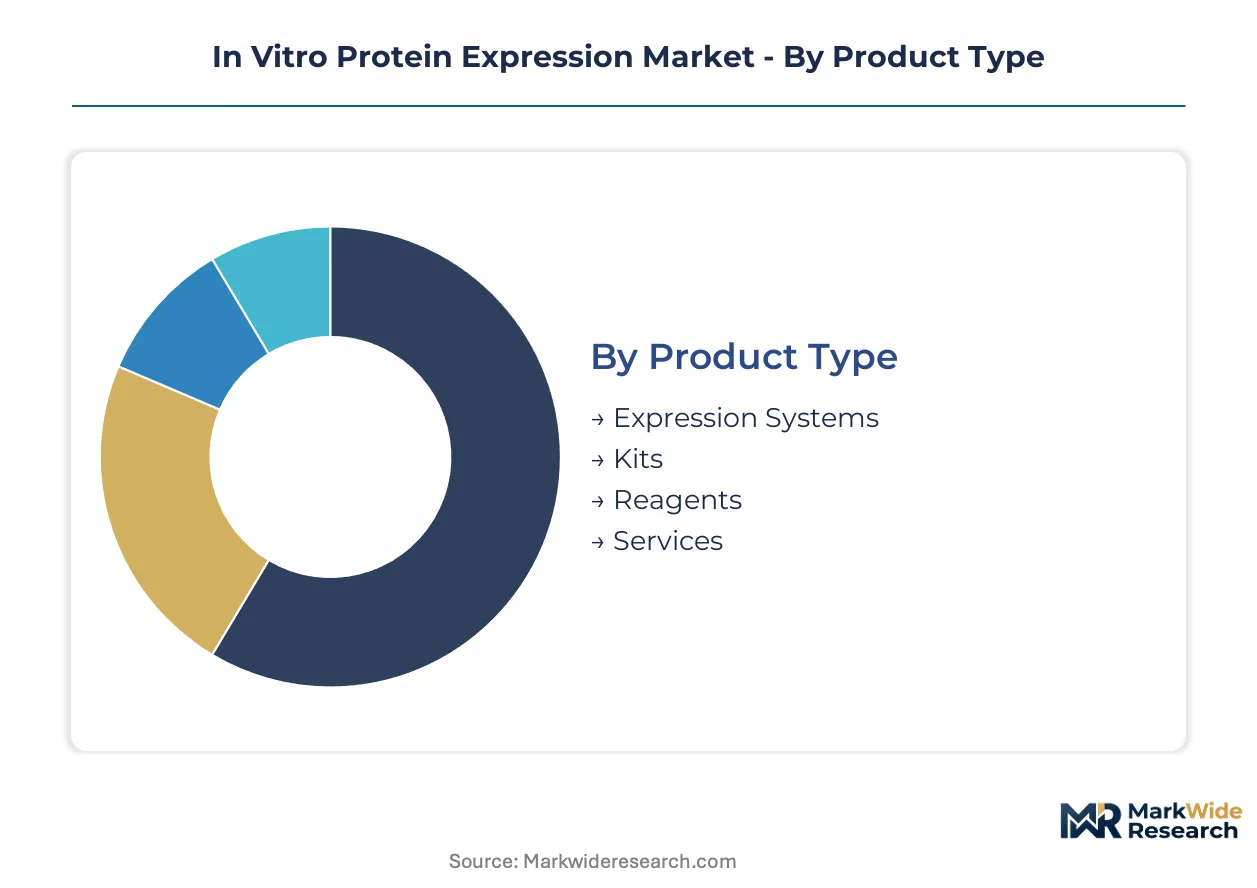
Segmentation in the In Vitro Protein Expression Market reveals how technology architecture, end-use requirements, and regulatory compliance tiers create distinct purchasing behaviors. Suppliers must align product configurations to these axes to capture recurring revenue versus project-based service contracts.
Product Type:
Technology architecture determines whether customers seek integrated workflows or modular components, with recurring consumable purchases driving margin stability against one-time instrument sales.
- Expression Systems:Integrated hardware-software platforms combining bioreactors, purification modules, and analytical sensors for automated end-to-end protein production. Demand concentrates among pharmaceutical companies in the United States running high-throughput therapeutic screening campaigns, constrained by capital expenditure approval cycles and facility footprint limitations.
- Kits:Pre-formulated reagent packs with standardized protocols for rapid deployment without specialized expertise. Academic institutions across Germany and the United Kingdom represent the densest customer base, drawn by NIH and European Research Council grant funding that favors reproducible, publication-ready methodologies.
- Reagents:Bulk enzymes, energy regeneration systems, and specialized buffers sold separately for protocol customization.
- Services:Contract construct design, expression optimization, and analytical validation outsourced to specialized providers.
Mature deployment sits with Kits. Newer deployment is concentrated in Services.
Application:
End-use specifications separate research-grade flexibility from clinical-grade documentation burdens, with therapeutic applications imposing stricter raw material traceability.
- Drug Development:Rapid production of candidate proteins for pharmacokinetic profiling and target engagement studies using both cell-free and cell-based architectures. Biotechnology companies in Boston and San Diego corridors drive volume, requiring toxic protein capabilities that cell-free systems uniquely enable.
- Vaccine Production:Expression of viral antigens and virus-like particles for immunogenicity assessment. European demand clusters around German and Swiss facilities responding to EMA's tightened ATMP classification guidelines for gene therapy components.
- Gene Therapy:Viral vector component production and capsid protein expression for AAV manufacturing.
- Diagnostics:Recombinant antigens and control materials for assay development and calibration.
Revenue concentration favors Drug Development. Steepest expansion trajectory is emerging in Gene Therapy.
Technology:
Biological chassis selection balances speed, folding fidelity, and post-translational modification requirements against cost per milligram produced.
- Cell-free Systems:Purified transcription-translation machinery in buffered reactions enabling non-natural amino acid incorporation and toxic protein production impossible in living cells. Antibody-drug conjugate developers in the United States and Netherlands are accelerating adoption, drawn by open-reaction architecture that permits site-specific chemical modifications.
- Mammalian Systems:CHO and HEK293 transient expression retaining cost advantages for complex glycoproteins requiring authentic human-like post-translational modifications. Contract manufacturing organizations in India are expanding capacity here for biosimilar production.
- Microbial Systems:E. coli and Bacillus platforms for high-yield intracellular or secreted proteins without glycosylation requirements.
- Yeast Systems:Pichia pastoris and Saccharomyces cerevisiae offering eukaryotic folding with simpler glycosylation patterns than mammalian hosts.
Established manufacturing relies on Mammalian Systems. Fastest technology transition is occurring in Cell-free Systems.
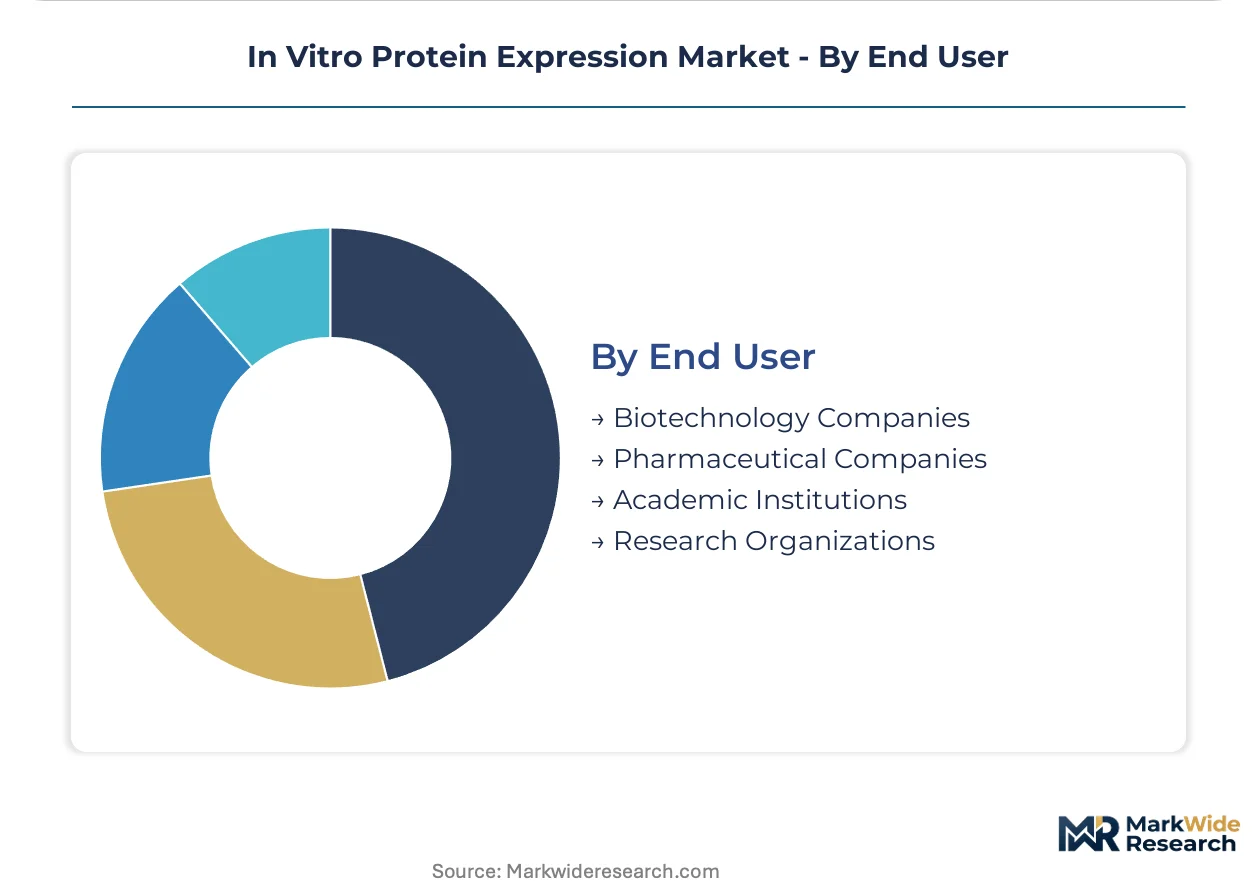
End User:
Procurement sophistication spans from grant-funded academic labs prioritizing publication speed to pharmaceutical procurement teams negotiating multi-year platform agreements.
- Biotechnology Companies:Venture-funded firms requiring rapid protein production to hit discovery milestones and secure subsequent financing rounds. San Diego and Cambridge, Massachusetts clusters generate concentrated demand for cell-free platforms that compress design-build-test cycles.
- Pharmaceutical Companies:Large-cap firms consolidating expression service contracts under preferred vendor panels with batch-release traceability mandates. FDA oversight of cell-derived reagents shapes their purity documentation requirements for diagnostic assay components.
- Academic Institutions:University labs dependent on federal grant funding with limited capital budgets favoring kit-based solutions.
- Research Organizations:Non-profit institutes and government laboratories with mission-driven protein production requirements.
Contract concentration is highest among Pharmaceutical Companies. Fastest user segment expansion is appearing in Biotechnology Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German bioprocessing equipment suppliers anchor raw material sourcing for high-purity reagent-grade lysates, while NIH funding priorities and CRO clustering patterns concentrate demand generation in specific metropolitan corridors across multiple continents.
United States
Boston and San Diego biotech clusters generate localized demand spikes for high-throughput expression validation services. FDA oversight of cell-derived reagents shapes purity documentation requirements for diagnostic assay components. NIH grant capital directs academic structural biology labs toward rapid therapeutic protein screening platforms.
Germany
Merck KGaA anchors European demand through dominance in GMP-compliant cell-free lysate production. EMA's ATMP classification guidelines influence how gene therapy developers qualify expression-derived viral vector components. Bavarian and North Rhine-Westphalian facilities concentrate clinical-grade material manufacturing.
India
Hyderabad and Bangalore contract development organizations seek cell-free platforms to bypass biosafety level containment requirements for toxic protein classes. CDSCO regulatory pathways for gene therapy components are tightening documentation standards for imported lysates. Karnataka and Telangana biotech parks are expanding cell-free service capacity.
United Kingdom
Academic institutions across England and Scotland represent dense customer bases for standardized expression kits. European Research Council grant funding favors reproducible, publication-ready methodologies. London-Oxford-Cambridge research triangle maintains concentrated demand for structural biology applications.
Switzerland
Swissmedic oversight of clinical-grade reagents drives premium positioning for GMP-certified expression system suppliers. Basel and Zurich biopharmaceutical procurement teams consolidate service contracts under platform agreements. Gene therapy developers here are locking multi-year supply agreements with certified lysate producers.
In Vitro Protein Expression Market Competitive Environment
Global majors compete with regional champions across reagent supply chains and service delivery networks. The vendor base stratifies between vertically integrated life science conglomerates, specialized cell-free technology developers, and regional distribution-focused reagent suppliers. Three archetypes dominate: kit manufacturers with ISO 13485-certified quality systems, GMP lysate producers with clinical-grade material streams, and instrumentation-integrated workflow providers. Competitive moves center on multi-year supply agreement lock-ins and AI-assisted construct design capability acquisition.
Among vertically integrated life science conglomerates, Thermo Fisher Scientific exemplifies the archetype leveraging supply chain control from plasmid synthesis through finished expression kits. Merck KGaA occupies a position representing European GMP-compliant lysate production dominance. Bio-Rad Laboratories sits within the instrumentation-integrated workflow tier, anchoring competitive positioning around shortened optimization cycles for contract research users.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Promega Corporation |
| New England Biolabs |
| QIAGEN |
| Lonza |
| Takara Bio |
| Others |
Value Chain & Pricing Dynamics
Research-grade versus clinical-grade lysate bifurcation drives a three-fold pricing gap that reshapes procurement patterns across the value chain, with GMP-certified German producers commanding premium positions while academic kit buyers face compressed margins from standardized reagent competition. This tier divergence feeds directly into supply chain architecture: clinical-grade material streams require dedicated manufacturing suites and batch-release traceability systems that research-grade suppliers cannot replicate without capital reconfiguration.
Pricing Analysis
Service bundling separates integrated workflow providers from component vendors, with Thermo Fisher Scientific and Bio-Rad Laboratories packaging construct design support and optimization consulting into platform agreements that academic buyers rarely access. Price differentiation hinges on ISO 13485 certification status and endotoxin documentation depth, with diagnostic manufacturers paying substantial premiums for qualified quality management systems. Pricing pressure stems from CHO and HEK293 transient systems retaining cost advantages at milligram-to-gram scales, forcing cell-free vendors to emphasize speed-to-result value propositions. Academic institutions exhibit highest price sensitivity, while pharmaceutical procurement teams prioritize supply security over unit cost.
Supply Chain Analysis
GMP-grade plasmid DNA supply rests on dedicated manufacturing suites concentrated in Germany, the United States, and Switzerland, with Bavarian and North Rhine-Westphalian facilities anchoring European clinical-grade lysate production. Critical inputs include energy regeneration enzymes, specialized transcription-translation buffers, and high-purity ribosome preparations sourced from controlled fermentation runs. Single-source vulnerability concentrates around Merck KGaA's dominance in GMP-compliant lysate streams, creating qualification bottlenecks for viral vector component manufacturers. Distribution runs through direct sales to large pharmaceutical accounts and specialized distributors serving academic and biotechnology segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as multi-year platform agreements concentrate purchasing power among fewer than five preferred vendors per major pharmaceutical account, squeezing regional kit suppliers without certified quality systems or AI-assisted construct design capabilities.
For Market Incumbents: Lock in lysate supply agreements with GMP-certified German producers before qualification windows close, and acquire machine-learning codon optimization tools to collapse customer optimization cycles. The threat of AI-native entrants automating construct design demands rapid capability integration, while endotoxin documentation burdens favor vendors with pre-existing ISO 13485 infrastructure. For New Entrants and Emerging Players: CDMO partnerships in Hyderabad and Bangalore offer the most penetrable entry channel, given Indian biosafety containment workarounds for toxic protein classes that Western facilities cannot match. White-space exists in automated microfluidic cartridge formats for continuous-flow reactors, where point-solution specialists can modularize workflows previously captured by integrated kit suppliers. A services-first go-to-market angle—bundling construct design with expression validation—builds recurring revenue before hardware investments. For Investors and Strategic Acquirers: Re-rating potential sits with cell-free technology developers possessing GMP lysate production capabilities given EMA's tightening ATMP classification guidelines for gene therapy components. Long-term viability frames around clinical-grade material streams commanding sustained pricing premiums over commoditized research-grade alternatives. The signal to watch is multi-year supply agreement announcements between viral vector manufacturers and certified lysate producers as inflection indicators for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Lysate Supply Agreement | Locks multi-year revenue visibility as EMA tightens ATMP qualification thresholds for gene therapy developers. |
| AI-Assisted Construct Design Acquisition | Collapses optimization cycles from weeks to days, differentiating against CHO and HEK293 transient expression alternatives. |
| ISO 13485 Certification Investment | Opens IVD manufacturer channels facing FDA-mandated batch-release traceability requirements for diagnostic reagents. |
| Microfluidic Cartridge Format Development | Captures value from pharmaceutical discovery groups specifying droplet-based systems for primary screening campaigns. |
| India CDMO Partnership Formation | Bypasses biosafety level containment requirements for toxic protein classes that constrain Western facility capacity. |
Study Parameters
Multi-period observation of NIH funding allocations, EMA regulatory guidance evolution, and CRO contract concentration patterns anchored the trend analysis, supplemented by interviews with protein engineering directors at biotechnology firms, regulatory affairs leads at diagnostic manufacturers, academic principal investigators, and procurement officers at contract research organizations. Secondary validation drew from FDA 510(k) filings for cell-derived diagnostic reagents, EMA ATMP classification guideline updates, NIH RePORTER grant databases, and ISO 13485 certification registries. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting approaches distributed revenue across expression systems, kits, reagents, and services according to deployment maturity and growth trajectory differentials, with technology splits between cell-free and mammalian systems further refined by end-use application. CAGRs were derived from fitted growth curves incorporating NIH funding priority shifts, microfluidic adoption rates in pharmaceutical screening operations, and GMP lysate production capacity expansion timelines. Industry-specific forecast inputs included EMA regulatory convergence assumptions and CDSCO pathway tightening for imported lysates in India.
Caveats apply where GMP lysate production capacity constraints, sudden shifts in NIH grant priorities, or faster-than-expected CHO system cost compression could materially shift the outlook. Forecasts reflect assumptions about regulatory timeline stability and academic funding continuity that warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Human Biobanking Ownership Market
Biomedical Technology
Immunofluorescence Analyzers Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Structural Biology and Molecular Modeling Techniques Market
Biomedical Technology
Global Cell Harvesting Market
Biomedical Technology
Global Plant Stem Cell Market
Biomedical Technology
Digital Biology Market
Biomedical Technology
Ontogenetic Market
Biomedical Technology
BOD Incubator Market
Biomedical Technology
Biomarker Detection Systems Market
Biomedical Technology
Cell Isolation Market
Biomedical Technology
Global Glycobiology Market
Biomedical Technology
Global Drug Discovery Technologies Market
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
Biologics Outsourcing Market
Biomedical Technology
Global Primary Cell Culture Market