
 Global Expression Vectors Market | 2026-2036
Global Expression Vectors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Expression Vectors Market Foresight
Contract manufacturing organization networks for viral vector production is reshaping how biopharmaceutical companies access GMP-grade expression systems. Thermo Fisher Scientific leverages its integrated plasmid-to-viral-vector platform to control supply timelines for gene therapy developers. QIAGEN specializes in automated plasmid purification workflows that reduce batch-to-batch variability for contract research organizations. New England Biolabs anchors molecular biology reagent supply through its restriction enzyme and DNA ligase portfolios that underpin vector construction protocols.
Expression vectors are engineered DNA molecules—typically 2-20 kilobases in plasmid form or packaged into adeno-associated viral capsids—designed to introduce and drive heterologous gene expression in host cells through promoter-driven transcription and translation machinery. Their primary purpose spans recombinant protein manufacturing, therapeutic gene delivery, and functional genomic screening in research and clinical settings. Viral vectors command premium positioning in gene therapy applications due to transduction efficiency requirements, while plasmid vectors sustain volume leadership in protein production and molecular cloning workflows. Mammalian cell host systems capture the fastest growth trajectory as complex biologics and cell-and-gene therapies demand human-compatible glycosylation patterns and proper protein folding.
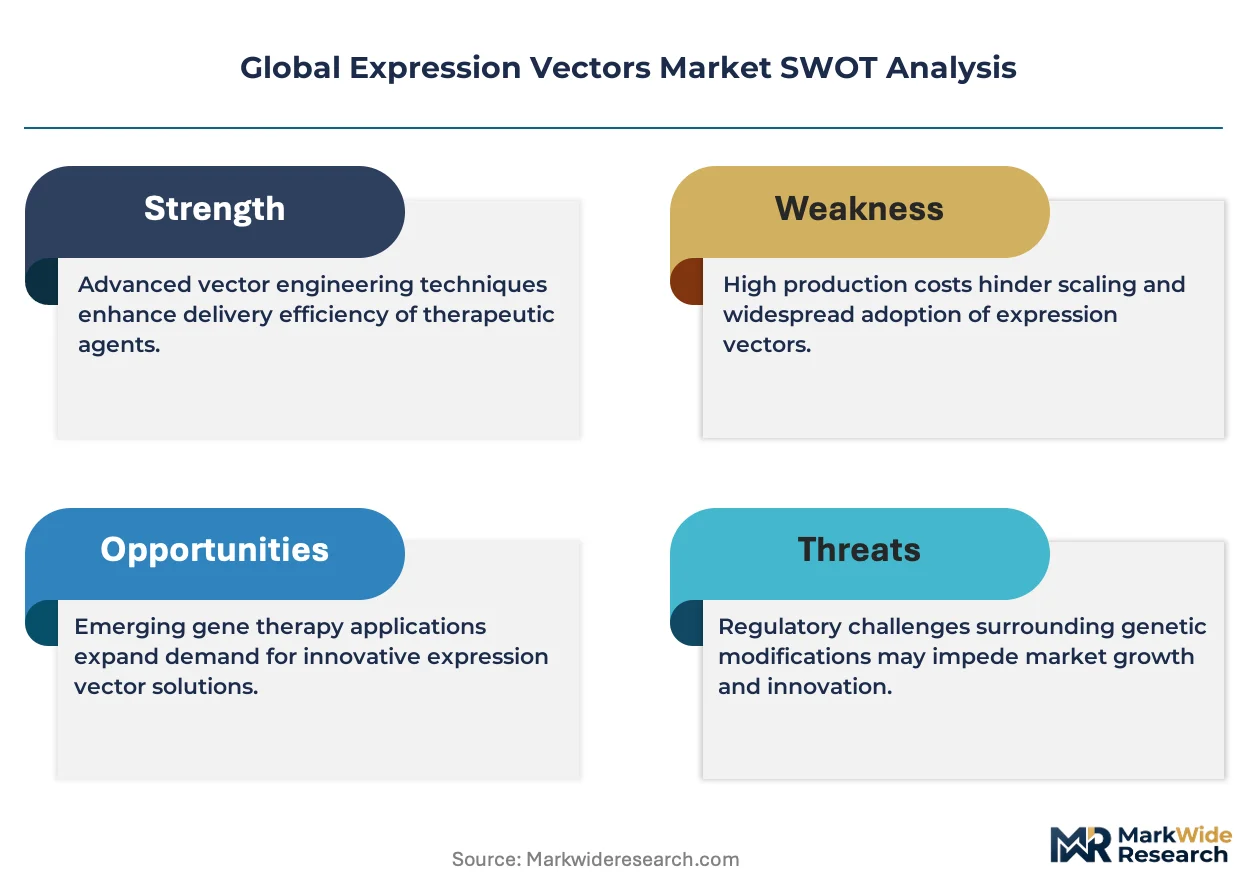
FDA gene therapy CMC guidance, EMA ATMP quality requirements, and ISO 13485 medical device quality standards collectively tighten vector characterization and documentation burdens for market participants. These frameworks elevate barrier-to-entry for new suppliers while favoring established players with validated quality management systems. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on replication-competent vector detection methods and empty capsid quantification thresholds.
Market Dynamics
Contract manufacturing organization networks for viral vector production are consolidating access to GMP-grade expression systems, with qualification timelines and capacity allocation now determining pipeline velocity for gene therapy developers.
Growth Catalysts
- FDA Gene Therapy CMC Guidance:The FDA's Chemistry, Manufacturing, and Controls framework mandates rigorous vector characterization, accelerating investment in analytical capabilities and quality infrastructure across biopharmaceutical manufacturing.
- Cell-and-Gene Therapy Pipelines:Biopharmaceutical developers are expanding IND filings for CAR-T and gene replacement therapies, driving sustained demand for clinical-grade plasmid and viral vector production capacity.
- China NMPA Accelerated Pathways:China's National Medical Products Administration has streamlined review timelines for innovative biologics, concentrating regional manufacturing investment in Suzhou and Shanghai biotech clusters.
Market Restraints
- Plasmid DNA Supply Concentration:High-quality supercoiled plasmid production concentrates among a limited supplier base, creating bottleneck risks for viral vector packaging workflows.
- EMA ATMP Quality Requirements:The European Medicines Agency's Advanced Therapy Medicinal Products framework imposes extensive documentation and batch release testing, extending qualification timelines for new market entrants.
- Serotype-Specific AAV Manufacturing:Adeno-associated viral vector production remains locked to specific serotype expertise, limiting supplier flexibility and creating capacity allocation inefficiencies.
Strategic Opportunities
- India CDMO Expansion:Indian contract development and manufacturing organizations are building viral vector capabilities to capture cost-sensitive biopharmaceutical outsourcing from Western sponsors.
- Continuous Bioprocessing Integration:Perfusion-based mammalian cell culture systems are converging with single-use bioreactor platforms, enabling real-time quality monitoring and reduced facility footprint.
- Japan PMDA Regenerative Medicine Framework:Japan's Pharmaceuticals and Medical Devices Agency offers conditional approval pathways for gene therapies, attracting sponsor investment in regional manufacturing infrastructure.
Industry Challenges
- Empty Capsid Quantification:Analytical methods for distinguishing intact from empty viral capsids lack standardization, complicating release criteria and comparability protocols across manufacturing sites.
- Replication-Competent Virus Detection:Biosafety testing for residual replication-competent adenovirus or lentivirus requires specialized containment facilities, constraining capacity expansion and extending batch release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Expression Vectors Market |
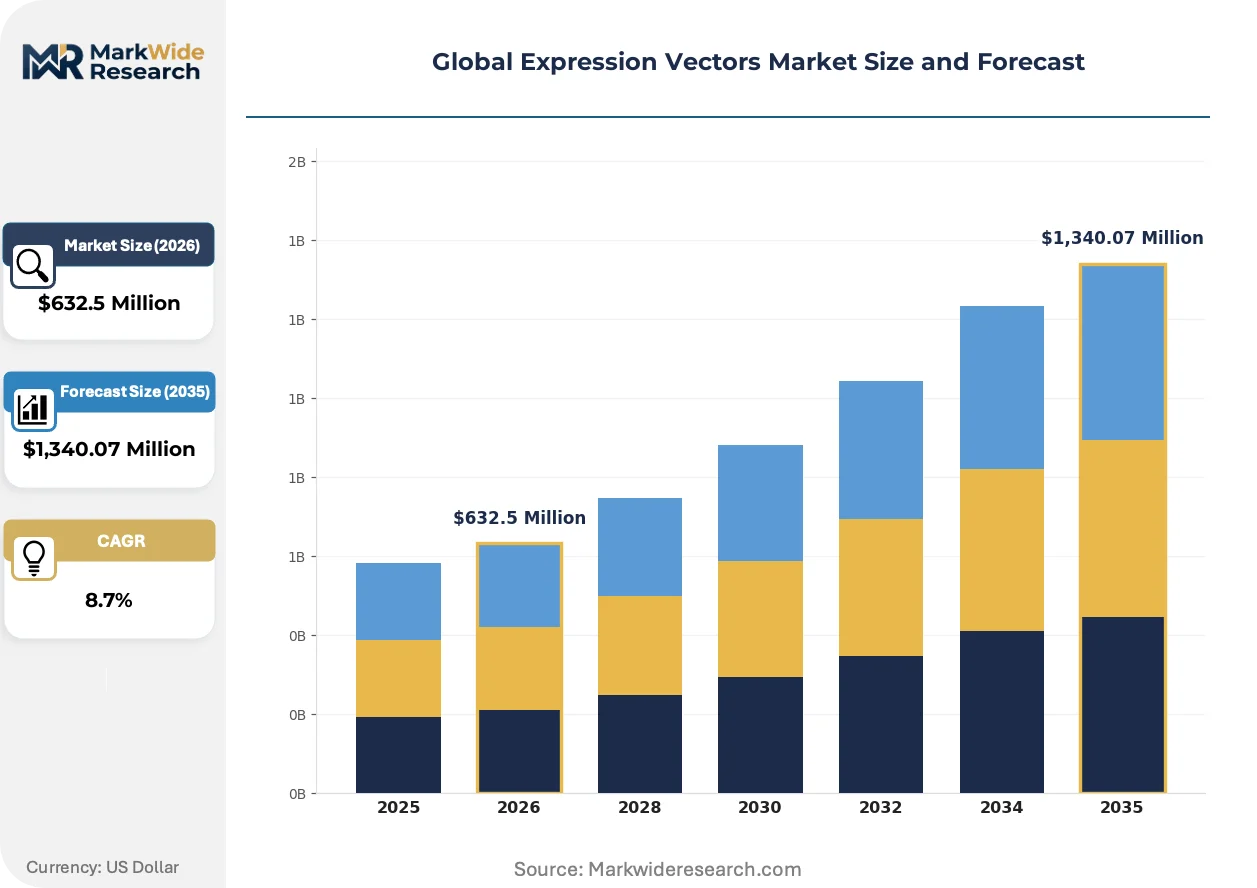
| Market Size in 2026 | $632.5 Million |
| Market Size in 2035 | $1,340.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vector Type: Plasmid, Viral, Bacterial Artificial Chromosome, Fosmid, Cosmids, Transposon Host System: Escherichia coli, Saccharomyces cerevisiae, Mammalian Cells, Insect Cells, Plant Cells, Cell-Free Systems Application: Protein Production, Gene Therapy, Vaccine Development, Functional Genomics, Antibody Production, Synthetic Biology End User: Biopharmaceutical Companies, Contract Research Organizations, Academic Institutions, Biotechnology Startups |
| Companies Covered | Thermo Fisher Scientific, Inc., Promega Corporation, Agilent Technologies, Inc., Bio-Rad Laboratories, Inc., Merck KGaA, QIAGEN, TAKARA HOLDINGS Inc., New England Biolabs, GenScript USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Expression Vectors Market Shifts & Advancements
Synthetic biology toolkits and automated vector design platforms are compressing development cycles, while regulatory harmonization efforts are reshaping quality expectations across manufacturing jurisdictions.
Suspension-adapted HEK293 cell lines are migrating from adherent culture systems as gene therapy manufacturers seek scalable, serum-free production platforms. Contract manufacturers in Germany and the United States are retrofitting facilities for stirred-tank bioreactor operations. This technology transition is enabling single-batch viral vector yields that previously required multiple production campaigns.
The EMA's ATMP quality guidelines and FDA's gene therapy CMC guidance are converging on empty capsid quantification thresholds and replication-competent virus detection standards. European manufacturers face accelerated implementation timelines for updated analytical method validation. Viral vector suppliers are consolidating release testing protocols to satisfy both regulatory regimes without redundant qualification studies.
Biopharmaceutical sponsors are unbundling vector manufacturing from integrated discovery-to-clinic contracts, creating discrete procurement categories for plasmid DNA, viral vector packaging, and fill-finish services. Large pharmaceutical companies are establishing preferred supplier networks with defined capacity reservations. This purchasing pattern shift is most pronounced among sponsors with multiple parallel gene therapy programs in the United States.
Global Expression Vectors Market Segmentation
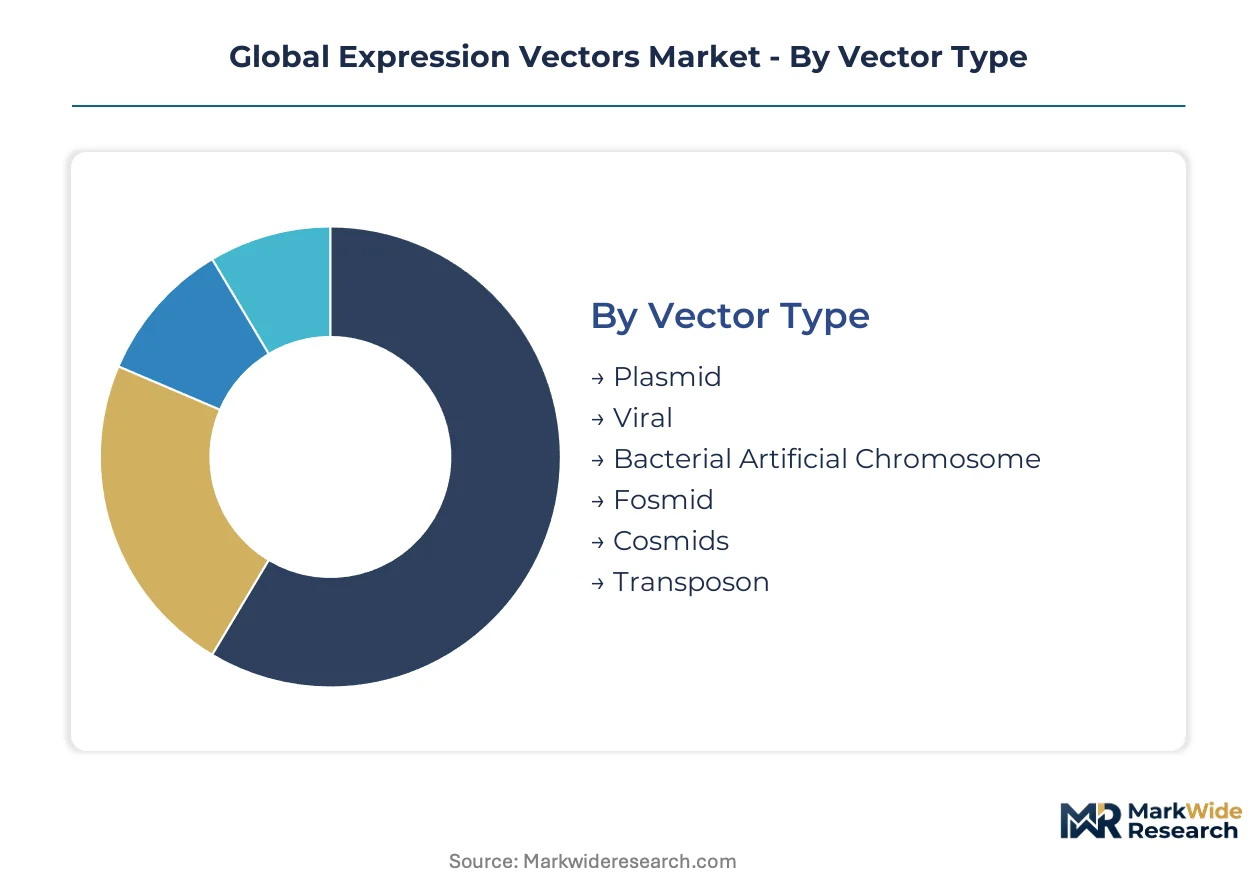
Expression vectors serve divergent technical requirements across protein manufacturing, therapeutic delivery, and research workflows. Segment boundaries reflect host compatibility constraints, regulatory qualification burdens, and manufacturing scale economics that reshape procurement patterns among biopharmaceutical developers.
Vector Type:
After-sales service intensity varies sharply by vector category, with viral vectors demanding sustained technical support for potency assays and regulatory filings while plasmid vectors require minimal ongoing vendor engagement.
- Plasmid:Circular DNA molecules engineered for high-copy replication in bacterial hosts support protein production and viral vector packaging workflows. Demand concentrates in contract manufacturing organizations across Germany and the United States as gene therapy developers outsource GMP-grade plasmid supply. FDA Chemistry, Manufacturing, and Controls documentation requirements elevate qualification burdens for clinical-grade material.
- Viral:Adeno-associated virus, lentivirus, and adenovirus capsids deliver therapeutic genes with tissue-specific tropism. Gene therapy sponsors in China and the United States lock in multi-year capacity reservations with specialized CDMOs due to serotype-specific manufacturing expertise scarcity.
- Bacterial Artificial Chromosome:Low-copy vectors accommodate large DNA inserts exceeding 100 kilobases for genomic library construction and complex pathway engineering.
- Fosmid:Stable single-copy vectors derived from F-factor plasmids serve clone stability requirements in metagenomic screening applications.
- Cosmids:Hybrid lambda phage-plasmid vectors package DNA fragments to 45 kilobases for physical mapping and chromosome walking protocols.
- Transposon:Mobile genetic element systems enable stable chromosomal integration for long-term expression in mammalian cell line development.
By volume, Plasmid leads. By growth pace, Viral is ahead.
Host System:
Manufacturing cost tiers separate established microbial platforms from emerging mammalian and cell-free alternatives that command premium pricing for complex biologics.
- Escherichia coli:Rapid doubling times and well-characterized genetics sustain dominance in industrial enzyme and insulin analog production. Biopharmaceutical manufacturers in India leverage established fermentation infrastructure for cost-sensitive recombinant protein supply.
- Saccharomyces cerevisiae:Eukaryotic post-translational modification capability supports vaccine antigen and therapeutic protein manufacturing with shorter development timelines than mammalian alternatives.
- Mammalian Cells:Chinese hamster ovary and HEK293 lines deliver human-compatible glycosylation for monoclonal antibodies and gene therapy vectors. Suspension-adapted platforms are displacing adherent culture systems as CDMOs in the United States retrofit facilities for single-use bioreactor operations.
- Insect Cells:Baculovirus expression systems produce complex proteins with glycosylation patterns distinct from mammalian hosts for research-grade applications.
- Plant Cells:Transient expression in Nicotiana benthamiana offers biosafety advantages and rapid scale-up for vaccine candidates and biologic manufacturing.
- Cell-Free Systems:In vitro transcription-translation enables rapid prototyping and toxic protein production without viable host constraints.
By installed base, Escherichia coli leads. By expansion trajectory, Mammalian Cells is climbing the fastest.
Application:
Customer maturity separates commoditized research applications from clinical-stage programs that demand validated supply chains and regulatory documentation packages.
- Gene Therapy:Viral vector delivery of therapeutic transgenes requires GMP manufacturing, extensive characterization, and batch release testing under FDA and EMA frameworks. Sponsors with multiple parallel programs unbundle vector procurement from integrated discovery contracts.
- Protein Production:Recombinant enzyme and cytokine manufacturing sustains volume demand across contract research organizations and industrial biotechnology. China NMPA accelerated pathways concentrate regional investment in Suzhou biotech clusters.
- Vaccine Development:DNA and viral vector platforms for infectious disease prophylaxis expanded during pandemic preparedness initiatives.
- Functional Genomics:CRISPR guide RNA delivery and reporter constructs support academic screening workflows with lower regulatory stringency.
- Antibody Production:Transient expression in mammalian hosts generates research-grade material for lead candidate selection before stable cell line development.
- Synthetic Biology:Standardized part libraries and automated design-build-test cycles compress development timelines for engineered metabolic pathways.
By revenue concentration, Gene Therapy leads. By volume scale, Protein Production dominates.
End User:
Procurement scale and technical sophistication separate large biopharmaceutical sponsors from resource-constrained academic laboratories with divergent service expectations.
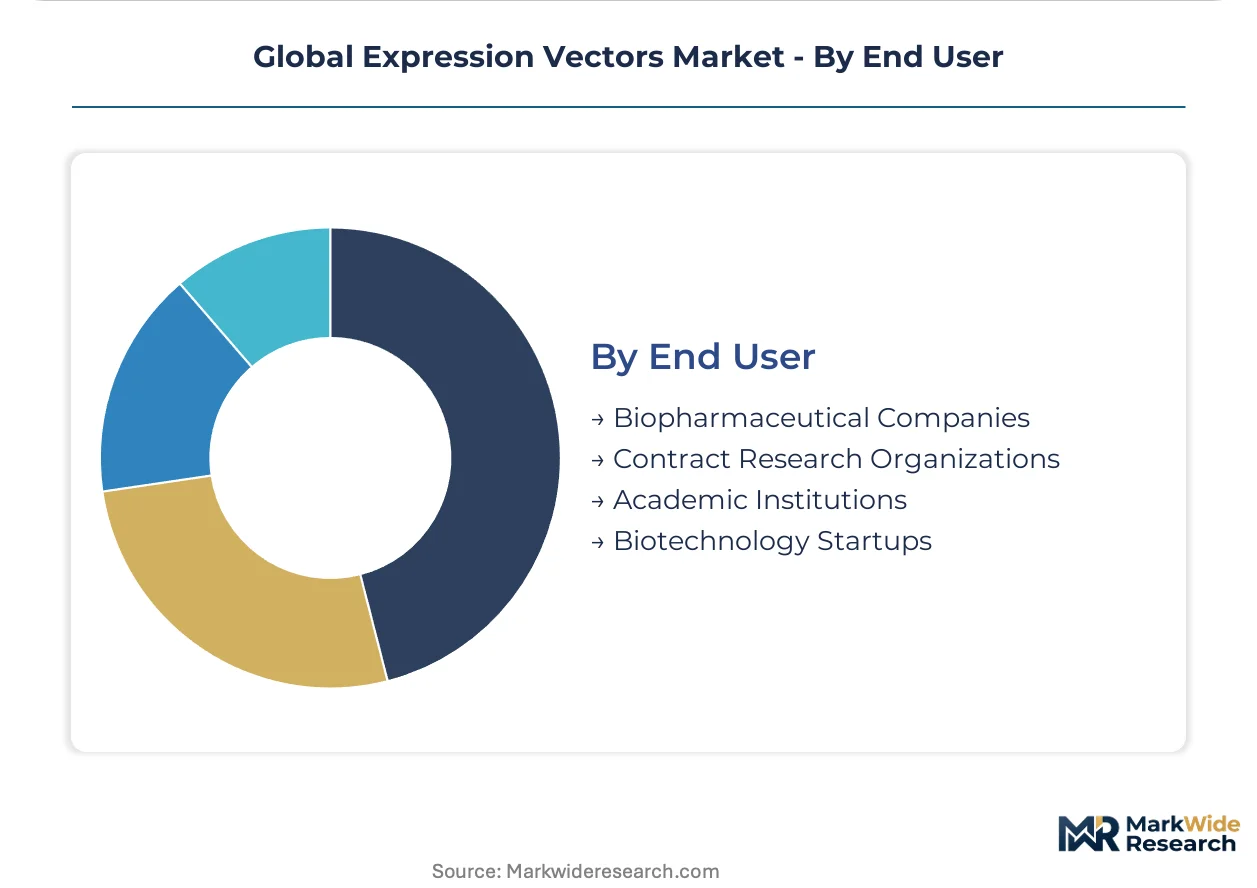
- Biopharmaceutical Companies:Integrated developers and emerging gene therapy sponsors drive demand for clinical-grade vectors with dedicated manufacturing slots and regulatory support. Preferred supplier networks with defined capacity reservations are reshaping vendor relationships among United States-based sponsors with parallel pipeline assets.
- Contract Research Organizations:Automated plasmid purification workflows and standardized viral vector packaging services reduce batch-to-batch variability for multi-client programs. QIAGEN and specialized CDMOs compete on turnaround time and documentation packages.
- Academic Institutions:Research-grade reagents and molecular cloning toolkits sustain volume demand with price sensitivity and minimal regulatory requirements.
- Biotechnology Startups:Venture-funded companies leverage contract manufacturing organization networks to access GMP capabilities without capital-intensive facility investment.
By spending volume, Biopharmaceutical Companies lead. By growth pace, Contract Research Organizations is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cold chain logistics network connecting Indianapolis, Rotterdam, and Shanghai underwrites the geography's role in time-sensitive viral vector distribution. Temperature-controlled air freight corridors link clinical manufacturing hubs to patient administration sites across three continents. Regional specialization reflects divergent regulatory maturities and capital access tiers.
United States
Gene therapy sponsors in Massachusetts and North Carolina lock in multi-year capacity reservations with specialized CDMOs. FDA Chemistry, Manufacturing, and Controls guidance mandates rigorous vector characterization, accelerating investment in analytical infrastructure. The Greater Boston biotech cluster concentrates viral vector manufacturing expertise alongside venture capital access.
Germany
Contract manufacturers in Bavaria and North Rhine-Westphalia retrofit facilities for stirred-tank bioreactor operations. EMA Advanced Therapy Medicinal Products quality requirements impose extensive documentation burdens, extending qualification timelines for new entrants. The Munich biotech corridor anchors European viral vector production capacity.
China
NMPA accelerated pathways for innovative biologics concentrate regional investment in Suzhou and Shanghai clusters. National Medical Products Administration streamlined review timelines attract multinational sponsor manufacturing commitments. The Suzhou Industrial Park hosts dedicated gene therapy manufacturing campuses serving domestic and export markets.
Japan
Pharmaceuticals and Medical Devices Agency conditional approval pathways for regenerative medicines attract sponsor investment in Kanto region infrastructure. PMDA regulatory convergence with FDA standards reduces redundant qualification studies for multinational developers. The Kawasaki biotech corridor integrates vector manufacturing with fill-finish capabilities.
India
Contract development and manufacturing organizations in Hyderabad and Bengaluru build viral vector capabilities to capture cost-sensitive biopharmaceutical outsourcing. Central Drugs Standard Control Organization alignment with ICH guidelines facilitates export-oriented manufacturing qualification. The Genome Valley cluster anchors plasmid DNA production for regional gene therapy developers.
Global Expression Vectors Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers and specialized component suppliers with divergent capital intensity requirements. Thermo Fisher Scientific controls end-to-end workflows from plasmid construction through viral vector packaging. Strategic archetypes include diversified life science conglomerates, molecular biology reagent specialists, and regional CDMO networks. Dominant competitive moves encompass facility retrofitting for suspension cell culture and preferred supplier agreements with multi-program gene therapy sponsors.
Among diversified platform providers, Thermo Fisher Scientific occupies a position exemplifying integrated plasmid-to-viral-vector control over supply timelines. QIAGEN represents the automated purification workflow archetype serving contract research organization demand for reduced batch-to-batch variability. New England Biolabs anchors the molecular biology reagent specialist tier through restriction enzyme and DNA ligase portfolios that underpin vector construction protocols across research and clinical settings.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Promega Corporation |
| Agilent Technologies, Inc. |
| Bio-Rad Laboratories, Inc. |
| Merck KGaA |
| QIAGEN |
| TAKARA HOLDINGS Inc. |
| New England Biolabs |
| GenScript USA Inc. |
| Others |
Supply & Pricing Matrix
Plasmid DNA production concentration in the United States and Germany funnels margin capture downstream toward viral vector packaging specialists and gene therapy sponsors with locked capacity reservations. FDA Chemistry, Manufacturing, and Controls documentation burdens create tiered qualification costs that segment suppliers into distinct pricing bands based on analytical capability investment.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates GMP-grade clinical vectors from research-grade reagents and bulk industrial enzymes. Price differentiation hinges on certification tier—ISO 13485 medical device quality versus research-use-only documentation—and after-sales regulatory support bundling. Cost compression in research-grade plasmid supply is intensifying as automated purification platforms reduce batch-to-batch variability. Academic laboratories exhibit highest price sensitivity; gene therapy sponsors with IND-track programs demonstrate lowest sensitivity due to qualification timeline risks.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for gene therapy developers with dual-sourcing strategies. Manufacturing gravity centers on the United States, Germany, and China as clinical production hubs, with raw material dependencies spanning supercoiled plasmid DNA, specialized cell culture media, and GMP-grade restriction enzymes. Single-source vulnerability concentrates in serotype-specific adeno-associated viral vector expertise. Distribution runs through temperature-controlled air freight corridors linking Indianapolis, Rotterdam, and Shanghai to patient administration sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment—manifest in FDA and EMA qualification timelines—protects incumbent positions against rapid displacement. Switching costs for gene therapy sponsors locked into multi-year CDMO contracts further cement established supplier relationships.
For Market Incumbents: Build regulatory documentation moats by deepening analytical method validation investments ahead of FDA-EMA convergence on empty capsid quantification thresholds. Expand stirred-tank bioreactor capacity in the United States and Germany to capture unbundled vector procurement from sponsors with parallel pipeline assets. Emerging CDMO entrants in India threaten cost-sensitive research-grade segments.
For New Entrants and Emerging Players: Mid-market contract research organizations in India and Southeast Asia represent the most penetrable entry point for automated plasmid purification workflows serving multi-client programs. Japan's PMDA conditional approval pathway for regenerative medicines offers a regulatory arbitrage opportunity for regional manufacturing investment. Lead with turnaround time guarantees and standardized documentation packages to differentiate from entrenched Western suppliers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed CDMO networks that consolidated during pandemic-era capacity expansion and now face utilization optimization pressure. Long-term viability across the analysis window favors platforms with integrated plasmid-to-viral-vector control and validated quality management systems. Monitor FDA-EMA regulatory convergence timelines as an inflection indicator for accelerated qualification cost burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA ATMP quality guideline alignment with FDA CMC standards reduces redundant qualification studies for multinational sponsors. |
| Manufacturing Scale-Up | Suspension-adapted HEK293 cell line migration enables single-batch viral vector yields replacing multiple production campaigns. |
| Backward Integration | In-house plasmid DNA production controls supply timelines for gene therapy developers facing CDMO capacity constraints. |
| Strategic Partnership | Preferred supplier networks with defined capacity reservations reshape procurement patterns among United States-based sponsors. |
| Geographic Expansion | Indian CDMO viral vector capability buildout captures cost-sensitive biopharmaceutical outsourcing from Western sponsors. |
Research Methodology
A standing panel of gene therapy development executives, regulatory affairs leads, CDMO operations directors, and academic principal investigators provided ongoing calibration against market developments. Primary interview findings triangulated with FDA gene therapy guidance documents, EMA ATMP quality guidelines, ClinicalTrials.gov vector trial registrations, and SEC filings from publicly traded life science tools companies. Bottom-up segment sizing across vector type, host system, application, and end user converged with top-down market validation.
Scenario-bracketing framed analytical outputs across the projection horizon, modeling demand trajectories under varying regulatory implementation timelines and clinical trial success rates. Segmentation dimensions spanned vector category, host cell platform, therapeutic application, and geographic regulatory cluster. CAGRs derived from installed base evolution, pipeline asset conversion assumptions, and pricing tier migration patterns. Forecast inputs incorporated gene therapy IND filing velocity, CDMO capacity expansion announcements, and plasmid DNA supply concentration metrics.
Macroeconomic conditions sit as an overlay; deviation in biopharmaceutical venture capital availability, cross-border logistics costs, or gene therapy reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions about regulatory convergence pace and clinical manufacturing technology adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Ligation Market
Biomedical Technology
Immunofluorescence Analyzers Market
Biomedical Technology
Antibody Library Technology Market
Biomedical Technology
Middle East and Africa Cell Counting Market
Biomedical Technology
BOD Incubator Market
Biomedical Technology
ST2 Biomarker Market
Biomedical Technology
Global Autologous Conditioned Plasma Market
Biomedical Technology
Global Neuroscience Antibodies and Assays Market
Biomedical Technology
Needle Based Biopsy Guns Market
Biomedical Technology
Biologics Outsourcing Market
Biomedical Technology
Global Stem Cell Assay Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
DNA Forensics Market
Biomedical Technology
Liquid Biopsy Market
Biomedical Technology
Nucleic Acid Aptamers Market