
 Biologics Contract Manufacturing Market | 2026-2036
Biologics Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Biologics Contract Manufacturing Market Intelligence
Multi-product GMP suite certification is redrawing competitive boundaries in biologics contract manufacturing. Samsung Biologics anchors massive mammalian cell culture capacity at its Songdo complex. Lonza specializes in microbial and cell therapy platforms across Swiss and US sites. Thermo Fisher Scientific extends analytical and fill-finish services through integrated CDMO networks.
Biologics contract manufacturing encompasses the outsourced production of protein-based therapeutics, viral vectors, and living cell products under controlled environmental conditions typically requiring single-use bioreactor systems and aseptic processing. The primary purpose centers on converting drug substance to finished drug product while meeting pharmacopeial purity, potency, and safety specifications for human administration. Monoclonal antibodies retain the largest revenue share within product type segments, though gene therapy manufacturing commands premium pricing due to batch complexity and low process yields. Viral vector technology faces capacity bottlenecks as more developers advance candidates toward commercial scale. Service type margins concentrate in process development and quality control, where specialized analytical expertise creates defensible positioning against commodity manufacturing.
FDA's Chemistry, Manufacturing, and Controls framework and EMA's Good Manufacturing Practice guidelines for advanced therapy medicinal products shape facility design, validation protocols, and batch release timelines for CDMO clients. China's NMPA biologics registration requirements and India's CDSCO manufacturing license standards further segment market access by geography. Stakeholders must monitor regulatory divergence between FDA's risk-based inspection model and EMA's centralized marketing authorization pathways when selecting multi-region manufacturing partners.
Market Dynamics
Viral vector manufacturing capacity constraints are forcing biologics developers to lock in multi-year CDMO partnerships before Phase II data readouts, compressing supplier selection timelines and inflating reservation premiums.
Growth Catalysts
- EMA ATMP GMP Guidelines:The European Medicines Agency's tightened manufacturing standards for advanced therapy medicinal products push gene therapy developers toward certified CDMO partners rather than in-house facilities.
- Continuous Bioprocessing:Perfusion cell culture technology adoption reduces facility footprint requirements and accelerates batch turnaround for mammalian-derived monoclonal antibodies.
- South Korea:Government biotech clusters near Seoul and Incheon concentrate specialized talent pools and regulatory expertise for viral vector production.
Market Restraints
- Plasmid DNA Supply:Limited qualified suppliers of GMP-grade plasmid DNA for transfection creates input cost volatility and batch-to-batch consistency risks.
- FDA Inspection Backlog:Post-pandemic staffing constraints at the Food and Drug Administration extend pre-approval inspection timelines by six to twelve months.
- Stainless Steel Bioreactor Obsolescence:Legacy fixed-tank systems face technical limitations in flexibility compared to single-use alternatives, stranding capital in older facilities.
Strategic Opportunities
- India CDSCO Pathway:India's streamlined biologics manufacturing license framework offers faster market entry for export-oriented viral vector production serving emerging markets.
- Allogeneic Cell Therapy:Off-the-shelf cell products eliminate patient-matched manufacturing complexity, opening CDMO capacity for standardized batch production.
- AI-Driven Process Analytics:Machine learning integration with distributed control systems enables real-time release testing and predictive deviation management.
Industry Challenges
- Cell Line Development Expertise:Shortage of scientists proficient in CRISPR-edited host cell engineering limits process development throughput at mid-scale CDMOs.
- Multi-Product Suite Validation:Demonstrating cleaning verification between viral vector and monoclonal antibody campaigns extends facility downtime and compliance documentation burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biologics Contract Manufacturing Market |
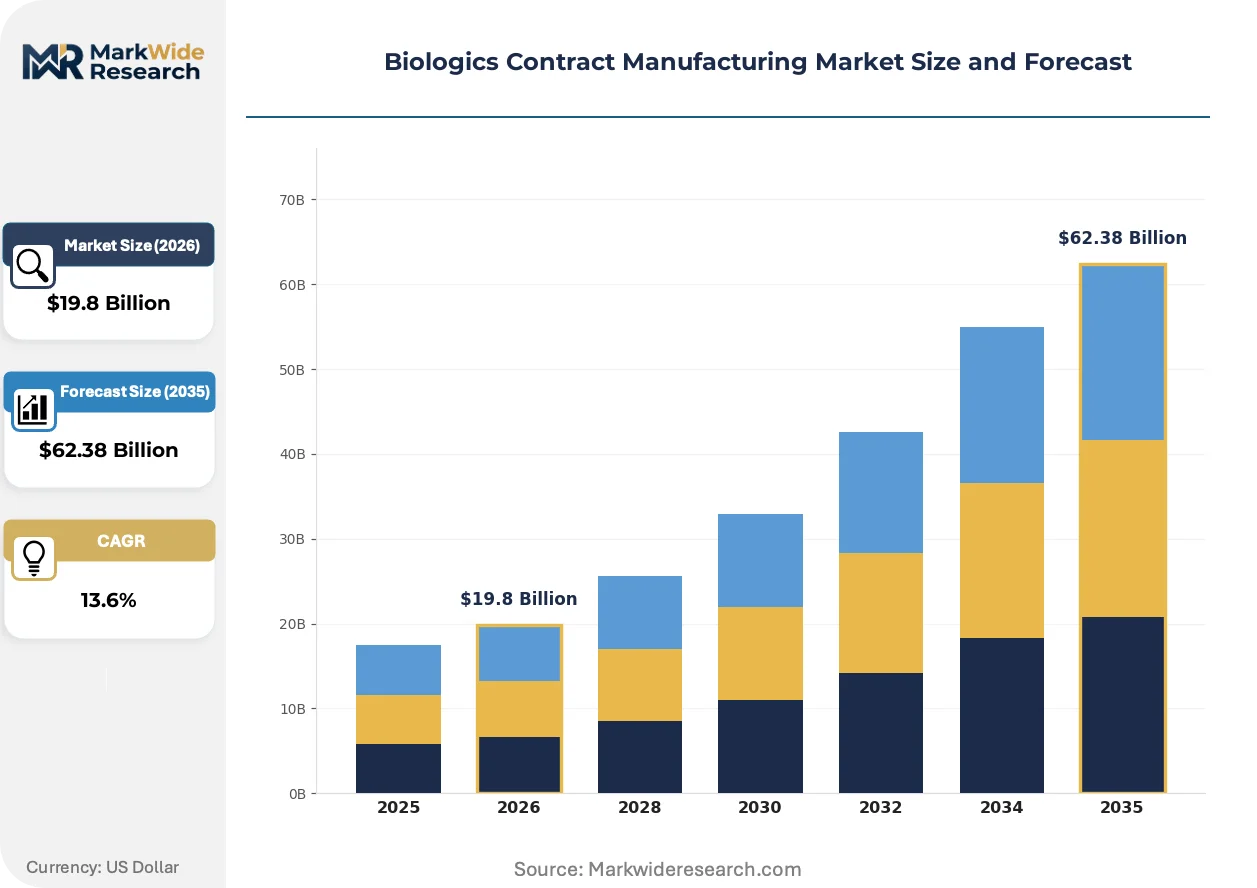
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $62.38 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Cell Therapy, Gene Therapy Technology: Recombinant DNA, Hybridoma, Viral Vector, Protein Engineering End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutes, Academic Centers Service Type: Process Development, Manufacturing, Quality Control, Packaging |
| Companies Covered | Samsung Biologics, Boehringer Ingelheim, Thermo Fisher Scientific, AGC Biologics, Fujifilm Diosynth Biotechnologies, Lonza, WuXi Biologics, Rentschler Biotechnologie, Catalent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biologics Contract Manufacturing Market Strategic Shifts & Innovations
Modular facility architectures and closed-system processing are dissolving traditional boundaries between drug substance and drug product manufacturing, enabling distributed production networks.
Single-use bioreactor assemblies with integrated perfusion control modules are decomposing the capital intensity barrier that previously restricted commercial-scale manufacturing to large pharmaceutical incumbents. Mid-cap biotech developers now access 2,000-liter production runs without facility ownership. This technology is compressing the minimum viable scale for profitable CDMO operations.
REACH registration requirements for novel process chemicals used in cell culture media are forcing European CDMOs to reformulate proprietary feeds and document alternative substance safety profiles. The regulatory burden falls heaviest on microbial fermentation platforms relying on complex undefined hydrolysates. Swissmedic and Germany's national chemical regulator are coordinating inspection protocols to reduce duplicate compliance costs.
Biotech developers increasingly unbundle analytical method development from manufacturing contracts, awarding validation and release testing to specialized laboratories. This procurement pattern fragments the traditional full-service CDMO model. The United States exhibits the most pronounced unbundling, with Boston and San Francisco clusters hosting dedicated analytical service providers.
Biologics Contract Manufacturing Market Segmentation
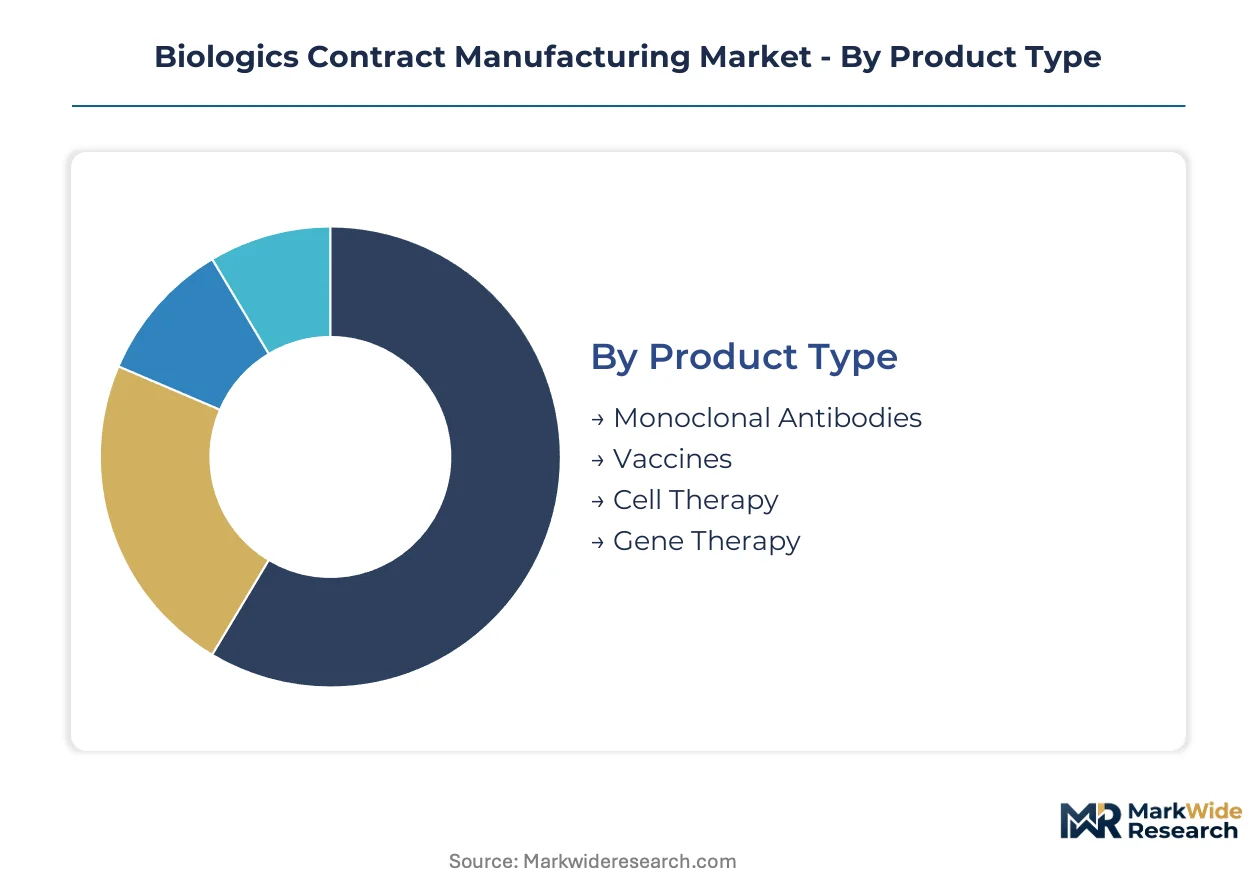
Biologics contract manufacturing segments diverge sharply by regulatory pathway complexity and capital intensity. Product type and service type splits determine facility investment profiles, while end-user concentration shapes geographic demand clustering.
Product Type:
Monoclonal antibodies and vaccines flow predominantly through domestic supply chains serving FDA and EMA markets. Gene therapy and cell therapy batches ship cross-border more frequently, with viral vector production concentrating near Seoul and Boston for export to European trial sites.
- Monoclonal Antibodies:Mammalian cell culture-derived immunoglobulins require 10,000+ liter bioreactor trains and protein A chromatography purification. Demand clusters in Massachusetts and California for oncology and autoimmune indications, with CDMOs booking capacity three years ahead of anticipated approvals.
- Gene Therapy:Adeno-associated viral vectors and lentiviral constructs demand specialized containment suites and segregation protocols. Production concentrates in South Korea and the United States due to EMA ATMP certification requirements and FDA gene therapy CMC guidance compliance burdens.
- Vaccines:Egg-based and cell culture platforms for prophylactic immunization.
- Cell Therapy:Autologous and allogeneic cellular products requiring cryopreservation logistics.
Monoclonal antibodies command the established base. The steepest expansion runs through gene therapy.
Technology:
Platform selection dictates facility retrofit costs and talent recruitment geography. Recombinant DNA and hybridoma methods anchor mature supply networks, while viral vector engineering requires newer workforce competencies concentrated near research universities.
- Recombinant DNA:Bacterial and yeast expression systems for insulin, growth factors, and cytokines. Production concentrates in Switzerland and Germany for EMA-registered biosimilars, with CDMOs leveraging established E. coli fermentation expertise from small-molecule transitions.
- Viral Vector:Transient transfection and stable producer cell lines for gene delivery vehicles. Capacity bottlenecks in the United States and South Korea force developers to reserve slots before Phase II data, compressing supplier selection timelines.
- Hybridoma:Murine and humanized antibody production from immortalized B-cell fusions.
- Protein Engineering:Computational design and directed evolution for enhanced therapeutic properties.
Recombinant DNA underpins volume scale. Viral vector platforms are climbing the fastest.
End User:
Pharmaceutical companies and biotechnology firms split procurement patterns by internal manufacturing heritage. Research institutes and academic centers access CDMO capacity through grant-funded consortia rather than direct commercial contracts.
- Pharmaceutical Companies:Large-cap sponsors with legacy biologics portfolios outsource overflow capacity and late-lifecycle products. Procurement concentrates in Ireland and Singapore for tax-advantaged supply chain structuring.
- Biotechnology Firms:Venture-backed developers without manufacturing infrastructure. Demand clusters in Boston and San Francisco, with CDMOs offering milestone-based payment structures to align with clinical progression risk.
- Research Institutes:Non-commercial investigational new drug applications and early-phase academic trials.
- Academic Centers:University-affiliated hospitals with investigator-initiated gene therapy programs.
Pharmaceutical companies anchor contract value. Biotechnology firms are expanding most quickly.
Service Type:
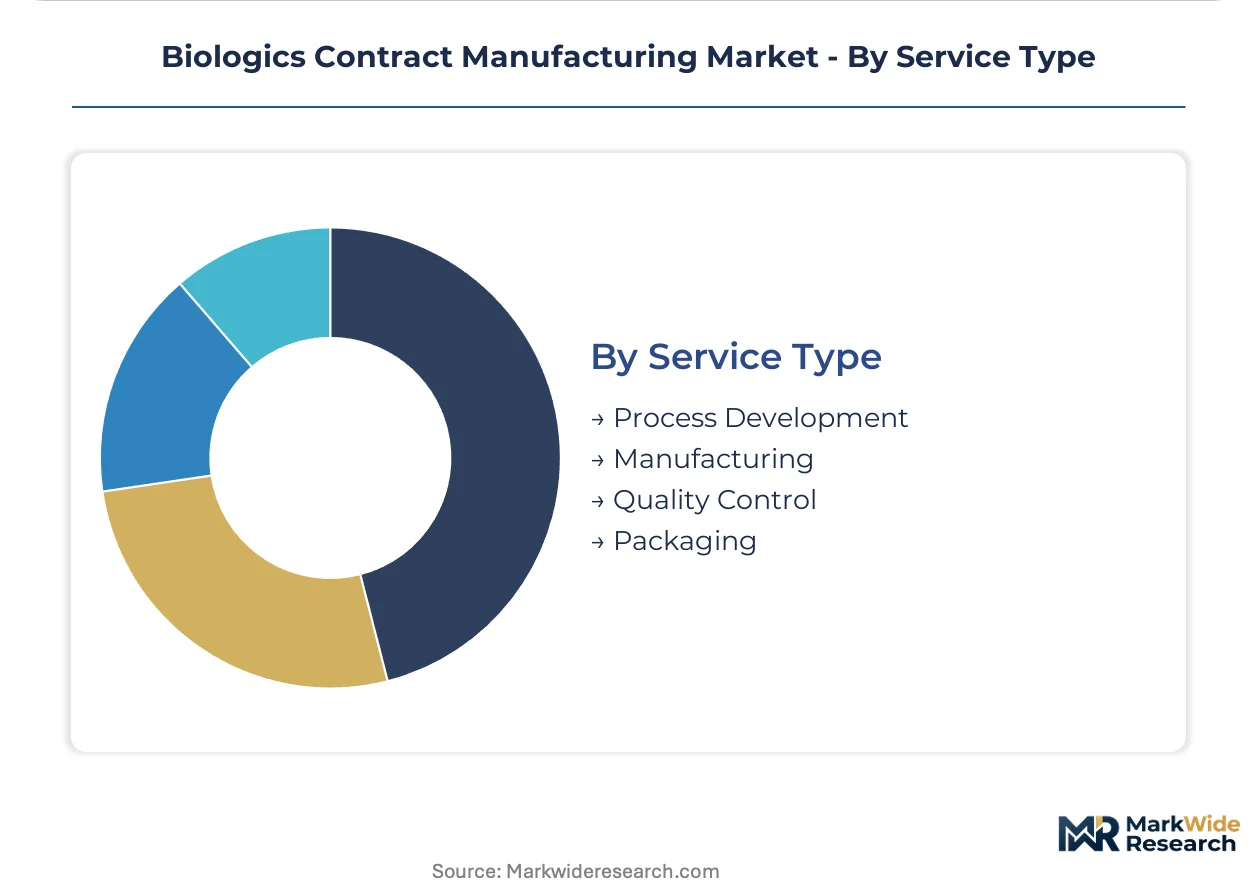
Process development and quality control command margin premiums through specialized expertise, while manufacturing and packaging face commoditization pressure from capacity expansion.
- Process Development:Cell line engineering, media optimization, and scale-up validation. Expertise concentrates near Basel and Cambridge, Massachusetts, where regulatory consulting integrates with technical services.
- Quality Control:Analytical method validation, release testing, and stability studies. CDMOs in the United States unbundle these services to dedicated laboratories in Boston and San Francisco, fragmenting the traditional full-service model.
- Manufacturing:Drug substance production and aseptic fill-finish operations.
- Packaging:Labeling, serialization, and cold chain distribution preparation.
Manufacturing commands the established base. Quality control is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in biologics contract manufacturing tilt toward net service exports from South Korea, Ireland, and Switzerland, while the United States and Germany absorb substantial inbound contract volumes for clinical-stage programs. Regulatory divergence between FDA Chemistry Manufacturing and Controls requirements and EMA Good Manufacturing Practice standards fragments cross-border batch release protocols.
United States
Biotechnology firms in Massachusetts and California drive demand for viral vector and cell therapy manufacturing slots. FDA's risk-based inspection model and gene therapy Chemistry Manufacturing and Controls guidance compress supplier qualification timelines. The Greater Boston cluster concentrates specialized analytical method development laboratories serving autologous cell therapy developers.
South Korea
Government-funded biotech incubators near Seoul and Incheon channel venture capital toward contract manufacturing infrastructure. MFDS alignment with FDA inspection protocols accelerates dual-approval pathways for export-oriented viral vector batches. Samsung Biologics anchors mammalian cell culture capacity at Songdo with dedicated gene therapy suites under construction.
Ireland
Tax-advantaged supply chain structuring attracts pharmaceutical companies establishing European distribution hubs for monoclonal antibodies. EMA centralized marketing authorization procedures require local batch release certification. The Dublin-Shannon corridor clusters fill-finish and serialization operations serving EMA-registered biologics.
Switzerland
Specialized microbial fermentation expertise from legacy small-molecule transitions supports biosimilar process development. Swissmedic coordinates inspection protocols with Germany's chemical regulator to reduce duplicate compliance costs. The Basel region concentrates regulatory consulting integrated with cell line engineering services.
India
CDSCO's streamlined biologics manufacturing license framework offers faster market entry for export-oriented viral vector production. Emerging market demand for affordable monoclonal antibody biosimilars pulls contract volume toward Hyderabad and Bangalore clusters. Domestic plasmid DNA supply constraints limit transfection-based gene therapy campaign expansion.
Biologics Contract Manufacturing Market Key Industry Players
Listed leaders compete with private specialists across capital access and strategic flexibility dimensions. The vendor base concentrates around three tiers: integrated life science conglomerates with analytical networks, pure-play biologics specialists with single-use platform expertise, and emerging Asian challengers with government-backed capacity expansion. Strategic moves center on multi-product GMP suite certification and continuous bioprocessing technology licensing rather than vertical integration into raw material supply.
Within the integrated conglomerate tier, Thermo Fisher Scientific and Lonza exemplify archetypes combining analytical services with manufacturing networks. Samsung Biologics anchors the scale-driven Asian challenger position. WuXi Biologics occupies a position bridging process development specialization with mammalian cell culture capacity. These three represent distinct competitive postures without overlapping core capabilities.
| Leading Market Players |
|---|
| Samsung Biologics |
| Boehringer Ingelheim |
| Thermo Fisher Scientific |
| AGC Biologics |
| Fujifilm Diosynth Biotechnologies |
| Lonza |
| WuXi Biologics |
| Rentschler Biotechnologie |
| Catalent |
| Others |
Cost & Logistics Intelligence
Capacity reservation agreements with multi-year offtake terms now dominate biologics CDMO contracting, locking biotechnology firms into price visibility while securing viral vector and mammalian cell culture slots ahead of clinical data readouts. This structure concentrates pricing power with Samsung Biologics, Lonza, and Thermo Fisher Scientific as qualified GMP suite availability tightens under FDA and EMA ATMP certification requirements.
Pricing Analysis
Biotechnology firms anchor contract pricing through milestone-based payment structures that defer manufacturing costs until Phase II data readouts. Three-tier pricing structure across premium ATMP-certified, standard GMP, and economy non-certified levels differentiates viral vector batches by containment complexity and regulatory pedigree. Cost compression in standard monoclonal antibody manufacturing is intensifying because single-use bioreactor platform commoditization erodes technical differentiation. Large-cap pharmaceutical companies exhibit lowest price sensitivity due to tax-advantaged supply chain structuring in Ireland and Singapore, while venture-backed developers negotiate aggressively on payment timing.
Supply Chain Analysis
United States and South Korea anchor viral vector and cell therapy manufacturing capacity, with Switzerland and Ireland specializing in microbial fermentation and fill-finish operations respectively. GMP-grade plasmid DNA, single-use bioreactor assemblies, and cell culture media formulations feed from concentrated supplier bases in Germany and the United States. Single-source vulnerability in plasmid DNA transfection inputs creates batch-to-batch consistency risks that propagate through gene therapy campaigns. Distribution runs through cold chain logistics networks serving FDA and EMA batch release sites, with cryopreservation requirements adding specialized handling layers for autologous cell products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward biotechnology firms as viral vector capacity scarcity forces CDMOs into longer development partnerships and milestone-aligned pricing. This consolidation of procurement leverage among venture-backed developers without manufacturing heritage compresses supplier selection timelines and inflates reservation premiums.
For Market Incumbents: Compound analytical service integration with manufacturing networks to defend against unbundling trends fragmenting the full-service CDMO model. Samsung Biologics and Lonza should expand multi-product GMP suite certification across Songdo and Swiss sites before emerging Asian challengers replicate single-use platform expertise. Capacity addition in South Korea leverages government-funded biotech incubators and MFDS-FDA alignment for dual-approval pathway acceleration. For New Entrants and Emerging Players: Lead with allogeneic cell therapy platform specialization where standardized batch production eliminates patient-matched manufacturing complexity that constrains autologous competitors. India offers the most penetrable geography for export-oriented viral vector production serving emerging markets, given CDSCO's streamlined biologics manufacturing license framework and lower plasmid DNA input cost exposure. Target analytical method development unbundling in Boston and San Francisco clusters where dedicated laboratories fragment traditional full-service procurement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among CDMOs with multi-year capacity reservation agreements and process development retainers rather than transactional manufacturing contracts. Long-term viability over the projection horizon rests on continuous bioprocessing technology licensing positions and AI-driven process analytics integration. Acquisition target archetype: mid-scale specialists with viral vector containment expertise and EMA ATMP certification nearing completion. Signal to watch: FDA inspection backlog resolution timelines as staffing constraints ease and pre-approval inspection queues compress.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Product GMP Suite Certification | EMA ATMP compliance separates certified viral vector capacity from commodity mammalian antibody manufacturing. |
| Continuous Bioprocessing Technology Licensing | Perfusion cell culture adoption reduces facility footprint requirements for Samsung Biologics and Lonza clients. |
| Analytical Method Development Unbundling | Boston and San Francisco laboratories fragment traditional full-service CDMO procurement patterns. |
| Allogeneic Cell Therapy Platform Investment | Off-the-shelf products eliminate patient-matched complexity and open standardized batch production capacity. |
| India CDSCO Manufacturing License Expansion | Streamlined framework accelerates export-oriented viral vector production for emerging market demand. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, CDMO procurement managers, and cell therapy manufacturing scientists. Secondary validation drew from FDA Chemistry Manufacturing and Controls guidance documents, EMA Good Manufacturing Practice submissions, ClinicalTrials.gov gene therapy protocol registrations, and CDSCO biologics manufacturing license databases. Bottom-up capacity utilization modeling and top-down market sizing triangulation anchored volume and value estimates across the analysis window.
Across the analysis window, the forecasting framework segmented biologics contract manufacturing by product type, service type, technology platform, and end-user archetype, with regional regulatory cluster as an additional dimension. CAGRs were derived from facility expansion announcements, capacity reservation contract visibility, and clinical pipeline progression rates. Industry-specific forecast inputs included viral vector batch complexity coefficients and single-use bioreactor platform adoption curves by geography.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EMA regulatory alignment, plasmid DNA supply stability, and continuous bioprocessing technology diffusion would require recalibration. Forecasts reflect documented assumptions regarding inspection timeline normalization and ATMP certification pipeline completion. Recalibration cycles align with material shifts in gene therapy clinical data readouts, CDMO capacity commissioning announcements, and regulatory divergence between FDA risk-based inspection models and EMA centralized marketing authorization pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Monoclonal Antibody Custom Service Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Polymerase Chain Reaction Reagent Market
Biotechnology Services
Luciferase Assay Market
Biotechnology Services
Bioanalytical Testing Services Market
Biotechnology Services
Proteinase K Market
Biotechnology Services
Global Alpha Galactosidase Market
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
Antibody Drug Conjugates Contract Manufacturing Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
Biotech API Manufacturing Services Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
Research Antibodies Market
Biotechnology Services
In Vivo CRO Market
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market