
 Cell Characterization Assays Kits Market | 2026-2036
Cell Characterization Assays Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Characterization Assays Kits Market Analytics
Biotechnology firms is broadening their share of end-use demand as cell therapy developers scale quality control workflows. Thermo Fisher Scientific leverages its consumables infrastructure to anchor recurring kit revenue across clinical and research segments. Merck KGaA sustains European manufacturing density for GMP-grade characterization reagents. BD Biosciences specializes in flow cytometry panel standardization that locks in multi-year assay contracts.
Cell characterization assays kits comprise standardized reagent systems—fluorochrome-conjugated antibodies, viability dyes, and functional readout substrates—designed for quantitative phenotyping, proliferation tracking, and functional analysis of living cell populations. These kits reduce inter-laboratory variability by providing pre-optimized buffer formulations and calibrated detection thresholds that comply with ISO 20391 cell counting standards. Flow cytometry kits command the largest revenue share due to their dominance in immune profiling and CAR-T release testing, while ELISA kits retain entrenched positions in cytokine quantification despite slower growth trajectories. Molecular probes represent the fastest-expanding technology segment as live-cell imaging platforms displace endpoint assays in drug discovery pipelines.
FDA enforces cell and gene therapy potency assay guidelines under 21 CFR 610, while EMA's ATMP framework mandates characterization consistency across manufacturing sites. ISO 20391 and CLSI H52 standards shape kit calibration protocols that determine market access for vendors serving regulated biopharma clients. Stakeholders must monitor evolving FDA guidance on comparability protocols and EMA reflection papers on analytical method lifecycle management as these will dictate R&D allocation and kit validation roadmaps.
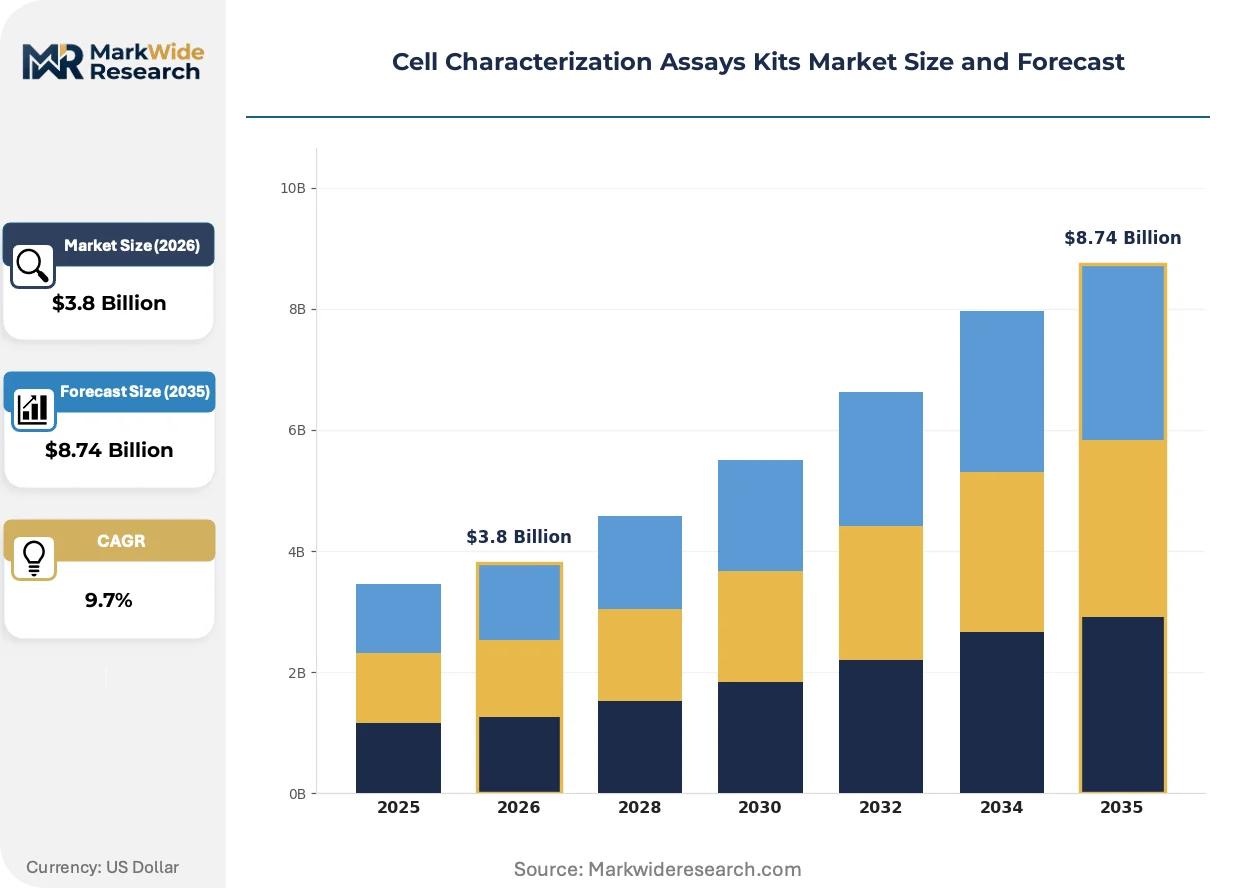
Market Dynamics
Cell therapy manufacturers are consolidating quality control workflows around standardized, GMP-compliant assay kits to meet FDA potency assay requirements under 21 CFR 610, compressing validation timelines and locking in multi-year supply contracts with certified vendors.
Growth Catalysts
- ATMP Framework Enforcement:EMA's Advanced Therapy Medicinal Products regulations mandate characterization consistency across manufacturing sites, forcing cell therapy developers to adopt pre-validated kit systems rather than home-brewed assays.
- CAR-T Release Testing:Commercialization of autologous cell therapies requires standardized flow cytometry panels for identity, purity, and potency testing at clinical scale.
- ISO 20391 Calibration Mandates:Cell counting standardization across biopharma contract manufacturing organizations drives replacement of manual methods with kit-based automated platforms.
Market Restraints
- Fluorochrome Supply Concentration:Specialty dye synthesis concentrates among a handful of chemical suppliers, creating input cost volatility and batch-to-batch variability risks for conjugated antibody production.
- GMP Certification Barriers:EMA and FDA manufacturing site inspections impose 18-24 month timelines for kit producers seeking regulated market access, freezing out smaller reagent vendors.
- Endpoint Assay Substitution:Live-cell imaging platforms are displacing traditional viability and proliferation kits in early-stage drug discovery, compressing addressable demand in research segments.
Strategic Opportunities
- Chinese NMPA Pathway:Domestic cell therapy developers in China face evolving characterization requirements under NMPA technical guidelines, creating white space for GMP-grade kit localization.
- Gene Editing QC Convergence:CRISPR-based cell engineering workflows require integrated on-target and off-target characterization, merging molecular and cellular assay categories.
- Digital Distribution Channels:Direct e-procurement platforms are penetrating mid-tier biotech procurement, displacing traditional distributor markups for standard research-use kits.
Industry Challenges
- Multi-Platform Validation Expertise:Kit developers must maintain proficiency across flow cytometry, imaging cytometry, and high-content screening modalities simultaneously, stretching technical teams thin.
- Legacy LIMS Integration:Biopharma quality systems built on decade-old laboratory information management architectures resist seamless data capture from modern assay platforms, delaying kit deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Characterization Assays Kits Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Cytometry Kits, Microscopy Kits, ELISA Kits, Western Blot Kits End User: Academic Institutions, Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations Technology: Fluorescent Labeling, Bioluminescent Labeling, Colorimetric Assays, Molecular Probes Application: Cancer Research, Drug Discovery, Stem Cell Research, Immune Profiling |
| Companies Covered | AYOXXA Biosystems, Merck KGaA, STEMCELL Technologies, Enzo Life Sciences, HemoGenix, Thermo Fisher Scientific, PELO Biotech, R&D Systems, BD Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Characterization Assays Kits Market Evolving Landscape
Standardized reagent systems are yielding to modular, configurable platforms as cell therapy workflows fragment across autologous, allogeneic, and iPSC-derived product classes. Three forces are compressing development cycles and reshaping vendor-customer relationships.
Microfluidic sample preparation is decentralizing cell characterization workflows by miniaturizing staining and acquisition steps onto chip-based platforms. Academic core facilities and mid-size biotechs are adopting these systems to reduce sample volume requirements and eliminate centrifugation steps. This technology is decentralizing analytical capacity from centralized service labs toward point-of-need deployment in manufacturing suites.
EMA's reflection papers on analytical method lifecycle management are tightening post-approval change control requirements for commercial cell therapies. Kit vendors must now commit to multi-year formulation stability and supply continuity guarantees to retain GMP contracts. European contract development and manufacturing organizations are responding by consolidating supplier panels and demanding audit rights over sub-tier reagent sources.
Subscription-based reagent procurement is displacing transactional purchasing in high-throughput screening operations. Biopharma discovery groups are unbundling kit components and negotiating annual consumption contracts directly with raw material suppliers, bypassing branded kit markups. This pattern is most visible in United States coastal clusters where venture-backed cell therapy startups prioritize burn rate management over vendor loyalty.
Cell Characterization Assays Kits Market Segmentation
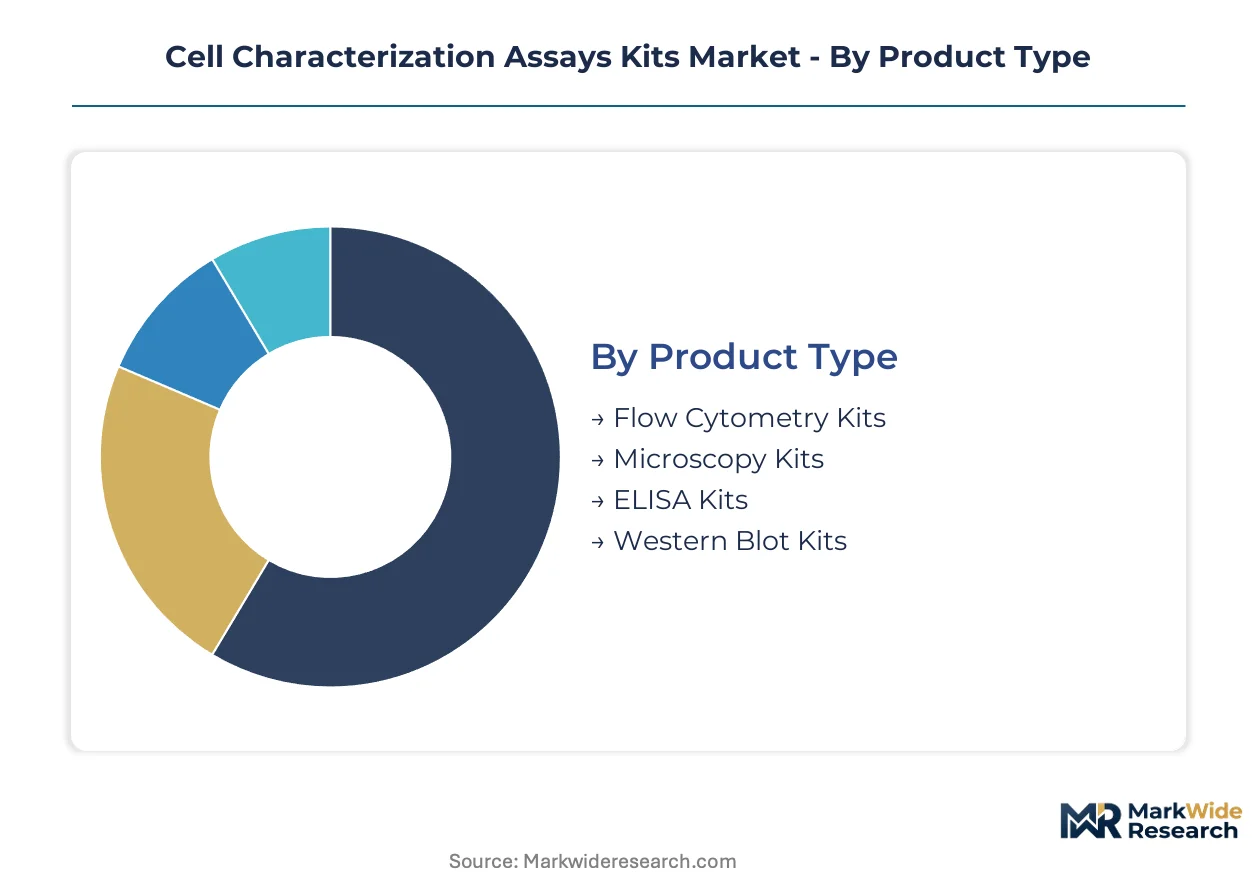
Cell characterization assays kits fragment across four intersecting dimensions. Product type determines technical capabilities and price positioning. End-user concentration shapes regulatory requirements and procurement patterns. Technology choice governs sensitivity thresholds and workflow integration. Application focus dictates panel complexity and validation depth.
Product Type:
Flow cytometry kits command premium pricing through clinical-grade validation, while microscopy and Western blot kits compete on research-volume economics.
- Flow Cytometry Kits:These systems bundle fluorochrome-conjugated antibodies, calibration beads, and acquisition buffers optimized for multi-parameter immune profiling. CAR-T manufacturers in the United States and Germany require standardized panels for identity and purity testing under FDA 21 CFR 610 and EMA ATMP frameworks, locking in multi-year supply contracts with certified vendors.
- Microscopy Kits:Live-cell imaging reagents including viability dyes, proliferation trackers, and organelle-specific probes enable kinetic phenotyping without endpoint sacrifice. Mid-tier biotechs in Boston and San Diego are displacing traditional viability assays with these platforms to reduce cell consumption in high-throughput screening.
- ELISA Kits:Cytokine quantification workhorses retain entrenched positions in bioprocess monitoring despite slower expansion trajectories.
- Western Blot Kits:Protein expression validation tools serve basic research segments with lower regulatory burden and price compression.
Today's leader: Flow Cytometry Kits. Tomorrow's challenger: Microscopy Kits.
End User:
Pharmaceutical companies and biotechnology firms concentrate purchasing power through consolidated procurement, while academic institutions and CROs fragment demand across project-based budgets.
- Pharmaceutical Companies:Large-cap developers impose GMP-grade specifications, audit rights, and multi-year supply continuity guarantees on kit vendors serving commercial cell therapy programs.
- Biotechnology Firms:Venture-backed cell therapy developers in United States coastal clusters prioritize burn rate management, driving unbundling of kit components and direct raw material sourcing to bypass branded markups.
- Academic Institutions:Core facilities adopt microfluidic sample preparation platforms to miniaturize workflows and reduce centrifugation steps, decentralizing analytical capacity from service labs toward point-of-need deployment.
- Contract Research Organizations:European CDMOs are consolidating supplier panels and demanding sub-tier reagent audit rights under tightening EMA post-approval change control requirements.
Biotechnology firms are gaining share fastest as cell therapy developers scale quality control workflows. Pharmaceutical companies retain the largest contract values.
Technology:
Fluorescent and bioluminescent labeling dominate current workflows, while molecular probes are climbing the fastest as live-cell imaging displaces endpoint methods.
- Fluorescent Labeling:Mature conjugation chemistry supports standardized panel development across flow cytometry and imaging platforms, though specialty dye synthesis concentration among limited chemical suppliers creates input cost volatility.
- Bioluminescent Labeling:ATP-based viability assays and reporter gene systems serve high-throughput screening operations with minimal equipment requirements.
- Colorimetric Assays:Simple absorbance-based readouts persist in resource-constrained settings but face displacement by more sensitive methods.
- Molecular Probes:Genetically encoded indicators and targeted chemical reporters enable longitudinal tracking of signaling dynamics, gaining traction in drug discovery pipelines seeking kinetic over snapshot data.
Fluorescent Labeling anchors current revenue. Molecular Probes represent the steepest expansion trajectory.
Application:
Cancer research and immune profiling concentrate clinical-grade demand, while drug discovery and stem cell research span broader research-use segments.
- Cancer Research:Tumor microenvironment characterization and circulating tumor cell isolation require complex multi-marker panels with stringent reproducibility standards.
- Immune Profiling:CAR-T and TCR-T development programs in the United States, Germany, and China drive demand for standardized identity, purity, and potency assays at commercial scale.
- Drug Discovery:Phenotypic screening campaigns prioritize throughput and cost efficiency over clinical-grade validation.
- Stem Cell Research:Pluripotency marker panels and differentiation trajectory tracking serve regenerative medicine pipelines with evolving characterization requirements under NMPA technical guidelines in China.
Immune Profiling commands premium pricing through regulatory necessity. Stem Cell Research is expanding most quickly as iPSC-derived products diversify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Kendall Square corridor concentrates the highest density of cell therapy developers purchasing GMP-grade characterization kits under FDA 21 CFR 610 potency assay requirements.
United States
CAR-T commercialization programs in Massachusetts and California drive standardized flow cytometry panel procurement for identity and purity testing. FDA enforces cell and gene therapy potency guidelines under 21 CFR 610, compressing validation timelines for kit vendors. The San Diego biotech cluster adopts live-cell imaging platforms to reduce cell consumption in high-throughput screening operations.
Germany
EMA's ATMP framework mandates characterization consistency across manufacturing sites, forcing adoption of pre-validated kit systems. Heidelberg and Munich host dense networks of contract development and manufacturing organizations consolidating supplier panels under tightening post-approval change control requirements. German CDMOs now demand multi-year formulation stability guarantees and audit rights over sub-tier reagent sources.
China
Domestic iPSC-derived product developers face evolving characterization requirements under NMPA technical guidelines, creating demand for localized GMP-grade kit production. Shanghai and Suzhou biotech parks attract foreign kit vendors establishing regional manufacturing to bypass import tariffs. Chinese cell therapy startups prioritize cost-efficient procurement through direct raw material sourcing.
United Kingdom
London and Cambridge cell therapy hubs require ISO 20391-compliant calibration standards for automated cell counting platforms replacing manual methods. The Medicines and Healthcare products Regulatory Agency aligns with EMA ATMP frameworks for commercial release testing. British academic core facilities adopt microfluidic sample preparation systems to decentralize analytical capacity from centralized service labs.
Switzerland
Basel's pharmaceutical manufacturing base sources clinical-grade characterization reagents under Swissmedic GMP certification requirements. Swiss contract manufacturers emphasize supply continuity guarantees for commercial cell therapy programs. The country's precision medicine initiatives drive demand for multi-parameter immune profiling panels in personalized oncology workflows.
Cell Characterization Assays Kits Market Competitive Landscape
Strategic partnerships dominate the current landscape as kit vendors secure multi-year supply contracts with cell therapy developers seeking GMP compliance. The market structure concentrates around three tiers: diversified life science conglomerates with consumables infrastructure, European specialists in GMP-grade reagent manufacturing, and regional distributors serving research-use segments. Two archetypes define competitive positioning: integrated platform providers bundling hardware and reagents, and modular kit specialists unbundling components for cost-sensitive biotechs. M&A activity and geographic licensing agreements represent the primary expansion vectors.
Among diversified conglomerates, Thermo Fisher Scientific and Merck KGaA exemplify the integrated platform archetype through consumables infrastructure and European manufacturing density respectively. BD Biosciences occupies a position within the flow cytometry standardization tier. STEMCELL Technologies and Enzo Life Sciences sit within the research-use specialist segment serving academic core facilities. These five named entities collectively span the regulatory spectrum from clinical-grade GMP supply to discovery-stage reagent procurement.
| Leading Market Players |
|---|
| AYOXXA Biosystems |
| Merck KGaA |
| STEMCELL Technologies |
| Enzo Life Sciences |
| HemoGenix |
| Thermo Fisher Scientific |
| PELO Biotech |
| R&D Systems |
| BD Biosciences |
| Others |
Value Network & Pricing Analysis
EMA's reflection papers on analytical method lifecycle management gate qualified supply for GMP-grade kit vendors and enforce premium-tier pricing access through multi-year formulation stability guarantees. Buyers without certified supplier status face compressed margins as EMA and FDA manufacturing site inspections impose 18-24 month qualification timelines that freeze out smaller reagent vendors.
Pricing Analysis
Distributor markups of 25-40% persist in research-use segments while direct e-procurement platforms penetrate mid-tier biotech procurement. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade GMP kits from research-use reagents and basic discovery tools. Cost compression in standard-tier flow cytometry panels is intensifying because biotech startups unbundle kit components to bypass branded markups through direct raw material sourcing. Academic core facilities demonstrate highest price sensitivity; pharmaceutical companies purchasing under multi-year supply contracts show lowest sensitivity due to audit and continuity requirements.
Supply Chain Analysis
Cold-chain logistics costs for fluorochrome-conjugated antibodies concentrate supply risk in United States, Germany, and China manufacturing corridors. Specialty dye synthesis draws from limited chemical suppliers in Switzerland and Japan, creating input cost volatility for conjugated antibody production. Single-source vulnerability in GMP-grade buffer formulations threatens batch-to-batch consistency for commercial cell therapy programs. Distribution runs through authorized distributors for GMP segments and direct platforms for research-use kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cell characterization assays kits rests on burn-rate-sensitive biotechs accepting premium pricing for GMP certification while cost-down pressure intensifies in research-use segments through component unbundling.
For Market Incumbents: Anchor multi-year supply contracts through GMP certification investments that lock in pharmaceutical company procurement under FDA 21 CFR 610 and EMA ATMP frameworks. Deepen backward integration into fluorochrome dye synthesis to defend against specialty chemical supplier concentration. Prioritize channel control over distributor relationships as direct e-procurement platforms threaten markup capture in mid-tier segments. For New Entrants and Emerging Players: Enter via NMPA technical guideline compliance for Chinese iPSC-derived product developers facing evolving characterization requirements. Target stem cell research applications as fastest-expanding segment with less entrenched supplier relationships than immune profiling. Pursue microfluidic sample preparation platform partnerships as go-to-market angle to decentralize analytical capacity from established flow cytometry incumbents. For Investors and Strategic Acquirers: Roll-up economics work for modular kit specialists because EMA post-approval change control requirements are consolidating supplier panels among European CDMOs demanding audit rights over sub-tier reagent sources. Five-to-ten year viability favors acquisition targets with GMP-grade manufacturing density and multi-year formulation stability commitments. Watch FDA guidance on comparability protocols as inflection indicator for R&D allocation shifts that favor pre-validated kit systems over home-brewed assays.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | EMA and FDA manufacturing site inspections enforce 18-24 month qualification timelines that freeze out smaller reagent vendors. |
| Backward Integration into Dye Synthesis | Specialty fluorochrome synthesis concentration among limited chemical suppliers creates input cost volatility for conjugated antibody production. |
| Direct E-Procurement Platform Launch | Mid-tier biotechs in United States coastal clusters prioritize burn rate management over distributor loyalty for research-use kits. |
| Microfluidic Platform Partnership | Academic core facilities adopt chip-based sample preparation to miniaturize workflows and eliminate centrifugation steps. |
| Chinese NMPA Localization | Domestic iPSC-derived product developers in Shanghai and Suzhou biotech parks face evolving characterization requirements under NMPA technical guidelines. |
Research Methodology
Coverage spans United States, Germany, China, and United Kingdom, with primary inputs from each regional cluster combining executive interviews with cell therapy developers, regulatory affairs leads at kit vendors, CDMO procurement managers, and academic core facility directors. Secondary validation draws from FDA 21 CFR 610 guidance documents, EMA ATMP framework reflection papers, NMPA technical guidelines, ISO 20391 calibration standards, and SEC filings of diversified life science conglomerates. Bottom-up demand modeling from end-user procurement patterns triangulates against top-down supply-side capacity assessments.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, end-user concentration, technology choice, and application focus with particular attention to CAR-T release testing scale-up and iPSC-derived product diversification. CAGRs derive from fitted growth curves calibrated to regulatory enforcement timelines and cell therapy commercialization milestones. Industry-specific forecast inputs include EMA post-approval change control implementation pace and NMPA technical guideline evolution for Chinese domestic developers.
Inputs from FDA guidance documents and EMA reflection papers were available through the study window; gaps in real-time NMPA enforcement data introduce uncertainty bands around Chinese market penetration assumptions. Forecasts reflect modeled assumptions about regulatory timeline adherence and cell therapy manufacturing scale-up rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
Molecular Methods Market
Biotechnology Services
Cell Lysis and Disruption Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Precast Agarose Gel Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market
Biotechnology Services
Global Downstream Processing Market
Biotechnology Services
Membrane Protein Characterization Service Market
Biotechnology Services
Recombinant Factor C Assay Market
Biotechnology Services
Cell Line Development Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market
Biotechnology Services
Aptamers Market
Biotechnology Services
Biologics CDMO Market