
 Organic Cassava Flour Market | 2026-2036
Organic Cassava Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Cassava Flour Market Analytics
Skilled agricultural labor availability across West African cassava belts is unwinding traditional harvest constraints and enabling mechanized peeling operations. Psaltry International anchors its supply chain through backward integration into Nigerian smallholder networks. DADTCO Rivers Cassava Processing Company leverages mobile processing units to reduce post-harvest losses in rural Tanzania. Ingredion Incorporated competes on industrial-scale hydrothermal treatment technology for modified cassava starch derivatives.
Organic cassava flour denotes the dried, milled endosperm of Manihot esculenta roots cultivated without synthetic pesticides or fertilizers, typically exhibiting 8-12% moisture content and less than 0.5% residual cyanogenic compounds after controlled fermentation and sun-drying or flash-drying protocols. The material functions primarily as a viscoelastic wheat flour substitute in gluten-free formulations and as a clean-label thickening agent in soups, sauces, and gravies. Gluten-Free Flour dominates product type revenue pools due to premium positioning in celiac-sensitive and paleo-diet consumer segments, while Snack Products represents the fastest-expanding category as extruded chip and puff manufacturers reformulate with grain-free bases. Health Food Stores capture disproportionate margin concentration through certified organic SKUs, though Online Retail is displacing traditional specialty distribution in urban North American and European markets.
EU Organic Regulation (EC) 2018/848 governs cultivation and processing standards for cassava flour sold within European Union member states, while FDA gluten-free labeling rules enforce the 20 ppm threshold for products marketed in the United States. Nigeria's National Agency for Food and Drug Administration and Control (NAFDAC) and Tanzania's Tanzania Bureau of Standards (TBS) additionally certify export-grade organic status for regional processors. Stakeholders must monitor evolving maximum residue limits for cyanogenic glycosides across importing jurisdictions and assess whether in-house detoxification investments or third-party toll processing delivers superior unit economics at scale.
Market Dynamics
Mechanized peeling and flash-drying investments are compressing unit costs for Nigerian and Tanzanian processors, enabling export-grade organic cassava flour to compete with wheat alternatives in North American and European gluten-free formulations.
Growth Catalysts
- EU Organic Regulation (EC) 2018/848:Mandatory certification protocols for third-country imports are consolidating demand around verified African suppliers with established audit trails.
- Gluten-free bakery reformulation:Clean-label mandates from major North American retailers are pulling volume toward grain-free bases that use cassava flour as a viscoelastic wheat substitute.
- Mobile processing units:Tanzanian deployment of containerized flash-drying equipment is reducing post-harvest losses below traditional sun-drying methods.
Market Restraints
- Input cost volatility:Synthetic fertilizer price swings in Nigerian input markets create margin pressure for smallholder cooperatives transitioning to organic cultivation protocols.
- Supply concentration risk:Nigerian processing capacity clusters in Oyo and Ogun states, exposing buyers to localized weather disruptions and logistics bottlenecks.
- Technical limitation:Residual cyanogenic compound thresholds below 0.5% require controlled fermentation cycles that extend processing timeframes versus conventional cassava flour.
Strategic Opportunities
- Underpenetrated geography:German health food retailers currently stock limited organic cassava SKUs, creating shelf-space expansion potential for certified exporters.
- Regulatory tailwind:FDA gluten-free labeling rules enforcing the 20 ppm threshold advantage dedicated cassava facilities over multi-grain processors with cross-contamination risk.
- Technology convergence:Near-infrared spectroscopy paired with blockchain traceability is enabling real-time cyanogenic compound verification for premium pricing tiers.
Industry Challenges
- Skill gap in mechanized harvesting:West African agricultural labor pools lack training for tractor-mounted uprooting equipment, constraining throughput scaling.
- Certification timeline compression:EU Organic Regulation conversion periods require 24-36 months for land certification, delaying revenue recognition for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Cassava Flour Market |
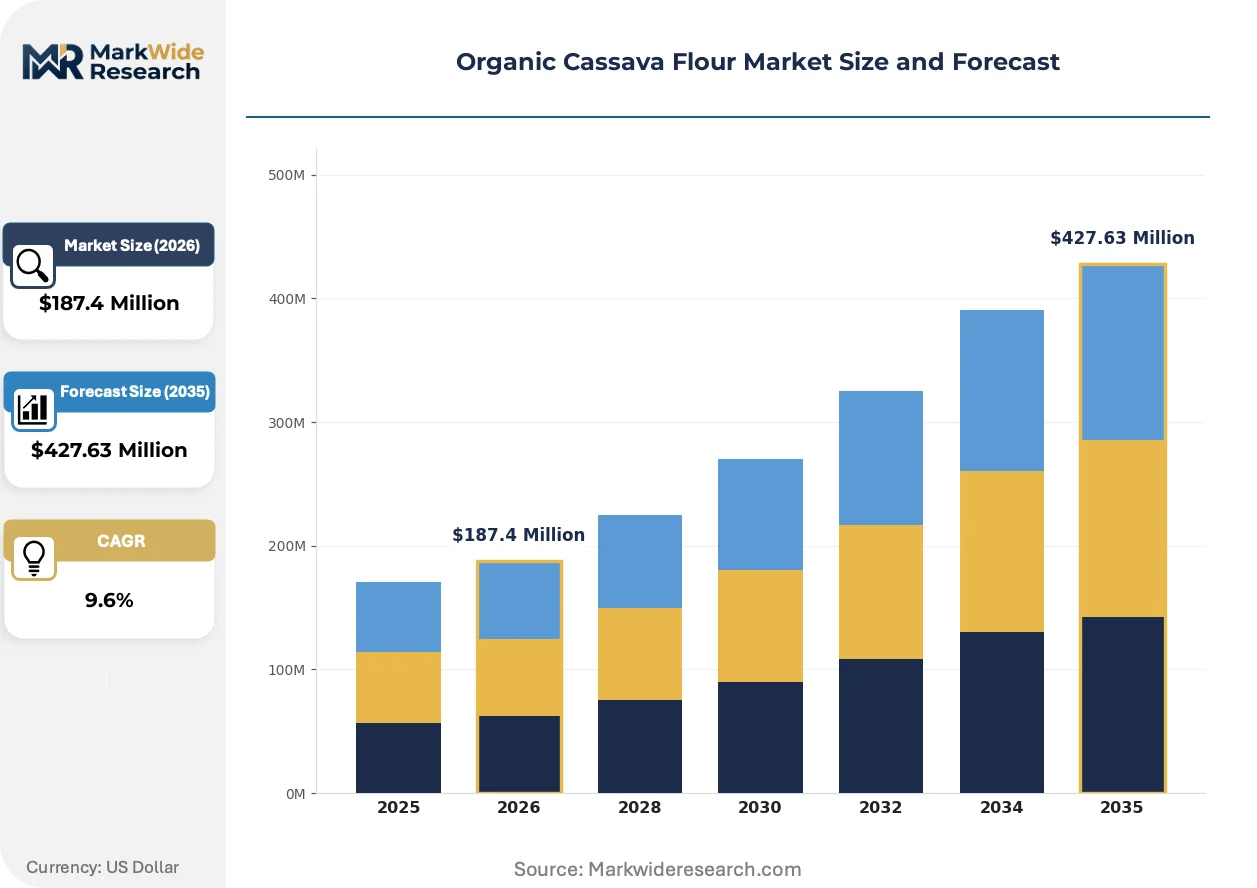
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free Flour, Baking Mix, Snack Products, Thickening Agent End User: Food Manufacturers, Bakery Outlets, Snack Producers, Home Consumers Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Specialty Shops Application: Baking, Cooking, Gluten-Free Products, Vegan Recipes |
| Companies Covered | Otto's Naturals, Psaltry International, DADTCO Rivers Cassava Processing Company, Green Hills Natural Foods, MHOGO Foods, Anthonys Goods, American Key Food Products, Edward & Sons Trading Co, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Cassava Flour Market Evolving Landscape
Flash-drying protocols and blockchain-enabled traceability are reconfiguring how organic cassava flour moves from Tanzanian smallholders to European gluten-free manufacturers.
Flash-drying technology is fragmenting traditional supply relationships by enabling rural Tanzanian cooperatives to produce export-grade flour without centralized factory infrastructure. Smallholder networks in Mtwara and Lindi regions are adopting containerized units that reduce moisture content to 8-12% within six hours of harvest. This capability is compressing the historical dominance of Nigerian bulk processors who relied on sun-drying cycles lasting 48-72 hours.
EU Organic Regulation (EC) 2018/848 is tightening third-country equivalence requirements for cassava flour entering European Union member states. The regulation mandates annual inspections of Nigerian and Tanzanian processing facilities by EU-accredited bodies. Gluten-free bakery manufacturers in Germany and the Netherlands are responding by consolidating supplier lists around cooperatives with pre-certified audit documentation.
Buyer concentration among North American paleo-diet retailers is forcing channel restructuring away from traditional food-service distributors. Direct-to-manufacturer contracts now account for growing volume share as brands like Simple Mills and Siete Foods source identity-preserved organic cassava flour with verified smallholder provenance. This pattern is most visible in Colorado and California, where clean-label formulation teams prioritize supply chain transparency over commodity pricing.
Organic Cassava Flour Market Segmentation
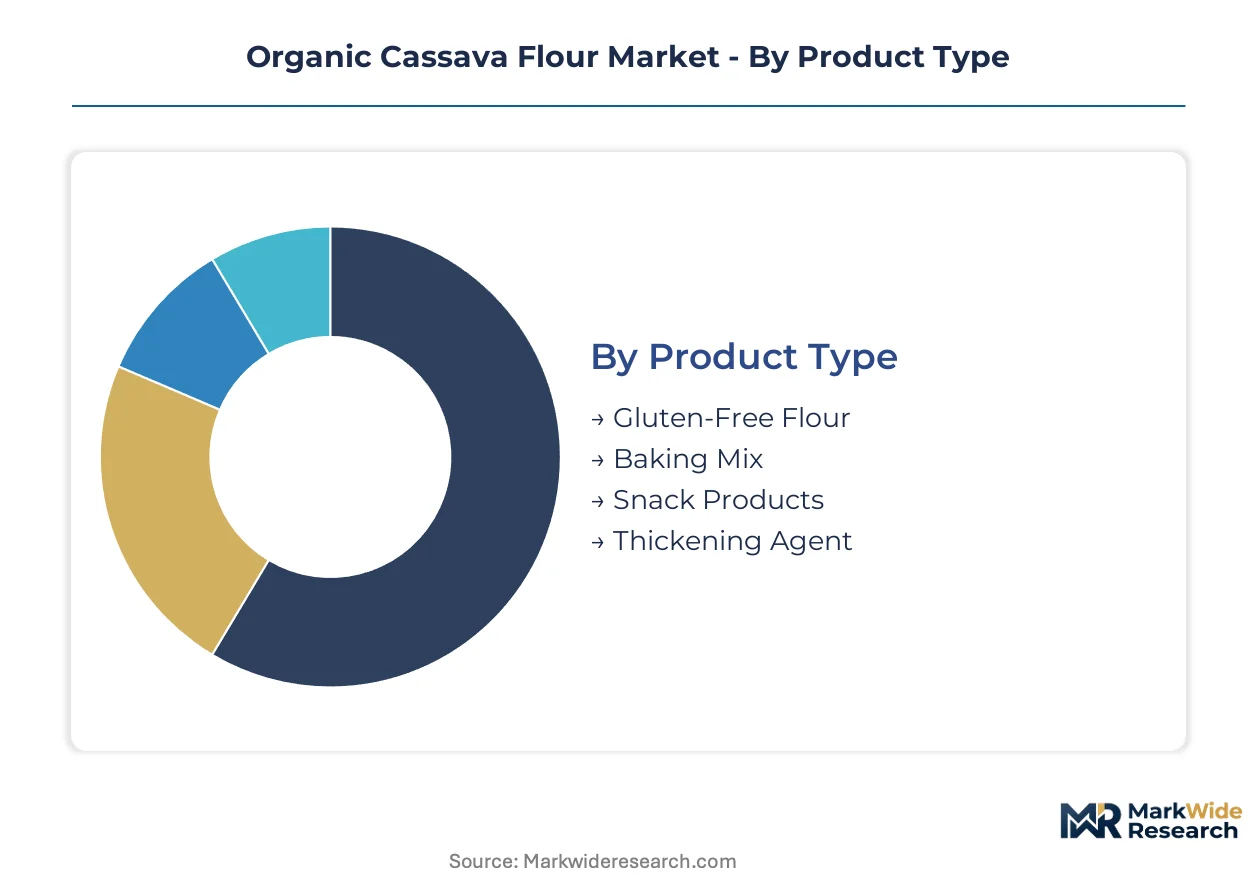
Segmentation reveals how organic cassava flour flows through distinct value pools. Product type determines processing investment intensity. Distribution channel governs margin capture. End user and application shape formulation specifications and certification requirements.
Product Type:
Margin pools concentrate in premium-positioned formats where clean-label certification commands pricing power over commodity alternatives.
- Gluten-Free Flour:Dried, milled endosperm with 8-12% moisture content and sub-0.5% residual cyanogenic compounds after controlled fermentation. Celiac-sensitive consumers in Germany and the Netherlands drive volume through verified 20 ppm gluten thresholds. FDA labeling rules advantage dedicated cassava facilities over multi-grain processors with cross-contamination exposure.
- Snack Products:Extruded chip and puff bases requiring grain-free reformulation. Paleo-diet retailers in Colorado and California source identity-preserved organic cassava flour with blockchain-verified smallholder provenance. This segment is climbing the fastest as manufacturers abandon corn and rice substrates.
- Baking Mix:Pre-blended formulations combining cassava flour with leavening agents and stabilizers for home consumer convenience.
- Thickening Agent:High-amylopectin fractions for soups, sauces, and gravies in clean-label food service applications.
Gluten-Free Flour holds installed capacity. Snack Products is rotating up the share rankings.
End User:
Volume concentration follows industrial buyers with direct smallholder contracting capabilities and in-house quality verification infrastructure.
- Food Manufacturers:Industrial-scale gluten-free and paleo-diet brands with formulation teams prioritizing supply chain transparency over commodity pricing. Simple Mills and Siete Foods maintain direct-to-cooperative contracts bypassing traditional distributors.
- Snack Producers:Extruded product manufacturers reformulating with grain-free bases. Containerized flash-drying units in Mtwara and Lindi regions enable rural Tanzanian cooperatives to meet export specifications without centralized factory infrastructure.
- Bakery Outlets:Artisan gluten-free bakeries requiring small-batch certified organic SKUs with verified provenance documentation.
- Home Consumers:Paleo-diet and celiac-sensitive households purchasing through online retail channels displacing traditional specialty distribution.
Food Manufacturers dominate procurement volume. Snack Producers are expanding most quickly through reformulation mandates.
Distribution Channel:
Channel selection determines whether margin accrues to certified organic positioning or volume throughput efficiency.
- Health Food Stores:Certified organic SKUs with disproportionate margin concentration through premium shelf positioning. German health food retailers currently stock limited organic cassava SKUs, creating expansion potential for verified exporters with pre-certified EU Organic Regulation documentation.
- Online Retail:Direct-to-consumer platforms displacing traditional specialty distribution in urban North American and European markets. Buyer concentration among paleo-diet retailers forces channel restructuring away from food-service distributors.
- Supermarkets:Mainstream retail placement requiring price-competitive positioning against wheat alternatives and conventional gluten-free flours.
- Specialty Shops:Ethnic and natural food boutiques serving celiac-sensitive communities with curated product selections.
Health Food Stores retain premium positioning. Online Retail is gaining share fastest through direct manufacturer relationships.
Application:
Application segmentation tracks how functional properties align with formulation requirements across wheat-substitution and clean-label thickening use cases.
- Gluten-Free Products:Viscoelastic wheat flour substitution in celiac-sensitive formulations requiring 20 ppm gluten thresholds. EU Organic Regulation third-country equivalence requirements consolidate demand around Nigerian and Tanzanian cooperatives with established audit trails.
- Baking:Bread, pastry, and confectionery applications leveraging cassava flour's neutral flavor profile and fine particle size distribution.
- Cooking:Traditional African and Latin American preparations maintaining cultural authenticity through organic cultivation protocols.
- Vegan Recipes:Plant-based formulations excluding grain, dairy, and egg ingredients simultaneously.
Gluten-Free Products anchor formulation demand. Baking is rotating up the share rankings through clean-label bakery expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German health food retailers consume organic cassava flour primarily through certified gluten-free bakery channels, while Nigerian buyers deploy it as a viscoelastic wheat substitute in industrial formulations. Tanzanian demand concentrates in export-grade flash-dried output for European snack manufacturers. This consumption-mix differential shapes where processing investments flow and which certification protocols dominate procurement decisions.
United States
Paleo-diet retailers in Colorado and California source identity-preserved organic cassava flour with verified smallholder provenance. FDA gluten-free labeling rules enforcing the 20 ppm threshold advantage dedicated cassava facilities over multi-grain processors with cross-contamination exposure. Clean-label formulation teams in Boulder and Los Angeles prioritize supply chain transparency over commodity pricing.
Germany
Celiac-sensitive consumers in Berlin and Munich drive volume through verified 20 ppm gluten thresholds for bakery applications. EU Organic Regulation (EC) 2018/848 mandates annual inspections of African processing facilities by EU-accredited bodies. German health food retailers currently stock limited organic cassava SKUs, creating shelf-space expansion potential for pre-certified exporters.
Nigeria
Smallholder processing cooperatives in Oyo and Ogun states scale output to serve export channels for North American gluten-free manufacturers. NAFDAC certifies export-grade organic status for regional processors seeking third-country equivalence under EU Organic Regulation. Psaltry International anchors supply chains through backward integration into Nigerian smallholder networks.
Tanzania
Rural cooperatives in Mtwara and Lindi regions adopt containerized flash-drying units that reduce moisture content to export specifications within six hours of harvest. Tanzania Bureau of Standards certifies organic status for regional processors accessing European Union member states. DADTCO Rivers Cassava Processing Company leverages mobile processing units to reduce post-harvest losses.
Netherlands
Gluten-free bakery manufacturers in Rotterdam and Amsterdam consolidate supplier lists around cooperatives with pre-certified EU Organic Regulation audit documentation. EFSA maximum residue limits for cyanogenic glycosides shape import inspection protocols at Rotterdam port facilities. Dutch traders intermediate between Tanzanian flash-drying cooperatives and German retail distributors.
Organic Cassava Flour Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in organic cassava flour supply chains. Nigerian and Tanzanian processors with captive smallholder networks compete against North American brands with direct-to-retailer distribution relationships. Three archetypes dominate: vertically integrated African processors controlling cultivation through export, North American clean-label brands with formulation expertise, and industrial ingredient suppliers with hydrothermal treatment capabilities. Competitive moves concentrate on backward integration into smallholder networks and flash-drying capacity expansion in East African rural zones.
Within the vertically integrated processor tier, Psaltry International and DADTCO Rivers Cassava Processing Company exemplify African-origin supply chain control, while Ingredion Incorporated occupies a position representing industrial-scale modified starch derivatives. These three entities anchor distinct competitive vectors: Nigerian smallholder network penetration, Tanzanian mobile processing unit deployment, and North American hydrothermal treatment technology.
| Leading Market Players |
|---|
| Otto's Naturals |
| Psaltry International |
| DADTCO Rivers Cassava Processing Company |
| Green Hills Natural Foods |
| MHOGO Foods |
| Anthonys Goods |
| American Key Food Products |
| Edward & Sons Trading Co |
| Ingredion Incorporated |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Nigerian cooperatives and North American gluten-free manufacturers lock in both supply access and price visibility, insulating buyers from spot-market volatility in cassava root inputs while securing EU Organic Regulation compliance documentation for European market entry.
Pricing Analysis
Contract-based long-term offtake structures dominate procurement between African processors and North American paleo-diet brands, with price differentiation driven by EU Organic Regulation certification tier and blockchain-verified smallholder provenance. Cost compression in standard-grade unverified flour is intensifying because Tanzanian mobile processing units are expanding export-grade capacity. Food manufacturers with direct-to-cooperative relationships exhibit least price sensitivity, while commodity traders serving mainstream supermarkets face acute margin pressure.
Supply Chain Analysis
Container availability on the Dar es Salaam-Rotterdam trade lane shapes landed cost structures for Tanzanian flash-dried output, with Nigerian supply from Lagos-Apapa ports drawing from Oyo and Ogun state processing clusters. Raw material dependencies center on organic cassava root stock, synthetic fertilizer substitutes for transitional cultivation, and diesel fuel for mechanized peeling operations. Single-source vulnerability concentrates in EU-accredited certification bodies for third-country equivalence audits. Distribution runs through Dutch trader intermediaries to German health food retailers and direct-to-manufacturer contracts for North American clean-label brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service offerings represent a faster-expanding revenue layer than commodity flour sales, as African cooperatives monetize audit-trail documentation and EU Organic Regulation compliance support to downstream manufacturers seeking supply chain transparency.
For Market Incumbents: Compound backward integration into Tanzanian smallholder networks with flash-drying unit deployment to defend against Nigerian supply concentration risk. Anchor premium positioning through captive organic cultivation land banks in Mtwara and Lindi regions, shortening EU Organic Regulation conversion timelines for new entrants.
For New Entrants and Emerging Players: EU Organic Regulation fast-track certification services for Nigerian smallholders transitioning from conventional cultivation create immediate service-revenue traction. German health food retail shelf-space expansion offers the most penetrable geography, with direct-to-manufacturer sales bypassing Dutch trader markups as the optimal go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cooperatives with pre-certified audit documentation and multi-year offtake contracts with paleo-diet manufacturers. Acquisition targets should exhibit established smallholder network control and containerized processing infrastructure. Watch FDA gluten-free labeling enforcement intensity as the signal indicating pricing power inflection for dedicated cassava facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Smallholder Networks | Captive organic root supply secures EU Organic Regulation compliance and reduces input cost volatility. |
| Mobile Flash-Drying Unit Deployment | Containerized processing in rural Tanzania compresses post-harvest losses below sun-drying methods. |
| Blockchain Traceability Implementation | Real-time cyanogenic compound verification enables premium pricing tiers for paleo-diet brands. |
| Direct-to-Manufacturer Contracting | Bypassing Dutch trader intermediaries captures margin concentration in North American clean-label channels. |
| EU Organic Regulation Certification Services | Third-country equivalence documentation monetization creates recurring revenue from compliance support. |
Research Methodology
Desk research of customs trade records, EU Organic Regulation certification databases, and FDA gluten-free labeling guidance documents preceded structured interviews with Nigerian cooperative managers, Tanzanian mobile processing unit operators, German health food retail buyers, and North American clean-label brand formulation directors. Primary fieldwork with flash-drying equipment suppliers and EU-accredited audit bodies anchored bottom-up capacity estimates, while top-down triangulation against export volume data validated demand-side assumptions.
Variance decomposition across product type, distribution channel, and end-user segmentation dimensions shaped analytical framework construction throughout the forecast period. CAGRs emerged from installed capacity expansion trajectories in Nigerian and Tanzanian processing zones, cross-referenced with North American paleo-diet retail shelf-space growth and EU gluten-free bakery reformulation trends. Modeled inputs incorporated synthetic fertilizer price indices for organic transition cost modeling and container freight rate volatility on East African trade lanes.
Underlying assumptions cover sustained EU Organic Regulation third-country equivalence requirements, with deviation risk concentrated in FDA gluten-free labeling threshold adjustments and West African agricultural labor availability for mechanized harvesting. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Asia Pacific Animal Feed Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
US Greenhouse Horticulture Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
Italy Animal Protein Market
Agriculture and Agri Products
Organic Hemp Market
Agriculture and Agri Products
Brazil Compound Feed Market
Agriculture and Agri Products
Russia Compound Feed Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market
Agriculture and Agri Products
Asia Pacific Poultry Feed Market
Agriculture and Agri Products
Algae-Based Animal Feed Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
Japan Floriculture Market