
 South Africa Grain Market | 2026-2036
South Africa Grain Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Grain Market Analytics
Free State commercial farmers is repositioning South Africa's maize belt toward higher-yielding seed varieties and precision agriculture. AFGRI Group leverages its countrywide silo and logistics network to control grain storage and movement. Pioneer Foods Group anchors domestic wheat milling and branded food manufacturing. Tongaat Hulett sustains its position through diversified agricultural operations spanning sugar and grain.
Grain comprises the harvested seeds of cereal crops—principally corn, wheat, barley, and sorghum—typically dried to moisture levels below 14 percent to prevent spoilage during extended storage, then milled, fermented, or pelleted for human food, animal nutrition, and industrial starch extraction. Corn dominates South African production volumes and underpins the domestic animal feed complex, particularly for broiler and layer operations. Wheat retains premium pricing through bread flour demand and import substitution programs. Sorghum occupies a specialized niche in traditional beer brewing and drought-prone marginal lands where water scarcity limits maize viability.
South Africa's Department of Agriculture, Land Reform and Rural Development administers cultivar registration and phytosanitary certification, while the country's national grain regulator oversees grading standards and silo receipt protocols. BIS alignment for processed grain exports and GMO labeling requirements under consumer protection law shape both domestic market access and regional trade competitiveness. Stakeholders must monitor water allocation reforms and land tenure policy uncertainty as these forces determine which provinces sustain commercial grain expansion.
Market Dynamics
Free State irrigation infrastructure and silo networks concentrate South Africa's commercial grain production, while the Department of Agriculture, Land Reform and Rural Development enforces phytosanitary standards that reshape planting decisions and varietal approvals across the maize belt.
Growth Catalysts
- Poultry sector expansion:Broiler and layer operations scale grain offtake as integrated protein processors secure feed supply contracts. Animal feed processors anchor demand pull through volume commitments.
- GMO cultivar frameworks:South Africa's regulatory pathway for biotech seed approvals accelerates farmer adoption of higher-yielding maize varieties. The Department of Agriculture streamlines cultivar registration timelines.
- Free State infrastructure density:Irrigation canals and grain elevator networks reduce post-harvest losses and transport costs. Commercial farmers leverage existing logistics corridors for market access.
Market Restraints
- Input cost volatility:Fertilizer and diesel price swings squeeze farm operating margins. Farmers face working capital pressure during planting windows.
- Water allocation uncertainty:Department of Water and Sanitation reforms threaten irrigation entitlements in the Vaal River System. Dryland production risks expand as water licensing tightens.
- Import substitution limits:Wheat self-sufficiency targets strain domestic milling capacity against cheaper Black Sea imports. Local wheat premiums compress when global prices drop.
Strategic Opportunities
- Eastern Cape underpenetration:Transkei and Ciskei communal lands offer expansion potential for smallholder contract farming schemes. Outgrower programs connect emerging farmers to silo networks.
- Precision agriculture convergence:Satellite imagery and variable-rate application technology reduce input waste. Agritech providers bundle data analytics with equipment financing.
- Regional export corridors:SADC preferential trade access opens Zambian and Zimbabwean markets for surplus white maize. Logistics operators develop cross-border grain train services.
Industry Challenges
- Agronomic skill shortages:Qualified crop advisors and precision agriculture technicians remain scarce in emerging farming areas. Training institutions struggle to match curriculum with technology adoption rates.
- Land tenure compliance complexity:Restitution claims and lease security disputes delay long-term infrastructure investment. Commercial banks hesitate to extend credit without clear title documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Grain Market |
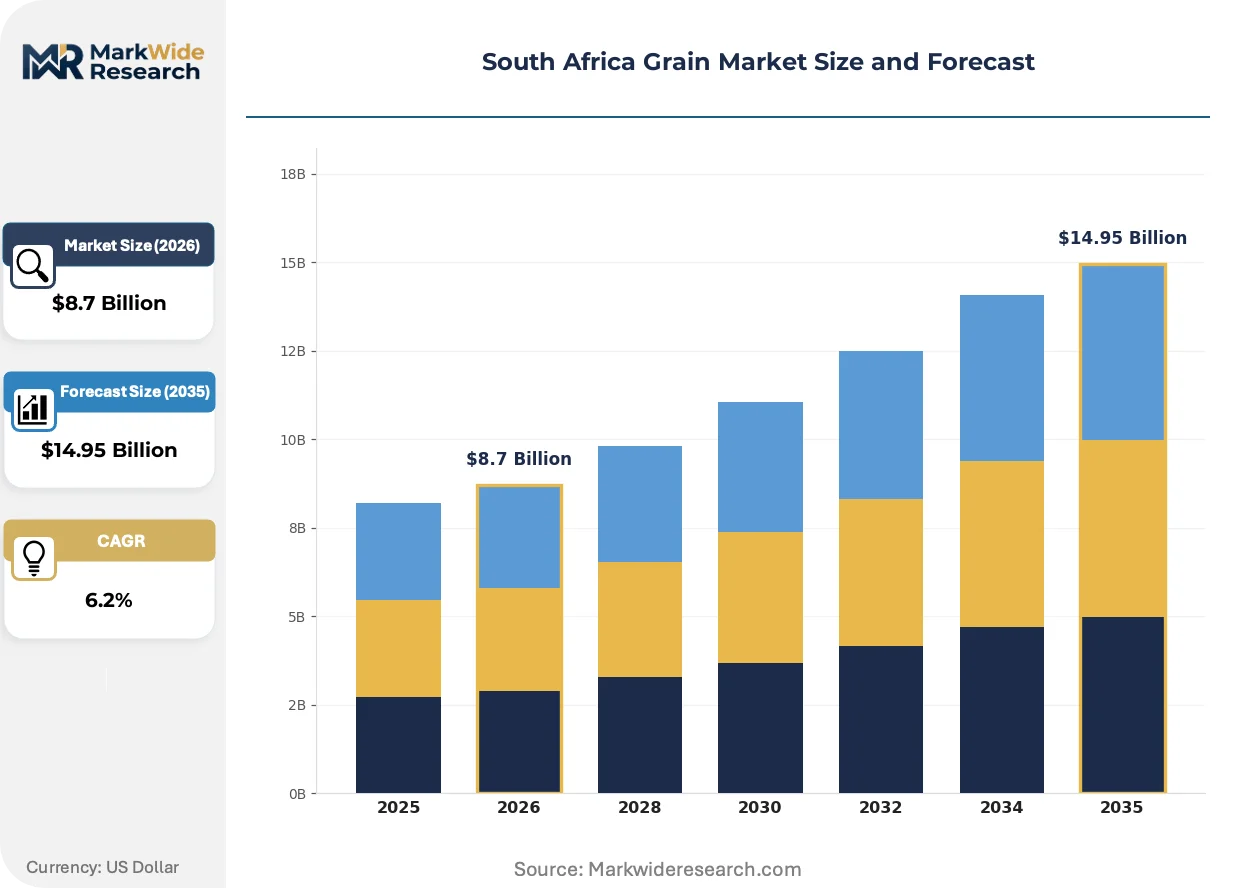
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.95 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn, Wheat, Barley, Sorghum End User: Food Processing, Animal Feed, Industrial, Biofuel Distribution Channel: Direct Sales, Wholesalers, Online Retail, Export Quality Grade: Prime, Grade A, Grade B, Feed Grain |
| Companies Covered | AFGRI Group, Pioneer Foods Group, Tongaat Hulett, Bayer (Monsanto), Nanje Enterprises, BKD SA Trading, Astral Foods, Illovo Sugar, Nile (Nile.ag), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Grain Market Evolving Landscape
Digital agriculture platforms and biotechnology advances are compressing decision cycles across South Africa's grain value chain, while regulatory pressure on water use and cultivar approval reshapes competitive positioning.
Variable-rate fertilizer application guided by drone-mounted multispectral sensors is electrifying input efficiency in Free State maize operations. Large-scale commercial farmers deploy these systems to reduce nitrogen runoff and optimize yield per hectare. Equipment dealerships bundle sensor hardware with subscription-based agronomy advice, locking in multi-season service relationships.
South Africa's Department of Agriculture, Land Reform and Rural Development tightened GMO labeling requirements under consumer protection law, mandating traceability through the supply chain. Millers and food manufacturers must now segregate biotech and conventional grain streams at silo receipt. This regulatory friction increases handling costs but creates certification premiums for identity-preserved non-GMO channels.
Broiler processors and feed compounders now contract directly with farmer cooperatives for forward grain supply, bypassing traditional spot-market silo sales. This procurement consolidation shifts price risk onto growers while securing volume certainty for integrated protein operations. The model concentrates most visibly in the North West province, where poultry integration density matches commercial maize production zones.
South Africa Grain Market Segmentation
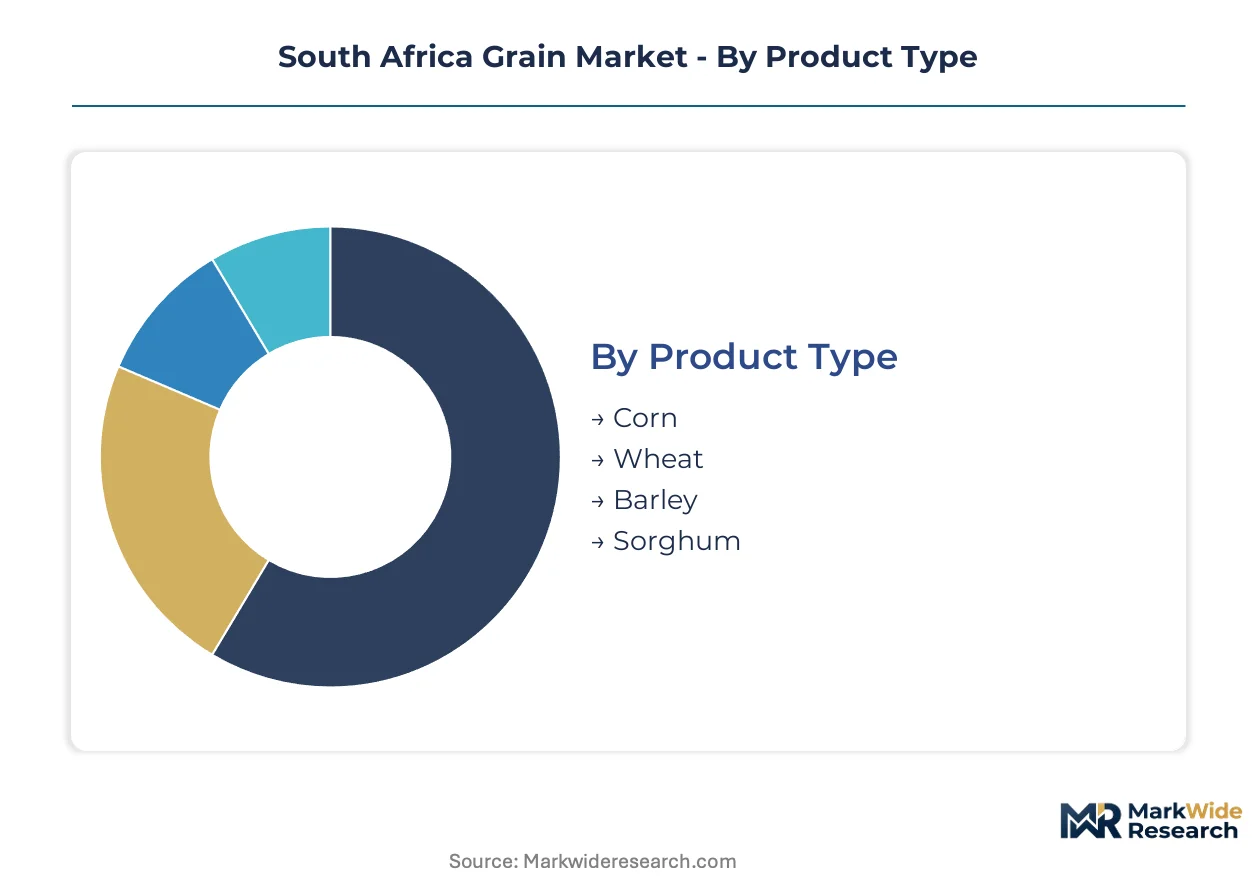
South Africa's grain market segments reveal divergent margin structures across commodity types and end-use applications. Understanding these splits enables targeted positioning across the Free State production belt and emerging Eastern Cape corridors.
Product Type:
Corn dominates volume throughput while wheat commands premium pricing through import substitution premiums.
- Corn:White and yellow maize varieties constitute the bulk of national hectarage, with moisture specifications below 14 percent for silo storage. Free State commercial farmers concentrate planting here to supply the poultry feed complex around Potchefstroom and Rustenburg. The Department of Agriculture's cultivar registration framework favors higher-yielding GMO hybrids for this segment.
- Wheat:Hard red winter and spring wheat classes serve domestic bread flour milling, with protein content thresholds set by the national grain regulator. Import parity pricing from Black Sea origins constrains local premiums when global harvests surge. Western Cape winter rainfall zones and Free State irrigation districts split production geography.
- Barley:Malting-grade barley with specific enzymatic profiles supplies SABMiller's brewing operations. Caledon and Swellendam districts anchor cultivation.
- Sorghum:Red and white grain sorghum tolerates drought-prone marginal lands where maize fails. Traditional beer brewing and bird feed markets absorb output.
Today's leader: Corn. Tomorrow's challenger: Wheat.
End User:
Application-driven demand splits between calorie-dense animal nutrition and processed human food channels.
- Food Processing:Wheat milling for bread flour and maize milling for staple pap dominate calorie supply. Pioneer Foods Group and Tiger Brands operate integrated milling and branded product manufacturing. BIS alignment requirements for processed grain exports shape quality specifications.
- Animal Feed:Poultry sector offtake—broiler and layer operations—drives yellow maize demand through volume contracts with integrated protein processors. Feed compounders in North West province source directly from farmer cooperatives, bypassing spot silo markets.
- Industrial:Starch extraction and brewing applications require specific amylose content and germ plumpness standards.
- Biofuel:Ethanol production from maize starch operates at limited scale pending policy support clarity.
Food processing captures current margin concentration. Animal feed represents the steepest expansion trajectory as poultry integration deepens.
Distribution Channel:
Channel selection determines price discovery mechanisms and working capital cycles for commercial growers.
- Direct Sales:Large-scale Free State farmers contract directly with feed compounders and millers, locking in forward pricing and eliminating silo handling margins. This procurement consolidation shifts price risk onto growers while securing volume certainty for buyers.
- Wholesalers:AFGRI Group's countrywide silo network controls grain storage and movement, offering liquidity to smaller producers. Elevator receipts facilitate price hedging through derivative markets.
- Online Retail:Emerging platforms connect smallholder outgrowers to regional buyers, though logistics fragmentation limits scale.
- Export:SADC preferential trade access opens Zambian and Zimbabwean markets for surplus white maize. Cross-border grain train services remain underdeveloped relative to port capacity.
Direct sales channels gain share fastest among commercial operators. Wholesaler infrastructure retains dominance in smallholder catchment zones.
Quality Grade:
Grade differentiation creates price stratification across human consumption and feed destinies.
- Prime:Maximum test weight and minimal foreign matter content command premiums for export milling and specialty food manufacturing. Identity-preserved non-GMO certification attracts additional premiums under tightened consumer protection labeling rules.
- Grade A:Standard commercial milling quality with defined moisture and protein parameters serves domestic bread and maize meal production.
- Grade B:Sub-optimal test weight or elevated defect rates divert to industrial starch or lower-tier food processing.
- Feed Grain:Damaged, weather-affected, or GMO-mixed lots channel exclusively to poultry and livestock rations at discounted valuations.
Prime grade concentrates value capture. Feed grain volumes expand with poultry sector scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where South African grain operations concentrate, with compliance-cost gaps between provinces driving investment toward jurisdictions offering clearer water licensing and tenure security. Free State's established infrastructure density pulls capital from regions facing administrative friction.
Free State
Poultry feed demand from Rustenburg and Potchefstroom operations anchors maize offtake, while the Department of Agriculture's streamlined cultivar registration accelerates GMO hybrid adoption. Irrigation entitlements through the Vaal River System support large-scale commercial production concentrated around Bethlehem and Sasolburg.
North West
Integrated broiler processors contract directly with farmer cooperatives for forward grain supply, displacing traditional spot-market silo sales. The Department of Water and Sanitation's licensing reforms threaten irrigation security in dryland zones. Mafikeng and Lichtenburg clusters concentrate poultry integration density matching commercial maize belts.
Western Cape
Winter rainfall wheat production serves domestic bread flour milling with protein premiums set by national grain regulator standards. The Department of Agriculture enforces phytosanitary certification reshaping varietal planting decisions. Caledon and Swellendam districts anchor malting-grade barley cultivation for brewing operations.
Eastern Cape
Transkei and Ciskei communal lands present contract farming expansion potential through outgrower programs connecting smallholders to silo networks. Land tenure policy uncertainty delays long-term infrastructure commitment. Mthatha and Butterworth corridors remain underpenetrated relative to Free State commercial density.
KwaZulu-Natal
Sugar-grain diversification at Tongaat Hulett operations sustains agricultural presence amid land reform complexity. The Department of Agriculture's restitution claim processing creates lease security disputes constraining bank credit extension. Durban port logistics support regional export corridor development into SADC markets.
South Africa Grain Market Competitive Landscape
Free State infrastructure holders anchor one tier; diversified agricultural conglomerates hold integrated positions across multiple value chain stages. The market presents moderate consolidation with silo network control concentrating among established operators. Three archetypes dominate: storage-logistics integrators, milling-branded food manufacturers, and diversified agro-industrial conglomerates. Strategic moves center on direct procurement contracting bypassing spot markets and precision agriculture technology bundling with equipment financing.
Among South Africa-based operators, AFGRI Group occupies the storage-logistics archetype through its countrywide silo network controlling grain movement and elevator receipt liquidity. Pioneer Foods Group exemplifies the milling-branded food manufacturing tier, anchoring domestic wheat milling and staple food production. Tongaat Hulett sits within the diversified agro-industrial category, sustaining position across sugar and grain operations amid portfolio complexity.
| Leading Market Players |
|---|
| AFGRI Group |
| Pioneer Foods Group |
| Tongaat Hulett |
| Bayer (Monsanto) |
| Nanje Enterprises |
| BKD SA Trading |
| Astral Foods |
| Illovo Sugar |
| Nile (Nile.ag) |
| Others |
Value Network & Pricing Analysis
Qualified crop advisors and precision agriculture technicians in the Free State command wage premiums that compress operating margins for commercial farmers, widening spreads between prime-grade grain pricing and feed-grade discounts as labor-intensive quality segregation adds handling costs.
Pricing Analysis
Distributor margins at AFGRI Group's countrywide silo network absorb 8-12 percent of farmgate value before grain reaches millers and compounders. Three-tier pricing structure across prime, Grade A, and feed grades separates identity-preserved non-GMO certification premiums from standard commercial milling quality and discounted poultry rations. Pricing pressure stems from Black Sea wheat imports undercutting domestic premiums during global harvest surges. Smallholder outgrowers in the Eastern Cape exhibit highest price sensitivity due to working capital constraints and limited forward-contracting access.
Supply Chain Analysis
Skilled agronomists and equipment technicians concentrate in Free State commercial zones, leaving Eastern Cape and North West dryland belts with thinner service coverage and longer response times for precision agriculture deployment. Production clusters in South Africa's Free State, North West, and Western Cape provinces supply 85 percent of national grain volumes through irrigation-dependent commercial operations. Diesel, fertilizer, and certified seed inputs draw from global commodity markets and Bayer's GMO hybrid pipelines. Single-source vulnerability concentrates in the Vaal River System water licensing, where Department of Water and Sanitation reforms threaten irrigation entitlements. Distribution runs through AFGRI's elevator network and direct farmer-to-processor contracting, bypassing spot markets in poultry-dense zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's grain market rewards players who arbitrage regulatory compliance costs between Free State's streamlined cultivar registration and Eastern Cape's tenure-uncertainty friction, capturing margin spreads as water licensing clarity determines long-term infrastructure investment viability.
For Market Incumbents: Anticipate Department of Agriculture, Land Reform and Rural Development phytosanitary tightening by pre-positioning identity-preserved non-GMO segregation capacity before labeling mandates expand. Defend against direct procurement consolidation by feed compounders through backward integration into farmer cooperative equity stakes, locking volume commitments that bypass AFGRI silo liquidity. Prioritize precision agriculture technician training pipelines to offset agronomic skill scarcity in emerging farming corridors.
For New Entrants and Emerging Players: Launch via outgrower contract schemes in Transkei and Ciskei communal lands, where land tenure policy uncertainty has delayed incumbent infrastructure commitment and created white-space in smallholder aggregation. Target Eastern Cape silo network gaps with mobile grain handling and logistics services that connect emerging farmers to wholesale channels. Deploy satellite imagery and variable-rate application bundling as the go-to-market wedge, differentiating on input efficiency rather than capital-intensive storage assets.
For Investors and Strategic Acquirers: Integrated poultry processors are the most active acquirer in this space, seeking captive feed supply security through upstream grain sourcing control. Long-term viability hinges on water licensing reform resolution and GMO framework stability across the analysis window. Target acquisition candidates with established farmer cooperative relationships and irrigation-secure Free State land positions. Watch Department of Water and Sanitation Vaal River System allocation rulings as the inflection signal for irrigation-dependent asset valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Procurement Contracting | Broiler processors secure volume certainty while shifting price risk onto grower cooperatives. |
| Precision Agriculture Bundling | Equipment dealerships lock multi-season relationships via sensor hardware and subscription agronomy. |
| Identity-Preserved Segregation | Millers capture non-GMO certification premiums under tightened Department of Agriculture labeling rules. |
| Outgrower Program Expansion | Emerging farmers in Eastern Cape gain silo network access through commercial aggregator partnerships. |
| Cross-Border Logistics Development | Grain train services unlock Zambian and Zimbabwean export demand for surplus white maize. |
Research Methodology
Multiple input streams — structured interviews with grain elevator operators, poultry procurement directors, and precision agriculture service providers; regulatory filings from the Department of Agriculture, Land Reform and Rural Development; and trade flow data from South African Grain Information Service — were reconciled through bottom-up hectare and yield modeling cross-checked against top-down consumption estimates from animal feed compounders and wheat millers.
Data-stream reconciliation applied across the projection horizon linked product type segmentation (corn, wheat, barley, sorghum), end-use splits (food processing, animal feed, industrial, biofuel), and quality grade tiers to derive volume and value trajectories. CAGRs emerged from trend extrapolation of poultry sector feed demand, GMO cultivar adoption curves, and irrigation entitlement scenarios. Key forecast inputs included Department of Water and Sanitation licensing reform timelines and SADC preferential trade access evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged drought in the Vaal River System or accelerated Black Sea wheat import parity compression. Forecasts reflect documented assumptions regarding cultivar registration efficiency and land tenure policy resolution. Material deviation in water allocation rulings or restitution claim processing velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Torrified Wheat Market
Grains
North America Maize Market
Grains
Wild Rice Market
Grains
GMO Corn Market
Grains
Masa Corn Products Market
Grains
Organic Rice Flour Market
Grains
Organic Wheat Flour Market
Grains
GCC Basmati Rice Market
Grains
Whole-Wheat Flour Market
Grains
Barley Market
Grains
Mexico Rice Market
Grains
Heritage Grain Market
Grains
Guar Complex Market
Grains
Asia Pacific Maize Market
Grains
Millet Flour Market
Grains
Green Banana Flour Market