
 Tunisia Grain Market | 2026-2036
Tunisia Grain Market Size, Share, and Industry Trends Forecast 2026-2036
Tunisia Grain Market Insights
Grain procurement advisory and storage logistics services are decoupling from traditional commodity trading, forcing handlers to sell risk management and quality certification separately from physical grain. Carthage Grains S.A. leverages its coastal silo network to control inbound flows from Black Sea origins. ROSE BLANCHE Group anchors domestic wheat milling through long-term offtake agreements with Tunisian bakeries. Soufflet competes on agronomic extension services tied to contract farming in the Mejerda Valley.
Grain comprises the harvested seed of cereal crops—principally wheat, barley, corn, and millet—distinguished by moisture content below 14.5 percent, test weight thresholds, and protein grades that determine milling yield and feed conversion ratios. Its primary commercial purpose spans human food processing, livestock nutrition, and industrial starch extraction. Wheat occupies the dominant value share as the staple input for Tunisian bread production, while barley margins concentrate in brewing and malt supply chains. Corn volumes in animal feed are expanding fastest as poultry integrators scale operations near Nabeul and Bizerte.
Tunisia's Ministry of Agriculture and the National Food Safety Authority enforce import licensing and phytosanitary border controls that determine which origins and quality grades enter commercial channels. The country's national standards body applies cereal grading protocols aligned with CODEX and ISO frameworks, conditioning price discovery at port terminals. Stakeholders must monitor whether Tunisia's grain self-sufficiency targets tighten import quotas or redirect public investment toward domestic seed breeding and irrigation expansion.
Market Dynamics
Phytosanitary import licensing from Tunisia's Ministry of Agriculture is fragmenting procurement channels, forcing millers to diversify origin countries and invest in separate quality certification infrastructure rather than relying on consolidated commodity traders.
Growth Catalysts
- Livestock modernization:Poultry integrators near Nabeul and Bizerte are expanding corn offtake volumes as automated feeding systems replace manual operations, creating sustained feed grain demand.
- CODEX-aligned grading protocols:Tunisia's national standards body adoption of international cereal classification frameworks is enabling price transparency at port terminals and attracting Black Sea suppliers.
- Sahel coastal corridor concentration:Port infrastructure clustering between Sousse and Sfax is reducing inland logistics costs for millers and accelerating inventory turnover cycles.
Market Restraints
- Import quota volatility:Tunisia's grain self-sufficiency targets generate unpredictable licensing volumes that complicate long-term procurement planning for handlers.
- Black Sea supply concentration:Reliance on Ukrainian and Russian wheat origins exposes millers to shipping route disruptions and currency fluctuation risks.
- Protein grade fragmentation:Variable wheat quality across import batches requires continuous blending adjustments that degrade milling yield consistency.
Strategic Opportunities
- Mejerda Valley contract farming:Irrigated acreage expansion in northern Tunisia offers handlers backward integration into domestic barley and wheat production.
- Quality certification unbundling:Separate phytosanitary testing and risk management services create standalone revenue streams independent of physical grain trading margins.
- Agronomic extension services:Technical advisory tied to input supply contracts builds farmer loyalty and secures origination pipelines in underdeveloped growing regions.
Industry Challenges
- Silo infrastructure modernization:Coastal storage facilities require significant capital deployment to meet temperature-controlled preservation standards for high-moisture corn imports.
- Phytosanitary compliance timelines:National Food Safety Authority border inspection protocols create port congestion and working capital compression for just-in-time millers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunisia Grain Market |
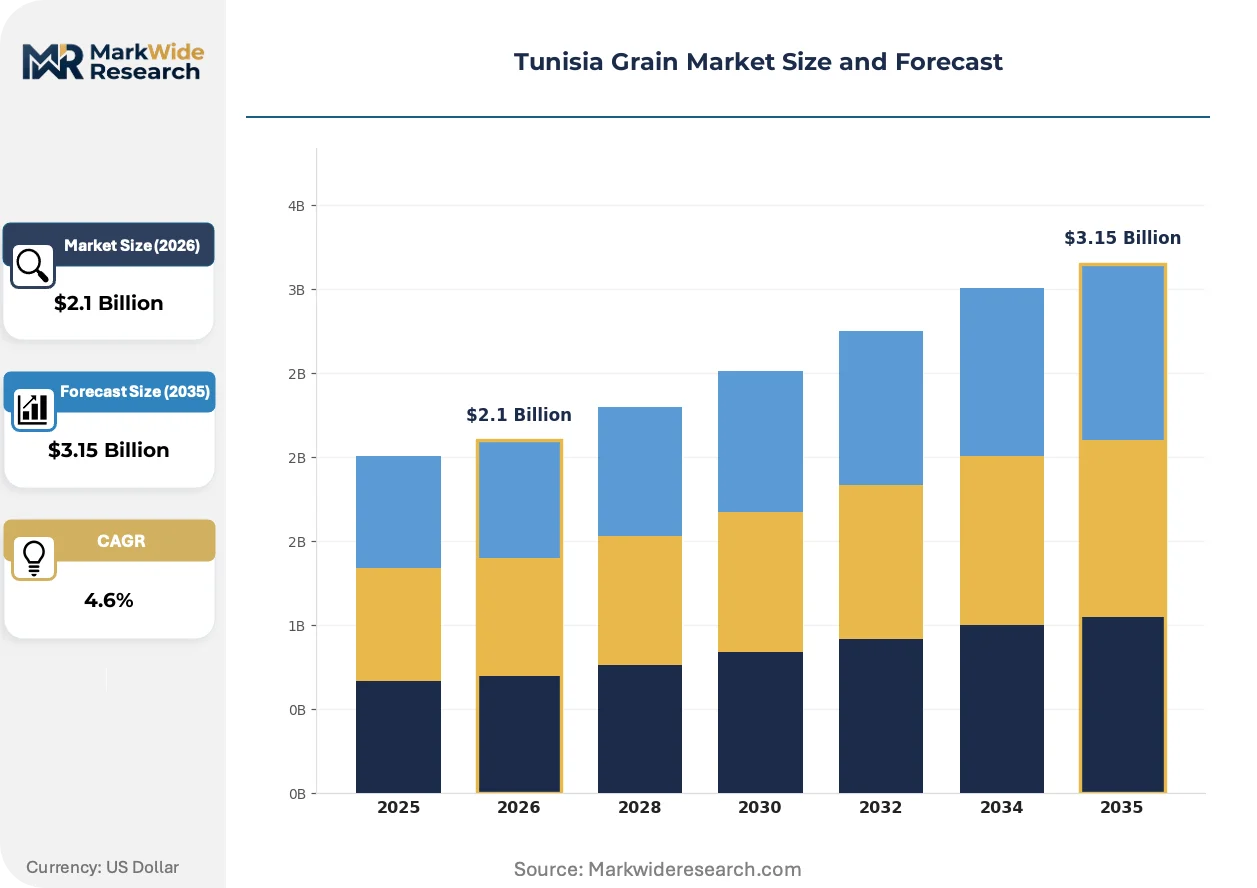
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat, Barley, Corn, Millet End Use Industry: Baking, Brewing, Animal Feed, Biofuel Distribution Channel: Wholesale, Retail, Direct, Exports Quality Grade: Premium, Standard, Commodity, Organic |
| Companies Covered | Carthage Grains S.A., ROSE BLANCHE Group, MRG International, Kilani Groupe, Louis Dreyfus, Soufflet, Casillo, Amber Grains, Finagrit, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunisia Grain Market Trends and Innovations
Digital traceability platforms and automated grain handling systems are compressing quality verification cycles and displacing manual sampling protocols across Tunisian port terminals and milling clusters.
Blockchain-based origin documentation is decentralizing supply chain verification by enabling millers to validate Black Sea wheat provenance without intermediary trader certification. Mid-sized bakeries in Sfax and Sousse are adopting these platforms fastest to satisfy National Food Safety Authority audit requirements. The technology is compressing documentation delays that previously extended customs clearance by multiple days.
Tunisia's Ministry of Agriculture enforcement of CODEX-aligned cereal grading protocols is standardizing quality arbitration procedures at port terminals. Millers now negotiate protein content and test weight specifications against transparent reference tables rather than bilateral trader agreements. This regulatory shift most affects durum wheat contracts, where handlers are restructuring procurement teams to include certified grain inspectors.
Feed compounders are consolidating grain purchasing through volume aggregation cooperatives rather than individual spot market transactions. Poultry integrators near Bizerte are forming collective buying groups to secure containerized corn shipments directly from Argentine origins, bypassing traditional importer intermediaries. This channel disintermediation concentrates most visibly in the animal feed segment, where price transparency pressures are eroding legacy trader margins.
Tunisia Grain Market Segmentation
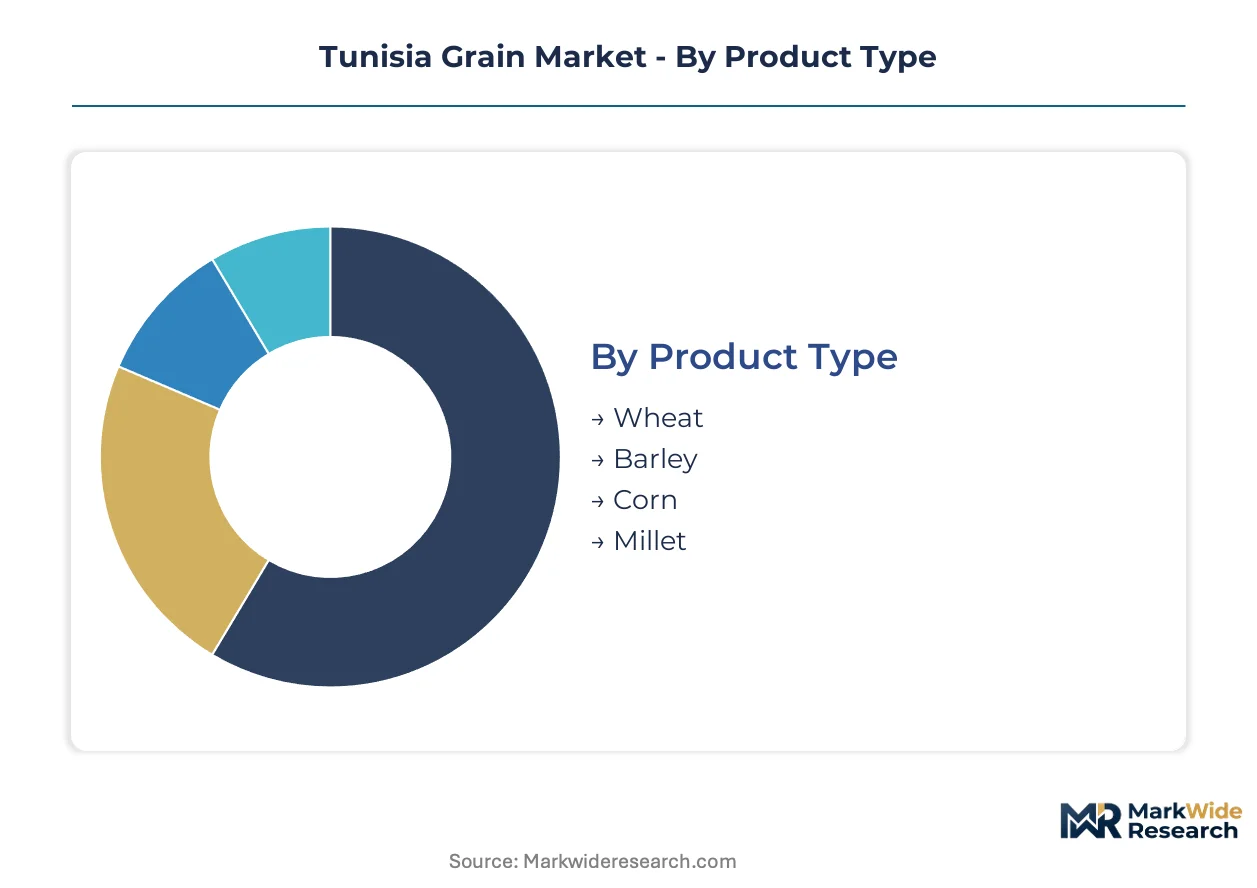
Grain handlers in Tunisia must navigate four distinct segmentation dimensions that reshape procurement strategies. Product type determines origin sourcing and phytosanitary compliance burdens. Quality grade tiers separate premium milling contracts from commodity feed volumes. Distribution channel choices reflect the decoupling of physical trading from risk management services.
Product Type:
Standardization dominates wheat and barley procurement through CODEX-aligned grading, while corn and millet retain greater specification variability across import origins.
- Wheat:Hard and soft varieties graded by protein content (11.5-14%) and test weight. Demand concentrates in Tunisian bakeries along the Sahel coastal corridor, where millers require consistent gluten strength for bread production. Tunisia's Ministry of Agriculture enforces import licensing that restricts origin countries and batch sizes.
- Barley:Two-row and six-row malting varieties with moisture thresholds below 14.5%. Brewing operations in Sfax and Sousse anchor procurement, though feed compounders increasingly substitute barley for corn when Black Sea shipping rates spike.
- Corn:Yellow dent varieties for animal feed with lower protein requirements than food-grade specifications. Poultry integrators near Nabeul and Bizerte are expanding automated feeding systems that demand uniform kernel size.
- Millet:Pearl and finger millet varieties serving niche human consumption and specialty feed markets. Traditional couscous producers in southern Tunisia maintain small-scale offtake through local collection networks.
Leading the category by volume: Wheat. Growing fastest: Corn.
End Use Industry:
Application-driven segmentation separates food-grade quality premiums from feed-grade commodity pricing, with biofuel representing an emergent demand channel.
- Baking:Durum and common wheat milled into semolina and flour for bread production. The National Food Safety Authority audits bakeries for mycotoxin compliance, forcing millers to maintain segregated storage for food-grade inventories.
- Brewing:Malting barley with specific enzyme activity and low protein content. Tunisia's brewing sector sources primarily from French and German origins to satisfy maltster specifications.
- Animal Feed:Corn, barley, and wheat byproducts formulated into poultry and ruminant rations. Feed compounders near Bizerte are consolidating purchasing through volume aggregation cooperatives.
- Biofuel:Low-grade cereals and starch-rich residues processed into ethanol. This segment remains underdeveloped due to Tunisia's grain self-sufficiency targets that prioritize food security over energy crops.
Baking commands the largest volume share. Animal feed is climbing the fastest as livestock operations modernize.
Distribution Channel:
Channel structure reflects the unbundling of physical grain handling from ancillary services across Tunisia's procurement landscape.
- Wholesale:Bulk shipments through port terminals at Sousse and Sfax, handled by licensed importers with silo infrastructure. Carthage Grains S.A. controls significant coastal storage capacity that shapes terminal pricing.
- Retail:Bagged grain sales to small-scale bakeries and livestock producers through regional distributors. This channel faces margin compression from direct sourcing trends among larger end-users.
- Direct:Containerized shipments from Argentine and Black Sea origins contracted by poultry integrators and large millers. Collective buying groups near Bizerte are bypassing traditional importer intermediaries.
- Exports:Limited re-export activity due to Tunisia's net importer status and domestic self-sufficiency policies. Occasional barley shipments transit to neighboring North African markets during surplus harvests.
Wholesale dominates throughput. Direct channels are gaining share fastest as buyers seek origin transparency.
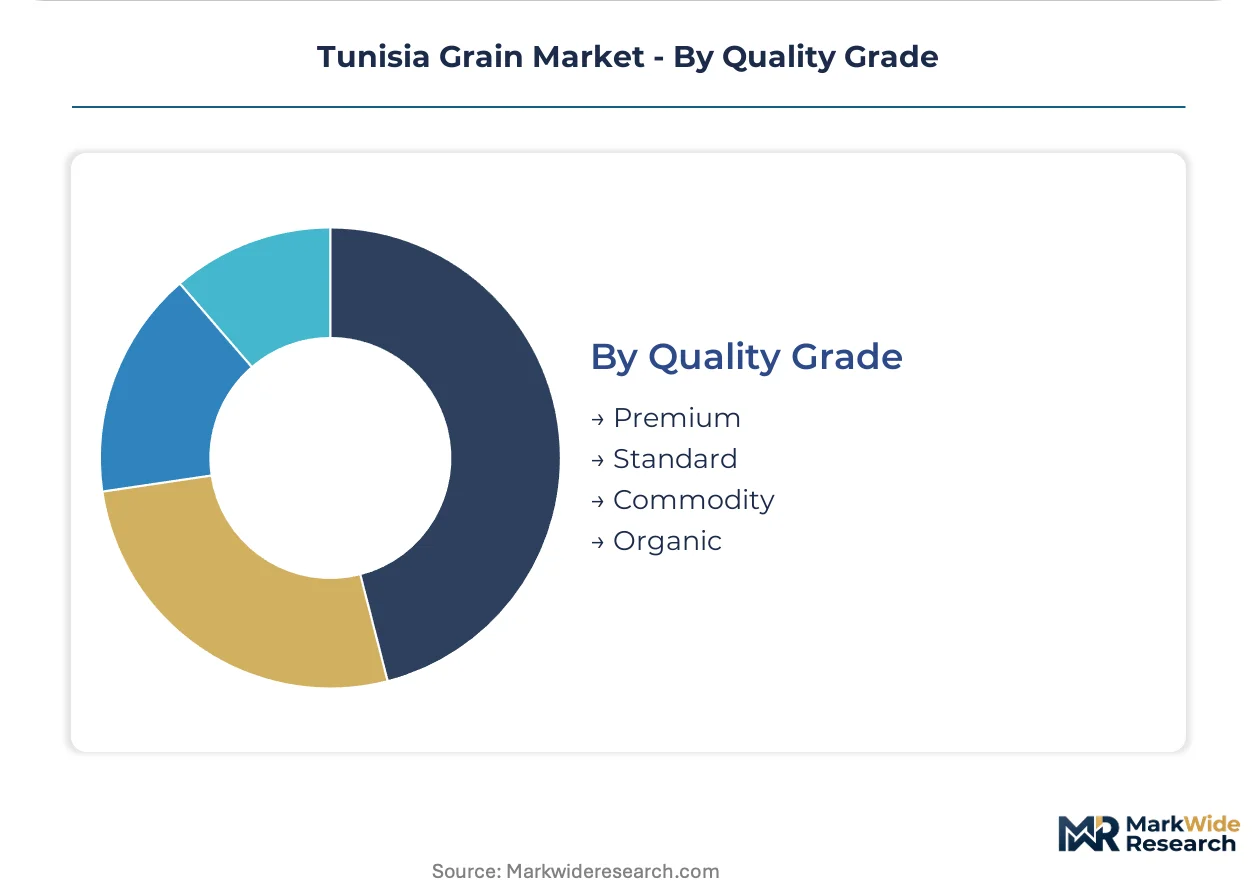
Quality Grade:
Price stratification across quality tiers enables handlers to match cereal specifications to end-use requirements while managing phytosanitary compliance costs.
- Premium:High-protein wheat (13.5%+) and low-moisture malting barley with full traceability documentation. Premium grades attract the strictest National Food Safety Authority inspection protocols at port entry.
- Standard:Mid-range protein wheat and feed barley meeting CODEX baseline specifications. This tier represents the volume anchor for Tunisia's milling and feed industries.
- Commodity:Lower-protein cereals suitable for industrial starch extraction and basic animal nutrition. Commodity grades face the most volatile import quota allocations from the Ministry of Agriculture.
- Organic:Certified chemical-free production with documented input restrictions. Organic volumes remain marginal due to limited domestic acreage and high certification costs for imported origins.
Standard grades lead by volume. Premium segments are expanding most quickly as bakery chains consolidate and upgrade specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tunisia consumes substantially more grain than it produces, creating structural import dependence concentrated in coastal port zones. Domestic harvests satisfy roughly one-third of cereal demand, forcing millers and feed compounders to source Black Sea and Argentine origins through Sousse and Sfax terminals.
Sahel Coastal Corridor
Poultry integrators near Nabeul and Bizerte are expanding automated feeding systems that demand uniform corn specifications. Tunisia's Ministry of Agriculture enforces phytosanitary import licensing that restricts batch origins and sizes. Milling clusters between Sousse and Sfax leverage port infrastructure to reduce inland logistics costs and accelerate inventory turnover.
Mejerda Valley
Irrigated barley and wheat production is expanding as handlers pursue backward integration into domestic origination. The national standards body applies CODEX-aligned grading protocols that condition price discovery for locally grown cereals. Contract farming operations in northern Tunisia are building farmer loyalty through agronomic extension services tied to input supply.
Cap Bon Peninsula
Specialty millet collection networks serve traditional couscous producers maintaining small-scale offtake relationships. The National Food Safety Authority audits food-grade inventories for mycotoxin compliance, forcing segregated storage investments. Artisanal processors in this southern region preserve heritage grain varieties through localized procurement channels.
Gulf of Gabès
Fishing and phosphates dominate economic activity, leaving grain demand fragmented among small-scale livestock producers. Import quota volatility from self-sufficiency targets generates unpredictable licensing volumes that complicate procurement planning. Regional distributors face margin compression as larger end-users shift toward direct containerized sourcing.
Tunisia Grain Market Competitive Landscape
Capital-heavy silo operators compete with asset-light trading houses across Tunisia's grain procurement landscape. Coastal storage infrastructure concentrates among handlers controlling terminal access, while smaller merchants survive on phytosanitary certification and risk management services unbundled from physical grain. Three archetypes dominate: integrated port operators with captive silo networks, agronomic service providers tied to contract farming, and origin-focused traders specializing in Black Sea or Argentine corridors. Competitive moves center on backward integration into domestic production and technology licensing for automated handling systems.
Within the integrated infrastructure tier, Carthage Grains S.A. and ROSE BLANCHE Group exemplify contrasting strategic positions. Carthage Grains S.A. anchors coastal terminal operations through silo network control that shapes inbound flow pricing from Black Sea origins. ROSE BLANCHE Group occupies a position emphasizing domestic milling integration through long-term bakery offtake agreements. Soufflet represents the agronomic extension archetype, sitting within the contract farming specialization vector in northern growing regions.
| Leading Market Players |
|---|
| Carthage Grains S.A. |
| ROSE BLANCHE Group |
| MRG International |
| Kilani Groupe |
| Louis Dreyfus |
| Soufflet |
| Casillo |
| Amber Grains |
| Finagrit |
| Others |
Pricing and Supply Chain Analysis
Tunisia's CODEX-aligned cereal grading protocols from the national standards body gate qualified supply access and premium-tier pricing for millers meeting protein content and test weight thresholds. Handlers lacking certified grain inspectors face exclusion from durum wheat contracts as the Ministry of Agriculture tightens phytosanitary border controls.
Pricing Analysis
Cost-down pressure on standard-grade wheat accelerates because Black Sea shipping disruptions force millers to absorb freight volatility rather than pass through to bakery customers. Three-tier pricing structure across premium, standard, and economy levels separates high-protein milling varieties from feed-grade barley and industrial starch cereals. Price differentiation hinges on CODEX certification tier and volume scale commitments in long-term offtake agreements. Small-scale livestock producers in the Gulf of Gabès exhibit highest price sensitivity, while consolidated poultry integrators near Bizerte prioritize specification consistency over per-ton savings.
Supply Chain Analysis
Freight cost volatility from Ukrainian and Russian wheat origins compresses handler margins at Sousse and Sfax port terminals. Supply concentrates in Black Sea corridors and Argentine corn export zones, with raw material dependencies on Ukrainian hard wheat, Russian soft wheat, and Argentine yellow dent corn. Single-source vulnerability from Black Sea route disruptions exposes millers to unpredictable inventory costs. Distribution runs through coastal silo networks controlled by licensed importers, with direct containerized channels gaining share as poultry integrators form collective buying groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tunisia's grain market represents a consolidation play as phytosanitary compliance timelines from the National Food Safety Authority force capital-light traders to exit or merge with silo-equipped handlers.
For Market Incumbents: Hedge against Black Sea supply disruption by securing alternative origin contracts with Argentine and French suppliers before import quota windows close. Expand temperature-controlled coastal storage capacity to capture high-moisture corn volumes from poultry integrators upgrading automated feeding systems near Nabeul. Defensive consolidation through acquisition of regional distributors in the Gulf of Gabès prevents margin erosion from direct sourcing trends.
For New Entrants and Emerging Players: Blockchain-based origin documentation platforms offer a technology-first wedge into the Sfax and Sousse bakery segments facing National Food Safety Authority audit pressure. Target underdeveloped contract farming networks in the Mejerda Valley where Soufflet's agronomic extension model has not yet saturated farmer relationships. Go-to-market through quality certification unbundling—selling phytosanitary testing and risk management separately from physical grain trading—sidesteps capital requirements for silo infrastructure.
For Investors and Strategic Acquirers: Ministry of Agriculture announcements tightening grain self-sufficiency targets is the leading indicator that import quota volatility will accelerate handler bankruptcies and create distressed acquisition opportunities. Long-term viability favors vertically integrated operators controlling both coastal terminal access and domestic origination pipelines. Watch for collective buying group formation among poultry integrators as the signal that direct channel disintermediation has reached critical mass and legacy trader margins have compressed beyond recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mejerda Valley Contract Farming | Secures domestic barley and wheat origination pipelines outside volatile import quotas. |
| Coastal Silo Infrastructure Modernization | Enables temperature-controlled preservation for high-moisture corn imports from poultry integrators. |
| Quality Certification Unbundling | Creates standalone revenue streams from phytosanitary testing independent of physical grain margins. |
| Blockchain-Based Origin Documentation Platform | Compresses customs clearance delays for Black Sea wheat at National Food Safety Authority audits. |
| Long-Term Offtake Agreement with Bakery Chains | Locks in premium-grade durum wheat demand along the Sahel coastal corridor. |
Research Methodology
Multi-period observation of import licensing volumes, port terminal throughput, and CODEX grading protocol adoption anchored the trend analysis, supplemented by interviews with grain procurement directors at milling clusters, phytosanitary compliance officers from the Ministry of Agriculture, coastal silo operators, poultry integrator supply chain managers, and bakery chain purchasing heads. Secondary validation drew from customs and trade data, national food safety authority bulletins, port authority throughput statistics, and agricultural ministry policy circulars. Bottom-up volume estimates from end-use consumption patterns triangulated against top-down import and production aggregates.
Segment-weighting across product type, quality grade tier, end-use industry, and distribution channel dimensions shaped the analytical framework throughout the forecast period. CAGRs derived from historical trajectory analysis adjusted for policy intervention timing and infrastructure investment cycles. Industry-specific forecast inputs included Ministry of Agriculture self-sufficiency target announcements and poultry integrator automation capex disclosures.
Several conditions sit outside the modeled scope, including extreme Black Sea shipping route closures exceeding historical disruption patterns and radical shifts in Tunisia's grain self-sufficiency policy stance. Forecast outputs reflect documented assumptions about phytosanitary compliance timeline stability and import quota allocation continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Europe Wheat Protein Market
Grains
North America Wheat Market
Grains
Grain Augers Market
Grains
Quinoa Flour Market
Grains
Spelt Wheat Market
Grains
Heritage Grain Market
Grains
Chickpeas Market
Grains
Paraguay Grains Market
Grains
Basmati Rice Market
Grains
Global Grain Analysis Market
Grains
Millet Flour Market
Grains
Fortified Rice Market
Grains
Wheat Protein Market
Grains
China Wheat Protein Market
Grains
Sorghum Market
Grains
Oat Flour Market