
 Grain Silos Market | 2026-2036
Grain Silos Market Size, Share, and Industry Trends Forecast 2026-2036
Grain Silos Market Analysis
Aftermarket service revenue is fragmenting across the grain silos value chain as original equipment manufacturers compete with independent maintenance networks for recurring income pools. Sukup Manufacturing Co. anchors its position through captive distribution across the US Midwest, while Symaga S.A.U. leverages its Spanish manufacturing base to serve North African and Middle Eastern export markets. Ag Growth International Inc. extends its reach through backward integration into handling equipment that feeds silo installation demand.
A grain silo is a cylindrical storage structure engineered from corrugated galvanized steel, reinforced concrete, or woven fabric, designed to maintain grain moisture below 14% through aeration systems and temperature monitoring to prevent spoilage and pest infestation. Steel silos dominate commercial installations due to faster erection timelines and lower foundation costs, while concrete silos sustain share in large-scale permanent facilities where structural longevity exceeds fifty years. Modular and pre-engineered installation types are capturing expanded demand from grain traders requiring rapid capacity deployment during harvest peaks.
EPA air quality standards and OSHA confined-space entry regulations shape US silo design requirements, while EU Green Deal carbon accounting and REACH chemical compliance drive coating and sealant specifications in European markets. The USDA's grain grading and storage incentive programs influence cooperative purchasing patterns across American farming regions. Stakeholders must monitor evolving mycotoxin storage protocols and carbon border adjustment mechanisms as these frameworks increasingly determine market access and equipment specification standards.
Market Dynamics
Post-harvest infrastructure investment is accelerating as export-oriented farming operations prioritize rapid capacity deployment during compressed harvest windows, while regulatory pressure from emissions standards and sustainability frameworks reshapes equipment specifications across major grain corridors.
Growth Catalysts
- EPA Emissions Standards:US air quality mandates are accelerating aeration system upgrades and corrosion-resistant coating adoption in commercial installations across the corn belt.
- Black Sea Export Corridors:Agricultural cooperatives in Ukraine and neighboring territories are expanding steel silo capacity to handle rising wheat and corn export volumes.
- Modular Pre-Engineered Systems:Grain traders are deploying rapid-erection silo configurations to capture harvest peak pricing advantages without permanent foundation commitments.
Market Restraints
- Galvanized Steel Price Volatility:Corrugated steel input costs fluctuate with scrap metal and zinc pricing, squeezing margins for fabrication-dependent suppliers.
- Foundation Engineering Concentration:Specialized geotechnical contractors for large-scale concrete silo projects cluster in Germany and the US Midwest, creating bottleneck risks.
- REACH Chemical Compliance:EU coating and sealant specifications add formulation complexity and extend product qualification timelines for European market entry.
Strategic Opportunities
- Brazil Cerrado Expansion:Soybean and corn farming frontiers in Mato Grosso and Goiás present underpenetrated demand for commercial-scale steel storage infrastructure.
- Carbon Border Adjustment Mechanisms:EU import tariffs based on embedded emissions are creating first-mover advantage for silo manufacturers with verified low-carbon supply chains.
- IoT-Aeration Convergence:Wireless moisture sensors combined with automated ventilation controls are opening premium pricing tiers for precision grain management.
Industry Challenges
- Confined-Space Safety Certification:OSHA entry protocols and EU machinery directives require specialized technician training that outpaces workforce pipeline development.
- Legacy Concrete Silo Integration:Retrofitting fifty-year-old structures with modern monitoring systems demands custom engineering that fragments project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain Silos Market |
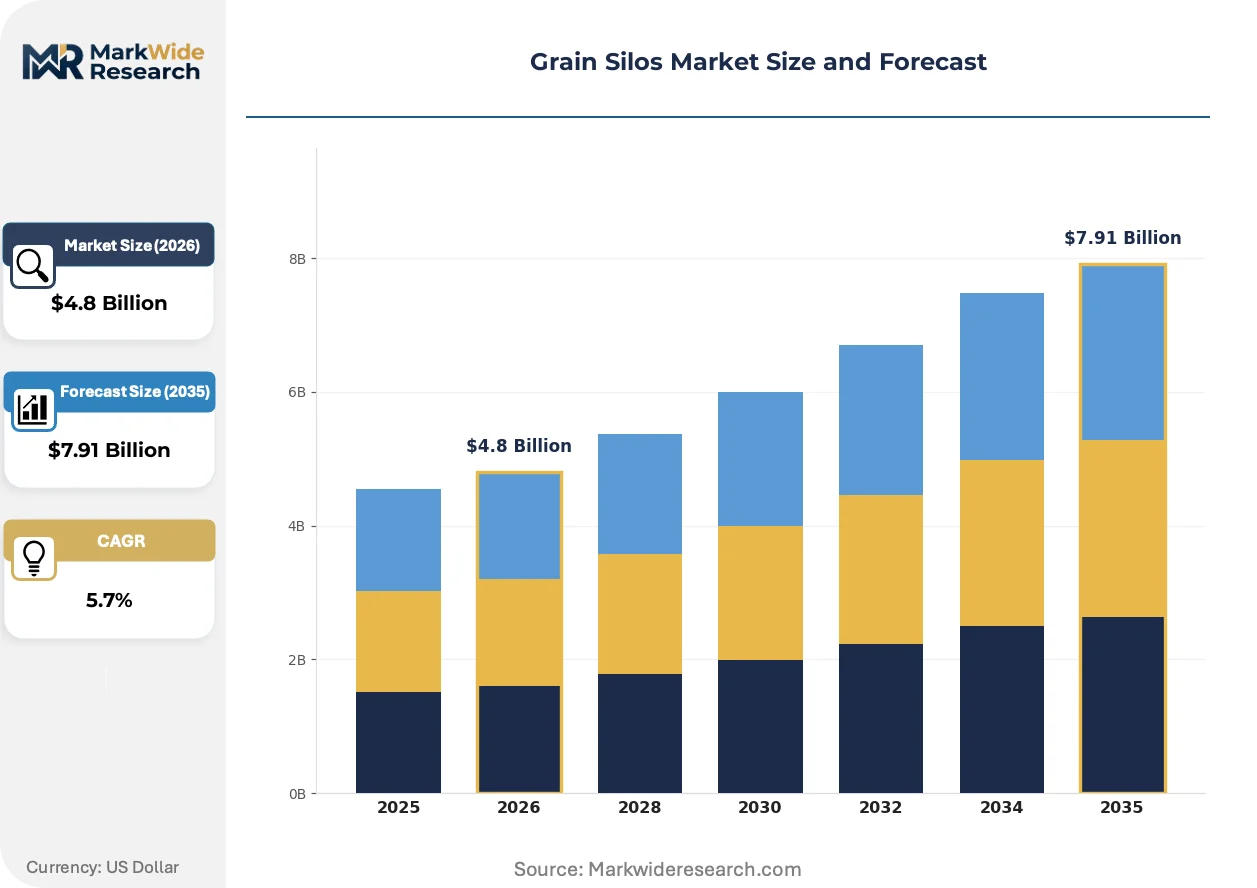
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Silos, Concrete Silos, Fabric Silos, Bins Capacity: Small Scale, Medium Scale, Large Scale, Customized End User: Agricultural Cooperatives, Commercial Farmers, Grain Traders, Food Processors Installation Type: On-Site, Modular, Pre-Engineered, Relocatable |
| Companies Covered | Symaga S.A.U., Grain Systems Inc., Sukup Manufacturing Co., SCAFCO Grain Systems Co., Prado Silos, Ag Growth International Inc., Brock Grain Systems, CTB Inc., Sioux Steel Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain Silos Market Emerging Trajectories
Digital infrastructure is penetrating grain storage operations through sensor networks and predictive analytics, while material science advances and procurement model evolution reshape how buyers evaluate total cost of ownership across facility lifecycles.
Wireless grain monitoring systems are virtualizing traditional manual temperature and moisture inspection protocols. Large cooperative buyers in Iowa and Illinois are deploying cellular-connected sensor arrays across multi-site portfolios. This technology is virtualizing the role of on-site grain managers and compressing response times to spoilage events from days to hours.
EU Green Deal carbon accounting rules are mandating lifecycle emissions disclosure for agricultural infrastructure procurement. Equipment suppliers must now document embodied carbon in steel production and transportation. European grain traders are prioritizing certified low-carbon silo configurations in tender evaluations, shifting competitive advantage toward manufacturers with integrated smelter partnerships or renewable energy-powered fabrication.
Service unbundling is separating equipment supply from installation and aftermarket maintenance. Independent maintenance networks are capturing recurring revenue pools that original equipment manufacturers previously controlled through captive service contracts. This fragmentation is most visible in the US Midwest, where regional repair cooperatives are undercutting factory-authorized technicians on aeration system overhaul pricing.
Grain Silos Market Segmentation
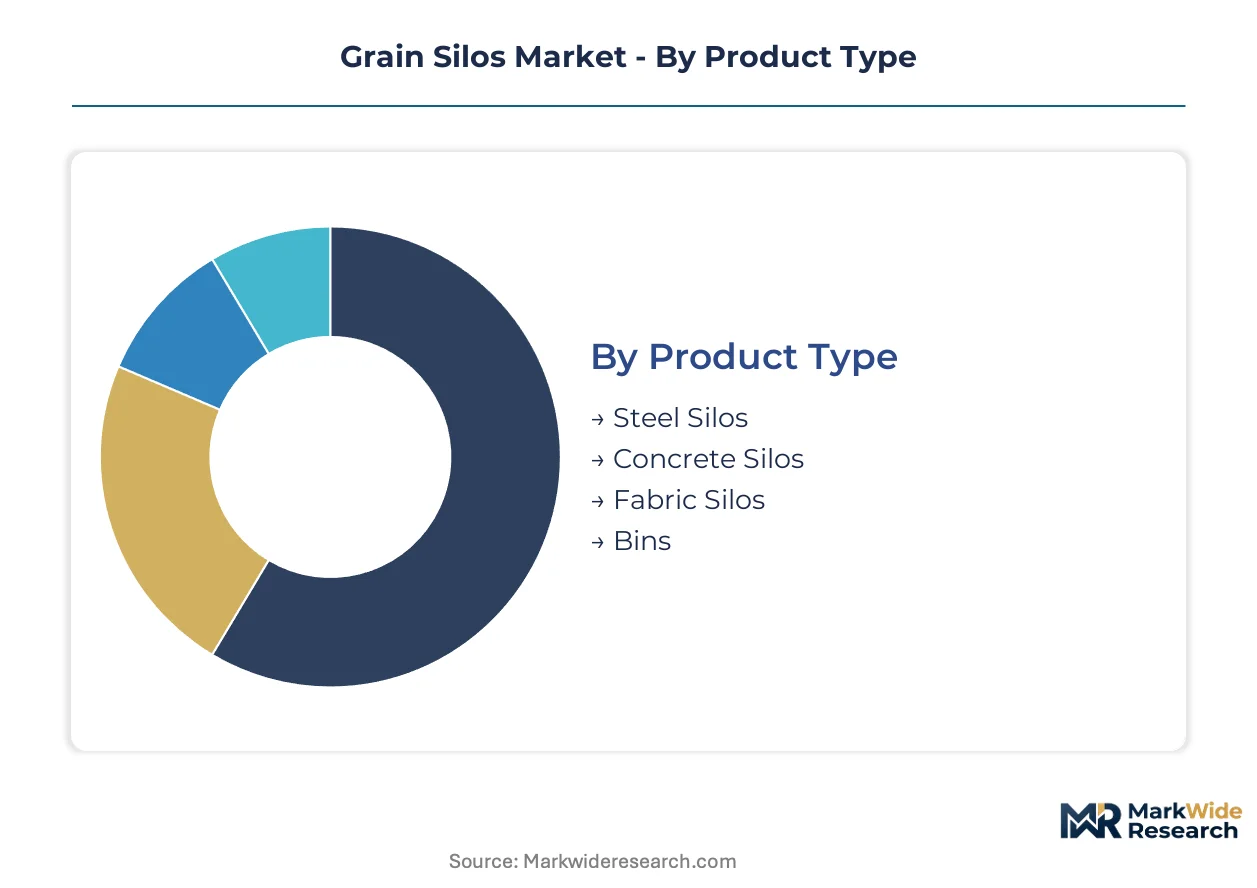
Grain silo procurement decisions cluster around structural material durability, throughput scale, and deployment speed requirements. Buyers evaluate total cost of ownership across fabrication, foundation, and operational maintenance lifecycles.
Product Type:
Material selection tracks directly against permanence requirements and capital recovery timelines.
- Steel Silos:Corrugated galvanized steel construction enables rapid field erection without extensive curing periods. Commercial grain traders in Brazil and Argentina specify steel configurations for export corridor capacity expansion where harvest-to-shipment windows compress decision cycles.
- Concrete Silos:Reinforced concrete delivers structural integrity exceeding fifty years with minimal degradation. Large cooperative facilities across the US Midwest and Black Sea corridor favor concrete for permanent infrastructure where depreciation schedules span multiple decades.
- Fabric Silos:Woven polyethylene or PVC membrane structures mounted on steel frames serve temporary overflow storage during peak harvest periods.
- Bins:Smaller-diameter flat-bottom or hopper-bottom units handle on-farm buffer storage before transfer to commercial elevators.
The dominant share belongs to steel silos, while concrete silos retain structural permanence advantages in long-tenure installations.
Capacity:
Scale thresholds align with ownership structure and grain throughput velocity.
- Small Scale:Sub-1,000 tonne units serve individual commercial farmers with localized storage before cooperative delivery.
- Medium Scale:1,000-10,000 tonne configurations balance capital efficiency against harvest aggregation requirements.
- Large Scale:Exceeding 10,000 tonnes, these installations anchor regional elevator networks and export terminal infrastructure.
- Customized:Project-specific engineering addresses constrained site footprints or specialized aeration requirements.
Large scale installations command the installed base, though medium scale configurations are expanding most quickly among emerging cooperative formations.
End User:
Buyer sophistication varies across ownership models and grain handling sophistication.
- Agricultural Cooperatives:Member-owned purchasing consortia dominate North American corn belt procurement, leveraging collective bargaining for multi-site installations.
- Commercial Farmers:Individual operators prioritize on-farm buffer capacity to capture basis improvement opportunities between harvest and sale.
- Grain Traders:Merchandising firms require rapid deployment capabilities to arbitrage spatial and temporal price spreads across harvest windows.
- Food Processors:Milling and ingredient manufacturers specify silo configurations integrated with inbound logistics and quality control protocols.
Agricultural cooperatives hold the dominant procurement volume, while grain traders are gaining share fastest through speculative capacity deployment.
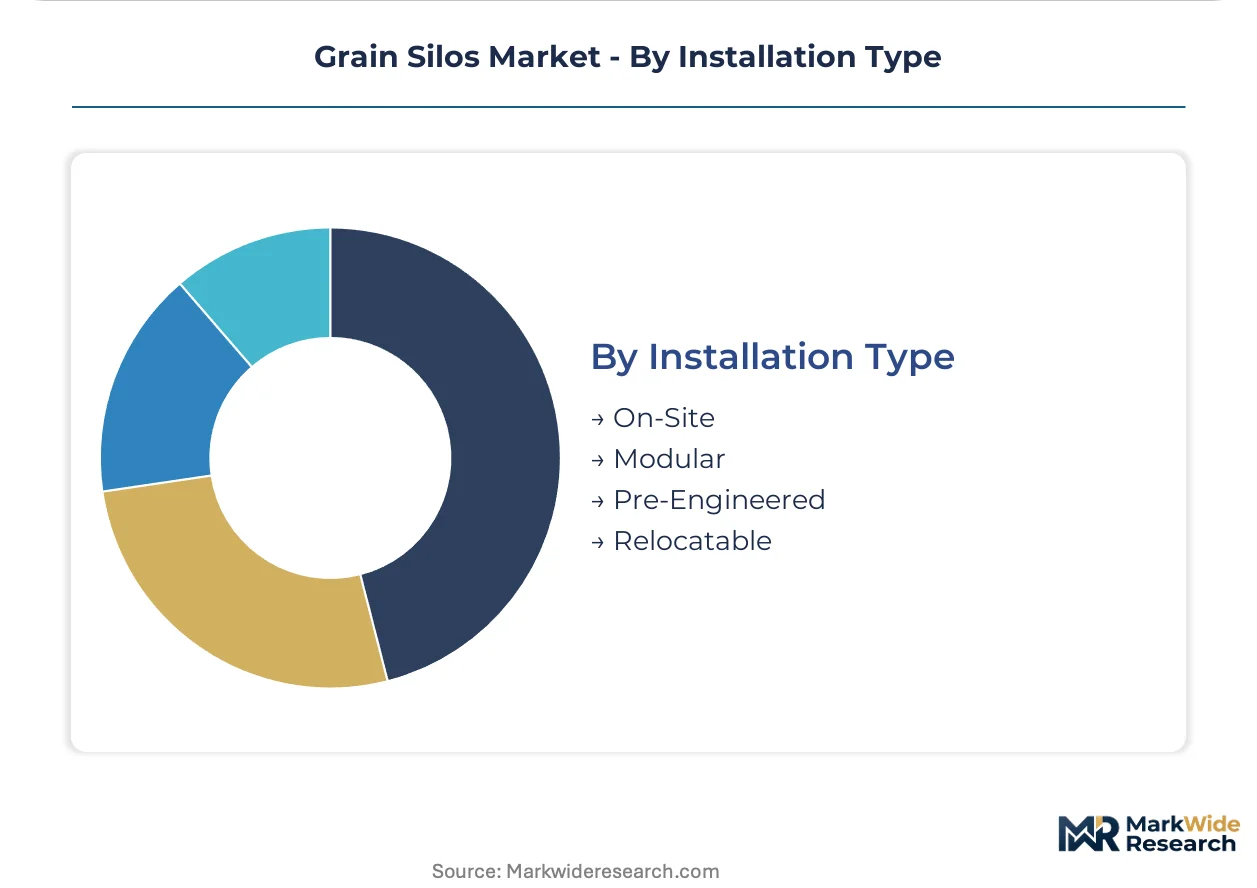
Installation Type:
Construction methodology determines speed-to-operation and capital commitment flexibility.
- On-Site:Traditional stick-built or slip-formed construction delivers maximum customization for permanent facilities.
- Modular:Factory-fabricated panel systems reduce field labor requirements and compress project schedules.
- Pre-Engineered:Standardized designs with pre-approved engineering documentation accelerate permitting and foundation preparation.
- Relocatable:Skid-mounted or bolted assemblies enable asset redeployment across harvest regions or lease termination recovery.
Pre-engineered systems capture the dominant specification share, while relocatable configurations are climbing the fastest among trading firms managing portfolio flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grain silo procurement patterns diverge sharply across geographies: export corridors favor rapid-deployment steel configurations, while mature farming regions prioritize permanent concrete infrastructure with multi-decade depreciation schedules.
United States
Agricultural cooperatives across Iowa and Illinois drive steel silo demand for corn and soybean storage. EPA emissions standards and OSHA confined-space regulations mandate aeration system upgrades and specialized technician certification. The US Midwest corn belt anchors commercial elevator networks with multi-site sensor deployment for remote grain monitoring.
Brazil
Soybean and corn farming expansion in Mato Grosso and Goiás fuels commercial-scale steel storage infrastructure. ANVISA oversees agricultural equipment safety compliance alongside environmental licensing requirements. The Cerrado frontier presents underpenetrated demand as export-oriented operators seek rapid capacity deployment during compressed harvest windows.
Ukraine
Black Sea wheat and corn export volumes drive steel silo capacity expansion among agricultural cooperatives. National regulators align infrastructure standards with EU accession requirements for grain quality and storage protocols. Odesa and Mykolaiv port corridors concentrate new installation activity for transshipment efficiency.
Germany
Large-scale concrete silo projects serve permanent cooperative facilities with structural longevity exceeding fifty years. EU Green Deal carbon accounting and REACH chemical compliance dictate coating and sealant specifications. Specialized geotechnical contractors cluster in Bavaria and North Rhine-Westphalia for foundation engineering concentration.
Argentina
Export-oriented farming in Buenos Aires and Córdoba provinces specifies steel configurations for harvest-to-shipment compression. The national agricultural technology regulator enforces grain quality standards for international market access. Rosario and Bahía Blanca port zones anchor regional elevator network expansion.
Grain Silos Market Vendor Landscape
Capability concentration sits with specialized coating and aeration system suppliers; scale advantage sits with integrated fabricators controlling captive distribution networks. The vendor base organizes around three strategic archetypes: Midwest-anchored cooperatives with multi-site service contracts, European specialists leveraging EU regulatory compliance as competitive moat, and South American fabricators capturing Cerrado expansion demand. Dominant competitive moves include backward integration into handling equipment and geographic expansion through modular pre-engineered system licensing.
Within the integrated-fabricator tier, Sukup Manufacturing Co. and Symaga S.A.U. exemplify divergent geographic anchoring strategies, while Ag Growth International Inc. occupies a position spanning equipment supply and installation services. Among North American specialists, Grain Systems Inc. and SCAFCO Grain Systems Co. represent the rapid-deployment configuration segment. Brock Grain Systems and CTB Inc. sit within the permanent infrastructure tier serving multi-decade facility planning. The competitive dynamic hinges on recurring revenue capture—original equipment manufacturers defend captive service contracts against independent maintenance networks fragmenting aftermarket income pools.
| Leading Market Players |
|---|
| Symaga S.A.U. |
| Grain Systems Inc. |
| Sukup Manufacturing Co. |
| SCAFCO Grain Systems Co. |
| Prado Silos |
| Ag Growth International Inc. |
| Brock Grain Systems |
| CTB Inc. |
| Sioux Steel Company |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese galvanized steel production is compressing input costs for corrugated silo fabricators while simultaneously eroding pricing power across mid-tier steel silo suppliers serving the Brazilian Cerrado and Black Sea corridors. This utilization dynamic forces suppliers to absorb margin pressure or differentiate through coating certification tiers, reshaping procurement negotiations between agricultural cooperatives and equipment vendors.
Pricing Analysis
Long-term offtake contracts dominate procurement between North American agricultural cooperatives and established fabricators, locking in volume commitments across multi-harvest cycles. Spot purchasing governs emergency capacity deployment by grain traders arbitraging compressed harvest windows. Price differentiation rests on EPA-compliant coating tiers and aeration system sophistication, with premium configurations commanding substantial uplifts. Cost compression in standard-grade steel silos is intensifying because Brazilian and Argentine import competition is flooding regional markets with uncoated alternatives. Commercial farmers exhibit the highest price sensitivity, prioritizing on-farm buffer capacity within tight capital budgets, while grain traders absorb premium pricing for rapid-deployment modular systems.
Supply Chain Analysis
Tariff exposure between the United States and China dominates raw material cost volatility for corrugated galvanized steel inputs. Manufacturing concentrates in China, the United States, and Germany, with Chinese mills supplying cost-competitive base steel and German fabricators specializing in REACH-compliant coating systems. The supply chain draws from zinc smelters in Australia and Peru, scrap metal recyclers across the US Midwest, and specialized aeration component suppliers in Germany. Single-source vulnerability sits with geotechnical engineering contractors for large-scale concrete foundation projects clustered in Bavaria and Iowa. Distribution runs through captive dealer networks anchored by Sukup Manufacturing Co. across the US corn belt, supplemented by independent maintenance cooperatives fragmenting aftermarket service revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as Black Sea export corridor reconstruction and Brazilian Cerrado expansion drive replacement demand following infrastructure damage and deferred maintenance cycles.
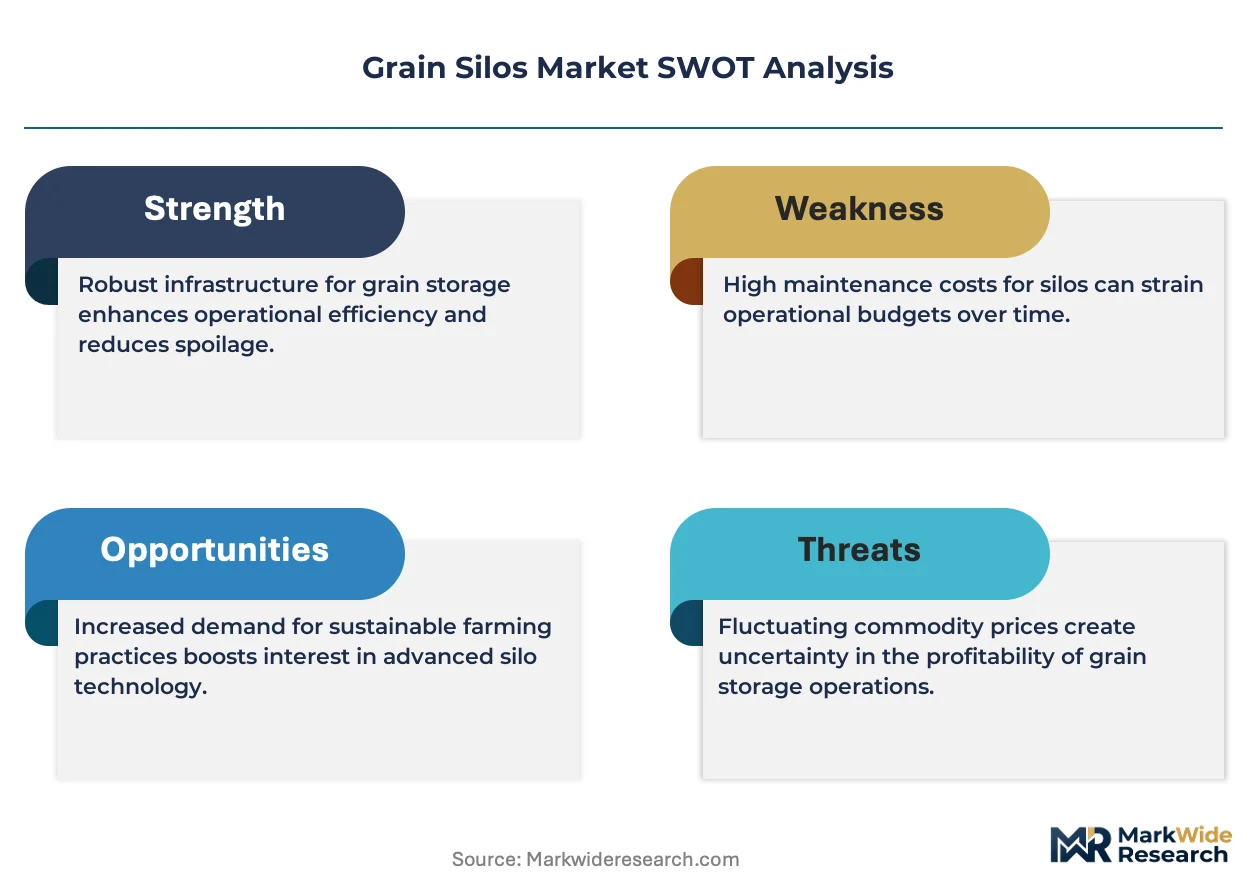
For Market Incumbents: Harden aftermarket service moats against independent maintenance networks by embedding IoT-aeration sensors into captive monitoring contracts that lock in recurring revenue. Deepen backward integration into zinc coating application to defend margin position against Chinese import price pressure. Prioritize EPA and EU Green Deal certification investments as competitive barriers that disqualify lower-cost regional competitors from tender participation. For New Entrants and Emerging Players: Establish a beachhead in relocatable pre-engineered silo configurations serving speculative grain traders in Argentina and Ukraine who prioritize asset flexibility over permanent infrastructure. Target the medium-scale cooperative segment in Mato Grosso and Goiás where incumbent coverage remains thin and rapid capacity deployment commands premium pricing. Pursue licensing partnerships with established coating suppliers to shortcut REACH and EPA compliance timelines. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because independent maintenance networks and regional fabricators face margin compression from galvanized steel volatility and regulatory compliance costs. Acquisition targets include specialized aeration system suppliers with IoT integration capabilities and modular pre-engineered design houses with proven rapid-deployment track records. Watch for inflection when carbon border adjustment mechanisms in the EU begin disqualifying high-embodied-carbon imports from tender eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Application | Captive zinc coating lines insulate margins from Chinese steel price volatility and EPA compliance delays. |
| IoT-Aeration System Convergence | Wireless sensor networks embedded in Sukup and Symaga installations compress spoilage response times and justify service contract premiums. |
| Modular Pre-Engineered Licensing | Factory-fabricated panel systems licensed to regional partners accelerate penetration in Brazil's Cerrado without capital-intensive field crews. |
| EU Green Deal Carbon Certification | Verified low-carbon supply chain documentation unlocks tender eligibility as carbon border adjustments tighten import rules. |
| Independent Maintenance Network Acquisition | Consolidating regional repair cooperatives recaptures aftermarket revenue pools fragmenting away from OEM service contracts. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with grain elevator operations managers, agricultural cooperative procurement directors, EPA compliance officers, and aftermarket service technicians; and secondary validation through USDA grain storage incentive program filings, EPA emissions standard enforcement records, EU ETS carbon accounting disclosures, and customs trade data on galvanized steel imports. Bottom-up capacity installation tracking across the US corn belt, Black Sea corridor, and Brazilian Cerrado was triangulated against top-down agricultural output projections.
Forecast inputs incorporated structural material segmentation by durability requirements, capacity tier deployment velocity, and end-user sophistication across cooperative, trader, and processor archetypes. Modeled dimensions spanned product type, installation methodology, and regional regulatory cluster intensity. CAGRs were derived from installed base depreciation schedules and replacement cycle timing observed across the projection horizon, with specific weighting for EU Green Deal compliance investment acceleration and IoT-aeration adoption curves in Iowa and Illinois cooperative networks.
Sensitivities concentrate around galvanized steel price volatility, Black Sea corridor stability, and carbon border adjustment implementation timing. Forecasts reflect assumptions on cooperative capital expenditure continuity and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Low Fat Rice Market
Grains
North America Rice Market
Grains
Global Oats Market
Grains
Wheat Bran Market
Grains
Asia Pacific Maize Market
Grains
Asia-Pacific Wheat Market
Grains
Sorghum Market
Grains
Paraguay Grains Market
Grains
Grain Dryers Market
Grains
Grain Augers Market
Grains
Pea Grits Market
Grains
Organic Rice Flour Market
Grains
Masa Corn Products Market
Grains
Africa Maize Market
Grains
Argentina Maize Market
Grains
Grain and Cereal Crop Market