
 Global Grain Analysis Market | 2026-2036
Global Grain Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Grain Analysis Market Foresight
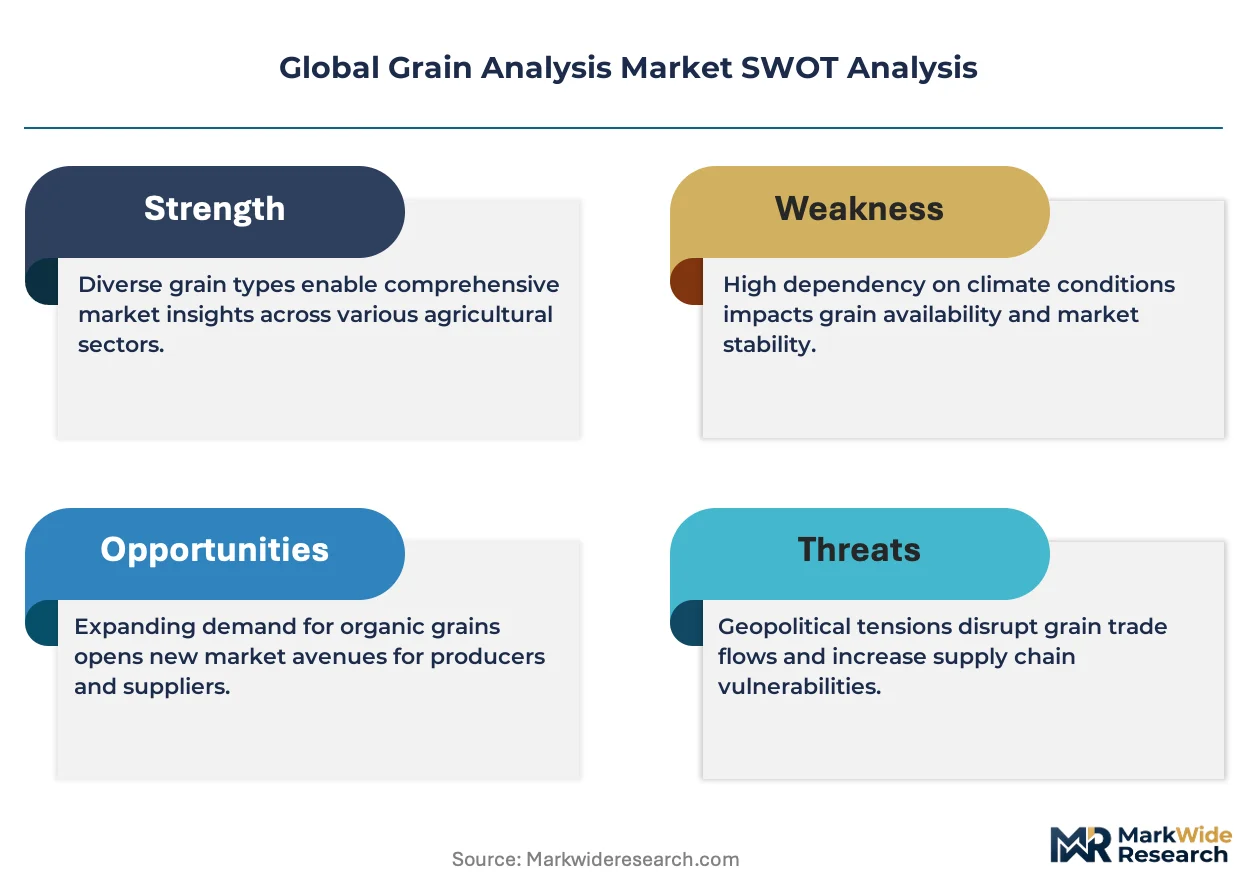
The grain analysis equipment landscape is restructuring around a sharp split between premium laboratory-grade systems and portable field-deployable units. Eurofins Scientific anchors the premium tier through its centralized reference laboratory network across multiple continents. SGS SA competes with integrated inspection and testing protocols that bundle sampling with certified analytical reporting.
Grain analysis encompasses the quantitative and qualitative assessment of cereal crop composition, moisture content, protein levels, and contaminant burden using spectroscopic, chromatographic, or molecular biological methods operating at detection thresholds measured in parts per billion. Its primary commercial purpose is to certify grain lots for trade, ensure feed and food safety, and optimize storage and processing parameters. Spectroscopy systems dominate installed base volume due to their non-destructive speed and minimal sample preparation, while PCR equipment captures concentrated margin pools in GMO screening and identity preservation workflows. Moisture analyzers sustain steady replacement demand as grain handlers upgrade from legacy capacitance-based units to more precise microwave resonance technologies.
The FDA, EFSA, and FAO/WHO Codex Alimentarius Commission collectively shape instrument demand through evolving mycotoxin limits, GMO labeling mandates, and harmonized sampling protocols that raise compliance thresholds for exporters. China's SAMR and GB standards for grain quality classification further fragment certification requirements for international traders. Stakeholders must monitor divergence between regional maximum residue limits and the analytical sensitivity required to document compliance at origin.
Market Dynamics
Near-infrared spectroscopy platforms are compressing analysis cycles from hours to minutes at commercial grain elevators, while regulatory divergence between EU maximum residue limits and FDA guidance on aflatoxin thresholds forces exporters to maintain dual certification protocols.
Growth Catalysts
- EU Mycotoxin Thresholds:Tightened EFSA maximum residue limits for aflatoxin and ochratoxin A in cereals mandate laboratory-grade screening at grain receiving points across member states.
- Feed Safety Mandates:China's SAMR enforcement of GB standards for grain quality classification creates compliance-driven instrument demand among exporters targeting Asian markets.
- Non-Destructive Speed:Spectroscopy systems eliminate wet-chemistry preparation delays, enabling real-time protein and moisture determination during harvest intake windows.
Market Restraints
- Reference Standard Costs:Certified mycotoxin reference materials and CRMs for aflatoxin B1 carry per-unit costs that constrain small-elevator adoption of in-house testing.
- Optics Supply Concentration:Precision NIR detector arrays and holographic gratings concentrate among German and Japanese optical component suppliers, creating lead-time vulnerability.
- PCR Throughput Limits:GMO screening workflows face bottlenecks from thermal cycler well-count constraints and nucleic acid extraction labor intensity.
Strategic Opportunities
- Identity Preservation Workflows:Non-GMO and organic certification chains in Ukraine and Argentina require blockchain-integrated sampling and PCR verification at multiple custody transfer points.
- Handheld Raman Convergence:Miniaturized 785-nm Raman systems paired with smartphone-based spectral libraries enable field-deployable mycotoxin screening without laboratory infrastructure.
- India FSSAI Modernization:The Food Safety and Standards Authority of India's push for centralized grain testing laboratories creates tender opportunities for automated sample preparation robotics.
Industry Challenges
- Spectroscopy Calibration Drift:NIR models require continuous updating against primary reference methods as grain varietals and growing conditions shift seasonally.
- Cross-Border Method Harmonization:Discrepancies between AOAC International, ISO, and Codex Alimentarius sampling protocols force laboratories to maintain multiple accredited procedures for export certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Grain Analysis Market |
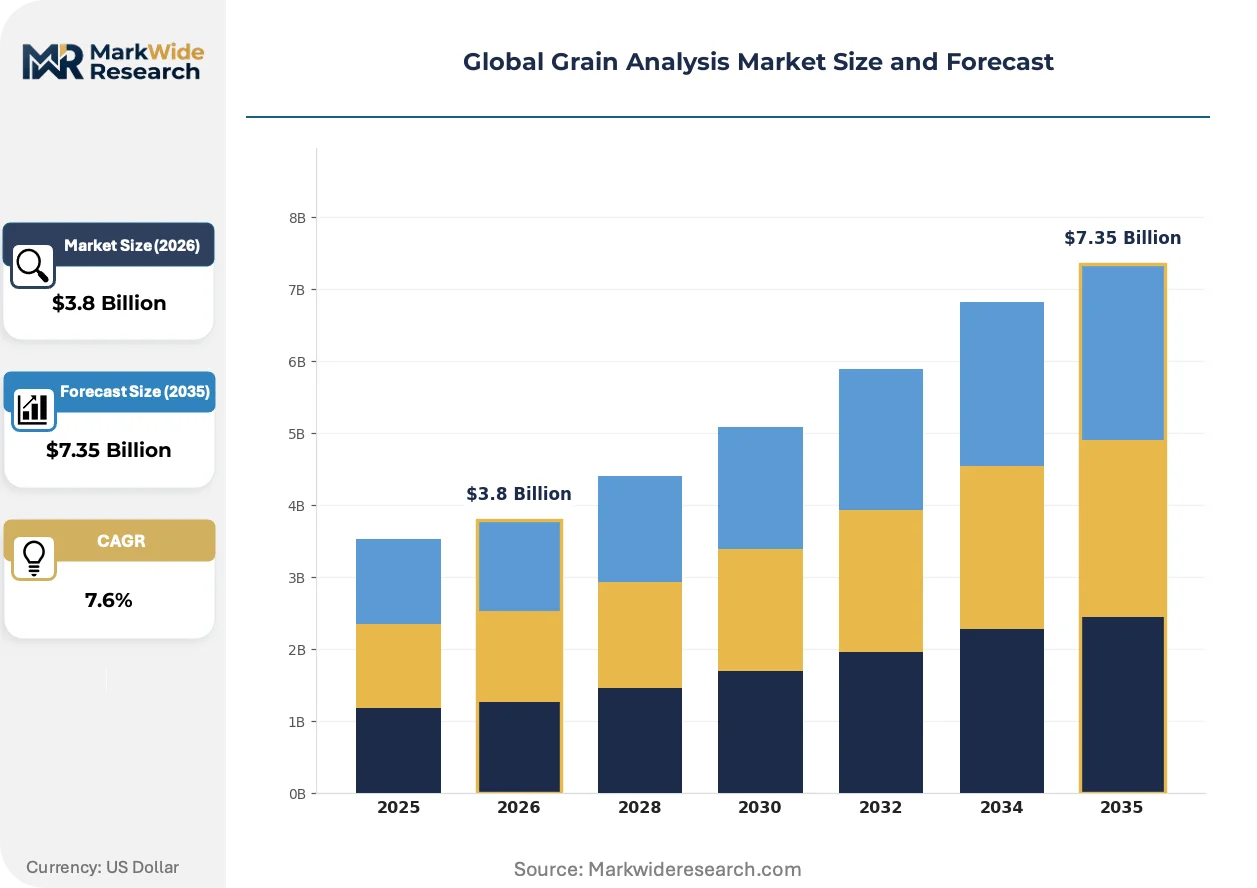
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spectroscopy Systems, Chromatography Instruments, PCR Equipment, Moisture Analyzers, Near-Infrared Analyzers Application: Quality Control, Contamination Detection, Nutritional Profiling, GMO Screening, Mycotoxin Analysis End User: Food Processors, Agricultural Research Institutes, Grain Exporters, Feed Manufacturers, Regulatory Authorities Distribution Channel: Direct Sales, Distributors, Online Platforms, Authorized Dealers, Technical Partners |
| Companies Covered | Thermo Fisher Scientific Inc., Eurofins Scientific, SGS SA, Intertek Group plc, NEOGEN Corporation, ALS Limited, Cargill, Incorporated, Archer Daniels Midland Company, Bühler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Grain Analysis Market Shifts & Advancements
Instrument architectures are bifurcating between laboratory reference systems and field-deployable units, with cloud-connected calibration models and AI-driven spectral interpretation compressing the expertise required for accurate grain grading.
Hyperspectral imaging systems operating in the 900-1700 nm range are expanding into commercial elevator operations for automated defect detection and foreign material identification. Large grain handlers in Iowa and Manitoba deploy these line-scan platforms at intake conveyors to replace manual sampling. The technology is expanding into premium segregation workflows where single-kernel protein mapping commands price premiums from specialty millers.
The EU Green Deal's Farm to Fork strategy imposes binding reduction targets for chemical pesticide residues in cereals, compelling grain traders to expand multi-residue LC-MS/MS screening beyond mycotoxins to include fungicide metabolites. This regulatory pressure cascades into instrument demand for high-resolution mass spectrometry platforms capable of non-targeted screening. Laboratories in Rotterdam and Hamburg respond by consolidating testing volumes into centralized reference facilities with SAMR-recognized equivalency.
Grain processors now unbundle analytical service contracts from equipment procurement, purchasing NIR platforms through operating lease structures with per-sample pricing rather than capital expenditure. This consumption-based model shifts maintenance and calibration liability to instrument vendors. The pattern is most pronounced among mid-sized cooperatives in France and Germany seeking to preserve balance sheet capacity for storage infrastructure expansion.
Global Grain Analysis Market Segmentation
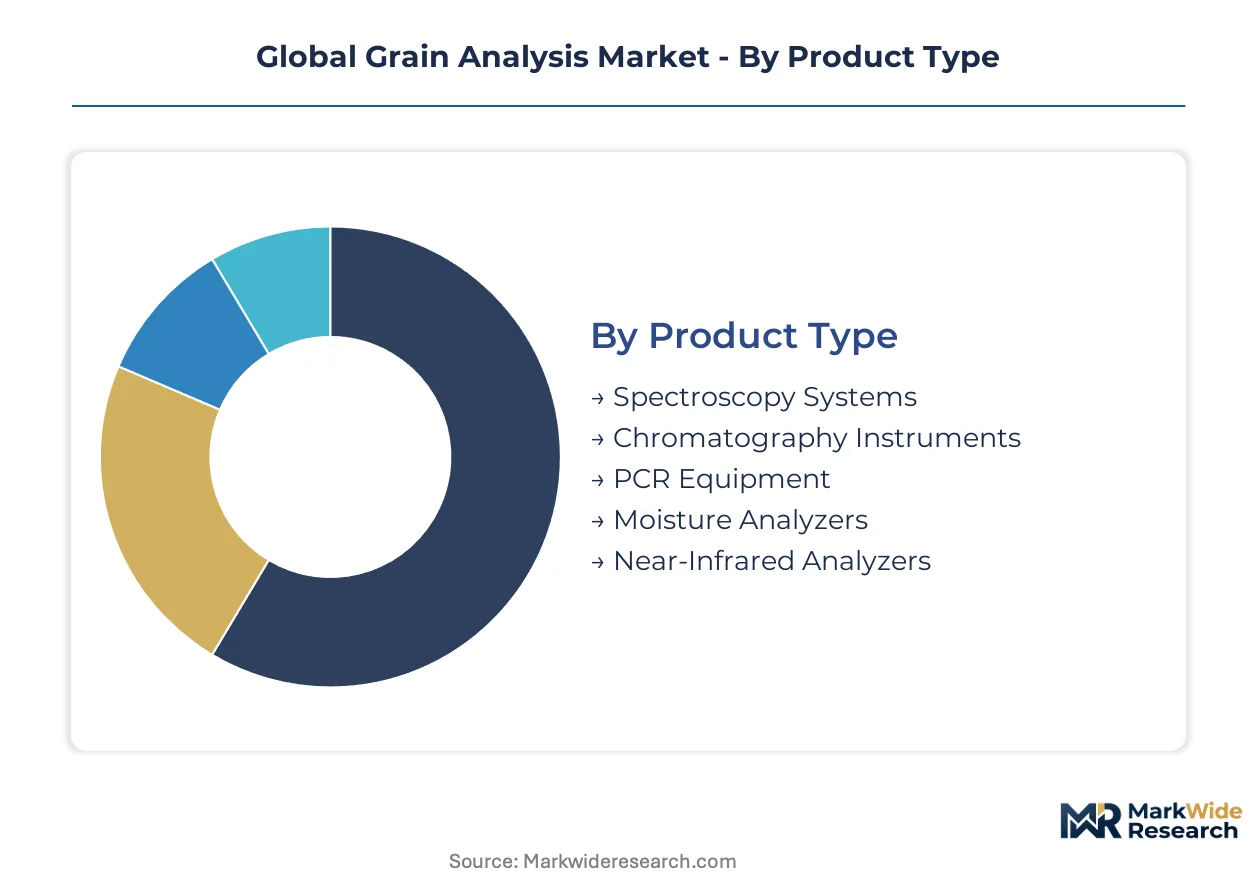
Grain analysis equipment procurement decisions pivot on certification requirements, with AOAC International and ISO 17025 accreditation determining which instrument categories qualify for export documentation. Segmentation reveals how regulatory fragmentation across FDA, EFSA, and SAMR jurisdictions creates divergent demand profiles for laboratory-grade versus field-deployable systems.
Product Type:
Spectroscopy systems and chromatography instruments carry the heaviest certification burden, requiring EFSA-recognized equivalency for EU grain trade and SAMR validation for Chinese import clearance.
- Spectroscopy Systems:NIR and FTIR platforms perform non-destructive protein, moisture, and oil quantification without wet-chemistry preparation. Demand concentrates at commercial elevators in Iowa and Manitoba during narrow harvest intake windows where throughput speed determines facility profitability. These systems require continuous calibration updates against primary reference methods as grain varietals shift.
- Chromatography Instruments:HPLC and LC-MS/MS systems deliver parts-per-billion detection thresholds for mycotoxin quantification mandated by tightened EU maximum residue limits. Laboratories in Rotterdam and Hamburg deploy these for multi-residue screening beyond aflatoxins to fungicide metabolites under the EU Green Deal's Farm to Fork strategy. Reference standard costs constrain adoption at smaller facilities.
- PCR Equipment:Thermal cycler systems enable GMO screening and identity preservation workflows with nucleic acid extraction protocols.
- Moisture Analyzers:Microwave resonance units displace legacy capacitance-based systems across Ukrainian and Argentine grain terminals.
- Near-Infrared Analyzers:Dedicated NIR platforms target protein mapping for specialty miller premiums in single-kernel segregation workflows.
Leading the category by volume: Spectroscopy Systems. Growing fastest: Chromatography Instruments.
Application:
Application selection tracks end-use margin structure, with contamination detection commanding premium pricing due to liability exposure while quality control sustains replacement-driven baseline demand.
- Quality Control:Routine protein, moisture, and test weight determination at grain receiving points supports base-grade certification for commodity trading. Installations span from primary elevators in Minnesota to port terminals in Brazil, with automation reducing labor intensity in high-throughput environments.
- Contamination Detection:Foreign material and defect identification via hyperspectral imaging line-scan platforms replaces manual sampling at intake conveyors. Large handlers in Iowa deploy 900-1700 nm systems for automated segregation, with single-kernel protein mapping commanding price premiums from specialty millers in Japan and Switzerland.
- Nutritional Profiling:Amino acid and fatty acid quantification supports feed formulation optimization for poultry and swine operations.
- GMO Screening:PCR-based identity preservation verifies non-GMO and organic certification chains across custody transfer points in Ukraine and Argentina.
- Mycotoxin Analysis:Aflatoxin and ochratoxin A screening at parts-per-billion thresholds satisfies FDA guidance and EFSA limits for human consumption.
Dominant by installed base: Quality Control. Climbing the fastest: Contamination Detection.
End User:
End-user procurement patterns separate capital-intensive laboratory networks from operating-lease adopters seeking per-sample pricing to preserve balance sheet capacity.
- Food Processors:Milling and baking operations require incoming grain certification for moisture and protein consistency to maintain product specifications. Facilities across France and Germany increasingly unbundle analytical service contracts from equipment procurement, shifting calibration liability to vendors through consumption-based models.
- Agricultural Research Institutes:Reference method development and varietal characterization drive demand for laboratory-grade chromatography and mass spectrometry platforms with full AOAC and ISO accreditation.
- Grain Exporters:Dual certification protocols for EU and Chinese markets necessitate SAMR-recognized equivalency at centralized reference facilities.
- Feed Manufacturers:Mycotoxin screening protects livestock productivity with detection thresholds stricter than food-grade requirements in some jurisdictions.
- Regulatory Authorities:Centralized grain testing laboratory tenders from India's FSSAI modernization program create demand for automated sample preparation robotics.
Highest absolute spending: Food Processors. Steepest expansion trajectory: Regulatory Authorities.
Distribution Channel:
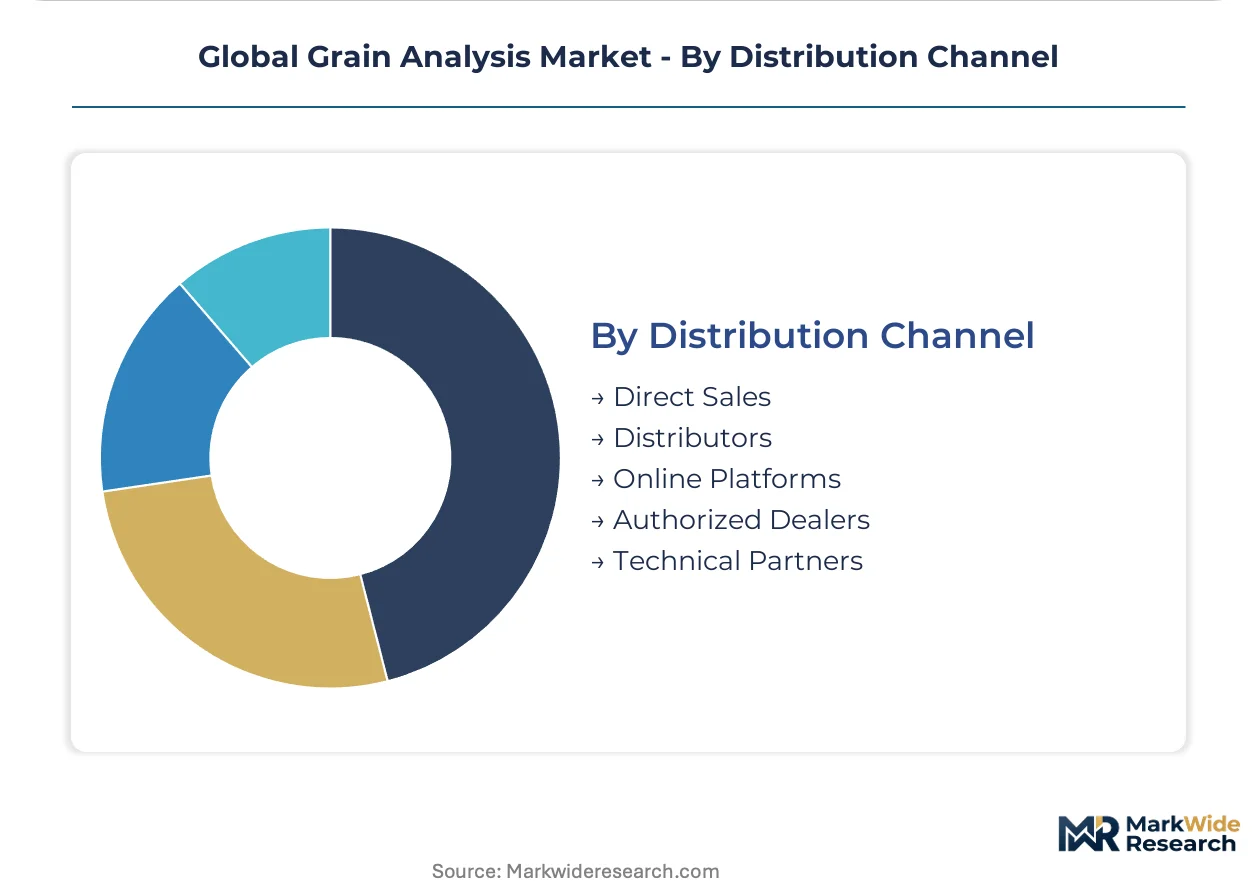
Channel selection reflects technical complexity, with spectroscopy and chromatography systems requiring installation and calibration support that online platforms cannot deliver.
- Direct Sales:Manufacturer-led engagements dominate laboratory-grade instrument procurement, with bundled service contracts covering maintenance, calibration, and regulatory compliance documentation. Eurofins Scientific and SGS SA anchor this channel through centralized reference laboratory networks.
- Distributors:Regional inventory and technical service coverage accelerates field-deployable unit penetration among mid-sized cooperatives lacking in-house metrology expertise.
- Online Platforms:Standardized moisture analyzers and consumables reach small elevators through e-commerce procurement with limited technical support.
- Authorized Dealers:OEM-certified installation and warranty service for portable Raman and NIR handheld units.
- Technical Partners:System integrators bundle grain analysis modules into broader automation projects for greenfield elevator construction.
Capturing majority volume: Direct Sales. Gaining share fastest: Technical Partners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam anchors the grain analysis infrastructure through its centralized reference laboratory network serving EU import certification. The port's testing facilities process mycotoxin screening for cereals entering European distribution channels.
United States
Iowa grain elevators deploy near-infrared spectroscopy platforms during narrow harvest intake windows where throughput speed determines facility profitability. FDA guidance on aflatoxin thresholds drives contamination detection investments across Midwest receiving points. Minneapolis-St. Paul corridor laboratories maintain dual certification protocols for export markets.
Germany
Hamburg laboratories consolidate multi-residue LC-MS/MS screening volumes under EU Green Deal Farm to Fork pesticide reduction mandates. EFSA maximum residue limits for ochratoxin A force upgrading from legacy wet-chemistry methods. Bavarian cooperatives unbundle analytical service contracts through operating lease structures with per-sample pricing.
China
SAMR enforcement of GB standards for grain quality classification creates compliance-driven instrument demand among exporters targeting domestic markets. Shanghai port terminals require centralized testing laboratory certification for import clearance. Yangtze River Delta grain handlers upgrade moisture analyzers to microwave resonance technologies.
India
FSSAI modernization programs generate tender opportunities for automated sample preparation robotics in centralized grain testing facilities. Mumbai laboratories face bottlenecks from thermal cycler throughput constraints in GMO screening workflows. Maharashtra feed manufacturers invest in mycotoxin detection to protect livestock productivity.
Brazil
São Paulo port terminals deploy hyperspectral imaging systems for automated defect detection at intake conveyors. ANVISA alignment with Codex Alimentarius sampling protocols forces maintenance of multiple accredited procedures for export certification. Paraná grain cooperatives adopt handheld Raman systems for field-deployable mycotoxin screening.
Global Grain Analysis Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade instrument tiers, with laboratory-grade chromatography and mass spectrometry systems commanding pricing multiples over portable field-deployable units. The vendor base organizes around three strategic archetypes: centralized reference laboratory networks, integrated inspection and testing protocol bundlers, and precision equipment fabricators with calibration service attachments. Consolidation pressures concentrate among mid-sized cooperatives seeking to outsource metrology expertise through consumption-based models. Dominant competitive moves include geographic expansion of accredited facility networks and technology licensing partnerships for miniaturized spectral platforms.
Within the reference laboratory archetype, Eurofins Scientific and SGS SA exemplify the centralized network model spanning multiple continents with bundled sampling and certified analytical reporting. Thermo Fisher Scientific Inc. occupies a position among precision equipment fabricators, anchoring the premium-tier instrument supply with calibration and maintenance service attachments. These three entities collectively represent the structural split between service-integrated and equipment-centric competitive positioning in grain analysis markets.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Eurofins Scientific |
| SGS SA |
| Intertek Group plc |
| NEOGEN Corporation |
| ALS Limited |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Bühler Group |
| Others |
Supply & Pricing Matrix
Precision NIR detector arrays from German and Japanese optical component suppliers cascade through three distinct pricing tiers as they reach grain elevator operators, reference laboratories, and mid-sized cooperatives across Iowa and Ukraine. Per-unit costs for certified mycotoxin reference materials constrain small-elevator adoption while bundled service contracts shift calibration liability to vendors.
Pricing Analysis
Per-sample pricing anchored to throughput volume dominates procurement decisions as Bavarian cooperatives and French grain handlers unbundle analytical service contracts from capital expenditure. Certification-grade differentiation separates AOAC-recognized laboratory systems from field-deployable units, with EFSA and SAMR validation tiers commanding premium positioning. Cost compression in the portable segment intensifies as smartphone-based spectral libraries displace dedicated hardware. Mid-sized cooperatives exhibit highest price sensitivity due to balance sheet constraints, while centralized reference laboratories absorb premium pricing for multi-residue screening capacity.
Supply Chain Analysis
Regional distribution centers in Hamburg and Rotterdam anchor hub-and-spoke patterns for chromatography consumables and reference standards serving EU grain trade. German and Japanese suppliers concentrate precision optics production, creating single-source vulnerability for holographic gratings and detector arrays. The supply chain draws from specialty chemical manufacturers in Switzerland and the Netherlands for certified reference materials. Tariff exposure on optical components threatens lead times for NIR platform assembly. Distribution runs through OEM-certified technical partners and direct manufacturer channels with bundled installation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal Farm to Fork pesticide reduction mandates erect a compliance moat that consolidates testing volumes into accredited facilities while excluding non-validated competitors from premium certification workflows.
For Market Incumbents: Anticipate handheld Raman convergence and AI-driven spectral interpretation compressing expertise requirements by deepening calibration service attachments and geographic expansion of SAMR-recognized equivalency networks. Consolidate testing volumes into centralized reference facilities before emerging players capture mid-sized cooperative operating lease demand. Certification investment in multi-residue LC-MS/MS capacity anchors defensive positioning against portable technology substitution. For New Entrants and Emerging Players: Miniaturized 785-nm Raman systems paired with smartphone-based spectral libraries offer technology-first wedge into field-deployable mycotoxin screening without laboratory infrastructure. Target India's FSSAI modernization tender pipeline for automated sample preparation robotics as the most penetrable geography. Pursue blockchain-integrated sampling verification for identity preservation workflows in Ukraine and Argentina as the primary go-to-market angle. For Investors and Strategic Acquirers: India's FSSAI centralized laboratory tender awards are the leading indicator that regulatory modernization will cascade into comparable procurement programs across Southeast Asian grain markets. Long-term viability centers on service-integrated positioning rather than equipment-only fabrication. Target acquisition archetypes include precision optics fabricators with captive detector array production and regional reference laboratories with multi-continent accreditation. Monitor divergence between EU MRL thresholds and FDA guidance as the signal for dual-certification infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Attachment Expansion | Bundled per-sample pricing shifts liability to vendors and locks in cooperative relationships across France and Germany. |
| SAMR-Recognized Equivalency Investment | Chinese GB standard compliance opens access to Yangtze River Delta grain handlers and export certification workflows. |
| Handheld Spectral Platform Miniaturization | 785-nm Raman convergence enables field-deployable screening without Rotterdam laboratory infrastructure. |
| Blockchain-Integrated Sampling Verification | Identity preservation chain custody supports non-GMO and organic premium segregation in Argentina and Ukraine. |
| Multi-Residue Screening Capacity Buildout | LC-MS/MS platforms capture EU Green Deal fungicide metabolite mandates beyond legacy mycotoxin workflows. |
Research Methodology
Multi-period observation of NIR platform deployment cycles, reference laboratory consolidation patterns, and regulatory threshold adjustments anchored the trend analysis, supplemented by interviews with grain elevator operations managers, reference laboratory directors, optical component procurement leads, and FSSAI tender program officials. Secondary validation drew from FDA guidance documents, EFSA scientific opinions, SAMR GB standard publications, and AOAC International certification registries. Bottom-up instrument shipment tracking triangulated against top-down trade flow analysis for cereals and oilseeds.
Segment-weighting across product type, application, end user, and distribution channel dimensions structured the analytical framework across the projection horizon. Equipment procurement patterns, replacement cycle timing, and regulatory compliance deadlines fed into CAGR derivation for spectroscopy, chromatography, PCR, and moisture analyzer categories. Calibration model update frequency and reference standard consumption rates provided grain analysis-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential harmonization between EU and FDA maximum residue limits, breakthroughs in quantum cascade laser spectroscopy, and geopolitical disruption of Black Sea grain trade corridors. Forecasts reflect documented assumptions regarding optical component supply continuity and accreditation body recognition protocols. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Rolled Oats Market
Grains
North America Wheat Protein Market
Grains
Gluten Free Ancient Grain Market
Grains
Asia Pacific Wheat Protein Market
Grains
China Wheat Protein Market
Grains
Millet Flour Market
Grains
Pulses Market
Grains
Non-Basmati Rice Market
Grains
Organic Oats Market
Grains
Soy Grits Market
Grains
United States Maize Market
Grains
Tunisia Grain Market
Grains
Fortified Rice Market
Grains
South American Maize Market
Grains
GCC Basmati Rice Market
Grains
Grain-Based Flours Market