
 Corn Flour Market | 2026-2036
Corn Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Flour Market Intelligence
The divergence between specialty organic products and bulk commodity corn flour is restructuring the competitive landscape. Archer Daniels Midland Company leverages its vast grain sourcing and processing scale to compete in the commodity segment. Ingredion Incorporated differentiates through its portfolio of modified starches and functional flours for specific food manufacturing applications. Gruma S.A.B. de C.V. sustains its market position through strong brand recognition in tortilla and masa flour, particularly in the Americas.
Corn flour is a powder ground from dried whole corn kernels, differing from cornstarch which uses only the endosperm. It primarily provides structure in baked goods like bread and muffins, and serves as a thickening agent in soups and sauces. Yellow corn flour leads in volume, but the organic corn flour segment commands a significant price premium. Within applications, snack foods are expanding quickly due to the demand for gluten-free products.
Food safety and labeling standards from bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern market access. These regulations, including India's FSSAI guidelines, dictate permissible additives, mycotoxin levels, and requirements for making 'gluten-free' claims. Producers must therefore align their sourcing and quality control processes with the specific certification demands of their target export markets.
Market Dynamics
The central force shaping the corn flour market is the divergence in demand between high-volume, price-sensitive commodity flour for processed foods and high-margin, certified gluten-free and organic flours for the health-conscious consumer segment, creating two distinct value chains.
Growth Catalysts
- Gluten-Free Labeling Regulations:Stricter standards for 'gluten-free' claims, such as those mandated by the US Food and Drug Administration (FDA), legitimize the category and build consumer trust, directly stimulating demand from individuals with celiac disease or gluten sensitivity.
- Snack Food Sector Expansion:The global snack food industry's continuous search for versatile, cost-effective, and gluten-free bases for extruded snacks, chips, and crackers provides a consistent volume driver for corn flour.
- Fortification Programs:Government-led food fortification initiatives in developing nations to combat micronutrient deficiencies are increasing the use of corn flour as a carrier for essential vitamins and minerals in staple foods.
Market Restraints
- Input Price Volatility:Corn grain prices are subject to significant fluctuations based on weather events, biofuel mandates, and global trade policies, creating margin pressure and planning uncertainty for flour millers.
- Threat of Substitution:In the gluten-free segment, corn flour faces intense competition from other functional flours, including rice, tapioca, and chickpea flour, which offer different textural and nutritional profiles.
- Mycotoxin Contamination Risk:Stringent limits on mycotoxin levels, enforced by bodies like the European Food Safety Authority (EFSA), can lead to costly batch rejections and supply chain disruptions, acting as a barrier to trade.
Strategic Opportunities
- Plant-Based Formulations:The expanding plant-based food industry presents an opportunity for corn flour to be used as a binder, texturizer, and coating in meat and dairy analogs, moving beyond traditional bakery applications.
- Functional Blends:Developing pre-mixed blends of corn flour with proteins, fibers, and other functional ingredients offers a pathway to capture value in the health and wellness food ingredients market.
- Emerging Market Penetration:Rising disposable incomes and urbanization in Southeast Asian and African nations are creating new consumer bases for processed and packaged foods that utilize corn flour as a primary ingredient.
Industry Challenges
- Supply Chain Traceability:Maintaining and documenting the integrity of organic or non-GMO supply chains from farm to finished product is a complex and costly operational challenge, requiring significant investment in certification and tracking systems.
- Energy Cost Management:The energy-intensive nature of drying and milling corn kernels exposes producers to volatility in electricity and natural gas prices, directly impacting production costs and overall profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Flour Market |
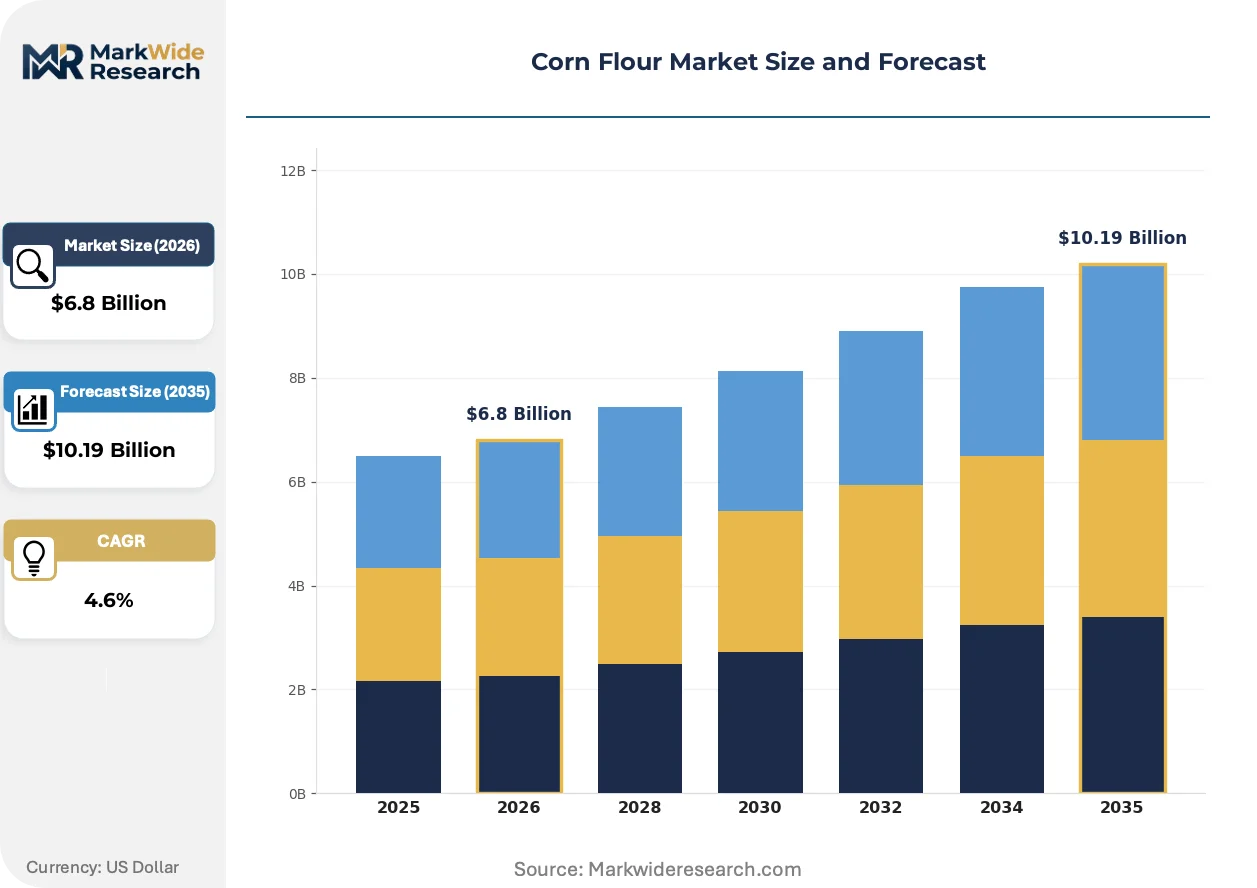
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Corn Flour, Whole Grain Corn Flour, White Corn Flour, Yellow Corn Flour Application: Baking, Thickening Agent, Snack Foods, Baby Food Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale End User: Households, Food Manufacturers, Restaurants, Bakeries |
| Companies Covered | Gruma S.A.B. de C.V., Tate & Lyle PLC, Archer Daniels Midland Company, Roquette Frères S.A., General Mills, Inc., Cargill, Incorporated, Bunge Limited, BENEO GmbH, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Flour Market Strategic Shifts & Innovations
Product innovation in corn flour is moving beyond its role as a bulk commodity. Emphasis on functionality, traceability, and specific dietary attributes is creating new value streams and segmenting the market based on processing technology and certification.
Modified corn flours, which are altered physically or enzymatically to achieve specific properties, offer superior stability and texture. Food manufacturers in the sauces, dressings, and dairy sectors are adopting these ingredients for improved viscosity and freeze-thaw performance. This technology is expanding into high-value functional ingredient applications, where it competes with more expensive hydrocolloids and gums.
India's Food Safety and Standards Authority (FSSAI) has implemented clear guidelines for 'gluten-free' product labeling and promoted food fortification. This regulatory framework establishes a structured market for certified corn flour, compelling producers to invest in dedicated processing lines and quality control. The regulations affect both domestic millers and importers aiming to serve India's vast and increasingly health-aware consumer base.
A consumer-driven preference for clean-label products is influencing ingredient selection criteria for major food brands. This behavioral shift favors minimally processed corn flours, such as whole-grain or organic varieties, over chemically modified alternatives in premium product lines. This trend is most pronounced within the natural foods channel and in categories like baby food and high-end baked goods in North America and Europe.
Corn Flour Market Segmentation
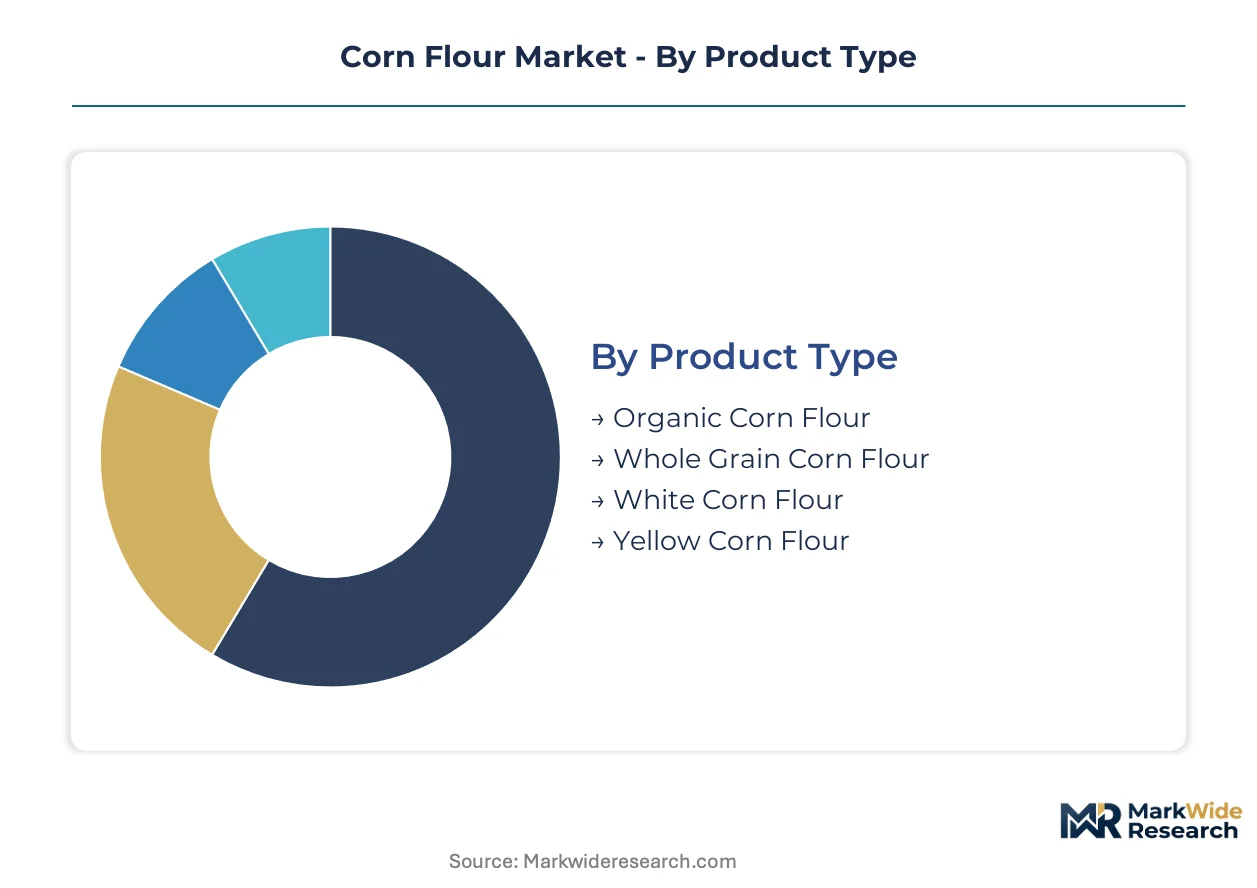
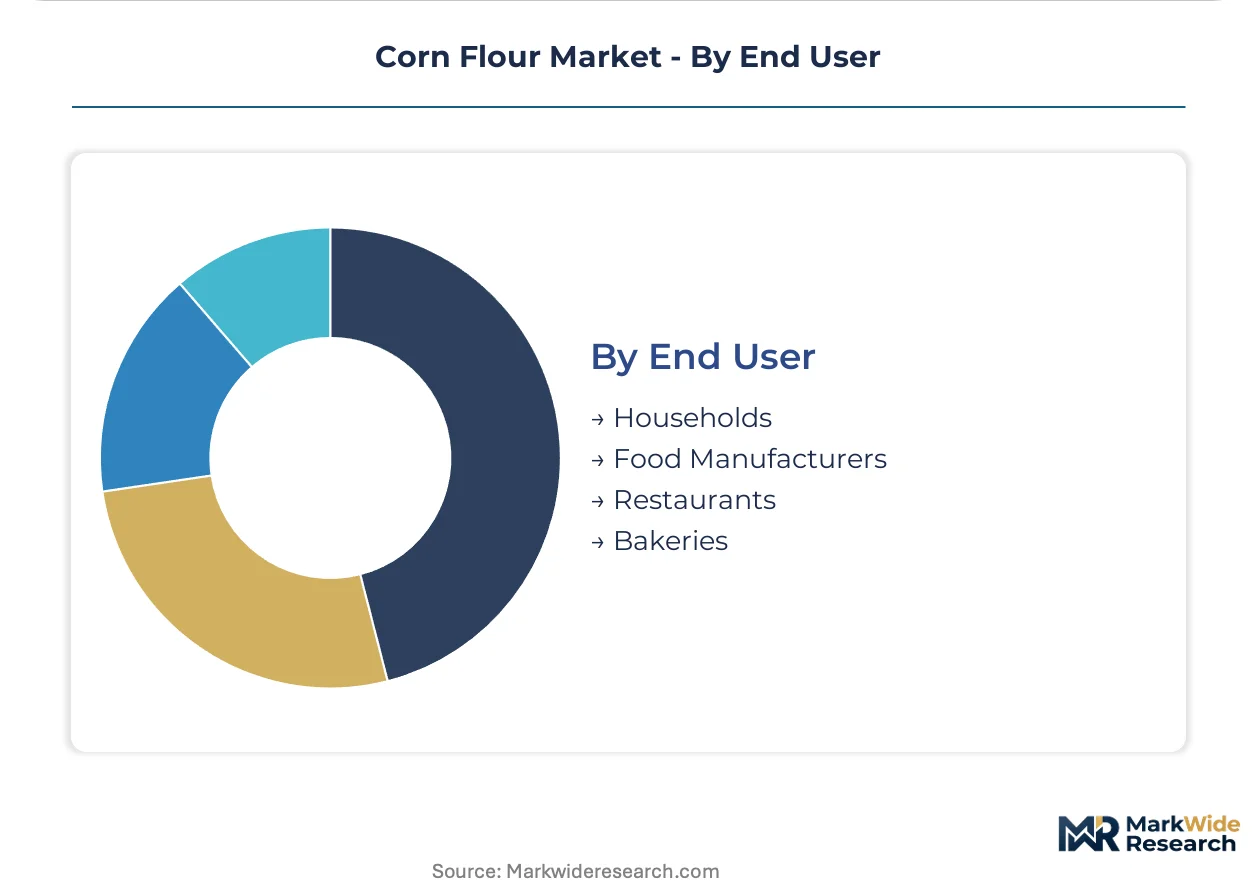
The corn flour market segments across product type, application, distribution channel, and end user, each revealing distinct demand drivers and competitive dynamics. Understanding these categories is critical for producers to tailor product offerings and market strategies effectively.
Product Type:
The corn flour market segments by product type, differentiating between commodity-grade flours used as embedded ingredients and specialty flours often sold as standalone consumer products.
- Organic Corn Flour:This flour derives from corn grown without synthetic pesticides or fertilizers, requiring stringent certification processes. Demand concentrates in European and North American health food stores, driven by consumer preference for clean-label ingredients.
- Yellow Corn Flour:Milled from yellow corn kernels, this variety provides a slightly sweet flavor and a characteristic yellow hue to finished products. Its high-volume use in processed foods and snack manufacturing in China and the US drives its market dominance.
- Whole Grain Corn Flour:This product retains all parts of the corn kernel, including the bran, germ, and endosperm, offering enhanced nutritional value.
- White Corn Flour:Ground from white corn varieties, this flour offers a milder flavor and lighter color, preferred for specific culinary applications like certain tortillas.
Volume placements concentrate in Yellow Corn Flour; the faster expansion belongs to Organic Corn Flour.
Application:
Segmentation by application highlights the diverse functional roles corn flour plays across various food industries, from primary structural components to subtle textural modifiers.
- Snack Foods:Corn flour serves as a primary ingredient in extruded snacks, chips, and crackers, valued for its gluten-free properties and ability to create crisp textures. The global snack food industry’s continuous innovation in product lines fuels significant demand.
- Baking:This application uses corn flour to provide structure, moisture retention, and a distinct flavor profile in items like bread, muffins, and tortillas. Traditional culinary practices in Latin America and growing gluten-free baking trends sustain this segment.
- Thickening Agent:Corn flour functions as a natural thickener in soups, sauces, and gravies, offering a smooth consistency without altering flavor significantly.
- Baby Food:Used in infant cereals and purees, corn flour provides a digestible and energy-rich base for early childhood nutrition products.
The Baking segment commands substantial volume, while Snack Foods exhibit the steepest expansion trajectory.
Distribution Channel:
The distribution channels for corn flour reflect varied consumer purchasing behaviors and the scale requirements of industrial buyers.
- Supermarkets:These large retail outlets offer broad consumer access to various corn flour products, catering to both household and smaller commercial baking needs. Wide geographic reach and established supply chains make supermarkets a primary channel.
- Online Retail:E-commerce platforms provide convenience and a wider selection of specialty corn flours, reaching niche consumer segments seeking organic or specific gluten-free options. This channel benefits from increasing digital adoption across consumer demographics.
- Health Food Stores:These specialized retailers stock premium and certified corn flour varieties, including organic and non-GMO options, targeting health-conscious consumers.
- Wholesale:This channel supplies large volumes of corn flour directly to food manufacturers and institutional buyers, focusing on bulk pricing and consistent supply.
Wholesale channels move the largest volumes, but Online Retail is gaining share fastest among consumer-facing options.
End User:
End-user segmentation reveals distinct purchasing patterns, distinguishing between large-scale industrial consumption and direct consumer purchases.
- Food Manufacturers:These industrial clients procure large volumes of corn flour for use in processed foods, snack production, and convenience meals. Their demand is driven by efficiency, consistent quality, and ingredient cost-effectiveness for mass production.
- Households:Individual consumers purchase corn flour for home cooking, baking, and dietary requirements, including gluten-free alternatives. Convenience and brand recognition influence purchasing decisions in this direct-to-consumer segment.
- Restaurants:Food service establishments utilize corn flour for various culinary preparations, including coatings, thickeners, and specialty dishes.
- Bakeries:Commercial bakeries use corn flour as a key ingredient in gluten-free breads, pastries, and other baked goods, catering to specific dietary needs.
Food Manufacturers account for the majority of industrial volume; Households represent a growing direct-to-consumer segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangzhou, a significant food processing and trade hub in China, drives substantial demand for corn flour as a foundational ingredient in its expansive food manufacturing sector. This regional concentration reflects broader industrial trends where large-scale production facilities seek consistent, high-volume ingredient supplies. Diverse consumer preferences for processed foods across Asia further amplify this demand.
United States
Demand for gluten-free products and continued expansion of the snack food sector define the corn flour market in the United States. The US Food and Drug Administration (FDA) establishes stringent labeling standards for gluten-free claims, building consumer trust. Major food manufacturers across the Midwest, particularly around Chicago, utilize corn flour extensively in processed snack production.
China
China's rapidly expanding food manufacturing base creates immense volume demand for versatile corn flour in processed goods. The national GB standards regulate food additives and quality, influencing ingredient selection by local producers. Industrial food parks in the Yangtze River Delta region, including Shanghai, are centers for corn flour consumption in various food applications.
India
Food fortification initiatives and a growing health-conscious consumer base stimulate corn flour demand in India. India's FSSAI guidelines promote food fortification, increasing corn flour use as a carrier for essential micronutrients. Food processing clusters in the Delhi-NCR region integrate corn flour into fortified staple foods and snack items.
Mexico
Traditional culinary practices, especially for tortillas and masa, anchor corn flour consumption across Mexico. Specific national food safety regulations ensure the quality and purity of corn-based products. Mexico City and its surrounding areas represent a significant hub for masa flour production and distribution to households and restaurants.
Germany
The market for organic and clean-label corn flour shows strong growth in Germany, driven by health-conscious consumers. The European Food Safety Authority (EFSA) sets strict limits on mycotoxin levels, ensuring high quality for imported and domestic corn flour. Bavaria's specialty food manufacturers are increasingly incorporating organic corn flour into premium baked goods and health products.
Corn Flour Market Key Industry Players
Premium-margin players sit above commodity-margin players across the corn flour market, characterized by product differentiation and certification rigor. The market exhibits a tiered structure, with large-scale processors competing on price and specialized firms focusing on niche applications. Companies pursue portfolio diversification and strategic partnerships to expand their market reach and product offerings.
Within the commodity segment, Archer Daniels Midland Company exemplifies a player leveraging vast grain sourcing and processing scale for high-volume supply. Ingredion Incorporated represents a specialist in functional flours, differentiating through its portfolio of modified starches for specific food manufacturing applications. Gruma S.A.B. de C.V. anchors the traditional market, sustaining its position through strong brand recognition in tortilla and masa flour, particularly across the Americas.
| Leading Market Players |
|---|
| Gruma S.A.B. de C.V. |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Roquette Frères S.A. |
| General Mills, Inc. |
| Cargill, Incorporated |
| Bunge Limited |
| BENEO GmbH |
| Ingredion Incorporated |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps in corn flour processing often prioritize long-term stability over short-term price volatility, influencing regional supply consistency and pricing discipline. Their investment in local sourcing networks can stabilize input costs for specific product lines.
Pricing Analysis
Value-based pricing in specialty corn flour segments anchors on functional performance, such as viscosity improvement or gluten-free texture. The dominant pricing structure remains contract-based long-term offtake for bulk commodity corn flour, while specialty varieties use per-unit transactional models. Price differentiation stems from certification level, particularly for organic and gluten-free products, and from volume scale for industrial buyers. Pricing softness runs through the commodity segment due to input price volatility from corn grain. Food manufacturers purchasing bulk corn flour are most price-sensitive, whereas health food brands seeking certified organic flour are least sensitive.
Supply Chain Analysis
Workforce availability, particularly for skilled milling operations and logistics, influences supply chain efficiency in major corn-producing regions like the United States and China. Global corn flour supply concentrates heavily in the United States, China, and Brazil, drawing from vast corn grain harvests. Raw material dependencies include corn kernels, energy for drying and milling, and specialized packaging materials. Commodity price volatility in corn grain represents a significant structural risk for millers. Distribution primarily runs through wholesale channels, directly supplying food manufacturers and large institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corn flour market is in a technology-transition phase, with advanced modified starches displacing traditional hydrocolloids in many functional applications. This shift redefines ingredient performance and cost-efficiency for food manufacturers.
For Market Incumbents:Anticipate continued margin pressure in bulk commodity corn flour from global grain price fluctuations. Invest in advanced processing technologies for modified flours to compete with specialized hydrocolloids. Deepen vertical integration into specialized corn sourcing, ensuring consistent quality for certified products. Expand capacity in key growth regions like Southeast Asia to capture new industrial demand.
For New Entrants and Emerging Players:Enter via niche segments focused on organic and clean-label corn flour for health-conscious consumers. The baby food application in Europe and North America represents a penetrable segment due to strong consumer preference for natural ingredients. Target functional blends for plant-based formulations, offering superior binding and texturizing properties. A direct-to-consumer online retail strategy, emphasizing traceability and certification, can build brand loyalty.
For Investors and Strategic Acquirers:Distressed-cycle entries favor vertically integrated mid-cap processors in the US Midwest, particularly those with strong access to non-GMO corn supplies. Long-term viability over a 5-10 year window depends on capturing value from the functional and specialty flour segments. Acquisition targets include regional millers with established organic certification and strong R&D capabilities in modified starches. The signal to watch is sustained growth in plant-based food manufacturing, indicating expanding demand for corn-derived ingredients.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Modified Starch Portfolio | Captures higher-margin functional ingredient demand, reducing reliance on bulk commodity sales. |
| Invest in Organic Certification & Sourcing | Addresses consumer preference for clean-label products, unlocking premium market segments. |
| Develop Plant-Based Food Formulations | Diversifies application base beyond traditional bakery, tapping into a high-growth sector. |
| Enhance Supply Chain Traceability | Meets stringent regulatory requirements and consumer demand for ingredient transparency. |
| Geographic Expansion into Southeast Asia | Accesses rapidly growing food manufacturing base and urbanizing consumer markets. |
Research Approach
Trade association data, regulatory filings from the FDA and EFSA, and customs records anchored secondary inputs for this study. Primary interviews with food manufacturing R&D directors, procurement leads for snack foods, and specialty ingredient distributors validated market trends. This approach combined bottom-up market sizing with top-down validation, ensuring robust data integrity. Public company 10-K filings and government agricultural reports provided additional quantitative context.
Market sizing was modeled at a granular level across product type, application, distribution channel, and end-user segments. Compound Annual Growth Rates (CAGRs) were derived by analyzing historical growth trajectories and projecting future demand drivers over the analysis window. The analytical framework integrated macroeconomic indicators, population growth, and per capita food consumption patterns. Key forecast inputs included gluten-free product innovation rates and plant-based food adoption trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme weather events impacting corn harvests or sudden shifts in trade policies. The forecasts reflect assumptions regarding regulatory stability and sustained consumer health trends. Material deviation in global corn prices or significant new competitive entries warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Green Pea Grits Market
Grains
Spain Rice Market
Grains
Barley Market
Grains
Global Maize Market
Grains
China Rice Market
Grains
Triticale Market
Grains
Gluten Feed Market
Grains
Asia Pacific Maize Market
Grains
Precooked Flour Market
Grains
Corn Market
Grains
Black Gram Market
Grains
United States Gluten-Free Oats Market
Grains
Torrified Wheat Market
Grains
Non-Basmati Rice Market
Grains
North America Maize Market
Grains
North America Oats Market