
 Global Flour Market | 2026-2036
Global Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flour Market Analysis
Food service distribution is tilting toward direct-mill partnerships as institutional buyers seek traceability and volume guarantees. Ardent Mills leverages its North American milling network to secure long-term contracts with quick-service restaurant chains. Wilmar International Ltd. anchors its position through integrated grain origination across Southeast Asian ports. Goodmills Group GmbH differentiates via specialty-grade wheat flour tailored to artisan bakery specifications.
Flour consists of finely ground cereal grains, legumes, nuts, or seeds, with wheat flour containing 9-15% protein content depending on extraction rate and hard versus soft wheat varietals; the primary commercial purpose is providing structure, viscosity, and browning reactions in baked goods and processed foods. Wheat flour dominates volume across industrial channels, while almond flour commands premium positioning in gluten-free and low-carbohydrate product lines. Specialty-grade flour captures expanding margin pools as clean-label and functional ingredient demands reshape formulation requirements in snack foods and premium baking segments.
Regulators including the FDA, EFSA, and India's FSSAI enforce mycotoxin limits, fortification mandates, and labeling standards that determine market access and product differentiation across jurisdictions. EU REACH compliance and GB standards in China impose additional purity and additive restrictions on imported flour and milling inputs. Stakeholders must monitor evolving grain origin documentation requirements and fortification policy shifts to sustain procurement flexibility and avoid supply disqualification.
Market Dynamics
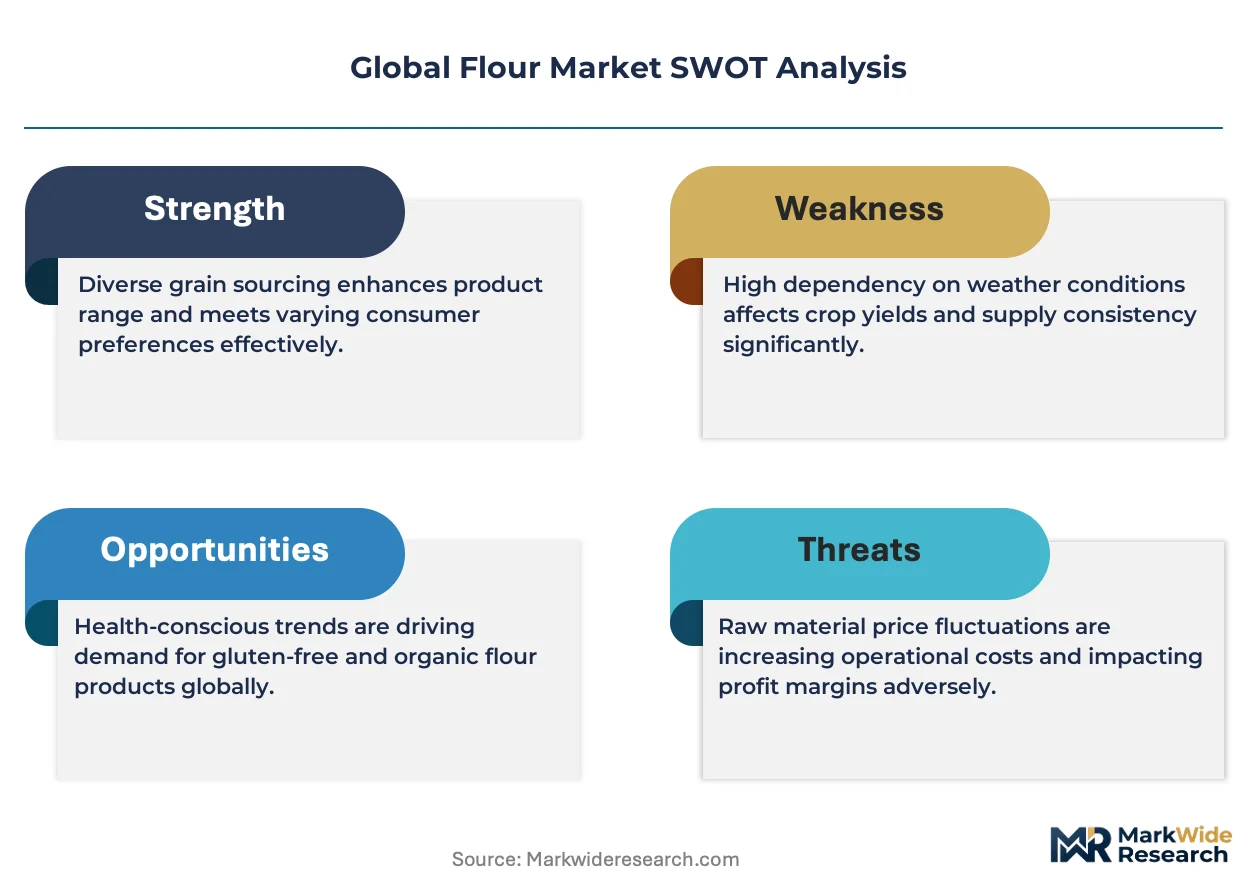
EU Green Deal sustainability requirements and F-Gas Regulation compliance mandates are forcing millers to reconfigure thermal processes, energy sourcing, and supply chain documentation systems across integrated operations.
Growth Catalysts
- India PLI scheme for food processing:The production-linked incentive program subsidizes capital investment in organized-sector milling, accelerating consolidation from fragmented chakki mills toward commercial facilities with fortification capabilities.
- Clean-label formulation demand:Snack food manufacturers and artisan bakeries specify single-origin wheat and heritage grain varieties, creating premium price tiers for identity-preserved flour streams with full traceability documentation.
- Enzymatic modification technology:Milling operations deploy fungal alpha-amylase and xylanase treatments to standardize dough rheology across variable harvest conditions, reducing batch rejection rates in industrial bakery contracts.
Market Restraints
- Wheat price volatility:Black Sea supply disruptions and drought cycles in Australia and Argentina transmit directly to input cost structures, compressing margins for non-integrated millers without origination assets.
- Fortification mandate fragmentation:Divergent iron, folic acid, and B-vitamin requirements across India's FSSAI, Nigeria's NAFDAC, and US FDA jurisdictions force SKU proliferation and compliance overhead without scale economies.
- Almond flour substitution threat:Keto and paleo diet adherence drives bakery formulators toward tree-nut alternatives in premium positioning, capping volume expansion for refined wheat flour in health-positioned product lines.
Strategic Opportunities
- Vietnam organized retail penetration:Modern trade expansion in Ho Chi Minh City and Hanoi creates channel access for branded packaged flour, displacing traditional loose-product wet markets with shelf-stable, fortified alternatives.
- Precision fermentation protein fortification:Converging biotechnology and milling infrastructure enables functional flour blends with embedded microbial protein isolates, targeting sports nutrition and clinical nutrition applications.
- Direct-to-bakery subscription models:Specialty millers bypass distributors to capture margin and demand data through recurring shipments to artisan micro-bakeries in Melbourne, Portland, and Copenhagen clusters.
Industry Challenges
- Mycotoxin testing certification timelines:EU REACH and GB standards in China require third-party laboratory verification for aflatoxin and deoxynivalenol levels, extending batch release cycles and working capital requirements.
- Legacy ERP integration with traceability platforms:Mid-cap millers face technical debt burdens connecting on-premise inventory systems to blockchain-enabled grain provenance networks demanded by quick-service restaurant procurement departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flour Market |
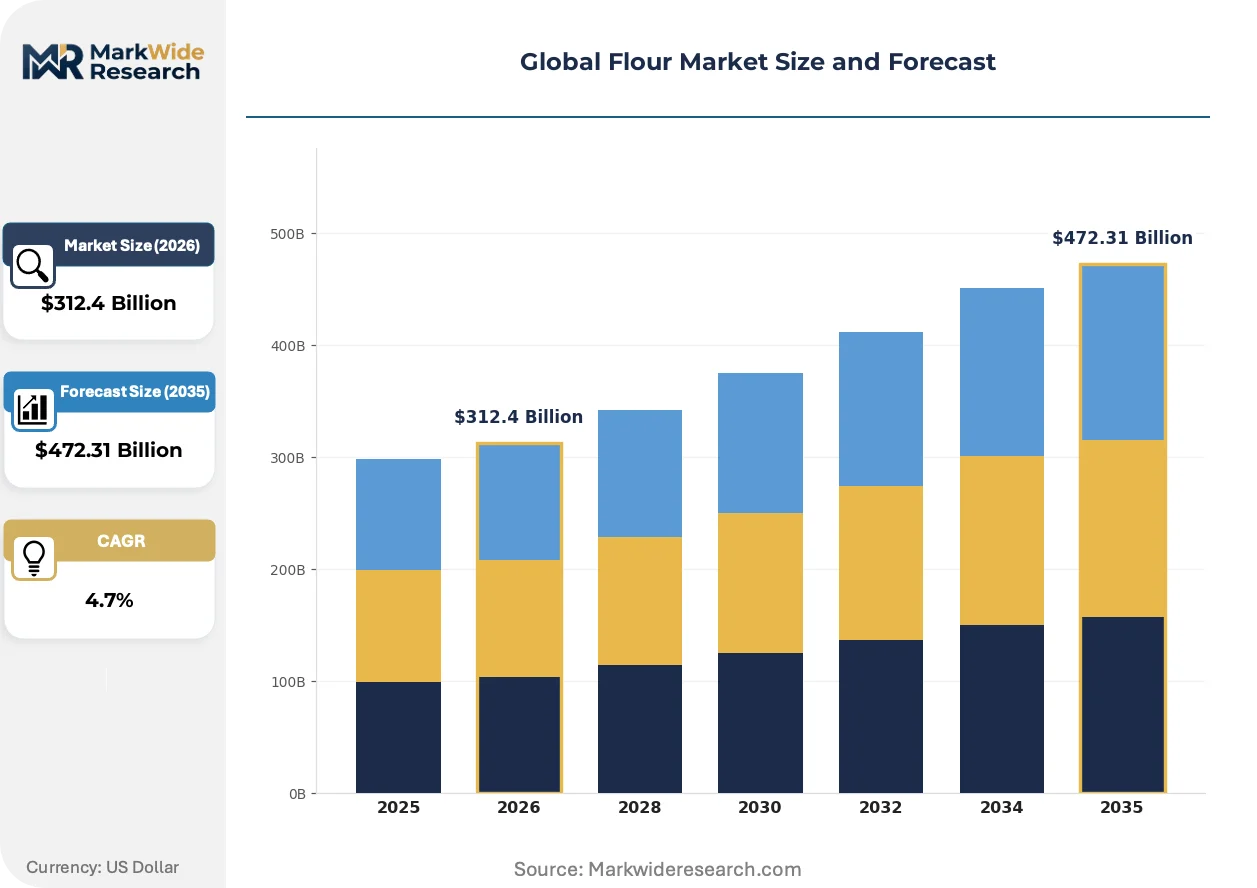
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $472.31 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat Flour, Rye Flour, Corn Flour, Almond Flour Grade: High Grade, Medium Grade, Low Grade, Specialty Grade Distribution Channel: Wholesale, Retail, Online, Food Service End Use: Baking, Cooking, Snack Foods, Industrial Applications |
| Companies Covered | Bunge Global, Wilmar International Ltd., Archer Daniels Midland Company, Interflour Group Pte Ltd, King Arthur Baking Company, Ardent Mills, Nisshin Seifun Group Inc., Goodmills Group GmbH, General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flour Market Emerging Trajectories
Near-infrared spectroscopy and automated batch control systems are digitizing quality assurance workflows, while regulatory fortification mandates and direct-mill procurement relationships reshape competitive positioning across wheat, alternative grain, and legume flour categories.
Hyperspectral imaging and machine learning algorithms deployed at mill intake points is digitizing grain segregation decisions. Large-scale commercial bakeries in Germany and the United States now require real-time protein and moisture data streams for contract compliance. This compression of analytical turnaround from hours to minutes is digitizing supplier qualification processes and disqualifying mills without inline sensing infrastructure.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants are forcing milling operations to retrofit pneumatic conveying and tempering systems with ammonia or CO2-based cooling architectures. Thermal process reengineering costs concentrate among Central European facilities with aging infrastructure. Italian and Polish millers are accelerating capital deployment to avoid production quota restrictions under the EU Green Deal implementation timeline.
Quick-service restaurant chains now mandate multi-year direct contracts with named mills rather than spot purchasing through foodservice distributors. This disintermediation concentrates volume commitments among Ardent Mills and Goodmills Group facilities with certified sustainable sourcing programs. The procurement model change is most visible in North American burger and sandwich chain supply chains, where traceability documentation requirements have eliminated two-tier distribution intermediaries.
Global Flour Market Segmentation
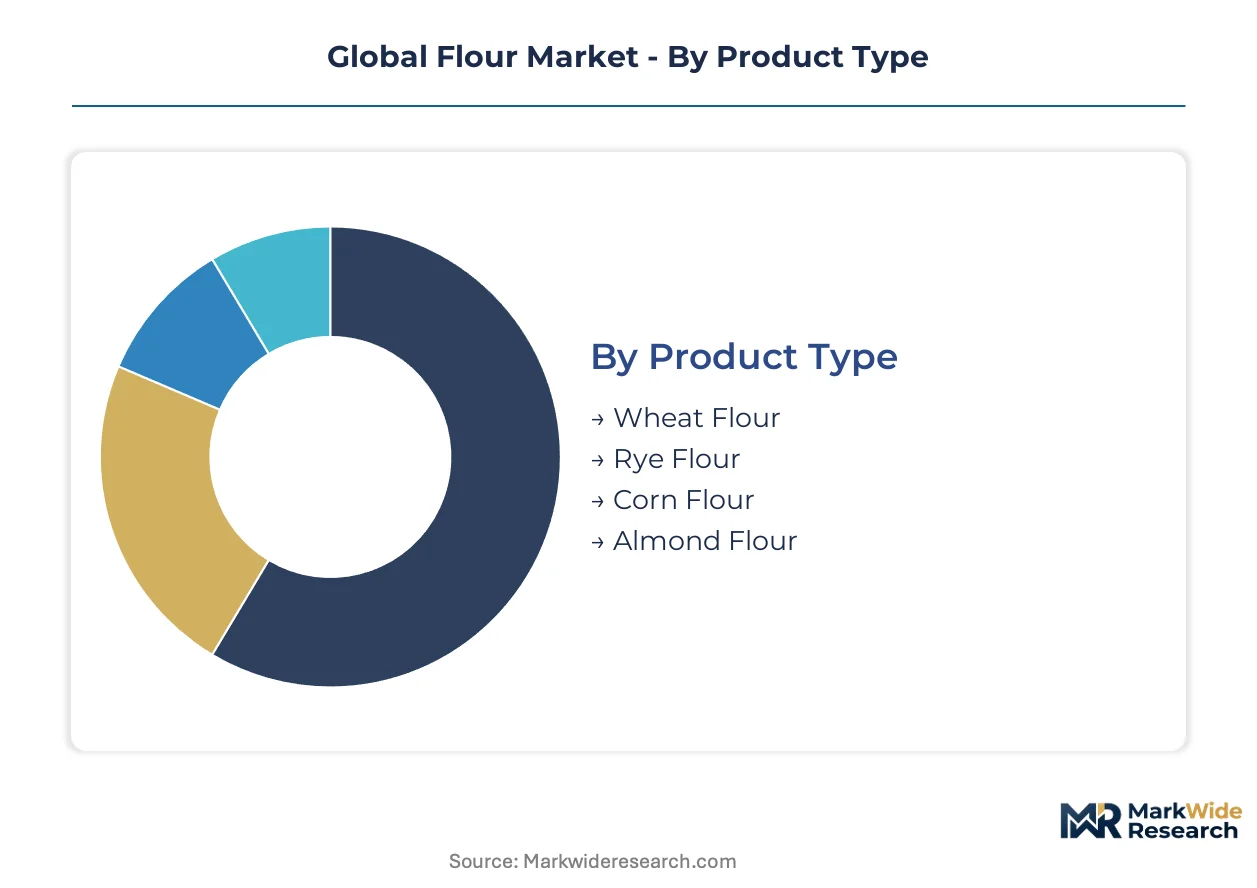
Flour market segmentation reveals how milling operations configure equipment, procurement, and quality systems around distinct product specifications. Each dimension—grain source, grade classification, channel access, and end-use application—carries unique margin profiles and regulatory compliance burdens.
Product Type:
Mature wheat flour dominates volume throughput while alternative grain and nut flours occupy emerging premium positioning with divergent supply chain requirements.
- Wheat Flour:Hard red winter and soft white wheat varietals deliver 9-15% protein content depending on extraction rate. Commercial bakeries in Germany and the United States specify protein levels within 0.5% tolerance for automated dough processing lines.
- Rye Flour:Pentosan-rich composition creates distinct viscosity profiles for dark bread traditions. Nordic and Baltic markets sustain demand for whole-grain rye with minimal enzymatic modification.
- Corn Flour:Masa harina specifications for tortilla production drive nixtamalization process investments among North American millers.
- Almond Flour:Blanched and natural varieties command premium positioning in ketogenic and gluten-free bakery formulations. California orchards supply the majority of raw material for industrial-scale almond flour production.
Wheat flour handles the majority of throughput; almond flour is the fastest mover on share.
Grade:
Cost tier stratification separates commodity volume plays from identity-preserved specialty streams with full traceability documentation.
- High Grade:Low ash content below 0.45% and consistent gluten strength specifications serve industrial biscuit and cracker manufacturers. EU EFSA mycotoxin limits enforce batch testing protocols that extend release timelines.
- Medium Grade:Standard extraction rates balance yield against baking performance for mainstream bread production.
- Low Grade:Higher bran inclusion suits animal feed and industrial starch applications with minimal quality premiums.
- Specialty Grade:Heritage grain varieties and single-origin wheat streams carry full provenance documentation. Artisan bakeries in Melbourne, Portland, and Copenhagen clusters specify named farms and harvest years.
Medium grade moves the largest volume tonnage; specialty grade is climbing the fastest on margin contribution.
Distribution Channel:
Customer type fragmentation separates institutional procurement with multi-year contracts from fragmented household purchasing with brand loyalty considerations.
- Wholesale:Bulk shipments to commercial bakeries and food manufacturers require FOB pricing and just-in-time delivery guarantees. Ardent Mills and Wilmar International anchor this channel with integrated origination networks.
- Retail:Packaged branded flour competes on shelf placement and fortification claims in modern trade formats.
- Online:Direct-to-consumer specialty flour subscriptions bypass distributor margins and capture demand data from home bakers.
- Food Service:Quick-service restaurant chains now mandate direct-mill contracts with traceability documentation, displacing traditional two-tier distribution.
Wholesale channels handle the majority of throughput; online direct sales are gaining share fastest among specialty segments.
End Use:
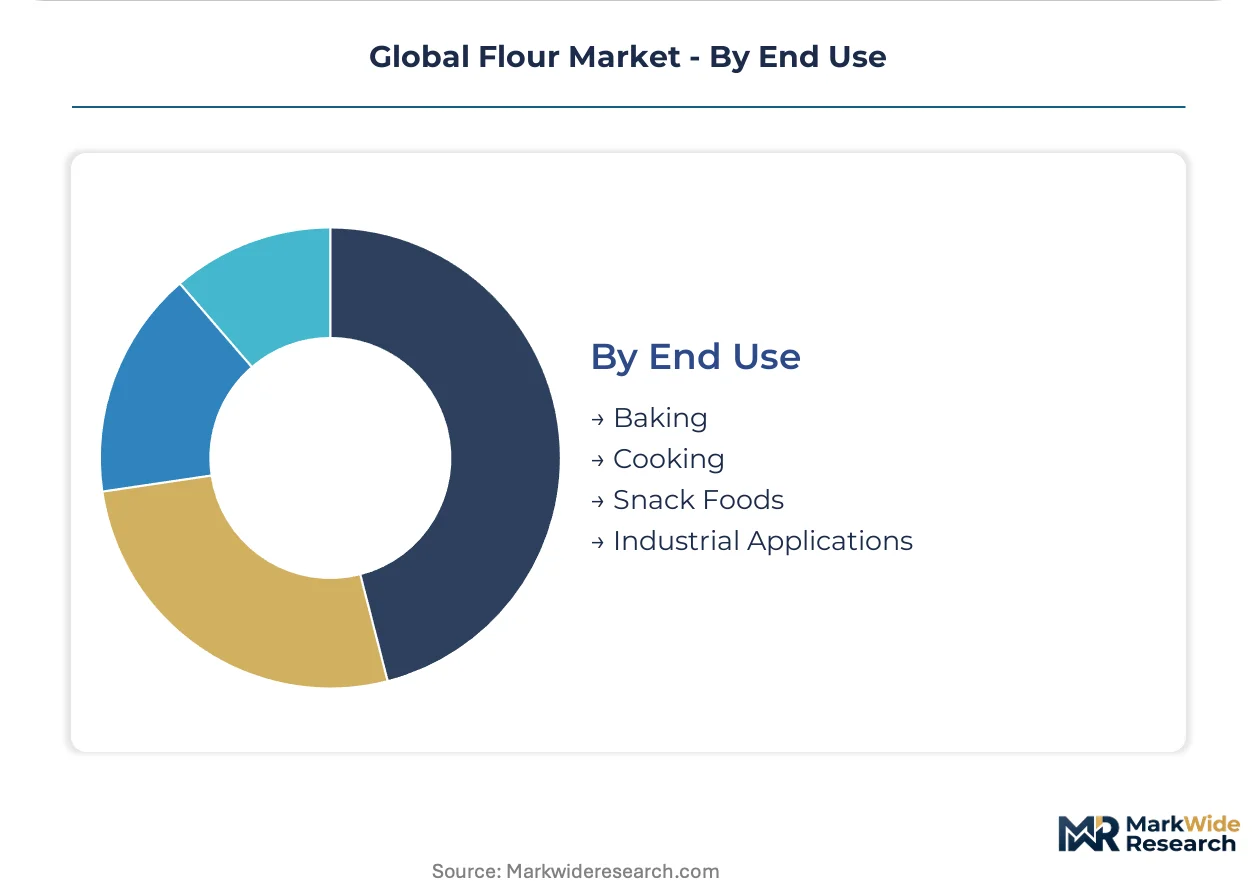
Application-specific requirements drive divergent milling investments, from high-capacity bread flour production to low-volume snack coating systems.
- Baking:Bread, pastry, and cake applications demand precise protein and ash specifications with enzymatic standardization. German and US industrial bakeries require real-time quality data streams for contract compliance.
- Cooking:Sauce thickening and coating applications prioritize starch gelatinization characteristics over gluten development.
- Snack Foods:Extruded and fried applications specify particular granulation ranges for texture control in seasoned coatings.
- Industrial Applications:Adhesive, pharmaceutical, and cosmetic uses consume food-grade flour for non-food applications with modified purity requirements.
Baking commands the largest share of flour consumption; snack food applications are expanding most quickly on formulation innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI fortification mandates and the PLI scheme for food processing anchor India as the dominant geography, while EU Green Deal requirements and F-Gas Regulation compliance reshape milling operations across European facilities.
India
Urbanization accelerates organized-sector flour consumption as consumers shift from fragmented chakki mills to packaged branded products. The PLI scheme for food processing subsidizes capital investment in commercial milling facilities with iron and folic acid fortification capabilities. Maharashtra and Gujarat host the largest concentration of new commercial milling capacity near Mumbai and Ahmedabad logistics corridors.
United States
Quick-service restaurant chains mandate direct-mill partnerships with traceability documentation for wheat sourcing. FDA mycotoxin limits and labeling standards enforce batch testing protocols that extend release cycles. Industrial bakeries in Chicago and Minneapolis-St. Paul metropolitan areas specify real-time protein data streams for automated dough processing compliance.
Germany
Artisan bakeries in Berlin and Munich drive demand for heritage grain varieties with full provenance documentation. EU REACH compliance and EFSA mycotoxin thresholds impose purity restrictions on imported wheat and milling inputs. Baden-Württemberg and Bavaria concentrate specialty-grade milling infrastructure serving premium biscuit and cracker manufacturers.
China
GB standards enforce additive restrictions and purity requirements on imported flour and domestic milling operations. Dual carbon goals accelerate energy sourcing transitions in thermal processes and pneumatic conveying systems. Shandong and Henan provinces anchor industrial wheat flour production for noodle and steamed bread applications.
Vietnam
Modern trade expansion in Ho Chi Minh City and Hanoi creates channel access for branded packaged flour displacing traditional wet markets. Organized retail penetration enables shelf-stable fortified alternatives with traceability claims. Foreign millers establish local production to capture margin in Southeast Asia's fastest-growing wheat flour demand center.
Global Flour Market Vendor Landscape
Vertically integrated agribusiness conglomerates and regional milling specialists split the market between scale-driven commodity throughput and identity-preserved specialty positioning. Tier-one players anchor procurement relationships with quick-service restaurant chains and industrial bakeries through multi-year direct contracts. Mid-cap specialists concentrate on heritage grain varieties and enzymatic modification capabilities for artisan bakery specifications. Competitive dynamics center on backward integration into grain origination assets and retrofitting aging facilities for EU F-Gas Regulation compliance.
Among Asia-Pacific integrated agribusiness operators, Wilmar International Ltd. anchors Southeast Asian port-based origination networks. Within the North American milling tier, Ardent Mills exemplifies scale-driven commodity positioning with certified sustainable sourcing programs. German-based Goodmills Group GmbH occupies the specialty-grade vector tailored to artisan bakery specifications and clean-label formulation requirements.
| Leading Market Players |
|---|
| Bunge Global |
| Wilmar International Ltd. |
| Archer Daniels Midland Company |
| Interflour Group Pte Ltd |
| King Arthur Baking Company |
| Ardent Mills |
| Nisshin Seifun Group Inc. |
| Goodmills Group GmbH |
| General Mills Inc. |
| Others |
Supply Flow & Price Mechanics
The Mumbai-Ahmedabad logistics corridor anchors cost dynamics across Indian organized-sector milling, where freight differentials between port-based grain intake and inland distribution centers compress margins for non-integrated operators while enabling price stratification between commodity and identity-preserved flour streams.
Pricing Analysis
The customization-premium spread widens substantially between commodity wheat flour and specialty-grade streams with full provenance documentation. Three-tier pricing structure across premium, standard, and economy levels reflects protein tolerance specifications, fortification compliance tiers under FSSAI mandates, and volume scale commitments from quick-service restaurant chains. Pricing pressure stems from Black Sea supply disruptions transmitting directly to input cost structures, compressing margins for non-integrated millers. Commercial bakeries exhibit lowest price sensitivity due to contract-based long-term offtake agreements, while fragmented chakki mill customers in India remain most responsive to spot price movements.
Supply Chain Analysis
Upstream feedstock flows draw from Australian hard red winter wheat, Argentine soft white varietals, and Black Sea origin grains depending on harvest cycles and tariff exposure. Milling operations rest on pneumatic conveying equipment, tempering infrastructure, and enzymatic modification systems as critical component dependencies. Single-source vulnerability concentrates in Black Sea corridor disruptions and drought cycles across major producing regions. Distribution runs through integrated origination networks at Southeast Asian ports for Wilmar International, direct-mill partnerships for North American quick-service restaurant chains, and modern trade formats displacing traditional wet markets in Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as direct-mill procurement relationships and blockchain-enabled traceability networks create interoperability requirements that concentrate volume among certified sustainable sourcing programs.
For Market Incumbents: Build certification moats around FSSAI fortification compliance and EU Green Deal sustainability documentation to defend against almond flour substitution in premium positioning. Deepen backward integration into grain origination assets across Australian and Argentine sourcing corridors. Capture channel control through multi-year direct contracts with quick-service restaurant chains that disintermediate traditional foodservice distributors. For New Entrants and Emerging Players: Pursue white-space opportunities in Vietnam's organized retail penetration and precision fermentation protein fortification for sports nutrition applications. The most penetrable segment sits in direct-to-bakery subscription models serving artisan micro-bakeries in Melbourne, Portland, and Copenhagen clusters with heritage grain varieties and full harvest-year documentation. A go-to-market angle anchored in enzymatic modification capabilities for dough rheology standardization addresses unmet needs in industrial bakery contract compliance. For Investors and Strategic Acquirers: Carve-out targets emerge from agribusiness conglomerates seeking to divest non-core milling assets amid EU F-Gas Regulation retrofitting cost burdens. Long-term viability centers on facilities with integrated origination networks and certified sustainable sourcing programs capable of serving direct-mill procurement relationships. The acquisition target archetype combines specialty-grade milling infrastructure with enzymatic modification technology. The signal to watch is quick-service restaurant chain procurement department migration toward real-time protein and moisture data stream requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Captures margin compression protection against Black Sea supply disruptions and Australian drought cycles. |
| EU F-Gas Regulation Compliance Retrofit | Avoids production quota restrictions under EU Green Deal implementation timelines for Central European facilities. |
| Direct-to-Bakery Subscription Launch | Bypasses distributor margins while capturing demand data from artisan micro-bakeries in premium clusters. |
| Precision Fermentation Protein Fortification | Enables functional flour blends targeting sports nutrition and clinical nutrition applications with embedded microbial protein isolates. |
| Blockchain-Enabled Traceability Platform | Satisfies quick-service restaurant procurement documentation requirements that eliminate traditional two-tier distribution intermediaries. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with commercial bakery procurement directors, milling operations managers, grain origination specialists, and foodservice distribution executives. Secondary validation drew from FSSAI fortification mandate filings, EU REACH compliance documentation, SEC 10-K disclosures from publicly traded agribusiness conglomerates, and customs trade data across major wheat importing corridors. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators to ensure consistency across volume and value outputs.
Calibration anchored on historical growth trajectories across wheat, alternative grain, and legume flour categories, with explicit modeling of grade tier, distribution channel, and end-use application dimensions throughout the forecast period. CAGRs derived from regression analysis against protein content specifications, extraction rate trends, and enzymatic modification technology penetration curves. Industry-specific inputs included PLI scheme subsidy disbursement timelines for Indian food processing capacity and EU F-Gas Regulation phase-down schedules for thermal process reengineering investments.
Macroeconomic conditions sit as an overlay; deviation in wheat commodity price volatility, freight rate fluctuations across Indian Ocean and Pacific corridors, or regulatory enforcement intensity under EU Green Deal implementation would shift the trajectory. Forecasts reflect documented assumptions regarding urbanization rates in India and Vietnam, substitution elasticity between wheat and almond flour in ketogenic formulations, and fortification mandate harmonization prospects across FSSAI, NAFDAC, and FDA jurisdictions. Cross-checking against USDA Foreign Agricultural Service production estimates and IGC grain market reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Red Rice Market
Grains
Precooked Flour Market
Grains
Grain Silos Market
Grains
Basmati Rice Market
Grains
Europe Wheat Market
Grains
Oatmeal Market
Grains
Global Grain Analysis Market
Grains
Dried Spent Grain Market
Grains
Green Banana Flour Market
Grains
Organic Wheat Flour Market
Grains
South America Rice Market
Grains
Asia-Pacific Rice Market
Grains
Durum Wheat Flour Market
Grains
United States Gluten-Free Oats Market
Grains
Colombia Grains Market
Grains
Lentil Market