
 Italy Rice Market | 2026-2036
Italy Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Rice Market Foresight
Modular packaging configurations combining vacuum-sealed retail packs with bulk food service formats is realigning procurement patterns across Italian rice distribution. Riso Gallo leverages vertical integration from mill to shelf to sustain brand visibility in domestic retail channels. Acquerello anchors its position through patented aging technology that differentiates its carnaroli grains in premium restaurant supply. Riso Scotti competes on manufacturing scale, operating one of Europe's largest rice processing complexes near Pavia.
Italy rice comprises Oryza sativa varieties cultivated in irrigated paddy fields, with carnaroli grains containing 24% amylose content that preserves structural integrity during extended cooking cycles for risotto preparation. Arborio dominates volume throughput across supermarket and wholesale channels due to its recognition among home cooks, while carnaroli commands margin concentration in food service and export segments where chefs prize its superior creaminess retention. Vacuum pack formats are expanding fastest within retail as shelf-life extension reduces spoilage losses for specialty varieties distributed through online channels.
EU Common Agricultural Policy subsidies shape planting decisions through direct payments tied to hectare limits and environmental conditionality requirements. Italy's Ministry of Agricultural, Food and Forestry Policies enforces DOP and IGP geographic indications that restrict carnaroli and arborio labeling to designated Po Valley zones, creating regulatory barriers for imported substitutes. Stakeholders must monitor CAP greening requirements and carbon accounting standards that will determine which milling operations qualify for continued premium positioning in European export markets.
Market Dynamics
The EU's Common Agricultural Policy greening requirements are redirecting hectare subsidies toward carbon-accounting compliance, forcing Po Valley millers to restructure cultivation protocols or forfeit premium export positioning.
Growth Catalysts
- CAP Environmental Conditionality:Direct payments now require sustainable water management and soil carbon retention, accelerating adoption of precision irrigation across Lombardy and Piedmont paddies.
- Food Service Premiumization:Northern Italian restaurants are specifying aged carnaroli for signature risotto preparations, pulling volume away from standard arborio through chef-driven procurement.
- Vacuum Packaging Technology:Extended shelf-life formats are unlocking e-commerce distribution for specialty varieties previously confined to gourmet retail.
Market Restraints
- Input Cost Volatility:Natural gas prices for parboiling and drying operations fluctuate with continental energy markets, compressing margins at mid-scale milling facilities.
- Supply Concentration Risk:Over 70% of carnaroli germplasm improvement relies on public breeding stations near Vercelli, creating varietal vulnerability to regional disease pressure.
- DOP Geographic Restrictions:Italy's Ministry of Agricultural, Food and Forestry Policies limits carnaroli and arborio labeling to designated Po Valley zones, blocking expansion into adjacent suitable territories.
Strategic Opportunities
- Sicily and Sardinia Underpenetration:These islands maintain rice cultivation infrastructure with distinct microclimates suitable for specialty red and black varieties commanding export premiums.
- Carbon Credit Stacking:CAP greening payments may combine with private soil-carbon protocols, creating dual revenue streams for early-adopter farms with verified measurement systems.
- Direct-to-Restaurant Platforms:Digital procurement channels are bypassing traditional wholesale tiers, allowing small DOP-protected mills to capture margin previously lost to intermediaries.
Industry Challenges
- Certification Timeline Compression:New EU carbon-accounting standards require third-party verification of cultivation emissions, with audit backlogs extending qualification periods beyond planting cycles.
- Irrigation Infrastructure Decay:Centuries-old Po Valley canal systems demand capital renewal that outstrips cooperative maintenance budgets, threatening water delivery reliability.
- Genetic Diversity Constraints:Narrow germplasm bases for premium varieties increase susceptibility to emerging blast fungus strains, requiring accelerated breeding program investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Rice Market |
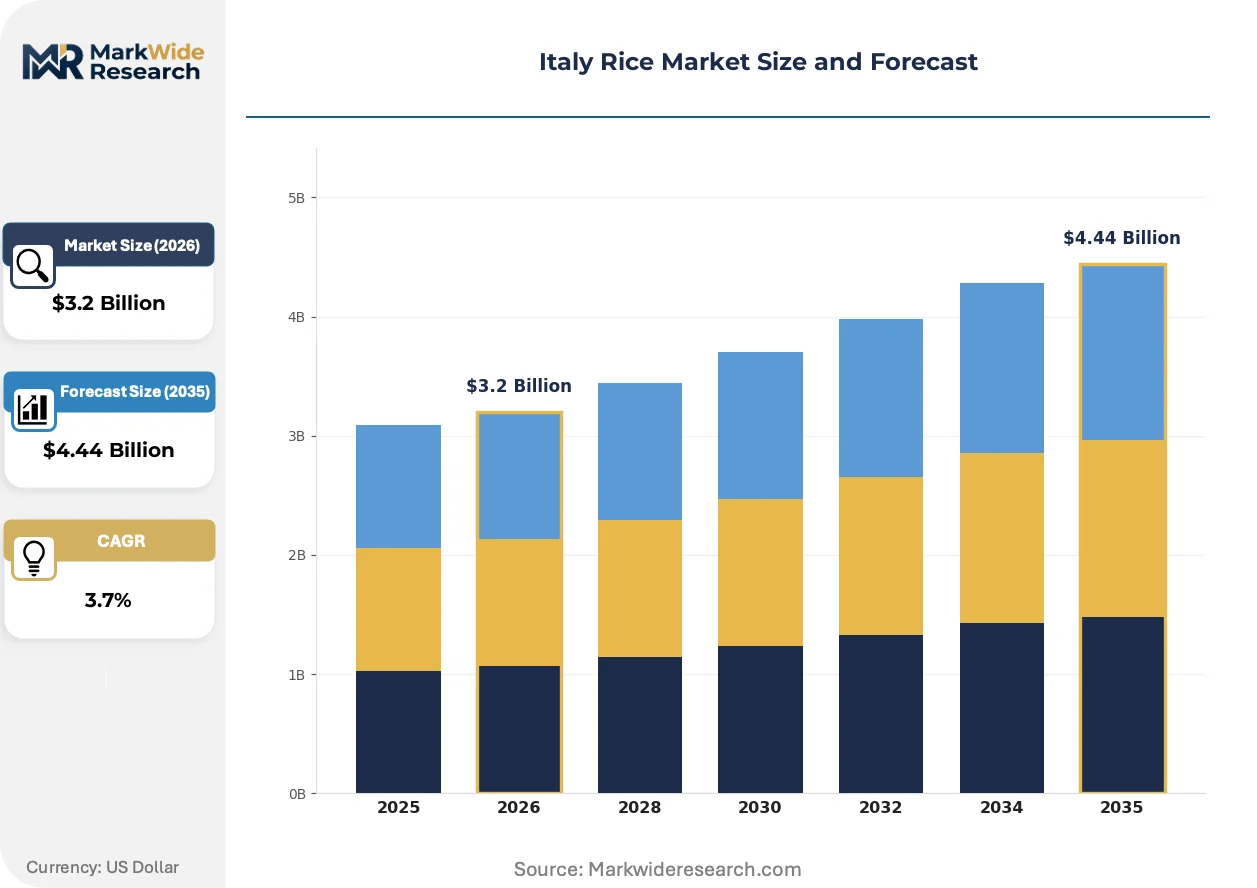
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $4.44 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arborio, Carnaroli, Vialone Nano, Baldo End User: Food Service, Retail, Exporters, Food Manufacturers Distribution Channel: Supermarkets, Online Retail, Wholesale, Direct Sales Packaging Type: Bulk Bags, Retail Packs, Vacuum Pack, Eco-Friendly Packaging |
| Companies Covered | Euricom, Acquerello, Riso Gallo, Paolo Grassi, Riseria Taverne, Riso Scotti, Cascina Belvedere, Germani Riso, Riso Vignola, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Rice Market Shifts & Advancements
Processing technology and distribution infrastructure are converging to reconfigure how Italian rice moves from paddy to final preparation, with sustainability verification becoming as critical as culinary performance.
Controlled-atmosphere aging is absorbing capital investment across premium milling operations. This patented technique modifies starch structure over 1-3 year cycles. High-end restaurant suppliers and export-focused packagers are adopting it aggressively. The technology is absorbing market share from conventional drying methods by enabling price premiums that offset facility upgrade costs.
EU Green Deal farm-to-fork targets are tightening pesticide residue thresholds for rice entering institutional food service. Italy's Ministry of Agricultural, Food and Forestry Policies is aligning national surveillance with these benchmarks. Integrated pest management adoption is accelerating in Pavia province, where cooperatives face immediate compliance deadlines for school and hospital supply contracts.
Chef procurement patterns are fragmenting away from single-variety contracts toward blended sourcing strategies. Restaurant groups now specify multiple carnaroli suppliers by harvest year and aging protocol. This behavior is most pronounced in Milan and Turin, where flagship kitchens compete on risotto texture differentiation and origin storytelling.
Italy Rice Market Segmentation
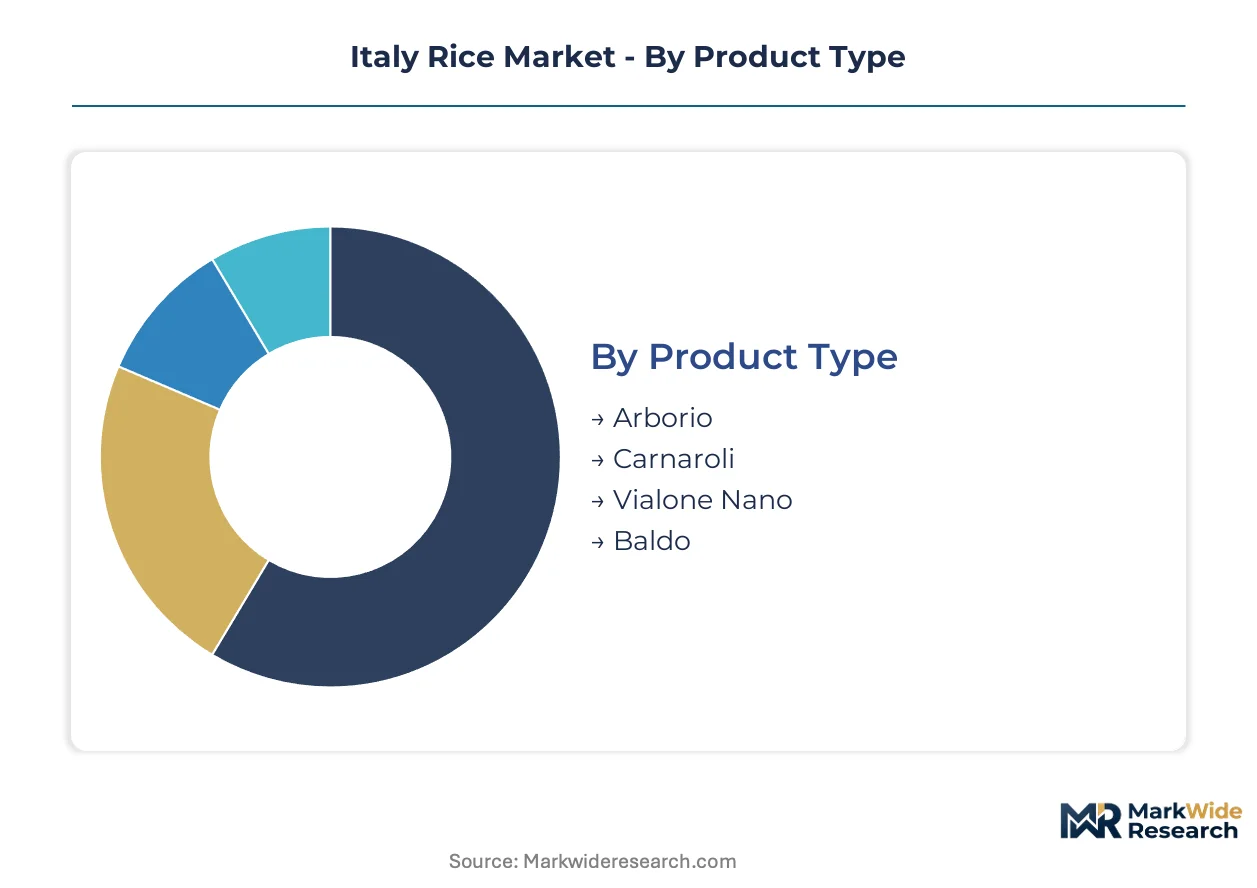
Italian rice procurement patterns diverge sharply across usage contexts, with risotto preparation standards dictating varietal selection while sustainability verification reshapes packaging preferences. Understanding these segment boundaries reveals where margin concentrates versus where volume flows.
Product Type:
Upgrade cycles in restaurant kitchens and evolving home-cooking sophistication are pushing demand toward higher-amylose varieties that tolerate extended cooking without structural collapse.
- Arborio:Medium-grain Oryza sativa with 18-20% amylose content that releases moderate starch during cooking. Supermarket chains across Lombardy and Piedmont stock this as the default risotto rice for home cooks seeking recognizable branding without premium outlay.
- Carnaroli:Higher amylose concentration at 24% creates superior creaminess retention and structural integrity through extended stirring. Northern Italian restaurants in Milan and Turin specify aged carnaroli harvest years for signature preparations, pulling procurement away from standard alternatives.
- Vialone Nano:Shorter, rounder grains from Veneto paddies with faster cooking absorption. Veneto-based food service distributors promote this for seafood risotto applications where quicker preparation cycles matter.
- Baldo:Hybrid variety combining carnaroli creaminess with arborio yield economics. Emerging presence in institutional catering contracts where cost efficiency competes with texture requirements.
Volume placements concentrate in Arborio; the faster expansion belongs to Carnaroli.
End User:
Cost tier differentiation separates commodity procurement from premium positioning, with each end-user category demanding distinct certification and logistics protocols.
- Food Service:Independent restaurants and chain kitchens specify DOP-protected carnaroli by harvest year and aging protocol. Chef-driven procurement in Milan bypasses wholesale tiers for direct mill relationships.
- Retail:Supermarket and online channels prioritize vacuum-packaged arborio for shelf-life extension. E-commerce platforms are unlocking specialty variety distribution previously confined to gourmet shops.
- Exporters:German and Swiss buyers dominate premium carnaroli offtake, with logistics prioritizing controlled-atmosphere containers for aged stock.
- Food Manufacturers:Ready-meal producers and soup manufacturers specify parboiled arborio for processing consistency. Mid-scale milling facilities near Pavia supply this segment on contract volumes.
Margin capture concentrates in Food Service; steepest expansion trajectory belongs to Retail e-commerce channels.
Distribution Channel:
Customer type fragmentation is reconfiguring channel economics, with digital-native buyers demanding transparency that legacy wholesale structures struggle to deliver.
- Supermarkets:Coop and Conad chains dominate arborio volume, leveraging private-label programs to compress branded margins. Shelf-space allocation favors vacuum-packed formats with extended dating.
- Online Retail:Amazon and specialized gourmet platforms are absorbing specialty variety growth, with DOP-protected mills building direct storefronts to capture margin previously lost to intermediaries.
- Wholesale:Traditional food service distributors face disintermediation as restaurant groups consolidate procurement through digital platforms.
- Direct Sales:Agriturismo operations and cooperative mills in Vercelli province sell aged carnaroli to visiting chefs and export buyers, bypassing conventional tiering entirely.
Transaction volume concentrates in Supermarkets; channel share gains most quickly in Online Retail.
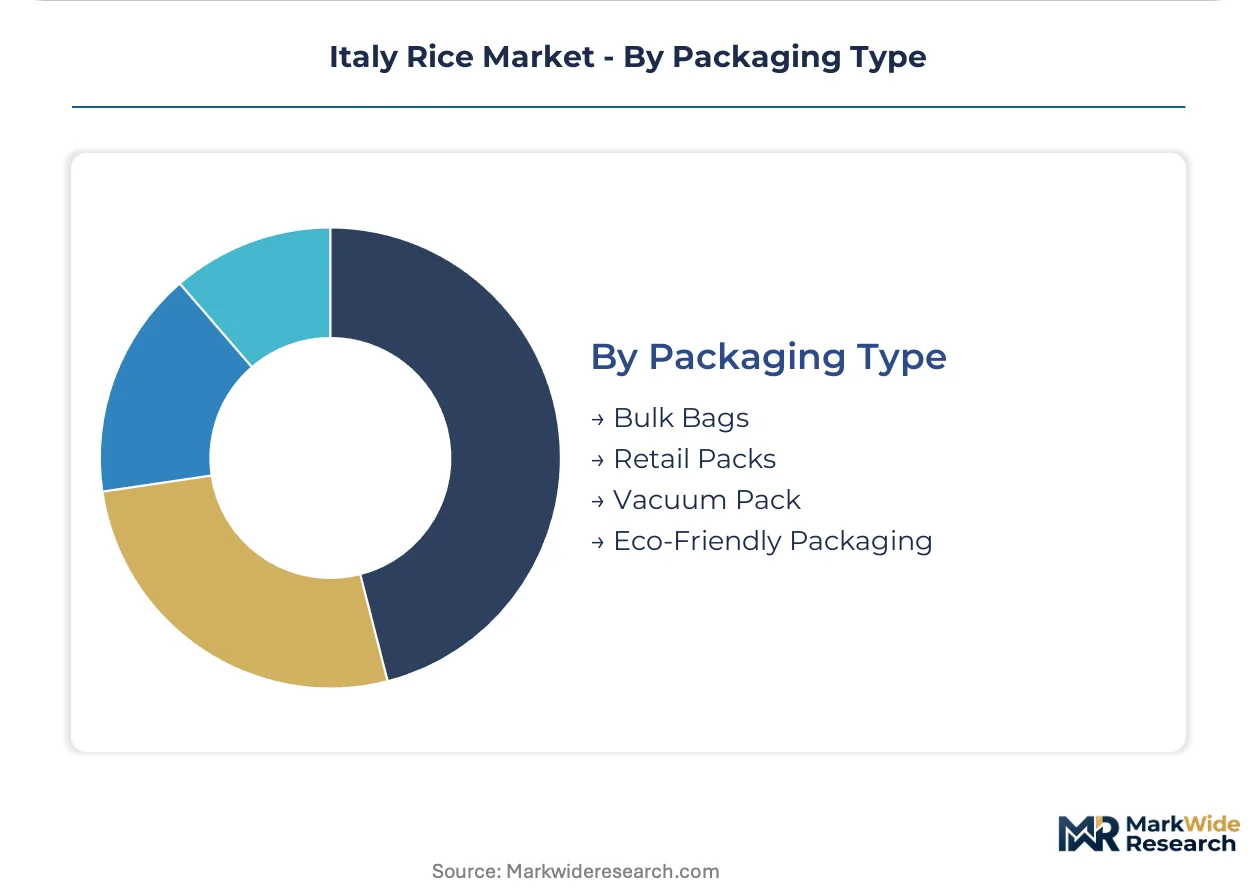
Packaging Type:
Supply concentration around sustainability verification is elevating eco-format premiums while vacuum technology extends distribution reach for perishable specialty varieties.
- Bulk Bags:25kg woven polypropylene dominates food manufacturer and institutional catering procurement. Logistics efficiency favors Po Valley millers with rail siding access.
- Retail Packs:1kg paper and plastic laminates serve supermarket conventional shelving. Conad private-label programs specify minimum recycled content thresholds.
- Vacuum Pack:Multi-layer barrier films extend shelf life from 12 to 24 months for carnaroli and aged varieties. E-commerce fulfillment centers require this format for specialty stock.
- Eco-Friendly Packaging:Compostable films and recycled paper structures command 15-20% shelf price premiums in northern Italian gourmet retail. EU Green Deal farm-to-fork targets are accelerating adoption.
Shipment volume concentrates in Bulk Bags; packaging innovation investment flows fastest toward Eco-Friendly formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian rice production concentrates in the northern plains while consumption spreads nationwide, creating distinct regional specialization patterns across cultivation, milling, and distribution.
Lombardy
Pavia province anchors national carnaroli output through century-old irrigation networks feeding specialized paddies. The region's Ministry of Agricultural, Food and Forestry Policies enforces strict DOP boundaries that restrict premium labeling to designated canal zones. Milan's restaurant density pulls aged carnaroli through direct procurement channels bypassing wholesale intermediaries.
Piedmont
Vercelli province hosts Europe's densest rice milling cluster with cooperatives processing arborio for retail distribution. Aging canal infrastructure demands capital renewal that outstrips cooperative maintenance budgets. The province's public breeding stations supply germplasm improvements for blast resistance across northern cultivation zones.
Veneto
Verona and Rovigo provinces specialize in vialone nano for seafood risotto applications favored by Adriatic coastal restaurants. Regional distributors promote faster-cooking varieties to food service operators seeking preparation efficiency. The Po Delta microclimate supports distinct texture profiles that differentiate Veneto output in export markets.
Emilia-Romagna
Bologna and Ferrara provinces bridge cultivation and processing with mills supplying parboiled arborio to ready-meal manufacturers. The region's food manufacturing density creates stable contract demand for processing-consistent varieties. Rail-linked milling facilities serve industrial buyers across the Po Valley corridor.
Sicily
Caltanissetta and Enna provinces maintain underutilized paddy infrastructure suitable for specialty red and black varieties. Distinct microclimates enable cultivation of antioxidant-rich grains commanding export premiums. Island production remains below capacity due to limited DOP recognition and distribution investment.
Italy Rice Market Competitive Landscape
The competitive structure tilts toward vertically integrated millers with controlled-atmosphere aging capabilities. Tiered concentration separates heritage DOP-protected operators from scale-driven processors serving commodity channels. Three archetypes dominate: patent-holding aging specialists, volume-oriented parboiling facilities, and cooperative mills with agriturismo direct sales. Capacity expansion in vacuum packaging and strategic partnerships with e-commerce platforms represent the dominant competitive moves reshaping procurement relationships.
Among vertically integrated specialists, Riso Gallo exemplifies the mill-to-shelf archetype with sustained retail visibility, while Acquerello occupies a position as the aging-technology anchor in premium restaurant supply. Riso Scotti represents the scale-driven end with one of Europe's largest processing complexes near Pavia. These three entities collectively illustrate how backward integration into cultivation, proprietary processing methods, and channel-specific packaging strategies differentiate positioning across supermarket, food service, and export segments.
| Leading Market Players |
|---|
| Euricom |
| Acquerello |
| Riso Gallo |
| Paolo Grassi |
| Riseria Taverne |
| Riso Scotti |
| Cascina Belvedere |
| Germani Riso |
| Riso Vignola |
| Others |
Supply & Pricing Matrix
Carnaroli-arborio price divergence manifests through DOP certification premiums commanding shelf price multiples against commodity arborio, with EU Green Deal farm-to-fork compliance costs layering onto supply chain configurations through carbon accounting verification requirements. Tiered pricing separates aged carnaroli harvest years from standard milling grades from bulk parboiled supply, each tier tethered to distinct canal-zone provenance and controlled-atmosphere facility access.
Pricing Analysis
Margin tightening in mid-scale milling reflects natural gas price volatility for parboiling operations compressing returns on standard arborio contracts. Three-tier pricing structure across premium aged carnaroli, standard DOP-certified grades, and economy parboiled supply stratifies by amylose content verification and harvest year documentation. Cost-down pressure on commodity arborio accelerates because supermarket private-label programs leverage Conad and Coop volume negotiations. Food manufacturers exhibit highest price sensitivity due to processing-consistent parboiled procurement contracts, while Milan restaurant groups demonstrate lowest sensitivity specifying aged carnaroli by mill and vintage.
Supply Chain Analysis
Reverse-logistics flows for expired vacuum-pack inventory return to cooperative mills for reprocessing into animal feed or industrial starch applications, recapturing value from retail channel spoilage. Supply concentrates in Italy's Po Valley, with germplasm improvement anchored at Vercelli public breeding stations and precision irrigation equipment sourced from Netherlands and Germany. Raw material dependencies include natural gas for drying operations, nitrogen fertilizers from Russian and Qatari suppliers, and multi-layer barrier films from Italian and German converters. Single-source vulnerability sits with Vercelli germplasm stations supplying blast-resistant traits across 70% of carnaroli cultivation. Distribution runs through Pavia rail-linked milling complexes feeding northern Italian supermarket distribution centers and direct-to-restaurant digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-atmosphere aging technology is displacing conventional drying methods across premium milling operations, restructuring capital deployment priorities for heritage DOP-protected cooperatives and scale-driven processors alike.
For Market Incumbents: Deploy backward integration into captive paddy cultivation securing canal-zone DOP acreage against EU CAP greening hectare restrictions. Incumbent millers must accelerate vacuum packaging capacity addition in Lombardy to capture e-commerce channel growth before specialty variety distribution consolidates around Amazon and gourmet platform partnerships. Certification investment in EU carbon-accounting verification represents the critical defensive lever against mid-scale competitors forfeiting premium export positioning.
For New Entrants and Emerging Players: Digital procurement platforms enabling direct mill-to-restaurant relationships offer technology-first entry points bypassing wholesale tier disintermediation. Sicily and Sardinia specialty red and black varieties present the most penetrable white-space geography, with distinct microclimates enabling antioxidant-rich grain premiums absent DOP recognition barriers. Go-to-market positioning through agriturismo direct sales to visiting export buyers and chef networks captures margin lost to conventional channel structures.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated aging-technology specialists with patented controlled-atmosphere capabilities and established DOP-protected canal-zone acreage. Long-term viability over the medium-term projection horizon rests on CAP subsidy continuity and carbon credit stacking feasibility for early-adopter farms with verified measurement infrastructure. Acquisition target archetype combines backward integration into cultivation with proprietary aging protocols and e-commerce channel control. The signal to watch is EU carbon-accounting audit backlog resolution determining which milling operations qualify for continued premium European export market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Aging Facility Investment | Patented starch modification technology enables carnaroli price premiums that offset facility upgrade capital requirements. |
| Vacuum Packaging Capacity Expansion | Extended shelf-life formats unlock Amazon and gourmet platform distribution for specialty varieties previously confined to retail. |
| Direct-to-Restaurant Digital Platform Launch | Bypassing wholesale intermediaries allows DOP-protected mills to capture margin previously lost to food service distributors. |
| Carbon Credit Stacking Verification Program | Dual revenue streams from CAP greening payments and private soil-carbon protocols reward early-adopter farms with measurement infrastructure. |
| Sicily Specialty Variety Cultivation Development | Antioxidant-rich red and black grain production leverages underutilized paddy infrastructure for export premium capture. |
Research Methodology
Independent corroboration across milling cooperative executives, restaurant procurement chefs, and EU agricultural policy specialists underwrites the qualitative findings on CAP subsidy restructuring impacts. Primary interviews with Pavia and Vercelli plant managers, Lombardy supermarket category buyers, and German import distributors combined with secondary validation from EU Common Agricultural Policy implementation documents, Italy Ministry of Agricultural surveillance data, and Po Valley irrigation cooperative records. Bottom-up variety-level volume estimates and top-down regional production aggregates were reconciled through iterative triangulation.
Comparable historical reference periods anchored the projection framework against documented CAP reform implementation cycles and prior energy price volatility episodes. The analytical framework models volume and value across product type segmentation by amylose content grade, end-user differentiation between food service specification and retail procurement, distribution channel fragmentation across digital and conventional tiers, and packaging format evolution toward sustainability verification. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion constraints. Forecast inputs incorporated natural gas price scenario sensitivity for parboiling operations and e-commerce penetration trajectories for specialty variety distribution.
Several conditions sit outside the modeled scope, including extreme weather events affecting Po Valley irrigation reliability, accelerated blast fungus strain emergence overwhelming Vercelli breeding programs, and abrupt CAP subsidy cancellation beyond scheduled reform timelines. Forecasts reflect assumptions on EU carbon-accounting standard implementation pacing and canal infrastructure maintenance investment continuity. Practitioners should monitor EU audit backlog clearance rates, German and Swiss import demand fluctuations, and precision irrigation technology adoption metrics across Lombardy cooperatives for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Guar Complex Market
Grains
Global Flour Market
Grains
Uganda Grains Market
Grains
Grain Dryers Market
Grains
Soy Grits Market
Grains
Spain Rice Market
Grains
North America Rice Market
Grains
Whole-Wheat Flour Market
Grains
South America Rice Market
Grains
Europe Wheat Protein Market
Grains
Wild Rice Market
Grains
United States Maize Market
Grains
Corn Market
Grains
Barley Grass Market
Grains
United States Rice Market
Grains
Grain Augers Market