
 Europe Maize Market | 2026-2036
Europe Maize Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Maize Market Foresight
The EU Green Deal is rebalancing the cost-of-entry calculus for maize growers seeking biofuel certification. Bayer leverages its seed trait portfolio to sustain premium positioning in drought-resistant hybrids. Limagrain Europe anchors its competitive stance through deep geographic dominance in France's maize belt. Syngenta competes on digital farming platforms that optimize nitrogen application rates across variable soils.
Maize, botanically Zea mays, is a C4 cereal grain with kernel moisture content typically ranging from 15% to 25% at harvest, differentiated by endosperm structure into flint, dent, sweet, and pop varieties. Its primary commercial purpose spans animal nutrition, human food processing, and industrial starch extraction. Dent corn leads volume flows into animal feed and ethanol channels where margin pools remain deepest. Sweet corn commands premium pricing through supermarket and online retail distribution, though snack manufacturing applications show the fastest structural expansion. Food processing-grade maize occupies a mature, quality-certified tier with stable offtake from industrial millers.
EMA and EFSA frameworks govern feed safety and genetically modified organism thresholds entering the food chain. The EU Green Deal and F-Gas Regulation jointly shape biofuel eligibility and on-farm emissions accountability, redirecting acreage toward lower-carbon cultivation protocols. REACH compliance adds chemical input constraints that filter market access for non-EU origin grain. Stakeholders must monitor how the EU AI Act and pending digital agriculture standards reshape precision farming data ownership before committing capital to automated harvesting infrastructure.
Market Dynamics
The EU Green Deal's tightening biofuel feedstock criteria is redrawing competitive boundaries for maize growers, forcing rapid recalibration of cultivation protocols and input sourcing strategies across the continent.
Growth Catalysts
- Animal feed expansion:Eastern European livestock operations are scaling dent corn procurement volumes to support herd modernization programs.
- REACH compliance:Stricter chemical input standards are filtering out non-compliant imports and protecting domestic producer margins.
- Starch processing corridor:Poland's industrial cluster is attracting capital-intensive milling investments that anchor regional demand.
Market Restraints
- Input cost volatility:Fertilizer and energy price swings compress margins for rain-fed growers in Romania's plains.
- GMO threshold friction:EFSA's strict traceability requirements create documentation burdens that slow cross-border grain movements.
- Protein meal substitution:Soybean and rapeseed meal alternatives are capturing feed formulation share in poultry and aquaculture channels.
Strategic Opportunities
- Underpenetrated Baltic states:Estonia and Latvia offer acreage expansion potential for farmers adopting precision agriculture tools.
- CSRD-aligned carbon certification:Early adopters of verified low-carbon cultivation protocols will secure premium biofuel contract access.
- Digital platform convergence:Integration of satellite imagery with variable-rate nitrogen application is opening yield optimization services.
Industry Challenges
- Data agronomy skill scarcity:Farm operations lack personnel capable of interpreting AI-driven soil and weather analytics.
- Capex intensity of automation:Autonomous harvesting equipment requires capital commitments that strain mid-scale cooperative balance sheets.
- EU AI Act compliance timeline:Uncertainty around algorithmic decision-making standards is freezing precision farming infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Maize Market |
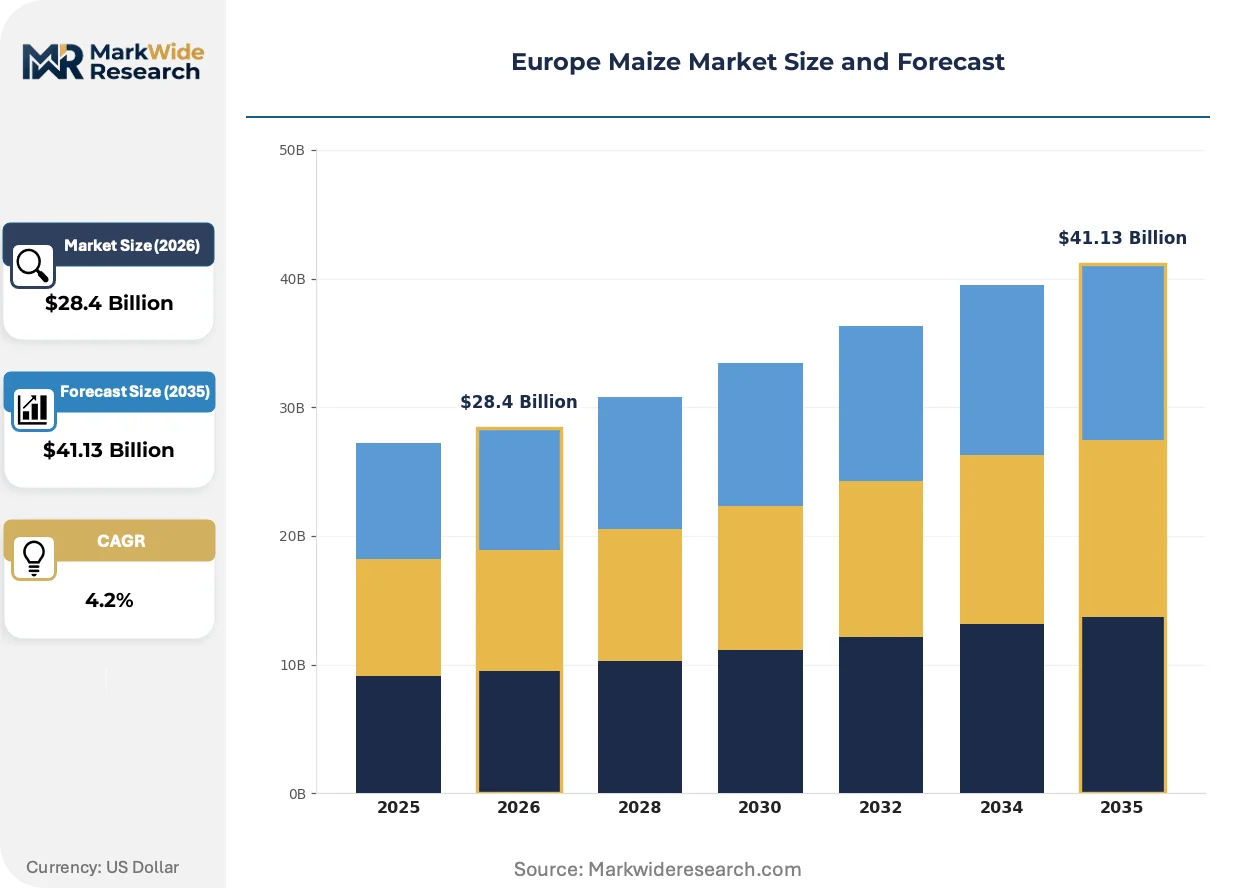
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $41.13 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Corn, Flint Corn, Dent Corn, Pop Corn End User: Animal Feed, Food Industry, Biofuel, Starch Production Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales Application: Food Processing, Industrial Use, Ethanol Production, Snack Manufacturing |
| Companies Covered | France (National Producer), Romania (National Producer), Poland (National Producer), Germany (National Producer), Spain (National Producer), BASF, Bayer, Limagrain Europe, Syngenta, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Maize Market Shifts & Advancements
Digital agriculture platforms and sustainability verification systems are converging to reshape how European maize growers manage input decisions and access premium market tiers.
Variable-rate nitrogen application technology is decentralizing agronomic decision-making from centralized extension services to individual farm managers. Medium-scale operations in France's maize belt are adopting these platforms fastest, drawn by immediate input cost reductions. This shift is decentralizing knowledge advantages that previously concentrated with large cooperative agronomists.
The EU AI Act's risk classification framework for agricultural algorithms is forcing platform developers to restructure data governance architectures. Developers must now document training data provenance and decision audit trails before commercial deployment. France's digital farming startups are responding by establishing EU-hosted data centers to satisfy operational resilience requirements.
Carbon certification is becoming a mandatory procurement filter for biofuel processors seeking EU Green Deal compliance. Large ethanol refiners in Hungary and Slovakia are now requiring documented cultivation emissions data from contracted growers. This behavioral shift is most visible in Romania, where grain traders are building in-house verification capabilities to maintain buyer relationships.
Europe Maize Market Segmentation
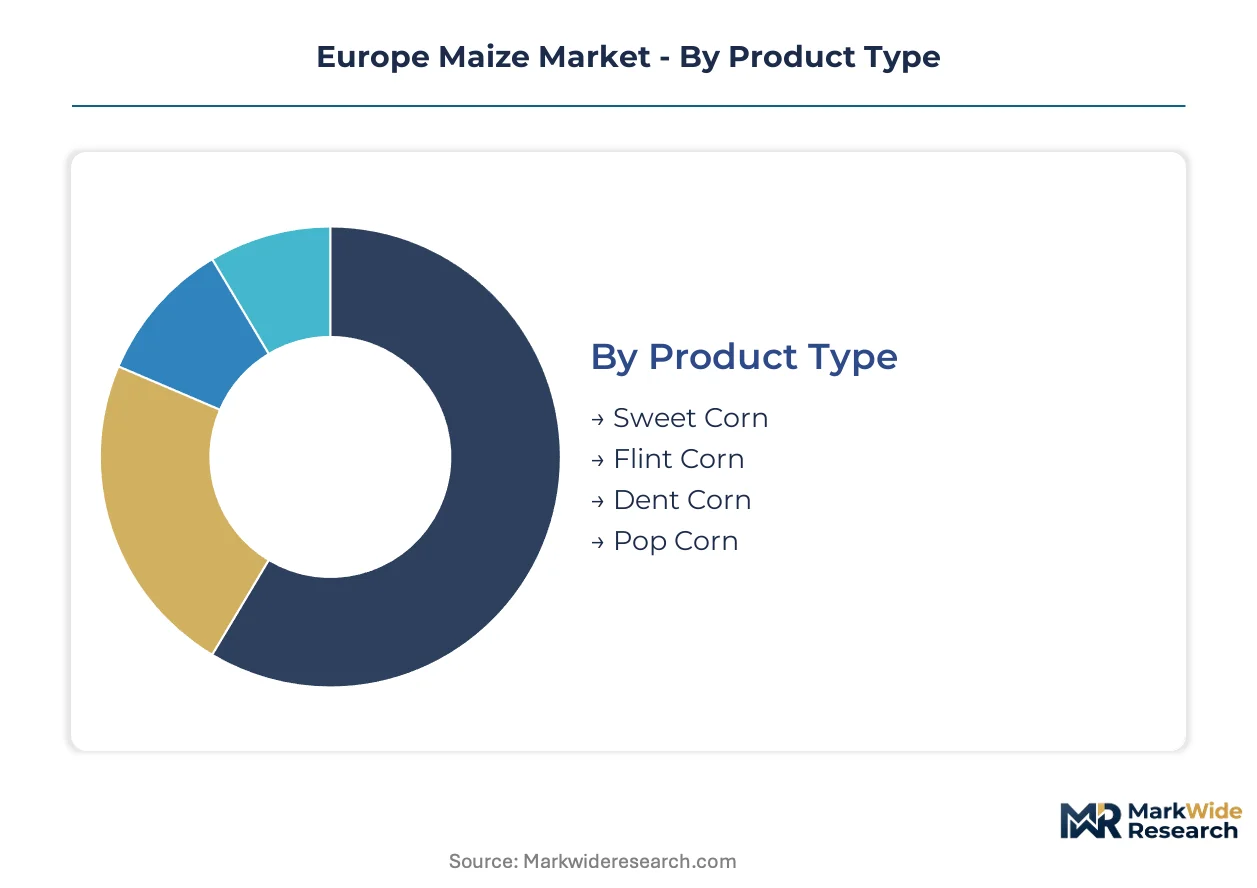
Maize segmentation across Europe reflects divergent margin structures and regulatory exposure. Each category channels capital toward distinct value pools, from commodity feed flows to premium biofuel certification tiers.
Product Type:
Standardization dominates commodity grades while specialty varieties command cultivation premiums and identity-preserved handling.
- Dent Corn:Starch-heavy endosperm structure delivers high fermentable carbohydrate content for ethanol conversion and energy-dense animal rations. Romanian plains growers and Polish feed compounders anchor continental volume flows, though EFSA's GMO traceability requirements add documentation friction to cross-border movements.
- Sweet Corn:Elevated sugar content at harvest requires rapid cold-chain transit to preserve sensory quality. Supermarket retail and snack manufacturing channels in France and Germany absorb premium pricing, with online grocery platforms expanding fastest among direct-to-consumer routes.
- Flint Corn:Hard endosperm suits traditional food milling and specialty polenta production. Italian and Spanish heritage processors maintain contracted acreage for Protected Designation of Origin supply chains.
- Pop Corn:Hard, dense kernels with minimal moisture expand under thermal stress for snack applications. Benelux packaging specialists and German cinema distributors drive specialized procurement.
Leading the category by volume: Dent Corn. Expanding most quickly: Sweet Corn through retail channel diversification.
End User:
Customer concentration varies from fragmented livestock operations to capital-intensive industrial processors with long-term contracting power.
- Animal Feed:Eastern European pork and poultry integrators scale dent corn procurement to support herd modernization. The EU Green Deal's sustainability criteria are tightening eligibility standards for feedstock entering biofuel channels, redirecting some commodity flows.
- Starch Production:Poland's industrial corridor attracts milling investments that anchor regional demand. Wet-milling facilities in Hungary and Slovakia require consistent moisture specifications and documented cultivation emissions data.
- Food Industry:Millers and processors source identity-preserved flint and specialty varieties for human consumption channels. REACH compliance filters non-EU origin grain from premium formulations.
- Biofuel:Ethanol refiners require low-carbon certification under EU Green Deal protocols. Hungarian and Slovak processors now mandate verified cultivation emissions documentation from contracted growers.
Animal Feed commands the greatest tonnage. Starch Production shows the steepest capital inflow trajectory.
Distribution Channel:
Channel selection determines margin capture and traceability burden for growers seeking premium market access.
- Wholesale:Grain traders and cooperative elevators aggregate commodity flows from Romania's plains and France's maize belt. Bulk handling infrastructure minimizes per-unit logistics costs for undifferentiated dent corn.
- Direct Sales:Large-scale operations contract directly with starch processors and ethanol refiners, bypassing intermediary margins. Carbon certification requirements favor this channel for biofuel-bound production.
- Supermarkets:Sweet corn and value-added fresh products reach consumers through controlled-atmosphere packaging and rapid replenishment systems. German and French retail chains dominate procurement volume.
- Online Retail:Direct-to-consumer platforms and B2B procurement portals expand specialty and heritage variety access. Baltic states show fastest platform adoption among mid-scale farm operations.
Wholesale handles the greatest tonnage. Online Retail gains share fastest among emerging customer segments.
Application:
Application segmentation separates mature, quality-certified tiers from emerging demand channels with diverging technical specifications.
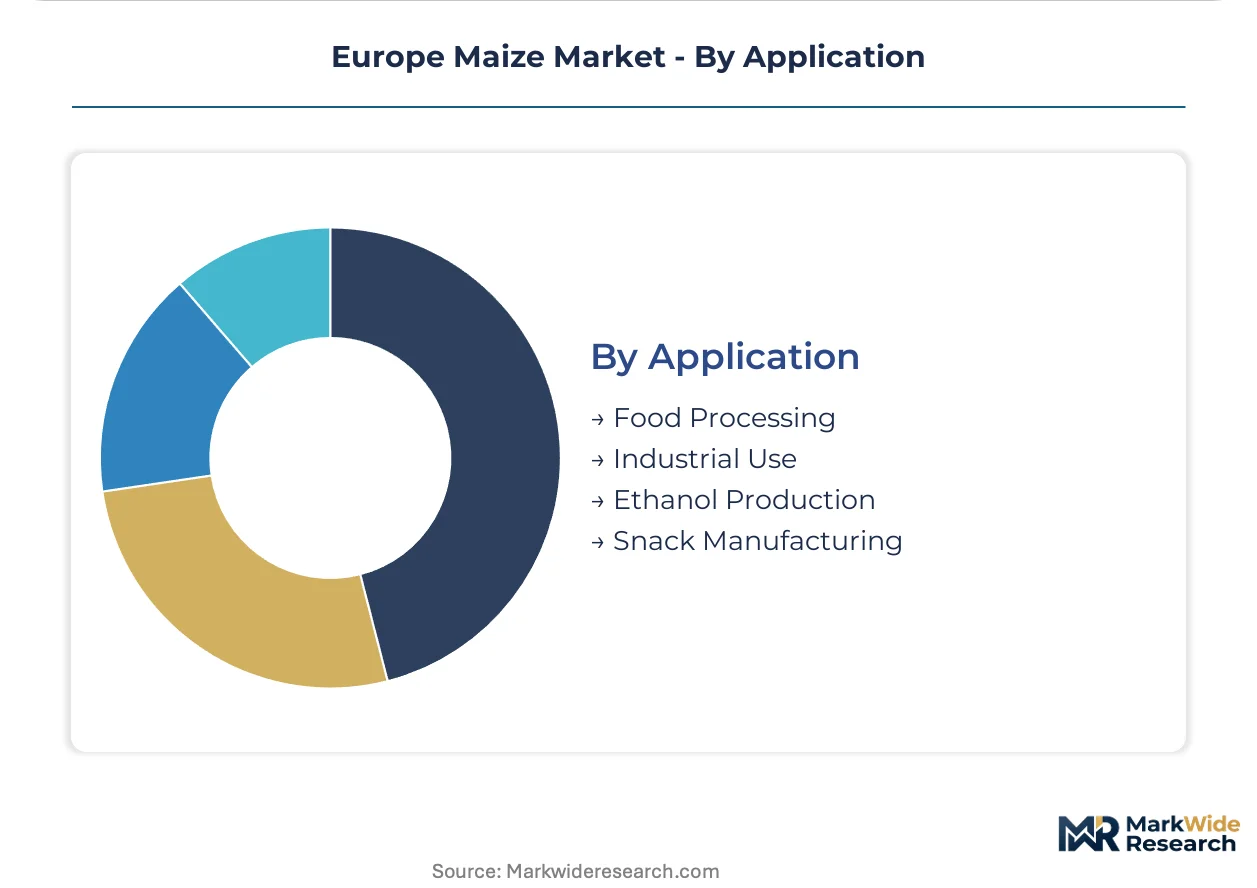
- Food Processing:Industrial millers demand consistent kernel size, moisture content, and mycotoxin compliance under EFSA frameworks. Mature demand with stable offtake from pasta, brewing, and breakfast cereal manufacturers.
- Ethanol Production:Fermentation efficiency depends on starch accessibility and low fiber content. EU Green Deal criteria redirect acreage toward lower-carbon cultivation protocols with verified input documentation.
- Snack Manufacturing:Popcorn and extruded products require specific expansion ratios and hull integrity. Fastest structural expansion among food applications, driven by convenience consumption trends.
- Industrial Use:Bioplastics, adhesives, and paper coating applications extract modified starches and derivatives. Capital-intensive processing clusters in Germany and the Netherlands concentrate demand.
Food Processing retains the largest volume base. Snack Manufacturing climbs the fastest among growth trajectories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's Special Economic Zones for starch processing concentrate capital inflows from multinational millers seeking EU Green Deal-compliant feedstock sourcing.
Romania
Eastern European livestock integrators scale dent corn procurement to support pork and poultry herd modernization programs. EFSA's GMO traceability requirements add documentation friction to cross-border grain movements. The fertile plains surrounding Timișoara and Constanța anchor continental volume flows for animal feed channels.
Poland
Industrial starch processors attract capital-intensive wet-milling investments that anchor regional demand for high-fermentable carbohydrate feedstock. REACH compliance filters non-EU origin grain from premium biofuel-bound formulations. The corridor linking Poznań to Łódź concentrates milling capacity expansion under EU Green Deal sustainability protocols.
France
Supermarket retail and snack manufacturing channels absorb premium sweet corn pricing through controlled-atmosphere distribution networks. The EU AI Act's risk classification framework forces platform developers to restructure data governance architectures for precision farming tools. The maize belt surrounding Toulouse and Bordeaux leads adoption of variable-rate nitrogen application technology.
Hungary
Ethanol refiners mandate verified cultivation emissions documentation from contracted growers seeking biofuel certification access. F-Gas Regulation shapes on-farm emissions accountability for acreage under lower-carbon cultivation protocols. The industrial cluster near Szeged concentrates capital from processors requiring documented input sourcing for EU Green Deal eligibility.
Germany
Popcorn and extruded snack manufacturers require specific expansion ratios and hull integrity for convenience consumption channels. CSRD-aligned carbon certification is becoming a mandatory procurement filter for biofuel processors seeking premium contract access. Bavarian packaging specialists and cinema distributors drive specialized procurement for heritage variety supply chains.
Europe Maize Market Competitive Landscape
French producers anchor one tier; German and Swiss specialists hold differentiated positions in seed trait development and digital agriculture platforms. The vendor base concentrates around integrated agrochemical-seed conglomerates with deep patent portfolios in drought-resistant hybrids and nitrogen-use efficiency. Three archetypes dominate: trait-integrated seed developers, precision agriculture platform operators, and geographic-specialist cooperatives with localized germplasm adaptation. Consolidation pressure favors M&A activity between regional seed houses and multinational input suppliers, while capacity expansion concentrates in Poland's starch processing corridor.
Within the trait-integrated tier, Bayer and Syngenta exemplify archetypes combining germplasm development with digital farming infrastructure. Limagrain Europe occupies a position as a geographic-specialist cooperative with deep roots in France's maize belt. BASF sits within the input-integrated segment, representing chemical-seed convergence strategies that dominate commercial channel access across Eastern European feed markets.
| Leading Market Players |
|---|
| France (National Producer) |
| Romania (National Producer) |
| Poland (National Producer) |
| Germany (National Producer) |
| Spain (National Producer) |
| BASF |
| Bayer |
| Limagrain Europe |
| Syngenta |
| Others |
Supply & Pricing Matrix
The EU Green Deal's carbon certification mandate gates qualified supply for biofuel-bound maize while erecting premium-tier pricing access barriers for compliant growers. This environmental framework redirects acreage toward lower-carbon cultivation protocols that processors now mandate, compressing margins for non-certified producers and concentrating pricing power among verified supply pools.
Pricing Analysis
Short lead-time premiums reward growers delivering identity-preserved varieties to starch processors and ethanol refiners with documented cultivation emissions data. Contract-based long-term offtake dominates biofuel channels where EU Green Deal compliance creates tiered pricing across certified, transitional, and conventional supply tiers. Price differentiation hinges on carbon certification grade and volume scale, with animal feed compounders showing highest price sensitivity against ethanol refiners absorbing premiums for verified low-carbon feedstock. Cost compression in conventional dent corn channels is intensifying as Romanian plains growers compete for undifferentiated feed volumes.
Supply Chain Analysis
River freight and rail logistics costs from Romania's Timișoara plains to Polish milling corridors shape landed cost competitiveness across the continent. Supply concentrates in Romania, Poland, and France, with raw material dependencies on nitrogen fertilizers, certified seed stock, and fuel inputs tethered to volatile energy markets. Single-source vulnerability runs through Black Sea export routes subject to geopolitical disruption. Distribution runs through cooperative elevators and grain traders aggregating commodity flows before channeling into direct sales for carbon-certified biofuel contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Maize Market operates as a cost-of-compliance story where REACH and EU Green Deal standards create barrier-to-entry moats protecting domestic producers with verified cultivation protocols.
For Market Incumbents: Anticipate protein meal substitution threats from soybean and rapeseed alternatives by deepening germplasm investment in nitrogen-use efficiency traits. Backward integration into precision agriculture platform development defends margin position against digital-native entrants. Prioritize CSRD-aligned carbon certification infrastructure to secure long-term biofuel contracting relationships with Hungarian and Slovak ethanol refiners. For New Entrants and Emerging Players: Mid-scale Baltic state farm operations represent an underserved buyer archetype seeking yield optimization services without cooperative dependency. Estonia and Latvia offer acreage expansion potential for precision agriculture tool adoption with limited incumbent platform saturation. A go-to-market angle anchored in EU AI Act-compliant data governance architectures differentiates against legacy providers restructuring compliance frameworks. For Investors and Strategic Acquirers: Consolidation announcements between regional seed houses and multinational input suppliers are the leading indicator that trait-integrated platform strategies are capturing competitive advantage. Long-term viability favors geographic-specialist cooperatives with localized germplasm adaptation capabilities and established biofuel processor relationships. Target acquisition profiles should emphasize verified low-carbon cultivation infrastructure and direct sales channel penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Certification Infrastructure Buildout | EU Green Deal compliance secures premium biofuel contract access for Romanian and Polish growers. |
| Precision Agriculture Platform Integration | Variable-rate nitrogen application tools decentralize agronomic advantages from large cooperatives to individual farm managers. |
| Backward Integration into Seed Trait Development | Drought-resistant hybrid portfolios protect margin pools in rain-fed Eastern European production zones. |
| Direct Sales Channel Expansion | Bypassing grain traders captures carbon certification premiums for biofuel-bound production in Hungary and Slovakia. |
| Geographic Expansion into Baltic States | Estonia and Latvia offer underpenetrated acreage for farmers adopting satellite-guided input optimization services. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with grain traders, starch processing procurement leads, cooperative agronomists, and biofuel refinery sustainability officers. EFSA guidance documents, EU Green Deal implementation texts, and REACH compliance databases provided regulatory boundary conditions. Bottom-up acreage and yield estimates from national agricultural statistics offices triangulated against top-down demand projections from feed compounder and ethanol industry associations.
Data-stream reconciliation across production surveys, trade flows, and processor capacity utilization informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user industry, distribution channel, and application, with additional granularity on carbon certification tier and geographic production cluster. CAGRs were derived from trend extrapolation of input cost trajectories, regulatory implementation timelines, and technology adoption curves for precision agriculture platforms.
Revisions become necessary when EFSA modifies GMO traceability thresholds, when EU AI Act algorithmic standards crystallize, or when energy price volatility disrupts fertilizer input costs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
White Beans Market
Grains
South America Wheat Market
Grains
Europe Wheat Protein Market
Grains
Global Oats Market
Grains
Rye Market
Grains
Asia-Pacific Wheat Market
Grains
Rolled Oats Market
Grains
Low Fat Rice Market
Grains
Tunisia Grain Market
Grains
Europe Wheat Market
Grains
Grain Storage Systems Market
Grains
Cameroon Grains Market
Grains
Mesquite Flour Market
Grains
Canada Pulses Market
Grains
Uganda Grains Market
Grains
United States Maize Market