
 South America Rice Market | 2026-2036
South America Rice Market Size, Share, and Industry Trends Forecast 2026-2036
South America Rice Market Analytics
Brazil's MAPA credit restructuring is consolidating smallholder access to mechanized planting equipment. Camil Alimentos leverages vertical integration from milling to branded retail across Brazilian urban centers. SLC Agrícola sustains large-scale mechanized production across its Cerrado and Pampa operations. Adecoagro anchors premium export-grade supply chains targeting Mercosur trade corridors.
Rice comprises the starchy endosperm of Oryza sativa grains, typically milled to remove hull and bran layers, with polished white rice containing 75-80% amylopectin starch by dry weight and serving as a primary caloric staple for over half of South America's population. Brown rice retains the nutrient-dense bran layer, commanding price premiums in Brazilian health-food retail channels where amylose content above 20% signals slower glycemic release. White rice dominates supermarket and wholesale throughput across Argentina and Uruguay, while jasmine and specialty aromatic varieties concentrate in personal retailer networks serving Brazilian Northeast urban markets.
ANVISA in Brazil and the country's national agricultural regulator enforce pesticide residue thresholds and grain moisture standards that determine mill eligibility for export certification. Uruguay's LATU laboratory protocols and Argentina's SENASA phytosanitary inspections create divergent compliance burdens for cross-border traders. Stakeholders must monitor how Mercosur harmonization negotiations reshape sanitary equivalence agreements before committing to transnational milling investments.
Market Dynamics
MAPA's agricultural credit restructuring is consolidating farm-level financing access across Brazil's irrigated paddy belts, compressing planting timelines and mechanizing smallholder operations that previously relied on manual transplanting cycles.
Growth Catalysts
- ANVISA residue protocols:Brazil's national health surveillance agency enforces pesticide thresholds that certify export-grade milling eligibility, pulling premium long-grain volumes into formal supply chains.
- Food service channel absorption:Brazilian urban restaurant networks are absorbing larger volumes of jasmine and specialty aromatic varieties, creating dedicated procurement lanes separate from commodity wholesale.
- Irrigated paddy concentration:Rio Grande do Sul's gravity-fed irrigation systems anchor regional output, stabilizing yield consistency against rainfall volatility that affects dryland cultivation elsewhere.
Market Restraints
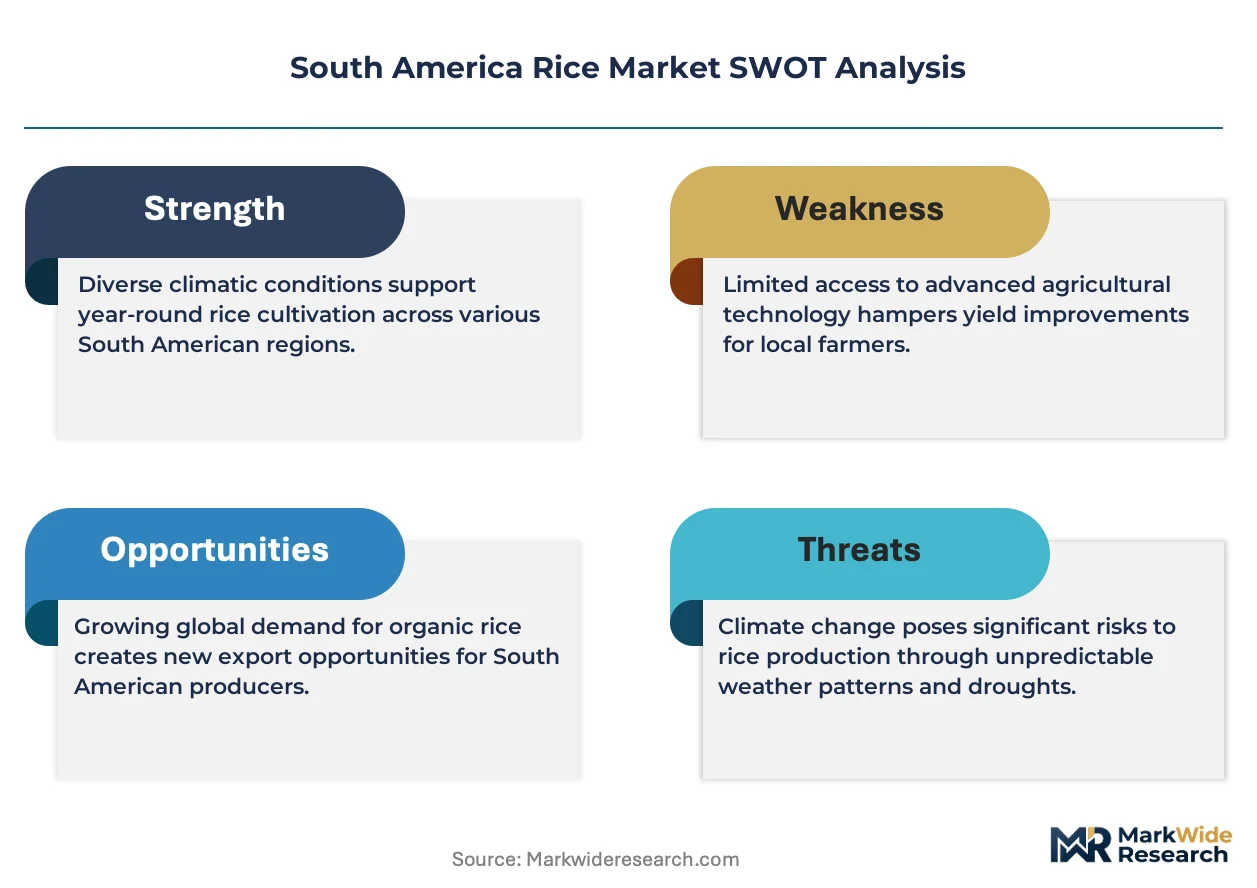
- Input cost volatility:Fertilizer and diesel price swings compress margins for mechanized operators in Brazil's Cerrado expansion zones.
- Cross-border regulatory friction:Uruguay's LATU laboratory protocols and Argentina's SENASA phytosanitary inspections create divergent compliance burdens for Mercosur traders.
- Substitution pressure:Cassava and imported wheat flour displace rice in Brazilian Northeast household budgets during price spikes.
Strategic Opportunities
- Underpenetrated Amazon corridor:Para and Amazonas states lack milling infrastructure, creating captive supply opportunities for barge-linked processing investments.
- Health-food retail channel:Brown rice with elevated amylose content commands price premiums in Brazilian supermarket health aisles.
- Mercosur harmonization tailwind:Pending sanitary equivalence negotiations promise streamlined cross-border certification for integrated milling operations.
Industry Challenges
- Certification timeline compression:ANVISA moisture and residue testing backlogs delay export clearance during peak harvest windows.
- Mechanized planting skill scarcity:GPS-guided transplanting and precision irrigation management outpace trained operator availability in Rio Grande do Sul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Rice Market |
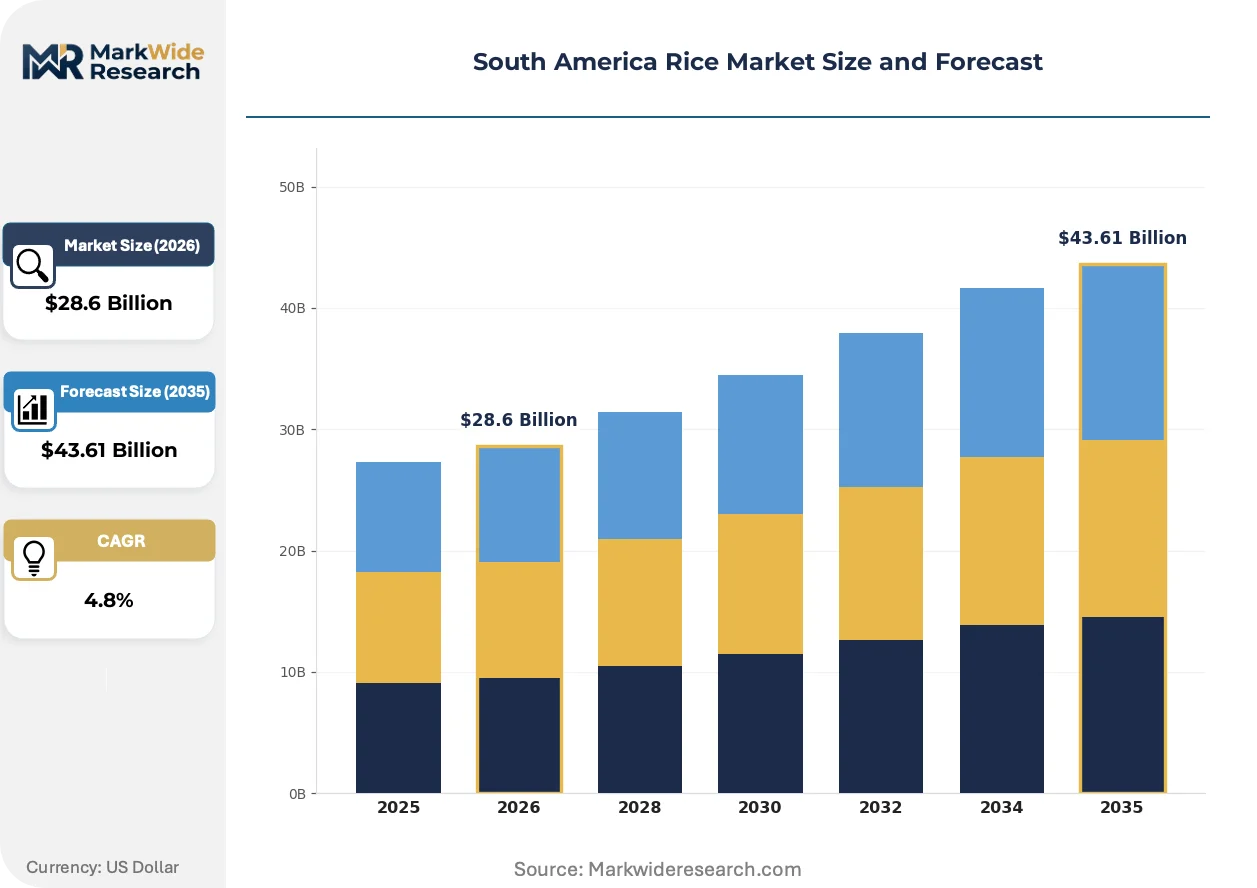
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Rice, Brown Rice, Sticky Rice, Jasmine Rice Distribution Channel: Supermarkets, Online Retail, Wholesale, Personal Retailers End Use Industry: Food Service, Household, Industrial, Export Packaging Type: Bulk Bags, Retail Packs, Sachets, Cans |
| Companies Covered | Camil Alimentos, SLC Agrícola, Adecoagro, Molinos Río de la Plata, SAMAN, Alicorp, Cooperativa Central de Productores de Arroz de Uruguay (CAPRU), Cooperativa de Arroceros de San Luis (Argentina), Cooperativa de Arroceros del Litoral (Paraguay), Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Rice Market Evolving Landscape
Digital traceability platforms and precision irrigation hardware are compressing the gap between farmgate and mill certification, while regulatory harmonization efforts reshape cross-border trade architecture across the continent.
Variable-rate irrigation systems equipped with soil-moisture sensors and automated gate controls are unifying water application with real-time yield mapping. Large-scale operators across Brazil's Pampa lowlands are deploying these systems at scale, replacing flood-irrigation schedules with precision delivery. This technology is unifying agronomic data streams with mill procurement systems, enabling pre-harvest quality forecasting that compresses price negotiation cycles.
ANVISA's updated maximum residue limits for glyphosate and carbofuran are forcing formulation switches across Brazilian paddy belts. The industrial consequence is a wholesale shift toward integrated pest management contracts linking chemical suppliers with extension services. Rio Grande do Sul's irrigated cooperatives are most affected, responding by consolidating spraying records into blockchain-anchored compliance ledgers for export certification.
Urban Brazilian consumers are rotating toward packaged branded rice over bulk wholesale purchases, disrupting traditional open-market trading at São Paulo's CEAGESP terminal. Supermarket chains are capturing this shift through private-label premium lines that disintermediate regional wholesalers. This pattern concentrates most visibly in São Paulo and Belo Horizonte metropolitan procurement, where shelf-ready packaging now dominates household purchase decisions.
South America Rice Market Segmentation
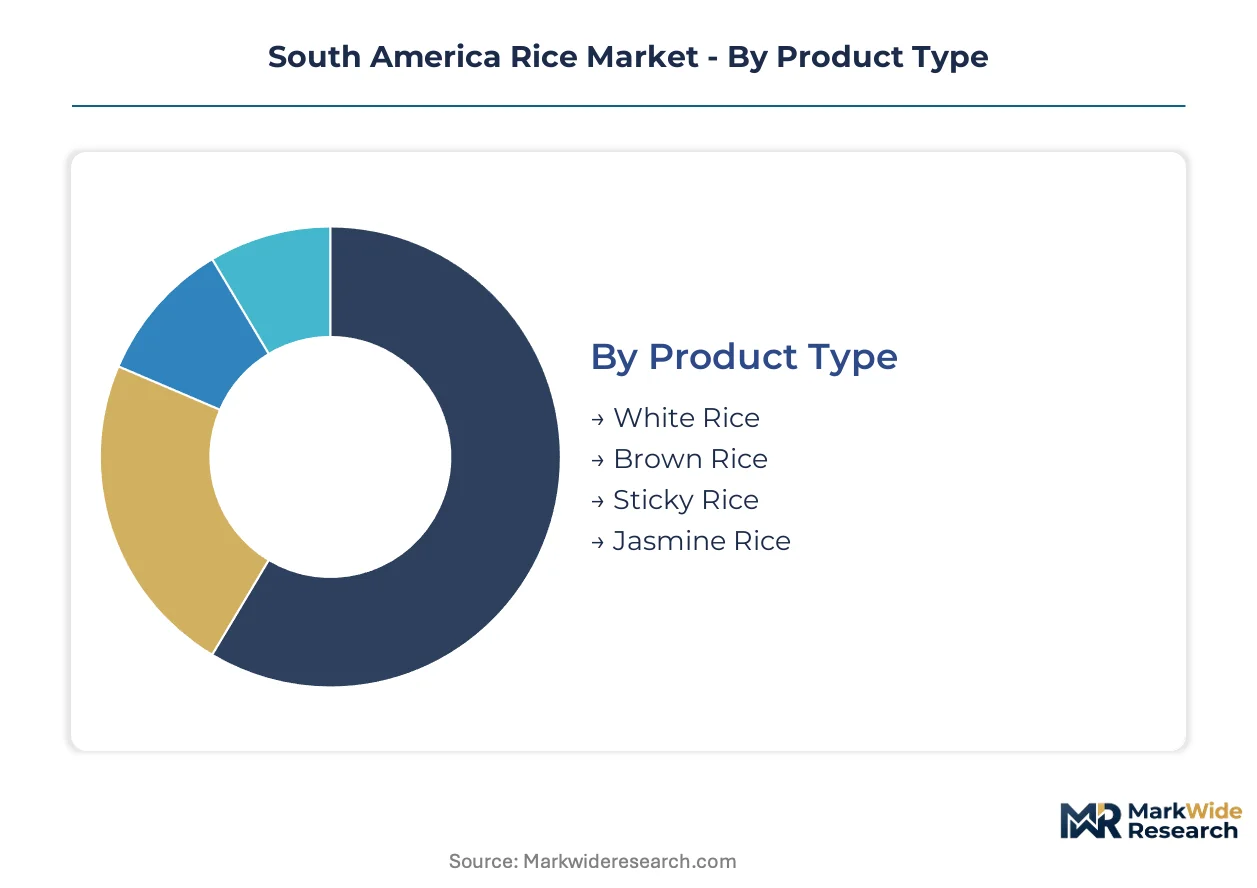
Product differentiation across South American rice markets follows distinct consumption patterns and supply chain configurations. Each segmentation dimension reveals divergent margin structures and procurement behaviors that shape competitive positioning.
Product Type:
Volume throughput concentrates in commodity grades while premium varieties capture disproportionate value per kilogram.
- White Rice:Polished grains with hull and bran removed contain 75-80% amylopectin starch by dry weight. Brazilian supermarket chains and wholesale terminals in São Paulo absorb the largest volumes, driven by household budget sensitivity in urban centers. ANVISA moisture standards determine mill eligibility for formal channel distribution.
- Brown Rice:Nutrient-dense bran layer retention elevates amylose content above 20%, signaling slower glycemic release. Brazilian health-food retail channels command price premiums, with demand concentrating in São Paulo and Belo Horizonte metropolitan health aisles.
- Sticky Rice:High-amylopectin glutinous varieties serve specialized ethnic food service applications.
- Jasmine Rice:Aromatic long-grain varieties flow through dedicated procurement lanes separate from commodity wholesale.
Mature deployment sits with White Rice. Newer deployment is concentrated in Brown Rice.
Distribution Channel:
Channel selection determines margin capture and brand control intensity for millers and traders.
- Supermarkets:Shelf-ready packaging and private-label premium lines now dominate household purchase decisions. São Paulo and Belo Horizonte metropolitan procurement shows the strongest shift from bulk wholesale to packaged branded rice.
- Online Retail:Digital platforms compress delivery cycles for urban consumers seeking convenience and subscription replenishment.
- Wholesale:Open-market trading at terminals like São Paulo's CEAGESP faces disintermediation pressure from direct supermarket procurement.
- Personal Retailers:Specialty aromatic varieties concentrate in neighborhood networks serving Brazilian Northeast urban markets.
Traditional throughput dominates wholesale. Digital penetration is expanding fastest through supermarket e-commerce integration.
End Use Industry:
Application requirements split between caloric staple provision and specialized ingredient functionality.
- Food Service:Brazilian urban restaurant networks absorb larger volumes of jasmine and specialty aromatic varieties, creating procurement specifications distinct from commodity grades. Rio Grande do Sul's irrigated cooperatives supply formal channel certification.
- Household:Primary caloric staple for over half of South America's population, with substitution pressure from cassava during price spikes.
- Industrial:Processed food manufacturers require consistent amylose specifications for ready-meal and snack applications.
- Export:Mercosur trade corridors demand compliance with divergent phytosanitary protocols across Uruguay's LATU and Argentina's SENASA.
Household consumption anchors volume. Export certification is climbing fastest as Mercosur harmonization advances.
Packaging Type:
Packaging economics reflect channel destination and consumer convenience expectations.
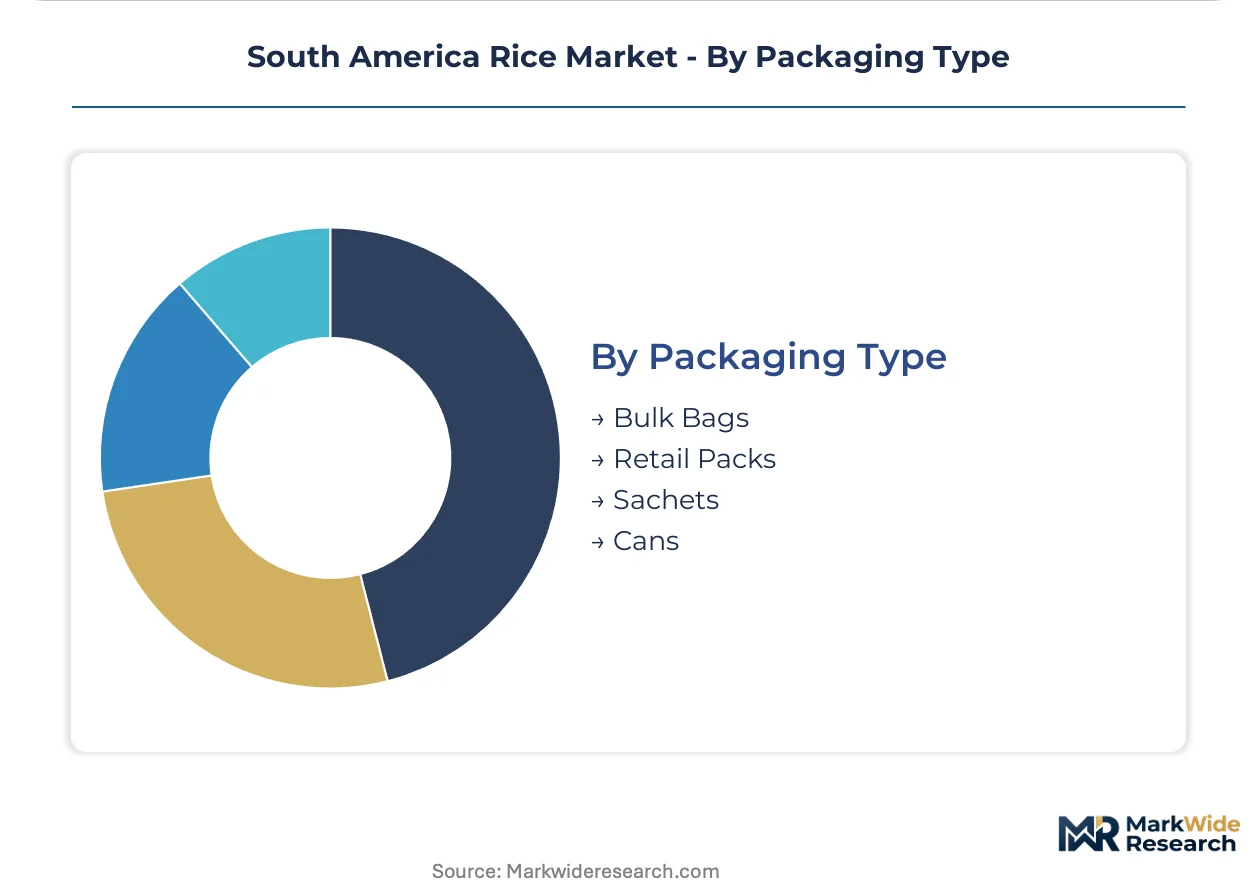
- Bulk Bags:50-kilogram woven polypropylene dominates wholesale terminal throughput and food service procurement.
- Retail Packs:One to five-kilogram laminated bags with branding and nutritional labeling capture supermarket shelf space.
- Sachets:Single-serve portions target institutional feeding programs and convenience-oriented urban households.
- Cans:Aseptic packaging extends shelf life for emergency stockpiling and remote distribution logistics.
Conventional bulk dominates commercial throughput. Value-added formats are gaining share fastest through retail channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Matopiba's agricultural development zone in Brazil's Cerrado biome is channeling credit and infrastructure toward mechanized paddy expansion, consolidating South American production gravity within federal incentive corridors.
Brazil
MAPA's agricultural credit restructuring is compressing planting timelines across Rio Grande do Sul's irrigated belts, where gravity-fed systems stabilize yields against rainfall volatility. ANVISA residue protocols certify export-grade milling eligibility, pulling premium long-grain volumes into formal supply chains. São Paulo and Belo Horizonte metropolitan procurement is shifting from bulk wholesale to packaged branded rice through supermarket private-label lines.
Argentina
SENASA phytosanitary inspections create compliance burdens for cross-border traders, yet Mercosur harmonization negotiations promise streamlined certification for integrated milling operations. The country's national agricultural credit programs support mechanized planting in Entre Ríos province. Buenos Aires anchors industrial processing capacity serving both domestic consumption and export-grade supply chains targeting Mercosur corridors.
Uruguay
LATU laboratory protocols enforce divergent pesticide residue thresholds that complicate regional trade integration. The country's national rice cooperative structure concentrates milling infrastructure in Treinta y Tres and Río Branco departments. Export certification is climbing fastest as sanitary equivalence negotiations advance with Brazilian counterparts.
Paraguay
Cooperativa de Arroceros del Litoral channels smallholder production through centralized milling infrastructure in the Alto Paraná region. The country's national agricultural development agency supports irrigation expansion along the Paraná River corridor. Limited domestic processing capacity creates captive supply opportunities for cross-border traders accessing Brazilian and Argentine markets.
Peru
Lambayeque and La Libertad departments anchor northern coastal production, where gravity-fed irrigation systems serve both domestic consumption and limited export volumes. The country's national agricultural innovation institute promotes variety development for high-altitude cultivation. Lima's wholesale terminals concentrate distribution for urban restaurant networks absorbing specialty aromatic varieties.
South America Rice Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South American rice markets, creating a tiered structure where scale-driven operators coexist with cooperative federations. Large-scale mechanized producers leverage vertical integration from milling to branded retail, while regional cooperatives anchor export-grade supply chains through collective bargaining power. Three archetypes dominate: integrated agribusiness conglomerates with multi-crop portfolios, cooperative federations pooling smallholder output, and branded consumer goods specialists controlling supermarket shelf space. Competitive intensity centers on backward integration into seed development and forward integration into direct-to-retail distribution.
Within the cooperative federation tier, Cooperativa Central de Productores de Arroz de Uruguay and Cooperativa de Arroceros de San Luis exemplify collective structures that aggregate smallholder production for export certification. Among integrated agribusiness operators, Adecoagro occupies a position representing large-scale mechanized production across multiple South American territories. Camil Alimentos anchors the branded consumer goods archetype, exemplifying vertical integration from milling operations through retail distribution networks. These three entities represent distinct strategic postures without implying specific market shares or operational metrics.
| Leading Market Players |
|---|
| Camil Alimentos |
| SLC Agrícola |
| Adecoagro |
| Molinos Río de la Plata |
| SAMAN |
| Alicorp |
| Cooperativa Central de Productores de Arroz de Uruguay (CAPRU) |
| Cooperativa de Arroceros de San Luis (Argentina) |
| Cooperativa de Arroceros del Litoral (Paraguay) |
| Others |
Value Network & Pricing Analysis
GPS-guided transplanting operator scarcity in Rio Grande do Sul widens pricing spreads between mechanized precision-grade supply and manual-cultivation commodity tiers, compressing margins at the lower end while certified export-grade volumes capture premium realizations.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium capture while spot inventory liquidates at discounts. Three-tier pricing structure across premium, standard, and economy levels segments by ANVISA certification status and amylose content specifications. Price differentiation hinges on brand equity in São Paulo supermarket chains versus anonymous bulk terminal trading. Cost compression in standard-grade mechanized production is intensifying because diesel and fertilizer input volatility outpaces contract price adjustments. Household consumers in Brazil's Northeast exhibit highest price sensitivity, rotating toward cassava substitutes during spikes, while food service procurement in Belo Horizonte shows lowest elasticity for jasmine and aromatic varieties.
Supply Chain Analysis
Single-source vulnerability sits with Rio Grande do Sul's gravity-fed irrigation infrastructure, where cooperative concentration dominates export-grade milling capacity. Geographic supply concentration centers on Brazil, Uruguay, and Argentina as the three primary origin points for Mercosur trade flows. Raw material dependencies rest on glyphosate and carbofuran formulations, urea fertilizer, and diesel fuel for mechanized operations. Supply chain risk manifests as regulatory restriction through divergent LATU and SENASA phytosanitary protocols that fragment cross-border shipment eligibility. Distribution runs through São Paulo's CEAGESP terminal for wholesale volumes and direct supermarket procurement for packaged retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American rice markets are consolidating around credit-access differentiation, with MAPA's restructuring favoring capitalized operators capable of mechanized precision agriculture while marginal smallholders face displacement.
For Market Incumbents: Acquire precision irrigation hardware fleets and GPS-guided transplanting systems to anchor yield consistency advantages in Rio Grande do Sul. Consolidate milling capacity in underpenetrated Amazon corridor states through barge-linked infrastructure investments. Substitute pressure from cassava and wheat flour in price-sensitive Northeast households demands forward integration into branded retail shelf space to capture loyalty premiums.
For New Entrants and Emerging Players: Digital traceability platforms offer technology-first entry points into ANVISA compliance documentation and blockchain-anchored residue ledgers. White-space targets include Para and Amazonas states lacking local milling infrastructure, brown rice health-food retail channels in São Paulo metropolitan health aisles, and direct-to-restaurant procurement bypassing traditional wholesale terminals. Go-to-market positioning should emphasize subscription replenishment models through supermarket e-commerce integration.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated cooperatives possessing export certification infrastructure given advancing Mercosur sanitary equivalence negotiations. Long-term viability across the analysis window favors operators controlling both seed development and direct-to-retail distribution. Acquisition target archetypes include irrigated paddy cooperatives with ANVISA-compliant milling assets and established Mercosur cross-border shipment records. The signal to watch is harmonization timeline acceleration in LATU-SENASA protocol equivalence discussions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Irrigation | Variable-rate systems with soil-moisture sensors unify water delivery with ANVISA-compliant yield forecasting. |
| Blockchain-Anchored Compliance Ledger | Spraying record immutability accelerates export certification clearance during Rio Grande do Sul harvest windows. |
| Amazon Corridor Milling Infrastructure | Barge-linked processing investments capture captive supply from Para and Amazonas production zones. |
| Direct-to-Restaurant Procurement Platform | Food service channel disintermediation captures jasmine and aromatic variety premiums outside CEAGESP terminal pricing. |
| Brown Rice Health-Food Retail Extension | Amylose-content positioning commands supermarket health-aisle price premiums in Belo Horizonte metropolitan markets. |
Research Methodology
Document review covered ANVISA regulatory filings, MAPA agricultural credit disbursement records, and Mercosur trade flow databases, complemented by interviews with cooperative milling managers, precision irrigation equipment distributors, and supermarket category buyers. Primary fieldwork engaged Rio Grande do Sul irrigated paddy operators, São Paulo CEAGESP terminal traders, and health-food retail channel procurement leads. Secondary validation drew from SENASA phytosanitary inspection protocols, LATU laboratory certification standards, and customs documentation for cross-border grain movements. Bottom-up acreage and yield estimates triangulated against top-down consumption surveys and food service channel absorption metrics.
Segmented volume and value trajectories emerged from modeling across product type, distribution channel, end-use industry, and packaging format dimensions, with additional granularity for certification-grade stratification. CAGRs were derived through regression analysis of historical production data against credit-access expansion and mechanization adoption curves. Forecast inputs incorporated irrigation infrastructure deployment schedules, ANVISA residue limit revision timelines, and Mercosur harmonization negotiation progress indicators across the projection horizon.
Several conditions sit outside the modeled scope, including extreme weather disruption of Rio Grande do Sul gravity-fed systems, abrupt fertilizer export restriction from supplier nations, and political suspension of Mercosur integration talks. Forecasts reflect documented assumptions regarding credit policy continuity and certification protocol stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Grain-Based Flours Market
Grains
Precooked Flour Market
Grains
United States Gluten-Free Oats Market
Grains
Millet Flour Market
Grains
Argentina Grains Market
Grains
Mesquite Flour Market
Grains
Masa Corn Products Market
Grains
Wheat Bran Market
Grains
Europe Rice Market
Grains
Ghana Grain Market
Grains
Ancient and Specialty Grain Flour Market
Grains
Wheat Protein Market
Grains
Corn Gluten Feed Market
Grains
Chickpeas Market
Grains
Black Gram Market
Grains
Gluten Feed Market