
 Mexico Rice Market | 2026-2036
Mexico Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Rice Market Foresight
Mexican rice milling capacity is broadening across Sinaloa and Campeche as irrigated acreage expands under federal water concessions. Verde Valle Foods leverages its vertically integrated supply chain from paddy procurement to retail distribution, sustaining shelf presence in modern trade channels nationwide. Grupo Comercial Gallo anchors the premium packaged segment through specialized long-grain offerings, while Gruma S.A.B. de C.V. competes via diversified grain portfolios that extend beyond rice into corn and wheat derivatives.
Rice comprises the starchy seed of Oryza sativa, typically milled to remove hull and bran layers, with moisture content standardized between 12% and 14% for commercial trade; its primary purpose is to serve as a caloric staple in direct consumption and as an input for processed foods including flour, beer, and ready meals. Long grain varieties dominate household purchases due to their fluffy texture and compatibility with Mexican cooking traditions, while specialty rice categories command margin premiums through organic certification and heritage cultivar positioning. Food manufacturers represent the fastest-growing end-user channel as industrial demand for rice-based ingredients accelerates in snack and beverage applications.
SADER enforces phytosanitary import permits and domestic seed registration that restrict unauthorized genetically modified strains, while NOM standards govern labeling and nutritional declarations on packaged rice products. COFEPRIS oversees maximum residue limits for pesticides, directly shaping which international suppliers gain market access. Stakeholders must monitor evolving water allocation policies under CONAGUA as climate stress intensifies competition for irrigation rights across northern growing basins.
Market Dynamics
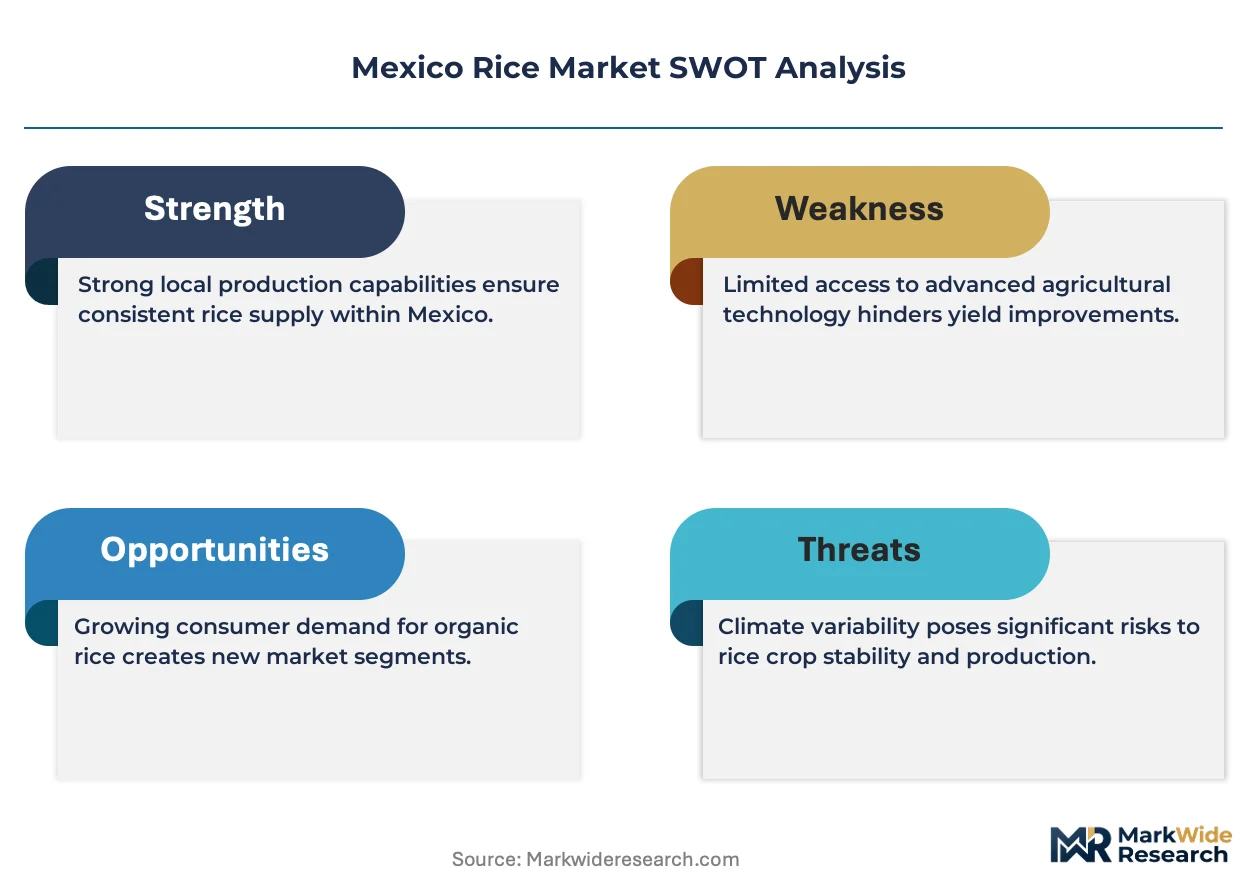
Water scarcity across northern Mexico is forcing CONAGUA to reallocate irrigation concessions, directly contracting planted acreage in Sinaloa and reshaping where domestic supply originates.
Growth Catalysts
- SADER seed registration protocols:Certified domestic varieties gain preferential access to federal crop insurance programs, accelerating farmer adoption of high-yield cultivars.
- Industrial food processing:Snack and beverage manufacturers expand rice flour and malt inputs, creating pull-through demand for specific grain specifications.
- Jalisco irrigation infrastructure:Modernized canal systems and pressurized delivery networks extend planting windows beyond traditional seasonal constraints.
Market Restraints
- Import dependency concentration:Over half of national consumption relies on paddy from three source countries, exposing millers to phytosanitary disruption.
- CONAGUA water rationing:Basin-level extraction caps in the Yaqui and Mayo river systems directly limit expansion of irrigated farmland.
- Substitute grain competition:Tortilla-grade corn and wheat flour maintain price advantages in calorie-sensitive consumer segments.
Strategic Opportunities
- Campeche wetland conversion:Federal drainage and dike investments unlock previously uncultivated acreage for commercial rice production.
- Organic certification premiums:SADER-accredited organic protocols command shelf price multiples in urban supermarket channels.
- E-commerce direct distribution:Platform logistics now reach rural households previously served only by informal tiendas.
Industry Challenges
- Milling technician scarcity:Specialized knowledge of parboiling and color-sorting equipment operation concentrates among aging workforces in Sinaloa.
- COFEPRIS residue testing timelines:Import lot clearance delays of 45-60 days tie up working capital and compress shelf-life windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Rice Market |
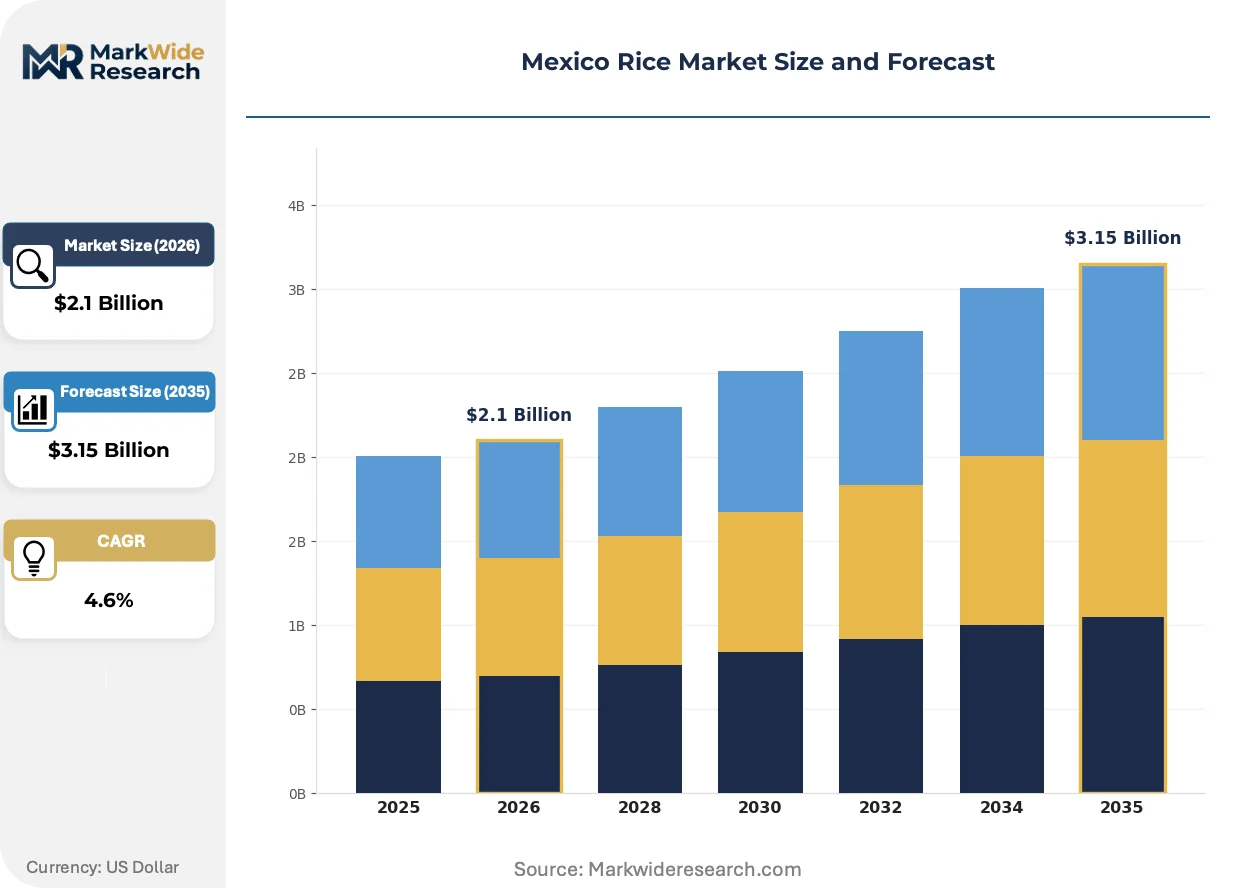
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Long Grain, Medium Grain, Short Grain, Specialty Rice Distribution Channel: Online Retail, Supermarkets, Wholesale, Convenience Stores End User: Households, Restaurants, Food Manufacturers, Exporters Packaging Type: Bags, Bulk, Boxes, Pouches |
| Companies Covered | Verde Valle Foods, Grupo Industrial Maseca, Grupo Comercial Gallo, Productos Verde Valle, Covadonga, SOS Corporación Alimentaria, Gruma S.A.B. de C.V., La Merced, Agroindustrias Unidas de México, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Rice Market Shifts & Advancements
Digital agriculture platforms and precision irrigation hardware are rewiring how Mexican growers manage water application and harvest timing. These tools compress decision cycles and reduce input waste.
Variable-rate irrigation technology is converging with satellite-derived evapotranspiration data to optimize water delivery in Sinaloa's district-level canal systems. Large-scale growers in the Yaqui Valley deploy these integrated systems to maintain yields under tightening CONAGUA allocations. The convergence is compressing per-hectare water consumption while stabilizing output quality for mill contracts.
NOM nutritional labeling amendments now mandate front-of-pack calorie disclosure on all packaged rice products sold through formal retail channels. COFEPRIS enforcement inspections have intensified at warehouse and point-of-sale levels since implementation. Premium branded processors have reformulated portion sizes and packaging formats to maintain shelf positioning under the new disclosure regime.
Urban household purchasing is fragmenting across multiple retail formats as convenience stores and quick-commerce platforms capture share from traditional weekly supermarket trips. Younger consumers in Mexico City and Guadalajara now buy rice in smaller, more frequent transactions through app-based delivery. This rotation is forcing pack size diversification and inventory velocity recalibration across the distribution network.
Mexico Rice Market Segmentation
Segmentation in the Mexico rice market reveals how capital allocation, regulatory exposure, and channel economics diverge across product grades and customer interfaces. Each dimension carries distinct margin profiles and compliance burdens that shape where millers and distributors concentrate investment.
Product Type:
Capital intensity varies sharply across grain categories, with parboiling and color-sorting infrastructure demanding the heaviest upfront outlays for long grain processors.
- Long Grain:Fluffy post-cook texture and amylose content above 22% define this specification. Jalisco and Sinaloa households drive volume demand as urban consumers favor separate grains in traditional preparations. CONAGUA water allocations directly constrain how much long grain paddy Sinaloa millers can secure under federal irrigation concessions.
- Medium Grain:Higher moisture retention and stickier cooked profile suit coastal regional cuisines. Nayarit irrigation districts concentrate plantings, though acreage contracts when Yaqui Valley water rights face seasonal curtailment.
- Short Grain:Premium sushi-grade specifications require specialized milling tolerances. Import dependency runs highest here as domestic production concentrates on longer varieties.
- Specialty Rice:Organic and heritage cultivar positioning commands shelf price multiples. SADER-accredited certification protocols limit how quickly supply can scale to meet urban supermarket demand.
Most installed capacity flows through Long Grain. Expansion is steepest in Specialty Rice.
Distribution Channel:
Channel selection determines working capital cycles, with wholesale and retail formats imposing divergent inventory turnover and payment term structures.
- Supermarkets:Formal retail chains in Mexico City and Guadalajara enforce NOM nutritional labeling compliance and front-of-pack calorie disclosure. Shelf slotting fees and promotional calendars compress margins for branded processors.
- Online Retail:App-based platforms enable direct-to-household delivery in smaller pack sizes. Younger urban consumers drive transaction frequency as convenience replaces weekly stock-up trips.
- Wholesale:Food service and industrial buyers purchase in bulk tonnage with extended payment windows. COFEPRIS residue testing timelines of 45-60 days tie up importer capital before lot release.
- Convenience Stores:Tiendas and OXXO-format outlets capture impulse purchases in rural and peri-urban zones. Inventory velocity demands rapid replenishment logistics that favor regional millers over distant suppliers.
Supermarkets absorb the largest revenue share. Online Retail is climbing the fastest.
End User:
Customer type dictates specification rigor, with industrial buyers imposing tighter grain uniformity and moisture standards than household purchasers.
- Households:Direct consumption anchors national volume demand. Urbanization in Guadalajara and Monterrey reshapes pack size preferences toward smaller, more frequent purchases.
- Food Manufacturers:Rice flour and malt inputs for snack and beverage applications require specialized milling specifications. This channel gains share fastest as industrial processing diversifies beyond traditional staples.
- Restaurants:Food service operators prioritize consistent cook times and portion yields across preparation formats. Supply contracts favor millers with color-sorting capabilities that reduce broken grain ratios.
- Exporters:Phytosanitary certification under SADER protocols limits eligible destination markets. COFEPRIS residue documentation requirements extend lead times for international shipments.
Households dominate volume throughput. Food Manufacturers show the steepest expansion trajectory.
Packaging Type:
Format economics hinge on material cost exposure and shelf-life engineering, with flexible pouches requiring lower capital entry than rigid box lines.
- Bags:Woven polypropylene remains standard for 1-5 kilogram household formats. Verde Valle Foods and Grupo Comercial Gallo anchor this segment through branded retail presence.
- Bulk:Food manufacturers and restaurants purchase unpackaged paddy or white rice in metric tonnage. Logistics concentrate around Sinaloa mill clusters with rail and port access.
- Boxes:Premium positioning in supermarket channels demands cardboard structural integrity for stacking height. NOM labeling mandates add compliance cost relative to flexible formats.
- Pouches:Stand-up flexible packaging gains traction in online retail and convenience channels. Barrier film specifications extend shelf life for smaller pack sizes in humid climates.
Bags carry the majority of unit volume. Pouches are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States rice imports from Mexico lag behind domestic sourcing, while Mexico's internal trade flows concentrate in specific agricultural corridors. Regional production patterns reflect irrigation access and federal water allocation decisions. Sub-regional specialization drives distinct competitive advantages across Mexican territory.
Jalisco
Urban household demand in Guadalajara reshapes pack size preferences toward smaller formats. SADER seed registration protocols favor certified high-yield varieties for federal crop insurance eligibility. The Lerma-Chapala basin irrigation infrastructure supports year-round production cycles for long grain milling.
Sinaloa
Industrial food manufacturers source bulk paddy for flour and malt processing inputs. CONAGUA basin-level extraction caps in the Yaqui and Mayo river systems constrain acreage expansion. Culiacán mill clusters anchor national supply chains with rail and port logistics connectivity.
Nayarit
Coastal regional cuisines sustain medium grain consumption for stickier preparation styles. Water rights curtailment in adjacent valleys shifts planting decisions toward shorter-cycle cultivars. The Santiago river irrigation district concentrates heritage variety preservation efforts.
Campeche
Federal drainage and dike investments unlock wetland acreage for commercial rice production. SADER phytosanitary standards govern seed importation for new cultivation zones. The Yucatán Peninsula's emerging production belt targets supply security for southeastern population centers.
Mexico City Metro
Quick-commerce platforms capture rice transactions from younger consumers abandoning weekly supermarket trips. NOM nutritional labeling mandates enforce front-of-pack calorie disclosure at warehouse and retail levels. Convenience store networks in peri-urban zones demand rapid replenishment logistics from regional millers.
Mexico Rice Market Competitive Landscape
Sinaloa-based producers anchor one tier; Jalisco specialists hold processing advantages through irrigation infrastructure proximity. The vendor base splits between vertically integrated grain conglomerates and regionally focused millers. Three archetypes dominate: diversified agribusiness portfolios, premium packaged brand builders, and commodity bulk suppliers. Capacity expansion and portfolio diversification represent the primary competitive vectors as water constraints reshape sourcing geography.
Within the diversified agribusiness tier, Gruma S.A.B. de C.V. and Grupo Industrial Maseca exemplify multi-grain portfolio strategies extending beyond rice into corn and wheat derivatives. Verde Valle Foods occupies a position representing vertically integrated supply chain control from paddy procurement through retail distribution. Grupo Comercial Gallo anchors the premium packaged segment archetype through specialized long-grain offerings. These three company structures illustrate how scale, integration depth, and brand positioning stratify competitive access to modern trade channels.
| Leading Market Players |
|---|
| Verde Valle Foods |
| Grupo Industrial Maseca |
| Grupo Comercial Gallo |
| Productos Verde Valle |
| Covadonga |
| SOS Corporación Alimentaria |
| Gruma S.A.B. de C.V. |
| La Merced |
| Agroindustrias Unidas de México |
| Others |
Supply & Pricing Matrix
Specialized milling technicians concentrated in Sinaloa's aging workforce widen labor-cost differentials between premium parboiling operations and standard white-rice processing, compressing pricing-tier spreads as automation investments lag in smaller Jalisco facilities.
Pricing Analysis
Capacity additions in Campeche's emerging wetland zones are reshaping price floors for medium-grade long grain as new irrigation infrastructure reduces dependency on Sinaloa's water-constrained basins. Pricing stratifies across premium packaged brands, standard bulk deliveries to food manufacturers, and economy-tier loose rice in informal tiendas. Cost compression in the economy tier is intensifying because substitute grain competition from tortilla-grade corn maintains calorie-price advantages. Food manufacturers exhibit the highest price sensitivity due to specification rigor and volume scale, while urban supermarket consumers show lowest sensitivity for SADER-certified organic positioning.
Supply Chain Analysis
Rail and port logistics costs from Culiacán mill clusters to Mexico City distribution centers anchor working capital cycles for bulk shipments, with barge alternatives through the Yaqui river system offering seasonal relief. Domestic supply draws from Sinaloa, Jalisco, and Nayarit irrigation districts, while import dependency rests on paddy from the United States, Uruguay, and Argentina. Single-source vulnerability concentrates in short-grain sushi-grade specifications where domestic production remains minimal. Distribution runs through vertically integrated conglomerates with captive retail networks alongside independent regional millers serving convenience store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value through SADER's phytosanitary permit requirements, which accelerate consolidation as compliance costs disproportionately burden non-integrated processors.
For Market Incumbents: Hedge water allocation risk by securing CONAGUA concessions in Campeche before federal drainage investments attract competing bids. Deepen backward integration into seed registration protocols to lock in federal crop insurance eligibility for contracted growers. Counter substitute grain competition through portion-size reformulation that aligns with NOM front-of-pack calorie disclosure mandates. For New Entrants and Emerging Players: Begin with specialty rice certification in Jalisco's modernized canal districts, where SADER-accredited organic protocols command shelf price multiples in Guadalajara supermarkets. Target e-commerce direct distribution for rural households previously served only by informal tiendas, leveraging platform logistics that bypass incumbent wholesale networks. Pursue co-packing arrangements with established millers to bypass parboiling equipment capital requirements. For Investors and Strategic Acquirers: Diversified agribusiness conglomerates with multi-grain portfolios are the most active acquirer in this space, seeking rice-specific capabilities to round out corn and wheat derivatives offerings. Over the coming decade, vertical integration depth from paddy procurement through retail distribution represents the durable value driver as water scarcity reshapes sourcing geography. Monitor CONAGUA basin-level extraction cap announcements as the inflection signal for acreage contraction timing in Sinaloa.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Registration | SADER-certified varieties unlock federal crop insurance programs that accelerate farmer adoption. |
| Campeche Wetland Capacity Expansion | Federal drainage investments unlock previously uncultivated acreage outside water-constrained northern basins. |
| Premium Organic Certification Program | SADER-accredited protocols command shelf price multiples in urban supermarket channels. |
| E-commerce Direct Distribution Launch | Platform logistics now reach rural households previously served only by informal tiendas. |
| Long-term Supply Agreement with Food Manufacturers | Industrial rice flour and malt demand creates pull-through for specific grain specifications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with SADER regulatory affairs officers, CONAGUA water allocation administrators, mill operations managers in Sinaloa and Jalisco, and category buyers at Mexico City supermarket chains. Secondary validation drew from SADER phytosanitary permit databases, CONAGUA irrigation concession registries, COFEPRIS residue limit notifications, and NOM labeling amendment filings. Bottom-up acreage and milling capacity estimates triangulated against top-down consumption surveys across household, food manufacturing, and food service channels.
Segment-weighting applied differential growth assumptions across long grain, medium grain, short grain, and specialty rice categories, with additional granularity for organic certification status and irrigation source reliability. Modeled dimensions included product type, distribution channel, end-user segment, and packaging format across the projection horizon. CAGRs derived from trend extrapolation of historical planted acreage, yield improvements from certified seed adoption, and industrial processing demand curves for rice-based ingredients. Water allocation policy scenarios and climate stress projections served as scenario inputs.
Several conditions sit outside the modeled scope, including abrupt CONAGUA basin-level extraction cap revisions, unilateral SADER phytosanitary import bans, and currency volatility effects on paddy import costs. Forecasts reflect documented assumptions about irrigation infrastructure completion timelines and seed registration protocol adherence rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
North America Pulses Market
Grains
Asia-Pacific Rice Market
Grains
Ancient and Specialty Grain Flour Market
Grains
Chickpeas Market
Grains
Organic Rice Market
Grains
South America Wheat Market
Grains
Non-Basmati Rice Market
Grains
Brazil Maize Market
Grains
Global Grain Analysis Market
Grains
White Rice Flour Market
Grains
Organic Cereals Market
Grains
Black Gram Market
Grains
United States Gluten-Free Oats Market
Grains
Global Cassava Flour Market
Grains
Sorghum Flour Market
Grains
South Africa Maize Market