
 Global Carpet Tile Market | 2026-2036
Global Carpet Tile Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carpet Tile Market Foresight
Subscription-based maintenance programs for modular flooring is consolidating vendor relationships around long-term service contracts rather than one-time product sales. Interface Inc. leverages its ReEntry take-back infrastructure to anchor recurring revenue streams across North American corporate portfolios. Shaw Industries Group Inc. sustains manufacturing scale through captive nylon recycling operations that lower raw-material exposure. Mohawk Industries Inc. competes on broad distribution density, occupying multiple price tiers through distinct brand architectures.
Carpet tile denotes a dimensionally stable modular floor covering, typically manufactured through tufting or fusion bonding of nylon or polypropylene face fibers onto bitumen, PVC, or thermoplastic composite backing layers, with standard dimensions of 50 cm by 50 cm. Its primary commercial purpose is to deliver localized replaceability, acoustic dampening, and underfoot ergonomics in high-traffic interior environments. Tufted construction dominates volume manufacturing due to speed and cost efficiency, yet fusion bonded formats capture premium specification in healthcare and precision-cleanroom settings where dimensional stability governs performance. Commercial offices represent the deepest application pool, though hospitality venues are generating faster specification growth as hotel operators prioritize rapid renovation cycles and noise mitigation between guest floors.
REACH restrictions on phthalate plasticizers and the EU Green Deal's embodied-carbon disclosure requirements are reshaping material selection across European supply chains, pushing manufacturers toward bio-based backings and recycled content verification. The EPA's Carpet and Rug Institute Green Label Plus program in the United States enforces volatile organic compound emission limits that filter market access for imported products. California's Department of Public Health Section 01350 protocol extends indoor air quality testing requirements that influence specification in public administration and educational institution projects. Stakeholders must monitor how building certification schemes integrate circularity metrics into procurement scoring, as this will determine which material platforms retain specification priority across corporate and government end users.
Market Dynamics
Subscription-based maintenance programs are consolidating vendor relationships around long-term service contracts rather than one-time product sales, compressing traditional distribution margins while embedding suppliers deeper into facility operations across corporate real estate portfolios.
Growth Catalysts
- EU Green Deal building renovation targets:The EU Green Deal mandates deep renovation of existing building stock, tightening embodied-carbon thresholds for interior finishes and accelerating specification of low-carbon modular flooring in commercial retrofits across Germany, the Netherlands, and the United Kingdom.
- Acoustic performance specifications:Hospitality operators in dense urban cores prioritize noise mitigation between guest floors, driving carpet tile specification for rapid renovation cycles that minimize room downtime during property refreshes.
- Healthcare precision-cleanroom demand:Fusion bonded construction formats capture premium specification in healthcare settings where dimensional stability governs infection control and maintenance protocols.
Market Restraints
- Nylon 6,6 feedstock volatility:Caprolactam and adipic acid price swings transmit directly to carpet tile manufacturing costs, compressing margins for producers without captive polymerization or long-term supply agreements.
- Phthalate plasticizer restrictions:REACH limitations on ortho-phthalates in PVC backings force reformulation investments and disqualify legacy product lines from European public procurement channels.
- Rigid core LVT substitution:Stone-polymer composite flooring displaces carpet tile in select commercial segments where moisture resistance and hard-surface aesthetics override acoustic priorities.
Strategic Opportunities
- India commercial real estate expansion:Grade A office stock in Bengaluru and Hyderabad is expanding rapidly, creating first-mover advantage for modular flooring suppliers establishing specification relationships with facility managers.
- Take-back infrastructure monetization:Reverse logistics networks for end-of-life carpet tile collection enable recurring revenue streams through material recovery fees and recycled-content product premiums.
- California Section 01350 procurement preference:Indoor air quality testing protocols for public administration and educational institution projects create specification gatekeeping that rewards compliant suppliers with sole-source eligibility.
Industry Challenges
- Recycled-content verification complexity:Mass-balance accounting for post-consumer nylon integration requires third-party certification infrastructure that many mid-tier producers lack, limiting access to green procurement schemes.
- Installation labor scarcity:Skilled commercial flooring mechanics are aging out of the trade faster than apprenticeship programs replenish capacity, extending project timelines and increasing wage pressure in major metropolitan construction markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carpet Tile Market |
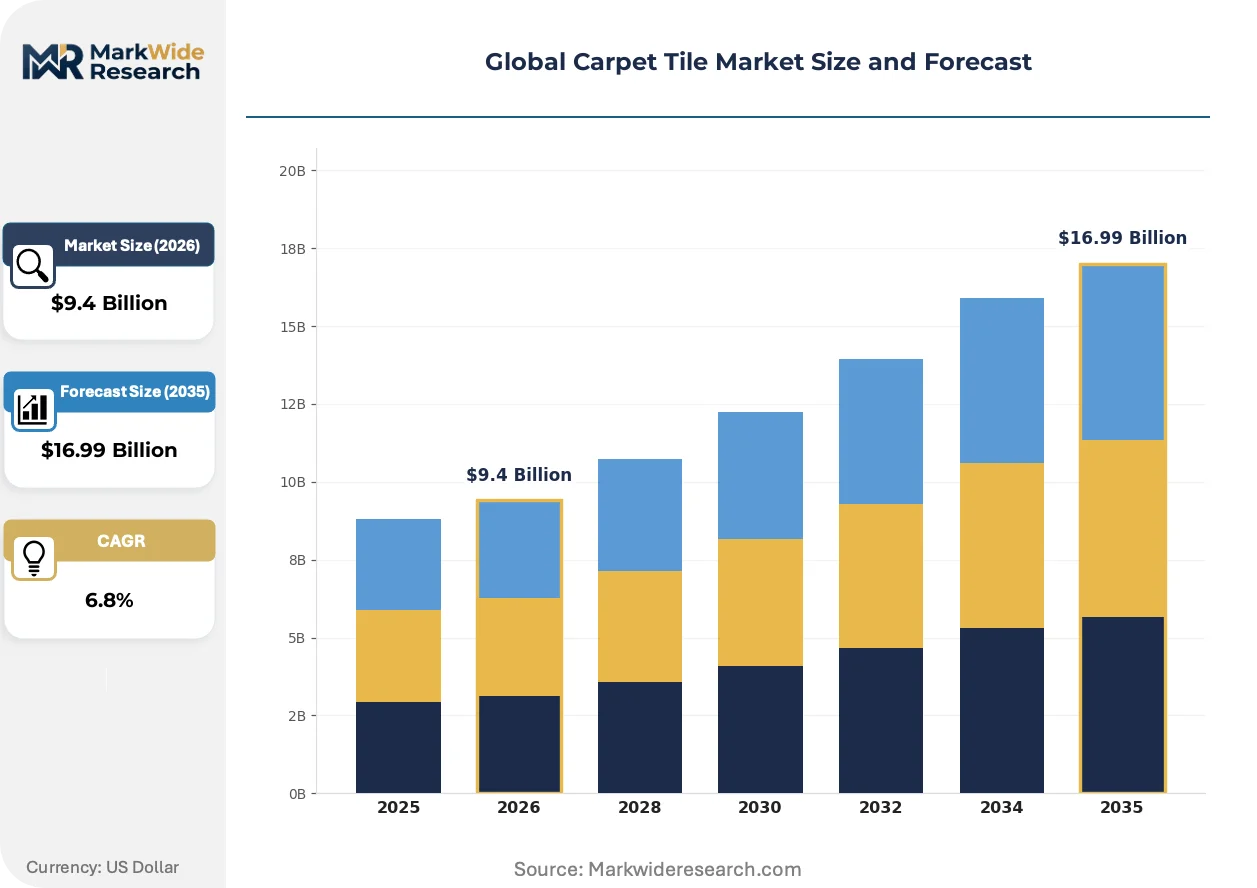
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tufted, Woven, Needle Punch, Fusion Bonded, Embossed Application: Commercial Offices, Educational Institutions, Hospitality Venues, Government Facilities, Recreation Centers End User: Corporate Offices, Higher Education, Hotels, Public Administration, Sports Complexes Installation: Glue Down, Peel & Stick, Loose Lay, Double Stick, Interlocking |
| Companies Covered | Interface Inc., Shaw Industries Group Inc., Mohawk Industries Inc., Tarkett S.A., Milliken & Company, Beaulieu International Group, Freudenberg Group, Bentley Mills Inc., Balta Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carpet Tile Market Shifts & Advancements
Material science advances and procurement model evolution are compressing product lifecycles while embedding circularity requirements into specification criteria across corporate and government end users.
Thermoplastic composite backing systems are consolidating market share from traditional bitumen and PVC alternatives by offering reduced weight, improved dimensional stability, and compatibility with closed-loop recycling infrastructure. Healthcare and education sectors in Northern Europe are specifying these platforms at accelerating rates. The technology is consolidating supplier relationships around integrated material-recovery partnerships rather than transactional product sales.
REACH restrictions on phthalate plasticizers and the EU Green Deal's embodied-carbon disclosure mandates are reshaping material selection across European supply chains. Manufacturers are reformulating backings toward bio-based polymers and accelerating recycled-content verification programs. Healthcare and public administration projects in Germany and the Netherlands face the most stringent compliance timelines, compressing specification windows for non-compliant suppliers.
Facility managers are unbundling flooring procurement from installation and maintenance services, creating discrete contracting opportunities for specialized service providers. Corporate real estate portfolios in the United Kingdom's core business districts are leading this fragmentation, separating capital expenditure for materials from operational expenditure for replacement cycles. Lease renewal triggers for full-floor carpet replacements concentrate demand timing, enabling predictive inventory positioning by suppliers with embedded service relationships.
Global Carpet Tile Market Segmentation
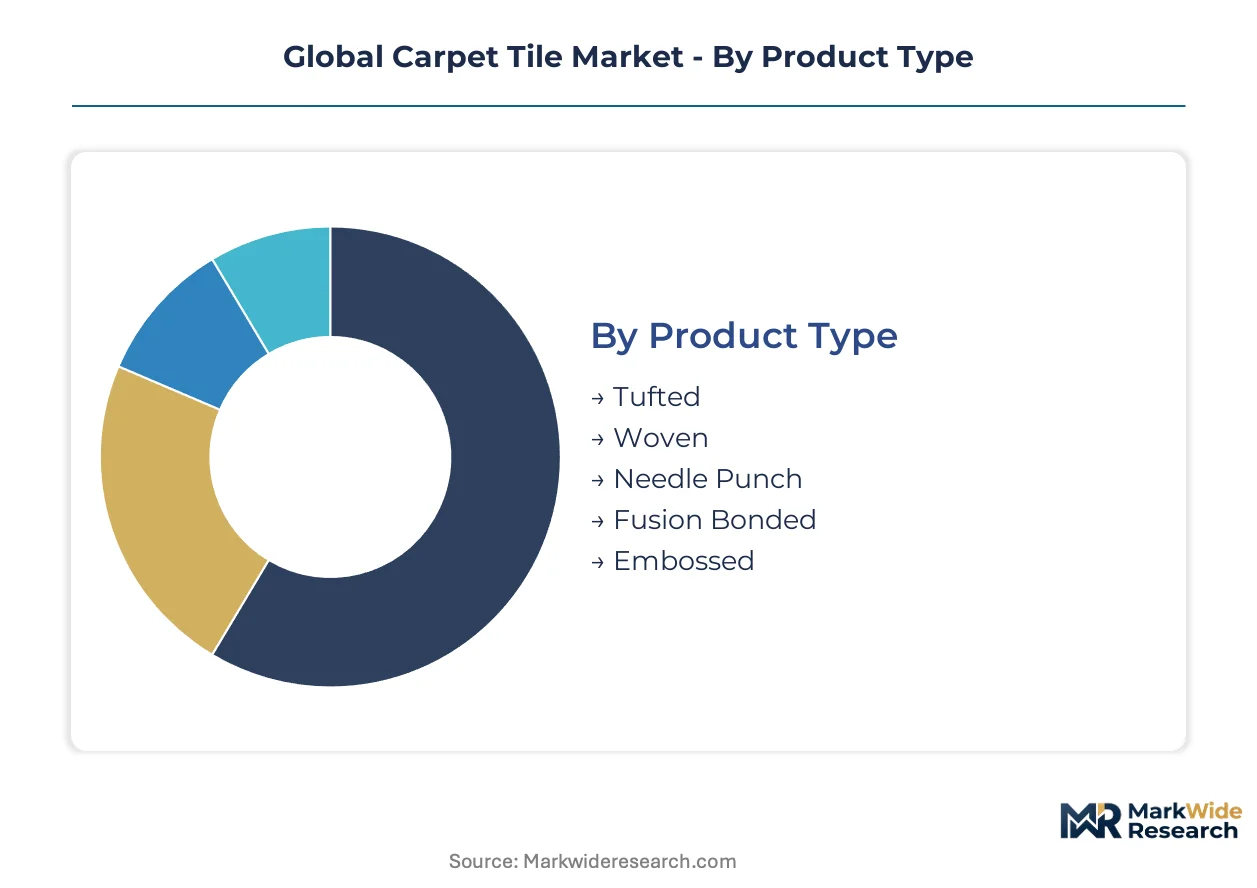
Modular flooring procurement decisions hinge on certification alignment across construction formats, installation methods, and end-use environments. Specification windows compress when regulatory thresholds diverge between product categories, forcing suppliers to maintain parallel compliance portfolios.
Product Type:
Tufted and fusion bonded formats face divergent certification burdens under REACH phthalate restrictions and EU Green Deal embodied-carbon disclosure mandates, while woven and needle punch alternatives navigate lighter regulatory scrutiny in secondary commercial applications.
- Tufted:Dominant manufacturing format utilizing nylon or polypropylene face fibers tufted into primary backing layers, then bonded with bitumen, PVC, or thermoplastic composite secondary backings. Commercial office retrofits in Germany and the Netherlands specify tufted carpet tiles for localized replaceability and acoustic performance in high-traffic zones, though caprolactam feedstock volatility compresses margins for producers lacking captive polymerization.
- Fusion Bonded:Precision construction fusing face fibers directly into homogeneous backing matrices without tufting, yielding superior dimensional stability and cleanroom compatibility. Healthcare facilities in Northern Europe and precision manufacturing environments specify fusion bonded formats where infection control protocols and static control requirements override cost considerations, with REACH plasticizer restrictions accelerating bio-based backing adoption.
- Woven:Interlaced warp and weft construction delivering aesthetic complexity and durability in premium hospitality settings.
- Needle Punch:Mechanically entangled fiber mats offering cost efficiency for recreation centers and secondary commercial spaces with moderate traffic loads.
- Embossed:Surface-textured formats specified where visual differentiation and slip resistance prioritize over acoustic performance.
Leading the category by volume: tufted construction. Growing fastest: fusion bonded formats in healthcare and cleanroom specification.
Application:
Cost tier stratification separates capital-intensive new construction from operational expenditure-driven renovation cycles, with lease renewal timing in United Kingdom business districts concentrating replacement demand.
- Commercial Offices:Deepest application pool driven by full-floor replacement cycles triggered by tenant turnover and lease renewals. Grade A office stock expansion in Bengaluru and Hyderabad creates specification opportunities for modular flooring with embedded service contracts, while United Kingdom core business districts unbundle material procurement from installation and maintenance services.
- Hospitality Venues:Hotel operators in dense urban cores prioritize rapid renovation cycles and inter-floor noise mitigation, specifying carpet tiles that minimize guest room downtime during property refreshes. Fusion bonded and tufted formats with enhanced acoustic underlayment capture premium specification in luxury and business-tier properties.
- Educational Institutions:California Section 01350 indoor air quality protocols and EPA Green Label Plus emission limits gate procurement for public administration and school construction projects.
- Government Facilities:EU Green Deal renovation targets and embodied-carbon thresholds tighten specification criteria for federal and municipal building retrofits across Germany and the Netherlands.
- Recreation Centers:Moisture resistance and durability requirements in athletic and community facilities favor thermoplastic composite backing systems over traditional bitumen alternatives.
Volume concentrates in commercial offices. Hospitality venues climb the fastest as renovation cycle compression accelerates specification turnover.
End User:
Customer type determines contract structure, with corporate real estate portfolios embedding long-term service relationships while public administration procurement favors discrete competitive bidding.
- Corporate Offices:Subscription-based maintenance programs consolidate vendor relationships around recurring revenue models rather than transactional product sales. Interface Inc. and similar suppliers anchor corporate portfolio contracts through take-back infrastructure and predictive replacement scheduling tied to lease renewal calendars.
- Hotels:Rapid property refresh cycles and brand standard compliance drive specification of modular flooring with verified recycled content and rapid installation protocols.
- Higher Education:Campus-wide sustainability commitments and student wellness priorities elevate indoor air quality certification and circularity metrics in procurement scoring.
- Public Administration:EU Green Deal mandates and REACH compliance requirements filter supplier pools for government facility renovations.
- Sports Complexes:Performance durability and maintenance accessibility govern specification for arenas, fitness centers, and community recreation facilities.
Corporate offices dominate contract value. Hotels expand most quickly as urban hospitality stock renovates at compressed cycles.
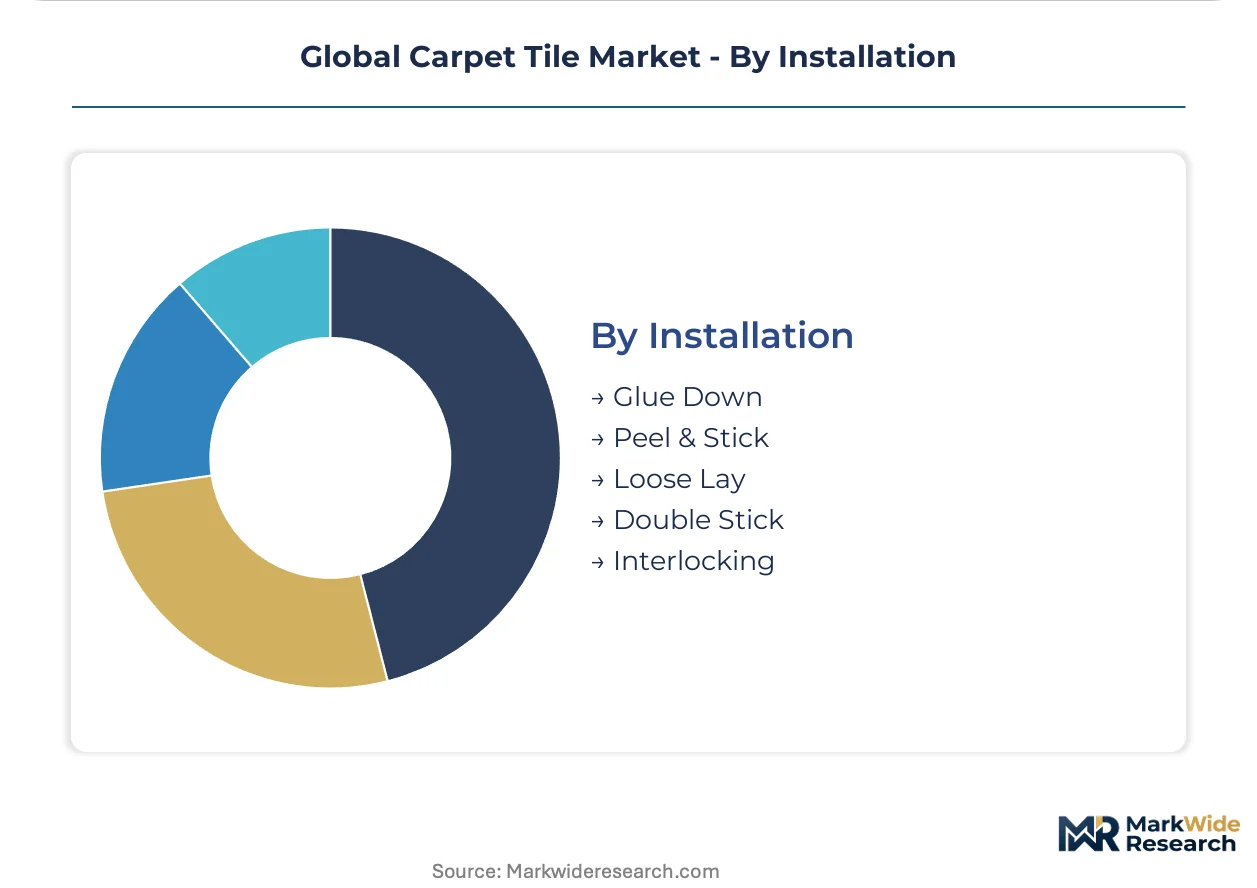
Installation:
Installation method selection trades initial labor cost against lifecycle flexibility, with skilled mechanic scarcity in major metropolitan construction markets extending project timelines and elevating wage pressure.
- Peel & Stick:Pressure-sensitive adhesive backing enables rapid deployment and localized replacement without specialized equipment. Hospitality renovation projects in United Kingdom business districts and German commercial retrofits specify peel and stick formats to minimize room downtime and reduce dependency on scarce installation labor.
- Glue Down:Permanent adhesive attachment delivering maximum dimensional stability for high-traffic commercial office environments and healthcare precision-cleanroom settings where subfloor preparation investment justifies long-term performance.
- Loose Lay:Friction and weight-based installation suited to temporary or reconfigurable corporate office layouts with frequent space planning changes.
- Double Stick:Dual adhesive layer system specified where superior bond strength and moisture barrier performance outweigh material and labor cost premiums.
- Interlocking:Mechanical edge-connection systems enabling tool-free installation and complete reusability in modular workspace and exhibition environments.
Peel and stick leads installation volume. Glue down retains share in healthcare and permanent commercial fit-outs. Interlocking gains traction fastest in flexible workspace specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's banking district and London's core business districts concentrate lease renewal-driven carpet replacement cycles, while Bengaluru and Hyderabad expand Grade A office stock. The EU Green Deal mandates deep renovation of existing building stock, tightening embodied-carbon thresholds for interior finishes. REACH phthalate restrictions and California Section 01350 protocols filter supplier access across major procurement channels.
United States
Corporate real estate portfolios in Manhattan and Chicago anchor specification volume for modular flooring with embedded service contracts. The EPA's Green Label Plus program enforces volatile organic compound emission limits that filter market access for imported products. California's Department of Public Health Section 01350 protocol extends indoor air quality testing requirements that influence procurement in public administration and educational institution projects.
Germany
Commercial office retrofits in Frankfurt and Munich expand specification volumes for low-carbon modular flooring as facility managers unbundle material procurement from installation services. The EU Green Deal's building renovation targets tighten embodied-carbon thresholds for interior finishes. REACH restrictions on phthalate plasticizers force reformulation investments and disqualify legacy product lines from European public procurement channels.
United Kingdom
Lease renewals in London's core business districts trigger full-floor carpet replacements, concentrating demand timing for suppliers with predictive inventory positioning. The EU Green Deal's embodied-carbon disclosure requirements reshape material selection across supply chains. Facility managers separate capital expenditure for materials from operational expenditure for replacement cycles, fragmenting procurement into discrete contracting opportunities.
Netherlands
Healthcare and public administration projects in Amsterdam and Rotterdam face stringent compliance timelines for REACH plasticizer restrictions and EU Green Deal mandates. Bio-based backing adoption accelerates as manufacturers reformulate to meet tightening thresholds. Thermoplastic composite backing systems consolidate market share from traditional bitumen and PVC alternatives by offering improved dimensional stability.
India
Grade A office stock expansion in Bengaluru and Hyderabad creates first-mover advantage for modular flooring suppliers establishing specification relationships with facility managers. The country's national building code and state-level environmental regulations increasingly reference indoor air quality standards. IT park developments in Hyderabad's HITEC City and Bengaluru's Outer Ring Road corridor prioritize rapid deployment formats to minimize construction timelines.
Global Carpet Tile Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the carpet tile market, creating a tiered structure where integrated manufacturers hold cost advantages while specialized service providers capture recurring revenue streams. The vendor base clusters around three strategic archetypes: integrated polymer producers with captive recycling infrastructure, broad-line flooring conglomerates spanning multiple price tiers, and modular specialists anchoring long-term maintenance contracts. Consolidation pressures favor players with verified recycled-content programs and embedded facility management relationships. Dominant competitive moves include take-back infrastructure monetization and geographic expansion into underpenetrated commercial real estate corridors.
Within the integrated manufacturing tier, Interface Inc. and Shaw Industries Group Inc. represent archetypes of circular business model implementation, while Mohawk Industries Inc. exemplifies multi-brand portfolio density across price segments. Interface anchors recurring revenue streams through ReEntry take-back infrastructure. Shaw sustains manufacturing scale through captive nylon recycling operations. Mohawk competes on distribution density, occupying multiple specification tiers through distinct brand architectures. These three players illustrate how material recovery capabilities and service contract embedding separate sustainable competitive position from transactional product competition.
| Leading Market Players |
|---|
| Interface Inc. |
| Shaw Industries Group Inc. |
| Mohawk Industries Inc. |
| Tarkett S.A. |
| Milliken & Company |
| Beaulieu International Group |
| Freudenberg Group |
| Bentley Mills Inc. |
| Balta Group |
| Others |
Supply & Pricing Matrix
EU Green Deal embodied-carbon disclosure mandates are forcing manufacturers toward bio-based backings and recycled-content verification, compressing margins for mid-tier producers lacking third-party certification infrastructure while embedding compliant suppliers deeper into long-term corporate service contracts.
Pricing Analysis
Margin tightening in standard-grade tufted formats reflects caprolactam and adipic acid feedstock volatility transmitting directly to nylon 6,6 carpet tile manufacturing costs. Three-tier pricing structure across premium, standard, and economy levels separates fusion bonded healthcare specification from commercial office tufted volumes and needle punch secondary applications, with certification grade and volume scale as primary differentiation drivers. Pricing pressure intensifies in bitumen-backed legacy lines as REACH phthalate restrictions disqualify non-compliant products from European public procurement. Corporate real estate portfolios demonstrate lowest price sensitivity due to subscription-based maintenance bundling, while recreation centers and secondary commercial spaces exhibit highest elasticity.
Supply Chain Analysis
Domestic-content preferences in United States federal and California state procurement are reshaping sourcing patterns for EPA Green Label Plus-certified products. Manufacturing gravity centers on the United States, Germany, and China, with Belgium and the Netherlands anchoring European distribution hubs. Raw material flows draw from caprolactam producers in the United States and Germany, PVC and bio-based polymer suppliers in China and Southeast Asia, and recycled nylon feedstock from captive collection networks. Single-source vulnerability concentrates in specialized fusion bonded backing substrates for healthcare cleanroom specification. Distribution runs through specification-driven contract channels serving facility management firms and corporate real estate portfolios rather than traditional retail flooring distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation labor scarcity across major metropolitan construction markets is constraining project completion capacity, propping pricing power for suppliers with embedded service relationships and predictive inventory positioning tied to lease renewal calendars.
For Market Incumbents: Anchor competitive position through captive nylon recycling infrastructure and ReEntry-style take-back program monetization that locks in recurring revenue streams across corporate portfolios. Defend against rigid core LVT substitution in moisture-sensitive segments by accelerating thermoplastic composite backing adoption and embedding predictive replacement scheduling into facility management contracts. For New Entrants and Emerging Players: Enter via Grade A office stock expansion in Bengaluru and Hyderabad, where first-mover specification relationships with facility managers remain unclaimed and rapid deployment peel-and-stick formats minimize dependency on scarce installation labor. Target hospitality renovation cycles in dense urban cores with acoustic-optimized product lines and verified recycled-content credentials that align with brand sustainability commitments. For Investors and Strategic Acquirers: The window for entry favors modular flooring specialists with operational take-back infrastructure and embedded corporate service contracts rather than pure manufacturing scale. Acquisition candidates must demonstrate third-party certification for mass-balance recycled-content accounting and established relationships with United Kingdom core business district lease renewal cycles. Watch for inflection when EU Green Deal renovation targets compress specification windows for non-compliant suppliers, triggering portfolio consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Take-Back Infrastructure Monetization | ReEntry-style programs anchor recurring revenue streams across North American corporate real estate portfolios. |
| Bio-Based Backing Reformulation | REACH compliance investments qualify suppliers for EU Green Deal public procurement channels in Germany and Netherlands. |
| Peel-and-Stick Format Expansion | Rapid deployment protocols reduce dependency on scarce commercial flooring mechanics in major metropolitan markets. |
| Recycled-Content Verification Programs | Mass-balance certification unlocks green procurement scoring in California Section 01350 public administration projects. |
| Embedded Service Contract Scaling | Predictive replacement scheduling tied to lease renewal calendars fragments procurement into long-term vendor relationships. |
Research Methodology
Trade association filings, customs and import-export databases, and SEC 10-K disclosures formed the secondary backbone, cross-referenced against primary interviews with commercial flooring contractors, facility management executives, corporate real estate portfolio directors, and carpet tile manufacturing plant managers. Bottom-up and top-down triangulation validated volume estimates across construction formats and installation methods.
Bottom-up modeling anchored individual segment projections to named input cost trajectories and regulatory compliance timelines, while top-down constraints applied macroeconomic boundary conditions across the analysis window. Segmentation dimensions included product construction type, application environment, end-user contract structure, and geographic regulatory cluster. CAGRs derived from historical elasticity patterns between commercial office stock turnover and replacement cycle timing, with nylon feedstock cost volatility and installation labor availability as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH enforcement acceleration or accelerated rigid core LVT substitution in acoustic-tolerant segments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Non-Resilient Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Floor Covering Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
US Vinyl Floorings Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
Sheet Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
Bath Mats Market
Flooring, Carpets, and Rugs
Hardwood Flooring Market
Flooring, Carpets, and Rugs
Carpet Floor Mats Market
Flooring, Carpets, and Rugs
India Laminate Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Carpet and Rugs Market