
 US Vinyl Floorings Market | 2026-2036
US Vinyl Floorings Market Size, Share, and Industry Trends Forecast 2026-2036
US Vinyl Floorings Market Insights
Aftermarket service revenue from floor preparation and subfloor remediation is tilting margin pools away from pure product sales toward installation-adjacent activities. Mohawk Industries leverages captive distribution through its dedicated flooring retail network to control channel economics. Shaw Industries Group anchors its position via backward integration into PVC resin compounding, securing raw material cost stability. Mannington Mills differentiates through specialized commercial-grade wear layer formulations that extend product lifecycle in high-traffic environments.
US vinyl floorings encompass multi-layer synthetic surfacing products, typically constructed with a PVC wear layer, printed decorative film, and rigid or flexible core substrate, manufactured through calendering or extrusion processes for moisture-resistant interior applications. Luxury vinyl plank dominates residential volume due to its dimensional stability and click-lock installation compatibility with floating floor systems. Sheet vinyl retains institutional share in healthcare and education settings where seamless hygiene protocols and heat-welded seams are specified by architects. The glue-down installation method competes with click-lock systems in commercial retrofits where substrate conditions demand direct adhesion.
The EPA regulates phthalate plasticizers in vinyl flooring under TSCA Section 6, while OSHA mandates slip-resistance standards for commercial installations, and California Air Resources Board enforces stringent VOC limits that reshape product formulation requirements nationwide. The FTC Green Guides constrain environmental marketing claims, forcing substantiation of recycled content assertions on product labeling. Stakeholders must monitor evolving state-level chemical disclosure laws and decide whether to standardize low-emission product lines nationally or maintain state-specific SKUs.
Market Dynamics
Waterproof rigid core technology is collapsing the traditional laminate flooring segment as residential renovators prioritize moisture-resistant click-lock systems for slab-on-grade foundations across Sun Belt states.
Growth Catalysts
- California Title 17 VOC Standards:Low-emission adhesive mandates in California are forcing nationwide formulation upgrades that manufacturers now market as premium differentiators in coastal markets.
- Single-Family Slab Construction:Moisture-prone concrete foundations in Florida, Texas, and Arizona favor vinyl plank installations over organic-core alternatives vulnerable to subfloor vapor transmission.
- Residential Renovation Spending:Homeowner investment in kitchen and bath upgrades channels demand toward waterproof luxury vinyl tile formats that simulate stone aesthetics at reduced installed cost.
Market Restraints
- PVC Resin Price Volatility:Feedstock exposure to ethylene and chlorine markets compresses margin stability for non-integrated manufacturers lacking captive resin compounding capacity.
- Phthalate Plasticizer Restrictions:EPA TSCA Section 6 oversight of orthophthalate chemistries forces reformulation investments that disadvantage smaller compounders with limited R&D resources.
- Sheet Vinyl Substitution:Healthcare and education architects specify heat-welded homogeneous sheet for seamless hygiene protocols, constraining luxury vinyl plank penetration in institutional new construction.
Strategic Opportunities
- Commercial Retrofit Channel:Glue-down installation methods gain traction in office-to-residential conversions where substrate irregularities demand direct adhesion rather than floating systems.
- FTC Green Guides Compliance:Substantiated recycled-content labeling creates positioning space for manufacturers with verified post-industrial PVC recovery streams in specification-driven segments.
- Aftermarket Service Integration:Floor preparation and subfloor remediation services capture margin pools beyond product sales, particularly in aging housing stock requiring moisture mitigation.
Industry Challenges
- Certified Installer Scarcity:Click-lock floating systems reduce skill barriers but commercial glue-down applications require trained mechanics familiar with moisture testing protocols and trowel-applied adhesive coverage rates.
- State SKU Proliferation:CARB-compliant formulations for California must coexist with standard-emission products for other states, complicating inventory management and production scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Vinyl Floorings Market |
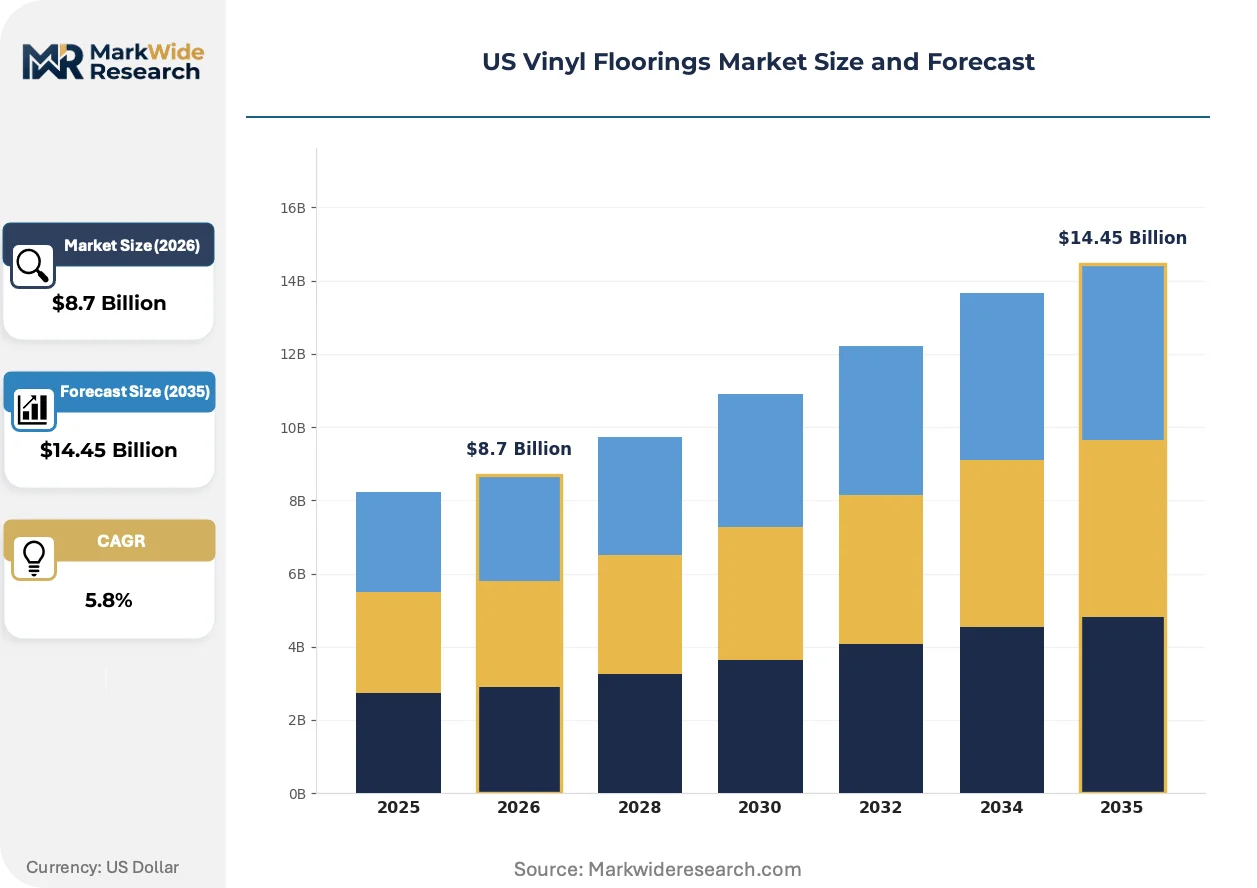
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Vinyl Tiles, Vinyl Plank, Sheet Vinyl, Vinyl Composite Tile Application: Residential, Commercial, Industrial, Institutional Installation Method: Glue Down, Click Lock, Loose Lay, Nail Down End User: Homeowners, Contractors, Architects, Designers |
| Companies Covered | Mohawk Industries, Shaw Industries Group, Armstrong Flooring, Tarkett, Mannington Mills, Interface, Forbo Holding, Gerflor Group, Congoleum Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Vinyl Floorings Market Trends and Innovations
Product architecture is converging around rigid mineral-composite cores while regulatory pressure on plasticizer chemistries accelerates bio-based additive development.
Stone plastic composite (SPC) core technology is collapsing the performance gap between vinyl and engineered wood flooring. Multi-family developers specify SPC plank for its dimensional stability under radiant heating systems and resistance to tenant turnover damage. The technology compresses warranty claim exposure for property managers while enabling thinner profile formats that reduce freight cube.
OSHA slip-resistance mandates for commercial installations are reshaping wear layer texture specifications. Architects now require coefficient of friction testing documentation alongside static load ratings for healthcare and hospitality projects. The regulation drives textured embossing investments that differentiate specification-grade products from mass-market residential lines.
Home improvement retailers are unbundling installation services from product transactions. Big-box channels now offer certified independent installer networks as a separate purchase decision, disrupting the traditional full-service flooring dealer model. This shift concentrates volume in suburban markets where consumers prioritize price transparency over design consultation.
US Vinyl Floorings Market Segmentation
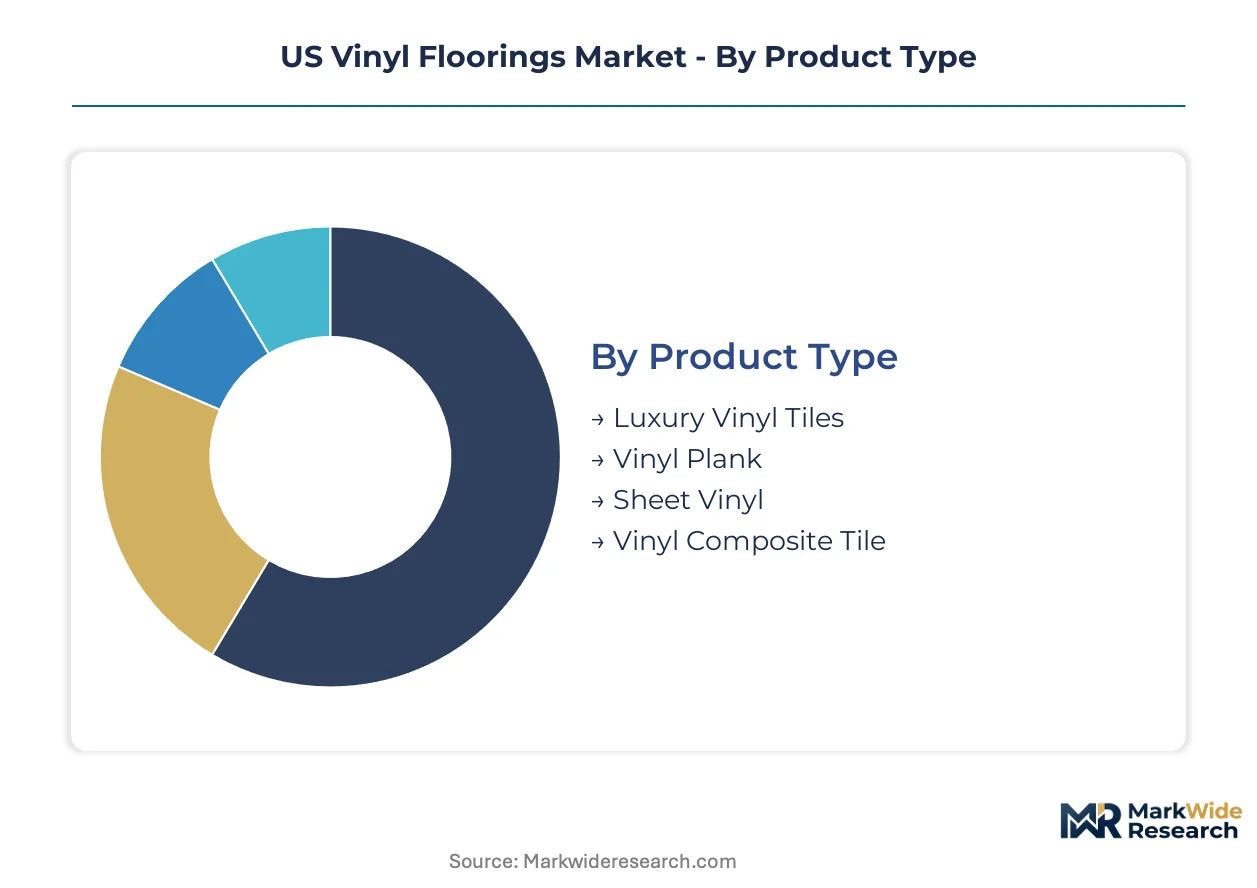
Segmentation in the US vinyl floorings market determines where margin pools concentrate. Aftermarket service intensity varies sharply across product architectures and installation methods, reshaping how manufacturers structure channel economics and warranty exposure.
Product Type:
After-sales service intensity diverges dramatically across vinyl flooring formats, with rigid core systems demanding subfloor moisture remediation that shifts revenue toward installation-adjacent activities.
- Luxury Vinyl Tiles:Modular square-format products with high-definition stone and ceramic visual reproduction. Demand concentrates in kitchen and bath renovations across Florida and Texas, where waterproof performance justifies premium positioning over organic-core alternatives.
- Vinyl Plank:Rectangular plank formats with click-lock or glue-down installation compatibility. Residential renovation spending in Arizona and Sun Belt states favors this format for its dimensional stability on moisture-prone slab foundations.
- Sheet Vinyl:Continuous roll goods with heat-weldable seams for seamless hygiene protocols. Healthcare and education architects in California specify this format for institutional new construction.
- Vinyl Composite Tile:Traditional through-pattern composition tile with homogeneous wear characteristics. Industrial facilities and high-traffic commercial retrofits maintain steady specification for its repairability and low replacement cost.
By volume, vinyl plank leads. By growth pace, luxury vinyl tiles are expanding most quickly.
Application:
Cost tier stratification separates specification-grade products for institutional clients from mass-market residential lines, with margin structure varying by project scale and certification requirements.
- Residential:Single-family renovation and new construction volume, concentrated in suburban Sun Belt markets. Homeowner preference for waterproof rigid core technology displaces traditional laminate flooring in slab-on-grade foundations.
- Commercial:Office, retail, and hospitality installations requiring slip-resistance documentation under OSHA mandates. Glue-down methods dominate where substrate irregularities preclude floating systems.
- Industrial:Manufacturing and warehouse environments prioritizing static load ratings and chemical resistance. Vinyl composite tile retains share for its repairability under heavy forklift traffic.
- Institutional:Healthcare, education, and government facilities with stringent hygiene and durability protocols. California Title 17 VOC compliance is mandatory for specification in public projects.
Residential commands absolute volume. Institutional applications show the steepest expansion trajectory as healthcare construction accelerates.
Installation Method:
Customer type divides sharply between DIY-capable homeowners and specification professionals, with skill requirements determining channel structure and margin capture.
- Glue Down:Direct adhesion to substrate using trowel-applied adhesives, requiring moisture testing and certified installer mechanics. Commercial retrofits and office-to-residential conversions favor this method for substrate irregularity tolerance.
- Click Lock:Floating floor systems with mechanical edge joining, enabling homeowner self-installation. Big-box retailers bundle independent certified installer networks as separate purchase decisions.
- Loose Lay:Friction-fit installation with perimeter anchoring, suited for temporary or rental property applications. Multi-family developers specify this for tenant turnover flexibility.
- Nail Down:Fastened installation over wood subfloors, limited to specific product constructions. Niche applications in wood-framed construction above-grade maintain residual demand.
Click lock dominates unit volume. Glue down is gaining share fastest in commercial retrofit channels.
End User:
Geography concentrates decision-making authority, with coastal architects driving specification standards that propagate inward through national retail networks.
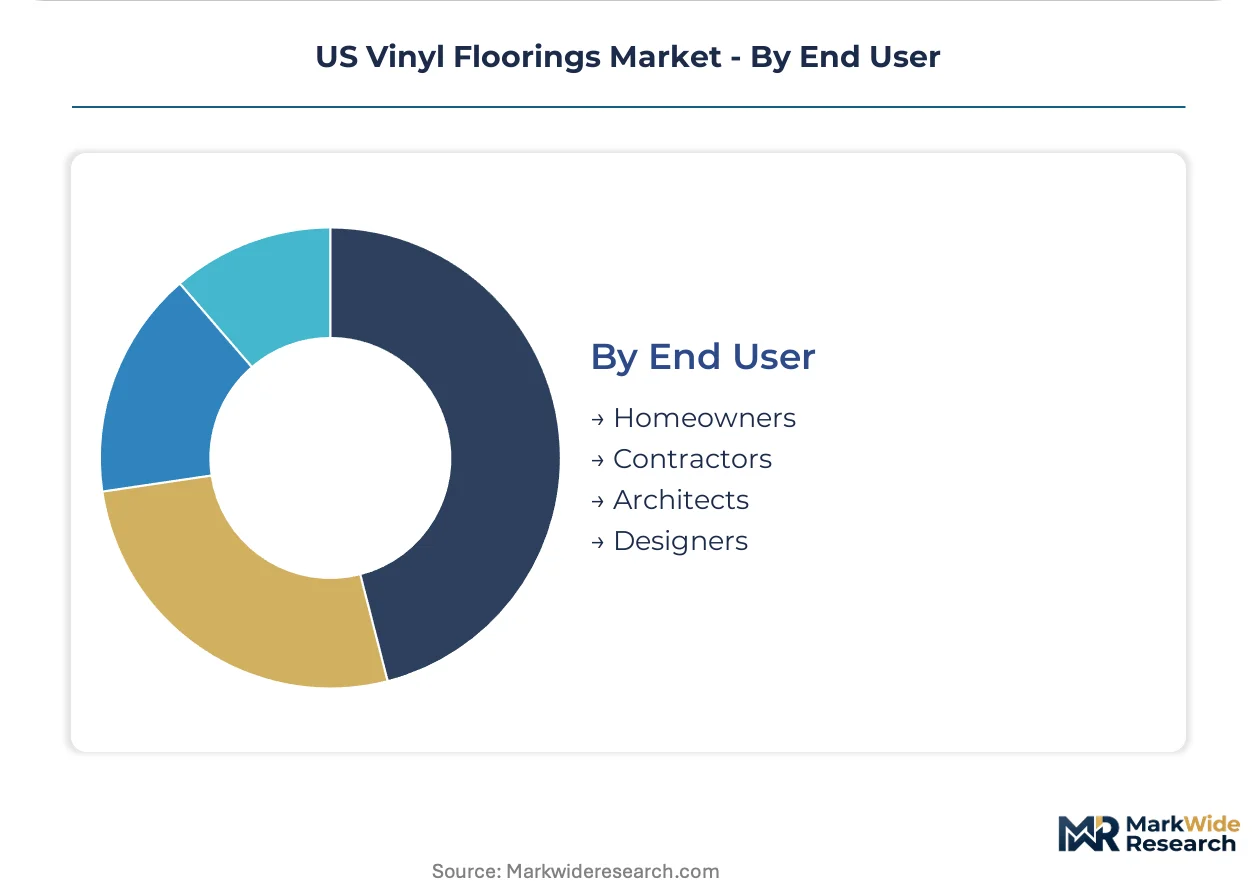
- Homeowners:Individual purchasers prioritizing waterproof performance and visual authenticity in kitchen and bath upgrades. Sun Belt states show highest per-capita spending on luxury vinyl tile formats.
- Contractors:Installation professionals managing subfloor preparation and moisture mitigation. Aftermarket service revenue from floor remediation tilts margin pools beyond product sales.
- Architects:Specification professionals requiring coefficient of friction testing and static load documentation. California and New York architects enforce stringent VOC and slip-resistance standards that reshape national product lines.
- Designers:Interior design consultants influencing material selection for high-end residential and hospitality projects. Visual authenticity and embossed texture quality drive specification decisions.
Homeowners generate the largest transaction volume. Architects control the fastest-growing specification-grade segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home renovation demand in Texas and Florida shows high elasticity to mortgage rate shifts, while California institutional buyers remain price-inelastic due to Title 17 compliance mandates. Sub-regional variation concentrates in Sun Belt moisture-prone construction zones versus Northeast corridor retrofit markets.
Southeast
Florida's slab-on-grade residential construction drives rigid core vinyl plank specification for moisture resistance against subfloor vapor transmission. The EPA TSCA Section 6 phthalate oversight shapes adhesive formulation choices across Georgia and Carolinas manufacturing nodes. Atlanta anchors distribution infrastructure serving multi-family developers prioritizing tenant turnover durability.
Southwest
Texas single-family construction volume concentrates demand for click-lock floating systems compatible with radiant heating installations. California Air Resources Board VOC limits propagate formulation standards into Arizona and Nevada markets through retailer supply chain integration. Phoenix construction corridors see accelerated adoption of SPC core technology for dimensional stability in extreme temperature cycling.
West Coast
California's Title 17 mandates force low-emission product lines that command premium positioning in Seattle and Portland specification markets. OSHA slip-resistance documentation requirements reshape wear layer texture investments for healthcare and hospitality projects. Los Angeles metro area drives luxury vinyl tile demand through kitchen and bath renovation spending in aging housing stock.
Midwest
Illinois and Ohio industrial facilities maintain vinyl composite tile specification for forklift traffic repairability and low replacement cost. The FTC Green Guides constrain recycled-content marketing claims across Michigan and Indiana manufacturing bases. Chicago commercial retrofit channel favors glue-down installation methods for office-to-residential conversion substrate conditions.
Northeast Corridor
New York and Boston architects enforce stringent coefficient of friction testing that filters specification-grade products from mass-market lines. State-level chemical disclosure laws in New Jersey and Connecticut complicate SKU management for manufacturers serving multi-state retail networks. Philadelphia anchors institutional procurement for education and healthcare facilities requiring heat-welded sheet vinyl seamless hygiene protocols.
US Vinyl Floorings Market Competitive Landscape
Capability concentration sits with integrated resin compounders; scale advantage sits with captive distribution networks. The market structures around three tiers: vertically integrated manufacturers controlling PVC supply chains, dedicated flooring specialists with formulation expertise, and diversified building materials conglomerates leveraging cross-category retail presence. Competitive moves cluster on backward integration into resin compounding and acquisition of regional installation service networks.
Within the integrated manufacturing tier, Mohawk Industries and Shaw Industries Group exemplify divergent strategic positions. Mohawk leverages dedicated flooring retail infrastructure to control channel economics and capture installation-adjacent margin pools. Shaw anchors its position through in-house PVC resin compounding capacity that insulates raw material cost volatility. Mannington Mills occupies a specialization position through commercial-grade wear layer formulation expertise targeting high-traffic institutional specification. These three represent distinct archetypes: captive distribution control, upstream supply security, and application-specific performance differentiation.
| Leading Market Players |
|---|
| Mohawk Industries |
| Shaw Industries Group |
| Armstrong Flooring |
| Tarkett |
| Mannington Mills |
| Interface |
| Forbo Holding |
| Gerflor Group |
| Congoleum Corporation |
| Others |
Pricing and Supply Chain Analysis
PVC resin price volatility tethered to ethylene and chlorine feedstock markets compresses margin stability while simultaneously widening spreads between integrated compounders and non-integrated manufacturers, forcing supply chain restructuring toward captive resin production or long-term offtake arrangements.
Pricing Analysis
Aftermarket service revenue from floor preparation and subfloor remediation drives lifetime value beyond product transactions. Three-tier pricing structure across premium, standard, and economy levels separates CARB-compliant low-emission formulations from standard products and entry-level imports. Cost compression in the standard tier intensifies because big-box retailers unbundle installation services and prioritize price transparency. Homeowners in Sun Belt renovation markets show highest price sensitivity, while California institutional buyers under Title 17 mandates remain least elastic.
Supply Chain Analysis
Tariff exposure between China and the United States dominates raw material sourcing decisions for decorative film and printed layer substrates. Domestic PVC resin compounding concentrates in Texas and Louisiana, while wear layer production draws from South Korean and German specialty chemical suppliers. Single-source vulnerability in plasticizer chemistries under EPA TSCA Section 6 oversight forces reformulation investments that disadvantage smaller compounders. Distribution runs through dedicated flooring retail networks, big-box home improvement channels, and direct commercial specification routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified installer scarcity and captive resin compounding capacity constitute the critical capability gaps separating margin leaders from price-takers in this market.
For Market Incumbents: Harden channel economics by acquiring regional installation service networks to capture aftermarket margin pools beyond product sales. Deepen backward integration into PVC resin compounding to insulate against ethylene price volatility and secure formulation control for CARB-compliant product lines. For New Entrants and Emerging Players: Pursue commercial retrofit channels in office-to-residential conversions where substrate irregularities favor glue-down installation methods and certified mechanic scarcity creates service bundling opportunities. Target multi-family developers in Phoenix and Dallas corridors with SPC core products for tenant turnover durability. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive distribution infrastructure. Long-term viability hinges on regulatory compliance capabilities and installation service integration rather than pure product manufacturing scale. Watch California Title 17 enforcement propagation into additional state jurisdictions as the inflection signal for nationwide low-emission product line investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVC Resin Compounding | Shaw Industries anchors cost stability through in-house resin production capacity. |
| Acquisition of Regional Installer Networks | Mohawk Industries captures aftermarket service revenue through dedicated retail infrastructure. |
| CARB-Compliant Formulation Standardization | Mannington Mills differentiates institutional specification through low-emission wear layer chemistry. |
| SPC Core Technology Platform Expansion | Multi-family developers specify rigid mineral-composite cores for radiant heating compatibility. |
| FTC Green Guides Compliance Certification | Verified post-industrial PVC recovery streams create positioning space in specification-driven segments. |
Research Methodology
Operator-level perspectives from plant managers at resin compounding facilities, procurement leads at flooring retailers, certified installation contractors, and commercial specification architects anchored the qualitative base. Secondary validation drew from EPA TSCA filings, CARB regulatory databases, SEC 10-K disclosures from publicly traded flooring manufacturers, and customs trade data on PVC resin imports. Bottom-up volume estimates triangulated against top-down construction spending forecasts across residential renovation and new construction categories.
Scenario-bracketing around mortgage rate sensitivity and single-family construction volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, installation method, application category, and regional regulatory cluster. CAGRs derived from trend-line extrapolation of historical volume data adjusted for technology substitution effects and formulation upgrade cycles. Forecast inputs incorporated Sun Belt migration patterns and Title 17 compliance cost pass-through assumptions.
Macroeconomic conditions sit as an overlay; deviation in residential renovation spending and mortgage rate trajectories would shift the trajectory of volume forecasts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market
Flooring, Carpets, and Rugs
Global Commercial Flooring Market
Flooring, Carpets, and Rugs
Europe Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Rigid Core Flooring Market
Flooring, Carpets, and Rugs
Decorative Rugs Market
Flooring, Carpets, and Rugs
India Carpets and Rugs Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
China Laminate Flooring Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
Carpet Floor Mats Market
Flooring, Carpets, and Rugs
Europe Floor Covering Market
Flooring, Carpets, and Rugs
China Wood Flooring Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market