
 India Wood Flooring Market | 2026-2036
India Wood Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
India Wood Flooring Market Outlook
Multi-source procurement among large flooring contractors is hardening as a dominant sourcing pattern across India's premium construction segment. Century Plyboards India Ltd. leverages captive veneer mills and resin formulation labs to control engineered wood substrate quality from pulp to plank. Welspun Flooring Ltd. competes through polymer-wood hybrid R&D aimed at tropical humidity resistance. Greenlam Industries anchors its position in the laminate overlay segment with continuous pressure laminate lines scaled for architect-specified commercial projects.
India wood flooring encompasses factory-finished plank systems ranging from three-layer engineered cross-laminated cores with two-millimeter hardwood wear layers to solid timber strips milled from teak, oak, and regionally sourced species, serving structural and aesthetic functions in interior finish applications. Engineered wood leads volume uptake in coastal cities where dimensional stability under monsoon cycling matters more than solid wood authenticity, while laminated wood occupies the price-sensitive mass residential tier through distributor-heavy networks. Specialty stores and home improvement centers remain the primary distribution channels for architect and interior designer specifications, though online retail gains traction among homeowner direct purchases in tier-one metros.
BIS mandates on formaldehyde emission classes and the Bureau of Indian Standards' plywood grading protocols shape product legality and builder liability exposure across state-level building codes. The Indian Green Building Council's rating criteria for low-VOC interior materials steer specification toward certified engineered wood in LEED-registered commercial towers. Stakeholders must monitor how India's PLI scheme for wood-based panels alters domestic manufacturing scale relative to Southeast Asian import flows.
Market Dynamics
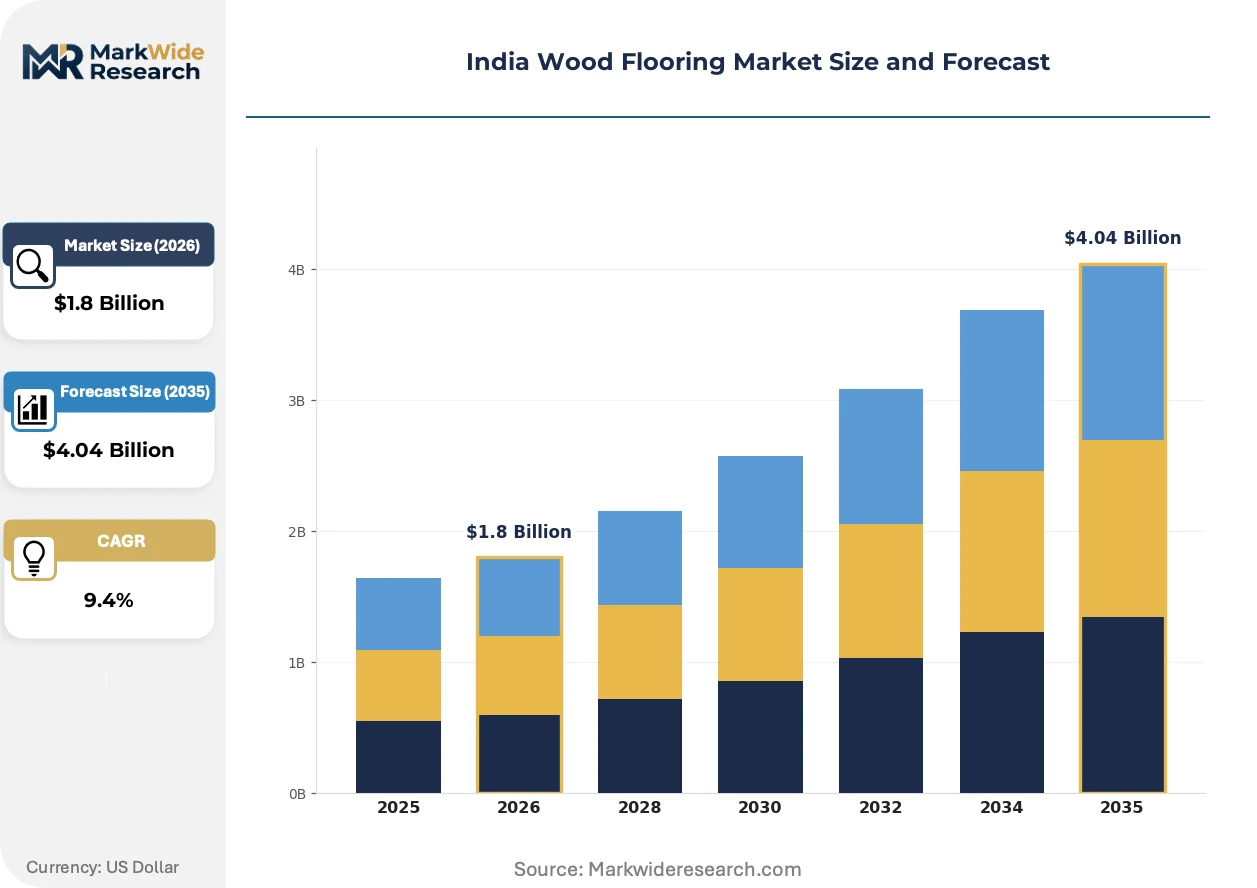
India's BIS certification mandates for engineered wood products are tightening material standards and reshaping supplier qualification across Maharashtra and Gujarat, where commercial real estate pipelines and premium housing clusters absorb the bulk of domestic and imported supply.
Growth Catalysts
- PLI scheme for wood-based panels:India's production-linked incentive scheme is altering domestic manufacturing scale relative to Southeast Asian import flows, incentivizing capital deployment into engineered wood substrate facilities.
- Luxury residential developments:Mumbai and Delhi developments are accelerating specification-grade wood flooring adoption among architect-specified commercial towers seeking LEED-registered status.
- Monsoon-resistant engineered cores:Three-layer cross-laminated construction with tropical humidity resistance is displacing solid timber in coastal cities where dimensional stability under cyclic moisture matters more than authenticity.
Market Restraints
- Imported resin and veneer supply concentration:Dependence on Southeast Asian pulp and adhesive inputs exposes margin structures to shipping rate volatility and currency fluctuation.
- Bureau of Indian Standards plywood grading protocols:Stringent formaldehyde emission class requirements create compliance friction for small-scale domestic mills lacking captive testing infrastructure.
- Laminate flooring price compression:Continuous pressure laminate imports from East Asia anchor the mass residential tier, constraining premium engineered wood expansion into price-sensitive segments.
Strategic Opportunities
- Tier-two metro penetration:Bangalore and Hyderabad home improvement centers show rising direct homeowner purchases for factory-finished plank systems previously concentrated in tier-one specification channels.
- Indian Green Building Council low-VOC criteria:LEED-registered commercial tower mandates are steering specification toward certified engineered wood, creating pull-through for compliant domestic manufacturers.
- Polymer-wood hybrid R&D:Convergence of thermoplastic binding with wood fiber substrates is enabling tropical climate performance claims that differentiate against pure timber competitors.
Industry Challenges
- Certified installer scarcity:Factory-finished plank systems require skilled floating-floor and glue-down application expertise that distributor-heavy networks struggle to maintain outside Maharashtra and Gujarat.
- Multi-source procurement complexity:Large flooring contractors hardening their sourcing patterns face integration friction when qualifying new domestic mills against established Southeast Asian suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Wood Flooring Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engineered Wood, Solid Wood, Laminated Wood, Parquet Application: Residential, Commercial, Institutional, Hospitality End User: Homeowners, Contractors, Architects, Interior Designers Distribution Channel: Online Retail, Specialty Stores, Home Improvement Centers, Distributors |
| Companies Covered | Century Plyboards India Ltd., Welspun Flooring Ltd., Pergo (Mohawk Industries), SquareFoot Flooring Pvt. Ltd., Mikasa Floors, Greenlam Industries, Armstrong Flooring (India), Action Tesa, Greenply Industries Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Wood Flooring Market Strategic Shifts
Specification-grade wood flooring in India is experiencing accelerated product evolution as coastal climate demands and green building mandates reshape material selection criteria across commercial and residential verticals.
Cross-laminated timber core construction with two-millimeter hardwood wear layers is expanding into architect-specified commercial towers in Mumbai and Delhi, where developers prioritize dimensional stability certification over solid timber authenticity. Large flooring contractors are specifying these systems at increasing rates for luxury residential developments. This expansion is compressing market share for traditional solid teak and oak strips in high-humidity zones.
BIS mandates on formaldehyde emission classes and plywood grading protocols are tightening product legality thresholds and elevating builder liability exposure across state-level building codes. Domestic mills without captive resin formulation labs face capital intensity barriers to compliance. Commercial real estate pipelines in Maharashtra and Gujarat are responding by consolidating supplier qualification around certified engineered wood substrates.
Direct homeowner purchases through online retail channels are disrupting specialty store and home improvement center dominance in tier-one metros, with interior designers losing specification control over material selection. Tier-two cities are replicating this pattern at compressed velocity. Bangalore and Hyderabad exhibit the most visible channel rotation as digital platforms aggregate factory-finished plank catalogs for unsupervised buyer decision-making.
India Wood Flooring Market Segmentation
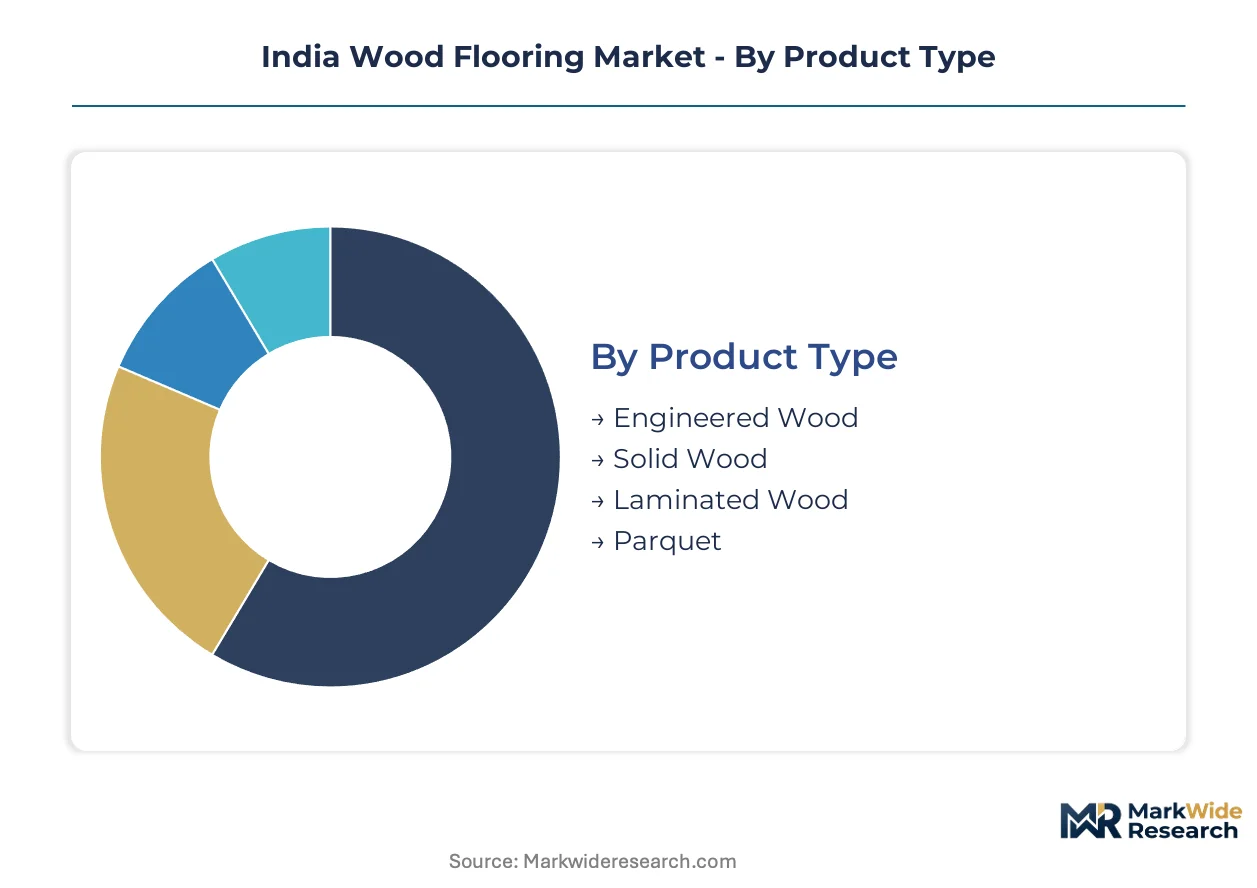
India's wood flooring market fragments across product engineering, application verticals, and procurement channels that each carry distinct margin profiles and compliance burdens. Segmentation clarity exposes where BIS certification mandates and PLI scheme incentives reshape competitive positioning.
Product Type:
Supply concentration in Maharashtra and Gujarat tilts manufacturing scale toward engineered substrates with captive resin formulation capabilities.
- Engineered Wood:Three-layer cross-laminated cores with two-millimeter hardwood wear layers dominate coastal city specifications. Mumbai and Delhi luxury residential developments specify these systems for dimensional stability under monsoon cycling, displacing solid timber in high-humidity zones.
- Solid Wood:Milled teak and oak strips retain architect preference in heritage restoration and premium authenticity-driven projects. Supply scarcity and import duty exposure constrain volume expansion beyond niche high-value installations.
- Laminated Wood:Continuous pressure laminate lines from East Asian imports anchor mass residential pricing tiers through distributor-heavy networks.
- Parquet:Geometric mosaic patterns serve boutique hospitality and institutional statement spaces requiring artisan installation expertise.
Today's leader: Engineered Wood. Tomorrow's challenger: Solid Wood.
Application:
Cost tier stratification separates specification-grade commercial towers from price-sensitive residential rollouts.
- Residential:Factory-finished plank systems split between premium housing clusters absorbing engineered wood and mass segments defaulting to laminate. Tier-one metro direct purchases through online retail are compressing specialty store channel control.
- Commercial:LEED-registered towers in Maharashtra and Gujarat mandate low-VOC engineered substrates, consolidating supplier qualification around BIS-certified domestic mills.
- Institutional:Government and educational facilities prioritize durability certification over aesthetic premium, favoring standardized engineered specifications with established maintenance protocols.
- Hospitality:Boutique hotel developments in Bangalore and Hyderabad specify parquet and solid wood for brand differentiation, though supply chain fragility limits nationwide rollout.
Commercial applications command specification authority. Residential volume scales fastest.
End User:
Procurement patterns harden around professional intermediaries versus unsupervised homeowner decision-making.
- Homeowners:Tier-one metro digital platforms aggregate factory-finished catalogs for direct purchase, eroding interior designer specification control.
- Contractors:Large flooring contractors enforce multi-source procurement protocols that favor established Southeast Asian suppliers over qualifying domestic mills.
- Architects:Mumbai and Delhi commercial tower specifications drive engineered wood adoption through Indian Green Building Council rating criteria compliance.
- Interior Designers:Specialty store channel dependence in tier-two cities preserves influence over material selection for premium residential projects.
Architects set material standards. Homeowners are gaining direct procurement velocity.
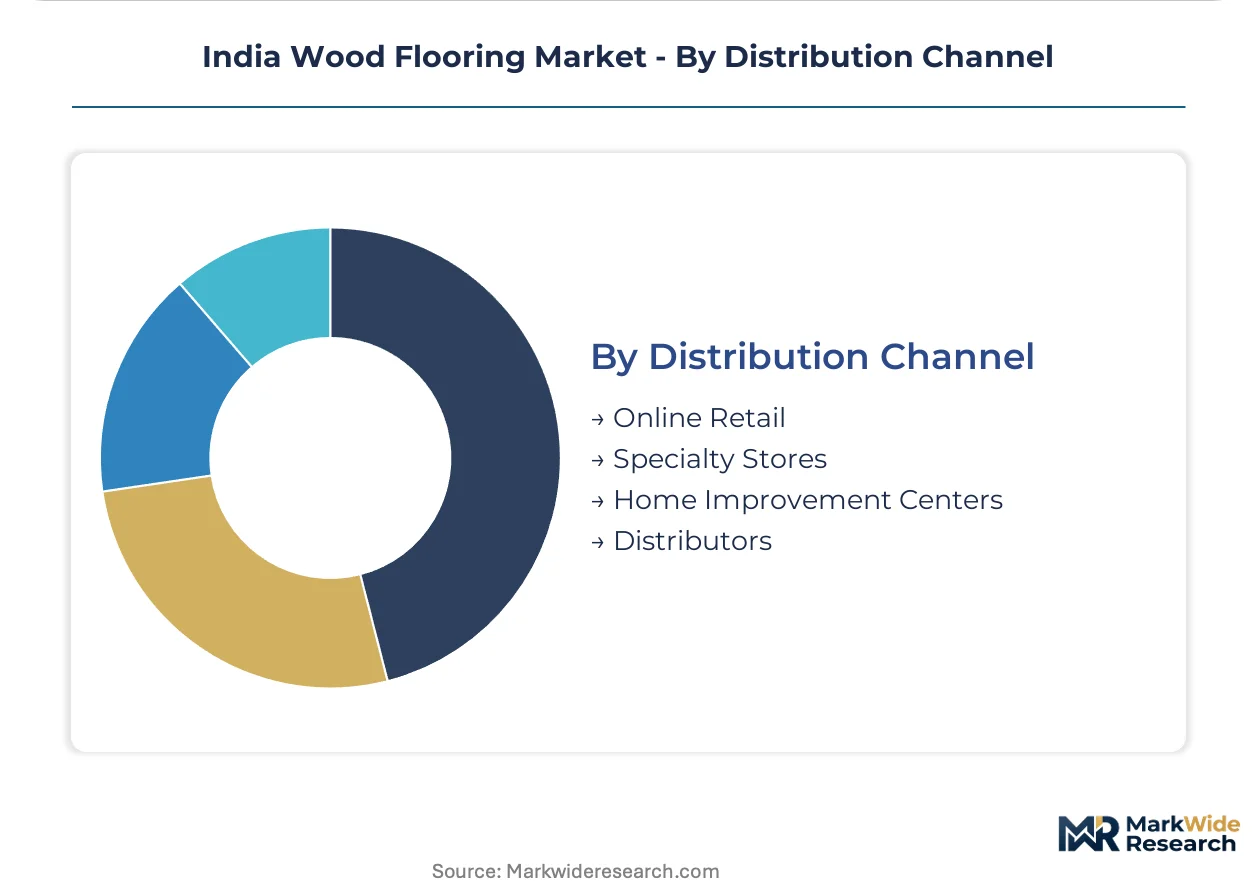
Distribution Channel:
Geographic reach determines which channels capture specification-grade versus mass market volume.
- Online Retail:Digital platforms aggregate factory-finished plank catalogs for unsupervised tier-one metro purchases, with Bangalore and Hyderabad showing fastest channel rotation.
- Specialty Stores:Architect and interior designer specifications concentrate in Maharashtra and Gujarat showrooms with certified installer networks.
- Home Improvement Centers:Tier-two metro penetration in Bangalore and Hyderabad demonstrates rising homeowner direct purchases for previously specification-controlled products.
- Distributors:Heavy networks anchor laminated wood in price-sensitive mass residential tiers, though certified installer scarcity outside core states constrains service quality.
Specialty stores retain specification authority. Online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic mills in Maharashtra and Gujarat exploit BIS compliance gaps that disadvantage smaller regional competitors lacking captive testing infrastructure. Production migrates toward these western states where resin formulation labs and veneer mills cluster, creating regulatory-arbitrage scale advantages.
Maharashtra
Mumbai's luxury residential pipeline absorbs specification-grade engineered wood for LEED-registered commercial towers. The state's BIS certification density enables faster product approval cycles than eastern competitors. Pune and Nashik manufacturing corridors concentrate cross-laminated timber facilities serving architect-specified projects.
Gujarat
Surat and Ahmedabad house continuous pressure laminate lines scaled for mass residential distributor networks. The PLI scheme for wood-based panels accelerates capital deployment into engineered substrate facilities here. Dahej and Hazira industrial zones attract resin formulation investments backward-integrated into flooring production.
Karnataka
Bangalore home improvement centers demonstrate fastest channel rotation toward online-retail aggregation of factory-finished planks. The state's software sector wealth drives direct homeowner purchases previously controlled by interior designers. Mysuru and Mangalore supply teak veneer inputs to western state fabricators.
Delhi-NCR
Gurugram and Noida commercial real estate mandates low-VOC engineered substrates for IGBC-rated towers. The National Capital Region's architect community specifies dimensional stability certification over solid timber authenticity. Faridabad mills face margin pressure from BIS formaldehyde emission class compliance costs.
Telangana
Hyderabad's tier-two metro penetration replicates tier-one digital purchasing patterns at compressed velocity. The state's pharmaceutical sector wealth supports boutique hospitality parquet specifications. Warangal and Karimnagar provide regional hardwood species for solid timber niche producers.
India Wood Flooring Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue polymer-wood hybrid differentiation and tropical climate performance claims. The vendor base clusters around three strategic archetypes: captive-integrated substrate manufacturers, import-dependent specification distributors, and continuous-laminate mass-market suppliers. Consolidation pressure intensifies as BIS grading protocols eliminate small-scale mills lacking in-house testing infrastructure. Dominant competitive moves include backward integration into resin formulation and geographic expansion into tier-two metro retail channels.
Among western India-based integrated producers, Century Plyboards India Ltd. exemplifies captive-veneer mill control over engineered substrate quality from pulp to plank. Welspun Flooring Ltd. anchors the polymer-wood hybrid R&D vector aimed at monsoon-resistant performance differentiation. Greenlam Industries occupies the laminate overlay segment with continuous pressure lines scaled for architect-specified commercial projects.
| Leading Market Players |
|---|
| Century Plyboards India Ltd. |
| Welspun Flooring Ltd. |
| Pergo (Mohawk Industries) |
| SquareFoot Flooring Pvt. Ltd. |
| Mikasa Floors |
| Greenlam Industries |
| Armstrong Flooring (India) |
| Action Tesa |
| Greenply Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Large flooring contractors in Maharashtra and Gujarat operate on project-based contract pricing that compresses distributor margins while rewarding certified domestic mills with volume premiums. BIS compliance costs and captive resin formulation capabilities stratify supplier tiers into price-differentiated qualification bands.
Pricing Analysis
Distributor markups on factory-finished plank systems vary by certification tier and installation service bundling. Three-tier pricing structure across premium certified engineered wood, standard BIS-compliant substrates, and economy laminate imports reflects formaldehyde emission class differentiation. Cost compression in the laminate tier intensifies because East Asian import volumes anchor mass residential price floors. Tier-two metro homeowners exhibit highest price sensitivity, while Mumbai commercial tower developers prioritize dimensional stability certification over unit cost.
Supply Chain Analysis
BIS plywood grading protocols and formaldehyde emission class mandates function as supplier qualification gates that eliminate small-scale mills lacking captive testing infrastructure. Raw material sourcing draws from Southeast Asian pulp and veneer inputs, Indian domestic timber plantations, and imported thermoplastic binding agents for hybrid substrates. Single-source vulnerability in resin formulation chemicals exposes margin structures to currency fluctuation. Distribution runs through specialty store networks for architect-specified projects and home improvement centers for direct homeowner purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India wood flooring has entered a late-cycle quality phase where specification-grade engineered wood commands premium positioning. LEED-registered commercial towers and luxury residential developments drive demand-shift toward certified low-VOC substrates with monsoon-resistant performance credentials.
For Market Incumbents: Acquire captive resin formulation labs and veneer mill assets to defend against margin erosion from BIS compliance cost escalation. Consolidate installer certification networks in Karnataka and Telangana before emerging polymer-wood hybrid entrants establish tropical climate performance claims. Backward integration into Dahej and Hazira industrial zones secures adhesive supply continuity. For New Entrants and Emerging Players: Boutique hospitality developers in Hyderabad and Bangalore represent an underserved buyer archetype seeking parquet and solid wood differentiation with artisan installation protocols. Tier-two metro home improvement centers offer penetrable white-space for factory-finished plank direct sales bypassing established distributor networks. Digital platform partnerships enable unsupervised homeowner catalog aggregation with certified installer dispatch. For Investors and Strategic Acquirers: Building materials conglomerates with western India manufacturing footprints are the most active acquirer in this space, targeting BIS-certified substrate producers with captive testing infrastructure. Long-term viability hinges on PLI scheme incentive capture and IGBC rating criteria alignment. Watch for inflection when the PLI scheme alters domestic manufacturing scale relative to Southeast Asian import dependency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive adhesive production insulates margin structures from Southeast Asian chemical import volatility. |
| IGBC Low-VOC Certification Program | LEED-registered tower mandates create specification pull-through for compliant domestic manufacturers. |
| Tier-Two Metro Retail Expansion | Bangalore and Hyderabad home improvement centers demonstrate fastest channel rotation toward direct homeowner purchases. |
| Polymer-Wood Hybrid R&D Investment | Thermoplastic binding convergence enables tropical humidity resistance claims against pure timber competitors. |
| Certified Installer Network Buildout | Skilled floating-floor and glue-down expertise scarcity outside Maharashtra constrains service quality expansion. |
Study Parameters
Direct dialogue with flooring contractors, architect specification leads, interior designer procurement heads, and home improvement center category managers grounded qualitative insights in operational reality. Secondary validation drew from BIS certification registries, Indian Green Building Council project databases, PLI scheme disbursement records, and customs import data for engineered wood substrates. Bottom-up volume triangulation against top-down construction pipeline estimates anchored forecast integrity.
Segment-level value outputs across product type, application vertical, end-user archetype, and distribution channel were modeled over the projection horizon. CAGRs derived from construction sector expenditure trajectories, commercial real estate absorption rates, and residential housing completion data. Monsoon cycling frequency indices and formaldehyde emission class adoption curves informed climate-resilience demand assumptions.
Underlying measurement precision varies by segment; Maharashtra and Gujarat commercial tower specifications carry tighter precision than dispersed tier-two residential estimates. Forecasts reflect documented assumptions on PLI scheme incentive continuity and BIS enforcement intensity. A model refresh is warranted upon material change in IGBC rating criteria or Southeast Asian import duty structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
Middle East Flooring and Carpet Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Floor Covering Market
Flooring, Carpets, and Rugs
China Engineered Wood Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Carpet and Rugs Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
Bath Mats Market
Flooring, Carpets, and Rugs
Carpet Market
Flooring, Carpets, and Rugs
Hard Surface Flooring Market
Flooring, Carpets, and Rugs
India Vinyl Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Plank (LVP) Market
Flooring, Carpets, and Rugs
United States Commercial Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
United States Floor Covering Market
Flooring, Carpets, and Rugs
United States Laminate Flooring Market
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market