
 Bath Rugs and Mats Market | 2026-2036
Bath Rugs and Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Bath Rugs and Mats Market Outlook
Market Context
Recycled PET fiber is shifting from niche positioning to mainstream economics in bath rug production, compressing virgin polyester margins across mid-tier supply tiers. Mohawk Industries leverages captive recycling infrastructure to stabilize input costs across its residential portfolio. Welspun Group anchors its export competitiveness through integrated cotton spinning in South Asia. Inter IKEA Group controls private-label specifications that now mandate minimum recycled content thresholds for supplier qualification.
Technical Definition and Segment Structure
Bath rugs and mats are absorbent textile floor coverings, typically constructed with pile heights between 15-35 millimeters and base weights of 800-1,500 grams per square meter, engineered to manage moisture migration and slip resistance in wet-zone environments. Cotton dominates residential replacement cycles due to biodegradability alignment, while memory foam commands premium positioning in spa and hotel channels where ergonomic underfoot support drives procurement specifications. Microfiber competes aggressively on drying speed and dye-substitution flexibility, though its synthetic origin faces escalating scrutiny under extended producer responsibility frameworks.
Regulatory Frame and Outlook
The EU REACH regulation restricts azo dyes and formaldehyde-based finishing agents in textile articles, compelling reformulation across export-oriented manufacturing bases. The US Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1630 that shape pile density and backing chemistry decisions for products entering American distribution. OEKO-TEX Standard 100 certification now functions as a de facto market access requirement across German and Scandinavian retail channels. Stakeholders must monitor divergence between EU chemical hazard classifications and US state-level disclosure mandates, particularly California's Proposition 65 litigation exposure, to avoid stranded inventory in transatlantic supply chains.
Market Dynamics
Recycled PET fiber economics are compressing virgin polyester margins across mid-tier bath rug supply tiers, forcing reformulation decisions throughout residential and hospitality manufacturing bases.
Growth Catalysts
- EU REACH chemical restrictions:Azo dye and formaldehyde limitations under ECHA oversight are accelerating OEKO-TEX certification adoption across export-oriented Turkish and Indian manufacturing clusters.
- Antimicrobial treatment protocols:Hospitality procurement teams in hotel and spa channels are mandating silver-ion or copper-infused pile finishes for wet-zone hygiene compliance.
- Sun Belt residential construction:Florida, Texas, and Arizona building permits are concentrating absorbent floor covering demand in moisture-prone climate zones.
Market Restraints
- Cotton input cost volatility:Pakistani and Indian spinning capacity constraints are transmitting price instability through natural fiber supply tiers.
- Microfiber synthetic origin liability:Extended producer responsibility frameworks in Germany and France are imposing end-of-life collection costs on polyester-based products.
- REACH compliance timeline friction:ECHA substance evaluation windows are extending reformulation cycles for textile finishers serving EU retail channels.
Strategic Opportunities
- Underpenetrated German mass retail:Aldi and Lidl private-label specifications are opening volume slots for OEKO-TEX certified suppliers meeting recycled content thresholds.
- Digital textile printing convergence:Dye-substitution flexibility is enabling SKU proliferation without minimum order quantity penalties for e-commerce pure-plays.
- California Proposition 65 defense:Litigation exposure around phthalate disclosure is creating premium positioning for compliant suppliers in West Coast distribution.
Industry Challenges
- Flammability testing backlog:16 CFR Part 1630 certification queues at CPSC-recognized laboratories are delaying US market entry timelines.
- Memory foam formulation IP:Viscoelastic polymer density patents held by chemical suppliers are constraining independent product development in ergonomic underfoot segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bath Rugs and Mats Market |
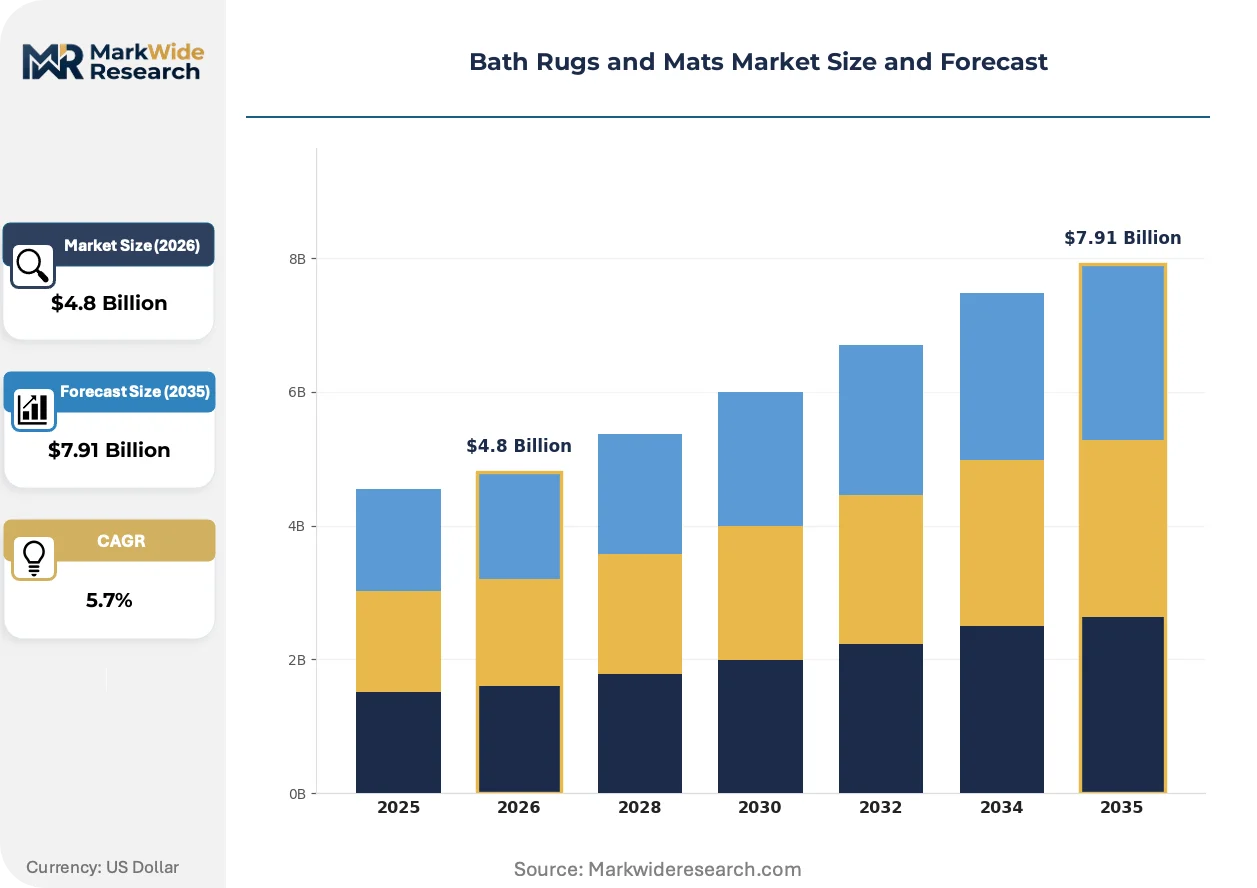
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Cotton, Microfiber, Polyester, Memory Foam Design: Contemporary, Traditional, Shaggy, Floral Shape: Rectangular, Round, Square, Oblong Usage: Residential, Commercial, Spa, Hotel |
| Companies Covered | Trident Group, Welspun Group, Mohawk Industries, Inter IKEA Group, Springs Global, American Floor Mats, Apache Mills, Clara Clark, Creative Bath Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bath Rugs and Mats Market Strategic Shifts
Material substitution and regulatory chemistry are compressing traditional competitive advantages in bath rug manufacturing, while buyer concentration in hospitality and mass retail channels rewrites sourcing specifications.
Antimicrobial fiber treatments are consolidating market access credentials for hospitality procurement teams. Hotel and spa operators now embed silver-ion or copper-based finishing requirements into blanket purchase orders. This specification creep is marginalizing untreated inventory in premium distribution channels.
REACH substance restrictions are forcing dye and finishing agent substitution across South Asian export bases. ECHA evaluation of azo compounds and formaldehyde releasers is compelling Turkish and Indian textile finishers to rebuild chemical inventories. German and Scandinavian retail buyers are treating OEKO-TEX Standard 100 as a non-negotiable qualification filter.
Direct-to-contractor platforms are compressing traditional wholesale markups in residential replacement cycles. Home improvement aggregators and builder procurement systems are disintermediating regional distributors for new construction specifications. Sun Belt states with high permit velocity are showing the fastest channel migration toward consolidated purchasing.
Bath Rugs and Mats Market Segmentation
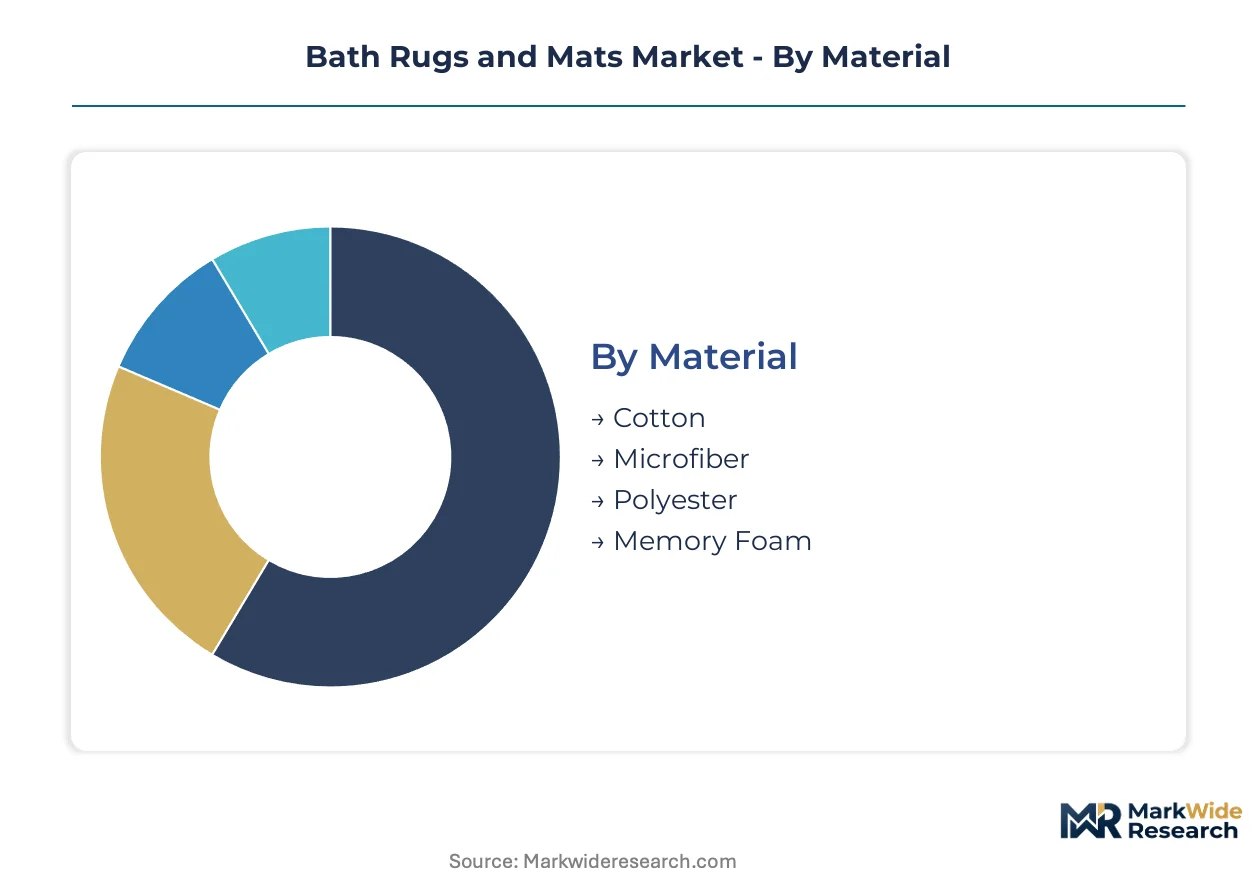
Material chemistry and end-use specifications fragment procurement patterns across bath rug manufacturing. Buyers in hospitality channels impose antimicrobial and ergonomic requirements that residential replacement cycles rarely match.
Material:
Cotton commands volume leadership through biodegradability alignment, while synthetic fibers compete on drying performance and recycled content thresholds.
- Cotton:Natural fiber with pile heights of 15-35 millimeters and base weights of 800-1,500 GSM, prized for moisture absorption and compostable end-of-life. Demand concentrates in German and Scandinavian retail channels where OEKO-TEX certification functions as a non-negotiable filter, though Pakistani and Indian spinning constraints transmit price instability through supply tiers.
- Microfiber:Synthetic filament construction engineered for rapid drying and dye-substitution flexibility in digital textile printing. Hotel and spa procurement teams in Sun Belt states favor its moisture management, yet extended producer responsibility frameworks in Germany and France impose end-of-life collection costs that compress margins.
- Polyester:Virgin and recycled PET variants serve mid-tier residential replacement cycles, with recycled fiber economics compressing virgin margins across Turkish and Indian manufacturing clusters.
- Memory Foam:Viscoelastic polymer core delivering ergonomic underfoot support for premium positioning in wet-zone environments.
Today's leader: Cotton. Tomorrow's challenger: Microfiber.
Design:
Aesthetic segmentation tracks channel concentration, with mass retail favoring versatile patterns and hospitality procurement specifying neutral palettes for brand coherence.
- Contemporary:Clean lines and minimal ornamentation dominating e-commerce pure-plays and direct-to-contractor platforms in Florida and Texas new construction.
- Traditional:Classic motifs and border detailing sustaining replacement demand in Northeastern US residential markets with older housing stock.
- Shaggy:Extended pile construction with texture emphasis, gaining traction in spa channels where tactile luxury supports premium pricing.
- Floral:Patterned designs with botanical motifs, concentrated in seasonal retail programs and gift channel distribution.
Contemporary designs anchor current volume. Shaggy textures are climbing the fastest in hospitality specification.
Shape:
Dimensional requirements vary by installation geometry, with standard bathroom footprints dictating rectangular dominance and custom spaces creating niche demand for alternatives.
- Rectangular:Standard 20x32 inch and 24x40 inch formats capturing the bulk of residential replacement and new construction specifications across US Sun Belt building permits.
- Round:Circular formats for pedestal sink and spa wet-zone installations, concentrated in hotel renovation cycles seeking visual differentiation.
- Square:Compact dimensions for powder rooms and secondary bathrooms, prevalent in multi-family residential construction.
- Oblong:Elongated profiles for double vanity and galley-style bathroom layouts, specified in higher-end residential and boutique hotel segments.
Rectangular formats maintain production scale advantages. Round shapes are gaining share fastest in hospitality renovation.
Usage:
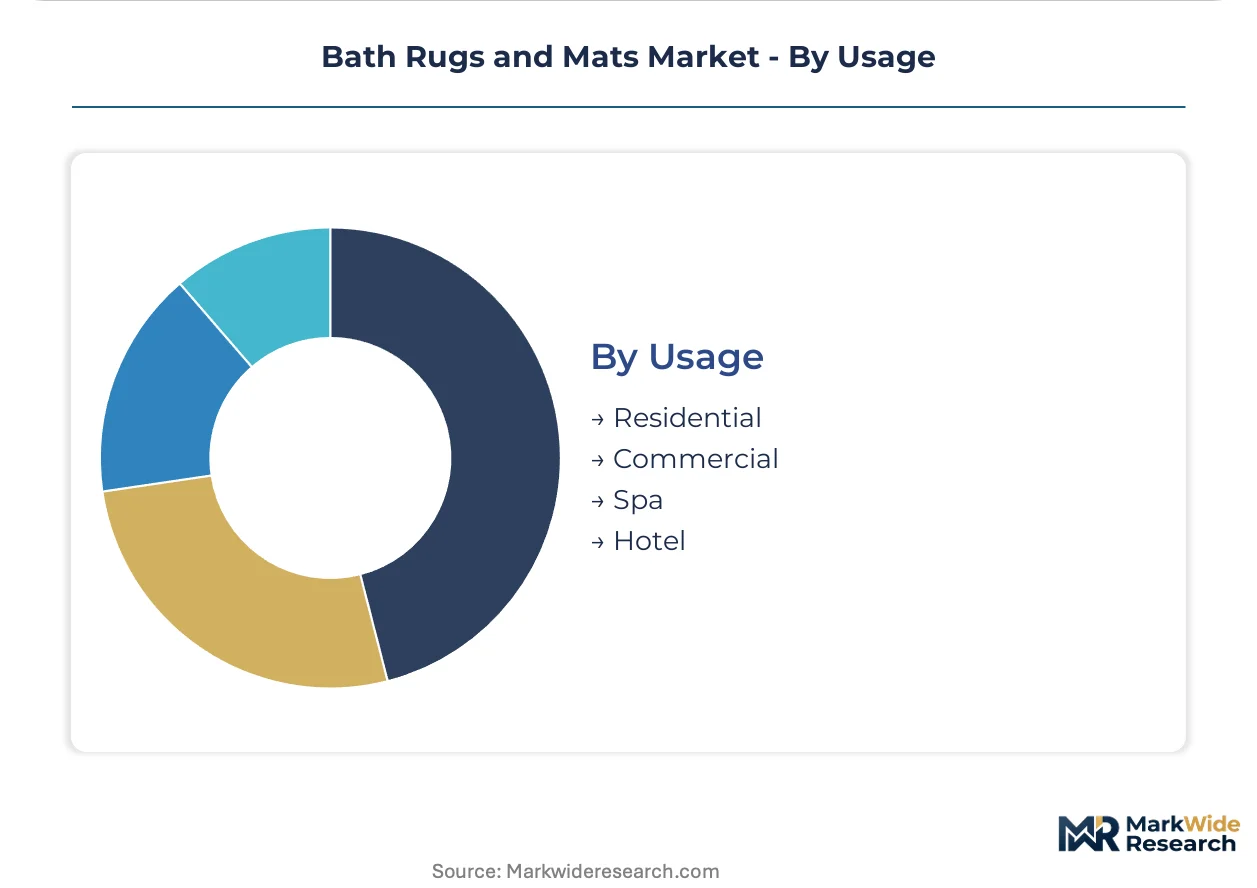
End-use segmentation separates price-sensitive residential replacement from specification-driven commercial procurement with divergent compliance burdens.
- Residential:Replacement cycles tied to home improvement spending and new construction velocity, with Sun Belt states showing fastest channel migration toward consolidated builder procurement.
- Commercial:Office and institutional applications with durability specifications and flammability compliance under 16 CFR Part 1630, facing certification queue delays at CPSC-recognized laboratories.
- Spa:Wellness channel mandating antimicrobial silver-ion or copper-infused finishes and ergonomic memory foam cores for wet-zone hygiene compliance.
- Hotel:Branded hospitality procurement with blanket purchase orders embedding recycled content thresholds and OEKO-TEX certification as qualification filters.
Residential usage holds volume concentration. Hotel procurement is expanding most quickly as branded chains renovate post-pandemic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Panipat's textile cluster dominates global bath rug manufacturing through integrated dyeing and finishing infrastructure. Regional procurement patterns diverge sharply between EU chemical compliance mandates and US flammability certification requirements. Sun Belt residential construction velocity is concentrating North American demand in moisture-prone climate corridors.
United States
Florida, Texas, and Arizona building permits are driving absorbent floor covering demand in high-humidity zones. The US Consumer Product Safety Commission enforces 16 CFR Part 1630 flammability standards that shape pile density specifications. CPSC-recognized laboratories in Georgia and North Carolina face certification backlogs that delay market entry timelines.
Germany
Aldi and Lidl private-label procurement is opening volume slots for OEKO-TEX certified suppliers. ECHA oversight of azo dyes and formaldehyde releasers under REACH is compelling Turkish exporters to rebuild chemical inventories. The Ruhr Valley textile finishing cluster is accelerating reformulation toward compliant finishing agents.
India
Welspun Group's integrated cotton spinning in South Asia anchors export competitiveness to EU and US channels. BIS textile standards and DGFT export protocols shape quality specifications for international buyers. The Panipat cluster in Haryana concentrates tufting and backing operations for North American mass retail.
Turkey
Denizli's towel and bath textile hub is pivoting toward OEKO-TEX certification to maintain German retail access. REACH substance evaluation windows are extending reformulation cycles for export-oriented finishers. The Aegean region's integrated mills are substituting azo dyes with compliant alternatives under ECHA pressure.
China
Yangtze River Delta polyester fiber producers are scaling recycled PET capacity for mid-tier bath rug supply. MIIT industrial standards and dual carbon goals are accelerating substitution away from virgin synthetic inputs. Zhejiang province's digital textile printing infrastructure is enabling SKU proliferation for e-commerce channels.
Bath Rugs and Mats Market Competitive Environment
Global majors compete with regional champions across certification and recycled content capabilities. The vendor base stratifies between integrated fiber-to-finish operators, private-label specialists, and hospitality-focused specification houses. Three archetypes dominate: captive recyclers stabilizing input costs, integrated spinners controlling cotton supply tiers, and specification aggregators mandating supplier thresholds. Competitive moves center on backward integration into fiber production and geographic expansion into underpenetrated mass retail channels.
Among India-based integrated producers, Welspun Group exemplifies the captive spinning archetype through South Asian cotton supply control. Mohawk Industries represents North American recycling infrastructure deployment with captive PET fiber operations. Inter IKEA Group anchors the specification-aggregator tier, embedding recycled content thresholds into supplier qualification protocols. These three occupy distinct competitive positions without direct overlap in procurement specifications or geographic sourcing priorities.
| Leading Market Players |
|---|
| Trident Group |
| Welspun Group |
| Mohawk Industries |
| Inter IKEA Group |
| Springs Global |
| American Floor Mats |
| Apache Mills |
| Clara Clark |
| Creative Bath Products |
| Others |
Value Chain & Pricing Dynamics
Captive recycling infrastructure anchors both supply security and pricing power for integrated North American producers, while outsourced dye-finishing in South Asian export bases exposes mid-tier suppliers to REACH-driven reformulation costs that compress margins without commensurate price recovery.
Pricing Analysis
Input-cost pass-through from cotton spinning constraints in Pakistan and India transmits volatility through natural fiber supply tiers, while recycled PET fiber economics compress virgin polyester margins across Turkish and Indian manufacturing clusters. Pricing stratifies across premium memory foam positioning in hospitality procurement, standard OEKO-TEX certified tiers for German mass retail, and economy microfiber segments facing extended producer responsibility cost burdens in France and Germany. Price erosion runs through mid-tier synthetic supply as hospitality buyers consolidate volume around antimicrobial specifications. Residential replacement cycles in Sun Belt states show highest price sensitivity, while hotel procurement teams prioritize compliance certification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Panipat's integrated dyeing and finishing cluster, where concentrated tufting and backing operations for North American mass retail create geographic chokepoint exposure. Raw material flows draw from Pakistani and Indian cotton spinning, Yangtze River Delta recycled PET fiber production, and Denizli's towel textile hub for OEKO-TEX compliant finishing. Supply chain risk centers on REACH substance evaluation windows extending reformulation cycles for EU-bound inventory. Distribution runs through direct-to-contractor platforms disintermediating regional wholesalers in Florida and Texas new construction, alongside consolidated hospitality procurement systems embedding recycled content thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU chemical compliance costs and US flammability certification backlogs, with Turkish and Indian exporters capturing margin from German retail OEKO-TEX mandates while North American producers exploit captive recycling infrastructure.
For Market Incumbents: Lock in backward integration into fiber production to stabilize input costs against Pakistani and Indian cotton volatility, while securing early queue positions at CPSC-recognized laboratories to defend market entry timelines against 16 CFR Part 1630 certification delays. Prioritize antimicrobial treatment IP partnerships to meet hospitality specification creep before untreated inventory marginalization accelerates. For New Entrants and Emerging Players: The mid-tier price-point gap between premium memory foam hospitality positioning and economy microfiber residential tiers opens white-space for OEKO-TEX certified recycled PET products targeting Aldi and Lidl private-label procurement in Germany. Digital textile printing infrastructure enables SKU proliferation without minimum order quantity penalties for e-commerce pure-plays. California Proposition 65 compliance creates premium positioning defense in West Coast distribution. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance investments exceed standalone mid-tier returns, creating acquisition opportunities for integrated operators with captive chemical reformulation capabilities. Long-term viability favors fiber-to-finish archetypes with recycling infrastructure or South Asian cotton supply control. Watch for ECHA substance evaluation acceleration as inflection signal for Turkish exporter distress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled PET Fiber | Mohawk Industries stabilizes input costs against virgin polyester margin compression. |
| OEKO-TEX Certification Investment | Turkish exporters secure German mass retail access under REACH compliance pressure. |
| Antimicrobial Treatment Partnership | Silver-ion finishing capabilities meet hospitality procurement specification creep. |
| Direct-to-Contractor Platform Launch | Home improvement aggregators disintermediate regional distributors in Sun Belt states. |
| Digital Textile Printing Scale-Up | Zhejiang infrastructure enables SKU proliferation for e-commerce pure-plays. |
Study Parameters
Multiple input streams — executive interviews with hospitality procurement directors and mass retail category buyers, technical consultations with textile finishing chemists, and regulatory tracking of ECHA substance evaluations — were reconciled against secondary validation from customs trade data, SEC textile sector filings, and OEKO-TEX certification databases. Bottom-up triangulation across material segment production volumes and top-down cross-checks against end-use channel demand completed the reconciliation framework.
Historical volume trajectories were cross-referenced against panel input from supply chain planners and distribution channel heads to construct projections across the analysis window. Segmentation modeling captured material chemistry, design aesthetic, dimensional format, and end-use specification dimensions. CAGRs derived from elasticity-adjusted demand curves incorporated Sun Belt residential construction permit velocity and hospitality renovation cycle timing as industry-specific inputs.
Caveats apply where ECHA substance evaluation acceleration, CPSC laboratory capacity expansion, or cotton harvest volatility could materially shift the outlook. Forecasts reflect documented assumptions about regulatory timeline adherence and channel migration speed. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Global Commercial Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Plank (LVP) Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
GCC Floor Covering Market
Flooring, Carpets, and Rugs
United States Laminate Flooring Market
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
Wood Plastic Composite (WPC) Floorings Market
Flooring, Carpets, and Rugs
Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Global Non-Resilient Flooring Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
Global Vinyl Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Floor Covering Market
Flooring, Carpets, and Rugs
Decorative Rugs Market
Flooring, Carpets, and Rugs
China Engineered Wood Flooring Market