
 Resilient Floor Covering Market | 2026-2036
Resilient Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Resilient Floor Covering Market Analytics
Healthcare facility construction is hardening demand for slip-resistant, antimicrobial resilient surfaces in acute-care and senior-living environments. Mohawk Industries leverages its broad manufacturing scale to supply multi-format vinyl systems across North American hospital networks. Tarkett S.A. anchors European demand through specialized rubber flooring for operating theaters and clean rooms. Shaw Industries Group competes on recycled-content technology leadership, differentiating its vinyl sheet lines for LEED-targeted projects.
Resilient floor covering comprises polymer-based or natural material systems engineered to absorb impact, resist moisture, and maintain dimensional stability under cyclic loading, with vinyl formulations typically incorporating PVC, plasticizers, and wear-layer coatings for 10-20 year service life in commercial settings. The product type dimension shows vinyl occupying the dominant volume position while rubber commands premium pricing in industrial and institutional channels; the application dimension reveals commercial retrofit activity outpacing new residential ground-up construction as margin pools shift toward healthcare, education, and hospitality verticals.
Regulatory frameworks including CARB Phase II in the United States, REACH and the EU Green Deal in Europe, and China's GB standards under MEE oversight constrain VOC emissions, phthalate content, and end-of-life disposal pathways for resilient flooring manufacturers. Compliance investments now function as market access gates, with non-certified products excluded from public procurement tenders and green building certification schemes. Stakeholders must monitor evolving chemical restriction lists and circular-economy mandates to align product development with tomorrow's specification requirements.
Market Dynamics
CARB Phase II compliance thresholds are compressing manufacturing flexibility while tier-one Chinese cities accelerate commercial renovation cycles, creating divergent cost pressures across supply chains.
Growth Catalysts
- Healthcare construction mandates:Acute-care facility specifications now require antimicrobial, slip-resistant surfaces in patient zones and operating theaters. Senior-living operators specify these materials for fall-prevention protocols.
- REACH chemical restrictions:European phthalate limitations under ECHA oversight are forcing formulation innovation toward bio-based plasticizers. Compliant products gain preferential access to public procurement tenders.
- Recycled-content specifications:LEED-targeted projects in North American commercial retrofits specify post-consumer vinyl content. Shaw Industries and competitors invest in closed-loop collection infrastructure to meet these requirements.
Market Restraints
- Petrochemical input volatility:PVC resin and plasticizer costs fluctuate with ethylene and chlorine feedstock markets. Margins compress unpredictably when naphtha prices spike.
- China supply concentration:Virgin PVC production clusters in Sichuan and Shandong provinces. Geopolitical friction or energy rationing disrupts raw material flows to global compounding facilities.
- Technical service-life ceilings:Current wear-layer technology limits commercial vinyl to 15-20 year replacement cycles. Specifiers in premium segments compare this unfavorably to 30+ year ceramic alternatives.
Strategic Opportunities
- India commercial real estate:Bangalore and Mumbai office stock expansion creates demand for cost-competitive resilient systems. Local manufacturing partnerships reduce import duty exposure.
- Digital specification platforms:Building information modeling (BIM) libraries now embed flooring performance data. Manufacturers integrating real-time carbon footprint metrics capture architect attention at design stage.
- EU Green Deal circular mandates:Upcoming extended producer responsibility rules for construction materials create first-mover advantage for take-back program operators. Tarkett's European collection network positions for compliance leadership.
Industry Challenges
- Formulation chemist scarcity:Expertise in low-VOC, high-performance polymer compounding concentrates at legacy manufacturers. New entrants struggle to recruit talent capable of navigating REACH and CARB constraints simultaneously.
- Certification timeline compression:Green building rating systems update criteria faster than 18-month product development cycles. R&D teams face specification obsolescence before launch.
- Legacy adhesive incompatibility:Existing commercial floors use solvent-based bonding systems incompatible with new low-emission substrates. Retrofit contractors encounter substrate preparation cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resilient Floor Covering Market |
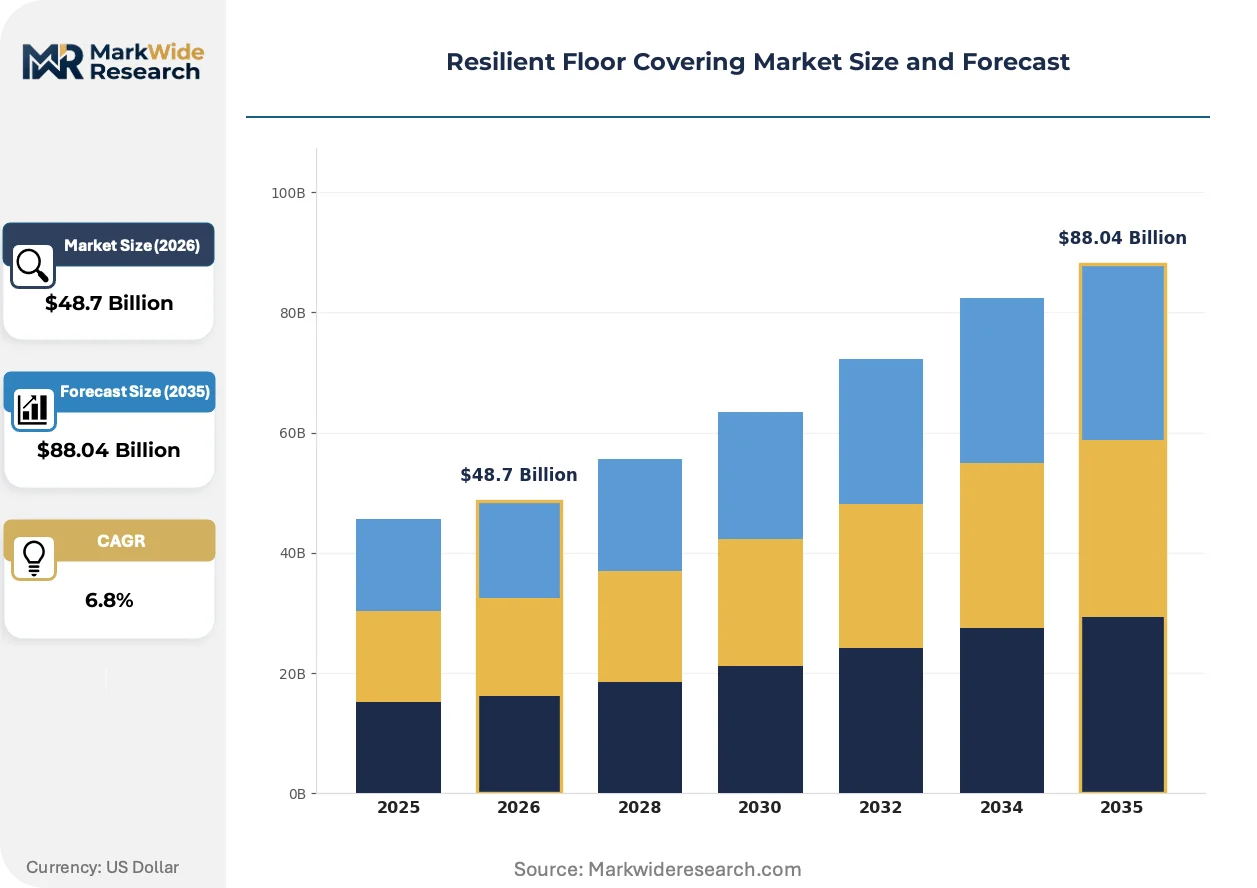
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Linoleum, Rubber, Cork Application: Residential, Commercial, Industrial, Institutional Installation Type: Glue-Down, Floating, Interlocking, Sheet End User: Homeowners, Contractors, Architects, Designers |
| Companies Covered | Mohawk Industries, Tarkett S.A., Shaw Industries Group, Armstrong Flooring, Forbo Flooring Systems, Gerflor, Interface, Mannington Mills, Beaulieu International Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resilient Floor Covering Market Evolving Landscape
Material science advances and specification digitization are compressing traditional product hierarchies while regulatory fragmentation forces regional customization of formerly standardized formulations.
Luxury vinyl tile (LVT) with rigid core construction is modularizing installation workflows through click-lock edge profiles that eliminate wet adhesive curing. Healthcare facility maintenance teams specify these systems for rapid room turnover during infection-control renovations. The technology is modularizing contractor labor models by reducing skilled-trade hour requirements and enabling phased occupancy during multi-wing retrofits.
California Air Resources Board (CARB) Phase II is tightening formaldehyde and VOC emission thresholds for composite wood products used in flooring substrates. Manufacturers serving West Coast markets must maintain dual inventory streams or reformulate universally to the stricter standard. Healthcare and education verticals in California now exclude non-certified products from design-bid-build tenders, compressing market access for non-compliant suppliers.
Building owners are consolidating flooring specifications under national account procurement structures that bypass traditional distributor relationships. Hospitality chains and retail rollouts now mandate centralized material selection with regional installation-only contracts. This concentration is most visible in United States multi-site operators where procurement teams negotiate direct manufacturer pricing for 50+ location deployment schedules.
Resilient Floor Covering Market Segmentation
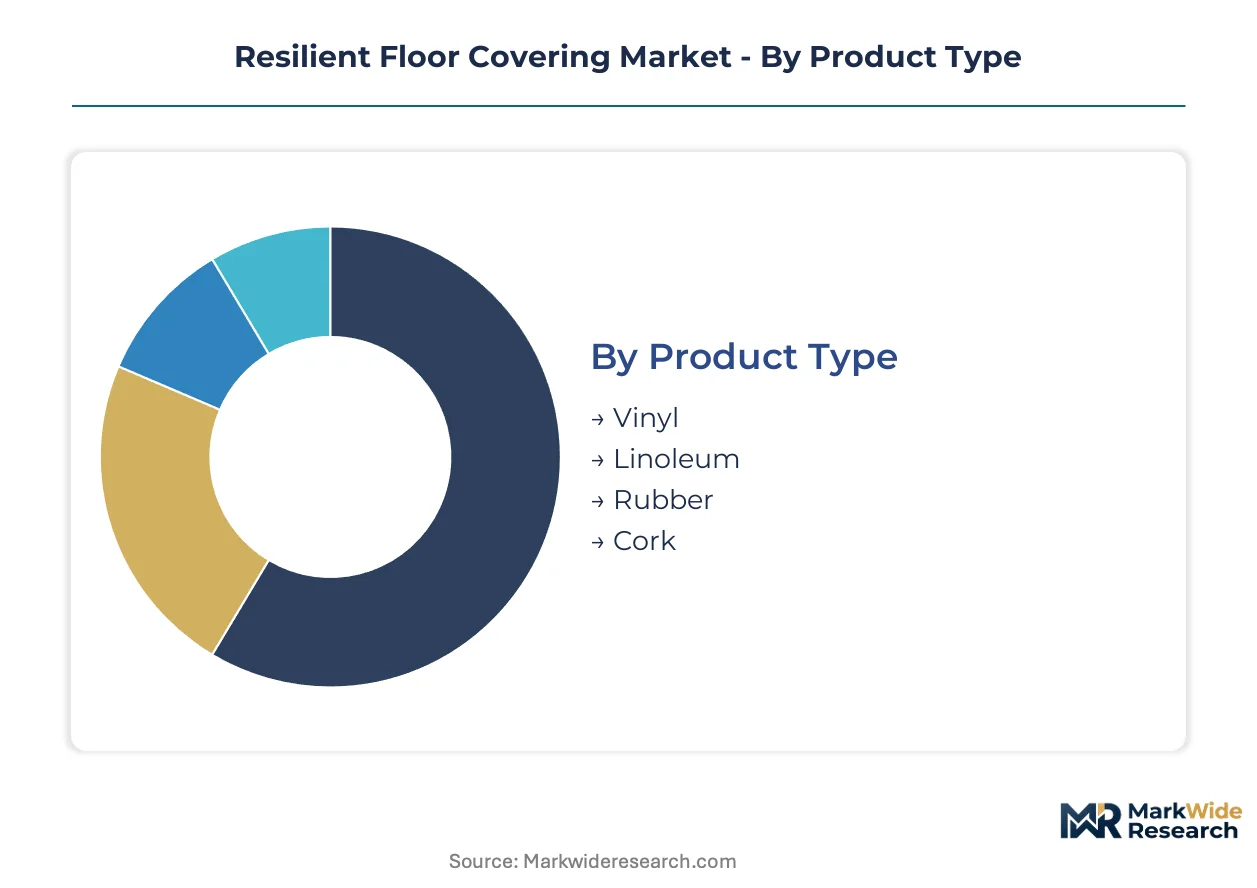
Resilient flooring procurement divides across material chemistry, building typology, installation methodology, and specification authority. Each dimension carries distinct margin profiles, certification requirements, and channel access rules that determine competitive positioning.
Product Type:
Standardization dominates vinyl formulations while rubber and cork require project-specific customization for performance thresholds.
- Vinyl:PVC-based systems with wear-layer coatings and printed decorative films deliver 10-20 year commercial service life. Demand concentrates in United States healthcare networks where CARB Phase II compliance functions as a tender gate; Shaw Industries and Mohawk Industries compete on recycled-content specifications for LEED-targeted hospital retrofits.
- Rubber:Polymer-bound natural and synthetic compounds engineered for impact absorption and static control. European operating theaters and clean rooms specify these surfaces under ECHA phthalate restrictions; Tarkett S.A. anchors supply through specialized formulations for infection-control environments.
- Linoleum:Bio-based composition of linseed oil, cork dust, and wood flour on jute backing. German and Dutch public procurement tenders favor these systems for circular-economy compliance.
- Cork:Harvested bark aggregate with polyurethane or acrylic binders. Portuguese and Spanish manufacturers supply acoustic underlayment and finished surfaces for premium residential applications in France and Italy.
Leading the category by volume: Vinyl. Expanding most quickly: Rubber in healthcare specifications.
Application:
Margin pools shift toward retrofit activity as new construction cycles lengthen and building owners prioritize operational continuity.
- Residential:Single-family and multi-family installations favor floating LVT systems for rapid turnaround. China's tier-one cities drive replacement cycles in high-rise stock.
- Commercial:Office, retail, and hospitality retrofits specify modular click-lock products to enable phased occupancy. National account procurement structures now bypass traditional distributor relationships for multi-site rollouts.
- Industrial:Manufacturing and warehouse floors demand static-dissipative rubber or heavy-gauge vinyl with enhanced chemical resistance.
- Institutional:Schools, government buildings, and transportation hubs require slip-resistant surfaces with extended warranty terms; public tenders mandate third-party certification.
Commercial applications generate the highest value per square meter. Institutional specifications are climbing fastest on healthcare construction mandates.
Installation Type:
Labor cost differentials and substrate condition dictate method selection across project types.
- Glue-Down:Full-spread adhesive bonding for permanent commercial installations. Skilled trade hour requirements and solvent-based adhesive incompatibility with low-emission substrates create retrofit cost overruns.
- Floating:Underlayment-cushioned systems without perimeter attachment. Residential renovation contractors favor these for speed and reversibility.
- Interlocking:Click-lock edge profiles enabling rapid room turnover. Healthcare facility maintenance teams specify these for infection-control renovations requiring minimal downtime.
- Sheet:Heat-welded seams for seamless moisture barriers. Wet environments in senior-living and acute-care facilities require these systems for fall-prevention protocols.
Interlocking systems are gaining share fastest in healthcare verticals. Glue-down remains the volume leader in permanent commercial specifications.
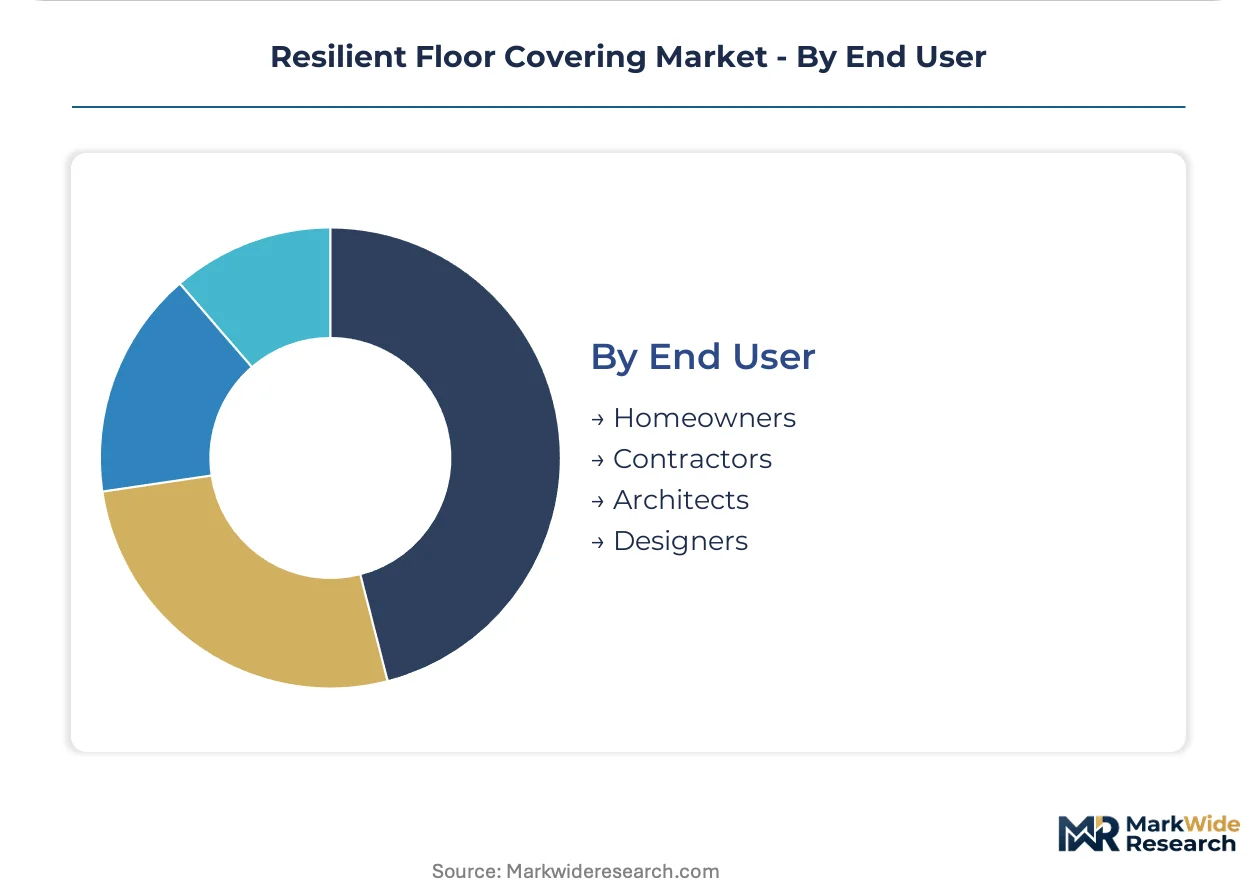
End User:
Specification authority concentrates with professional intermediaries while procurement influence fragments across project stakeholders.
- Homeowners:Direct retail purchases through big-box and specialty flooring channels. Visual sampling and price transparency drive selection; warranty terms influence final commitment.
- Contractors:Installation firms with material-plus-labor contracts negotiate volume rebates and preferred access to technical support. Their influence peaks in residential and light commercial segments.
- Architects:Design-phase specification authority over commercial and institutional projects. BIM library integration and real-time carbon footprint data now determine manufacturer inclusion in shortlists.
- Designers:Interior design consultants curating aesthetic and performance requirements for hospitality and corporate clients. Their selections flow through to national account procurement structures.
Architects control the highest-value specifications. Contractors represent the largest transaction volume by project count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in China's Yangtze River Delta and Pearl River Delta concentrate vinyl compounding capacity, while India's special economic zones in Gujarat and Maharashtra attract flooring manufacturers seeking export duty advantages.
United States
Healthcare construction mandates in Texas and Florida drive antimicrobial surface specifications for hospital networks. CARB Phase II compliance thresholds in California exclude non-certified products from public tenders, tightening West Coast market access. Manufacturing clusters in Georgia and Alabama supply vinyl sheet and LVT systems for national distribution.
China
Tier-one cities including Shanghai, Beijing, and Shenzhen accelerate commercial renovation cycles in high-rise office stock. GB standards under MEE oversight constrain VOC emissions and phthalate content in domestic production. Virgin PVC production concentrates in Sichuan and Shandong provinces, feeding compounding facilities in the Yangtze River Delta.
Germany
Public procurement tenders in Berlin and Hamburg favor linoleum and bio-based compositions for circular-economy compliance. REACH chemical restrictions under ECHA oversight force formulation innovation toward bio-based plasticizers. Industrial clusters in North Rhine-Westphalia anchor rubber flooring production for European operating theaters and clean rooms.
India
Bangalore and Mumbai office stock expansion creates demand for cost-competitive resilient systems in commercial real estate. BIS certification requirements and state-level building codes constrain imported product specifications. Manufacturing partnerships in Gujarat special economic zones reduce import duty exposure for multinational suppliers.
France
Healthcare facility retrofits in Paris and Lyon specify slip-resistant surfaces for senior-living fall-prevention protocols. EU Green Deal circular mandates and extended producer responsibility rules under ANSM oversight reshape end-of-life disposal requirements. Lyon-based manufacturing anchors specialized rubber formulations for infection-control environments.
Resilient Floor Covering Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated scale players dominating institutional procurement while regional fabricators capture residential retrofit volume. The market structure tiers across three strategic archetypes: diversified building-material conglomerates with captive resin supply, specialized flooring pure-plays with formulation expertise, and private-label assemblers serving price-sensitive channels. Dominant competitive moves include backward integration into PVC resin production and strategic partnerships with healthcare network procurement consortia.
Among diversified material conglomerates, Mohawk Industries and Shaw Industries Group occupy positions defined by manufacturing scale and recycled-content technology leadership. Tarkett S.A. exemplifies the specialized pure-play archetype, anchoring European supply through rubber flooring expertise. These three entities represent the competitive spectrum from volume-driven vinyl systems to premium institutional specifications, with each sitting within distinct margin pools shaped by certification requirements and specification authority.
| Leading Market Players |
|---|
| Mohawk Industries |
| Tarkett S.A. |
| Shaw Industries Group |
| Armstrong Flooring |
| Forbo Flooring Systems |
| Gerflor |
| Interface |
| Mannington Mills |
| Beaulieu International Group |
| Others |
Value Network & Pricing Analysis
Captive resin production in Sichuan and Shandong provinces anchors supply positioning for vinyl compounders while simultaneously constraining pricing flexibility for non-integrated manufacturers facing PVC feedstock volatility. This upstream control creates divergent margin structures between conglomerates with in-house chlor-alkali operations and assemblers exposed to spot resin markets.
Pricing Analysis
Short lead-time premiums compress standard pricing bands as healthcare facility maintenance teams demand rapid-turnaround inventory for infection-control renovations. Three-tier pricing structure across premium, standard, and economy levels separates CARB Phase II certified systems from general commercial grades and spot-imported alternatives. Price differentiation hinges on certification tier and volume scale, with national account procurement extracting double-digit discounts against list pricing. Margins are tightening due to ethylene feedstock volatility and energy rationing risks in Chinese production clusters. Contractors represent the most price-sensitive segment, while architects specifying LEED-targeted projects demonstrate lowest sensitivity.
Supply Chain Analysis
Dual-sourcing mandates from United States hospital network procurement consortia require qualified backup suppliers for critical flooring specifications, forcing manufacturers to maintain redundant compounding relationships. Geographic supply concentrates in China, Germany, and the United States, with virgin PVC resin drawing from Sichuan and Shandong production bases. Raw material dependencies center on ethylene, chlorine, and plasticizer additives, with bio-based alternatives gaining share under REACH constraints. Single-source vulnerability persists in specialized rubber formulations for European operating theaters. Distribution runs through manufacturer-direct national accounts and regional distributor networks serving contractor installation firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where CARB Phase II certification creates a barrier-to-entry moat that rewards pre-qualified incumbents while excluding reformulation-lagged competitors from public procurement tenders.
For Market Incumbents: Anchor market position through backward integration into PVC resin production and closed-loop collection infrastructure for recycled-content specifications. Defensive consolidation should target regional fabricators with established healthcare network relationships. Threat from modular click-lock LVT systems displacing traditional glue-down specifications demands R&D investment in rapid-installation product architectures. For New Entrants and Emerging Players: Enter via white-space targeting of India's commercial real estate expansion in Bangalore and Mumbai, where BIS certification requirements favor local manufacturing partnerships over import-dependent models. The most penetrable segment lies in cost-competitive floating LVT systems for residential renovation contractors. Go-to-market positioning should emphasize digital specification platform integration with BIM library compatibility and real-time carbon footprint metrics. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified building-material conglomerates seeking formulation expertise and healthcare procurement relationships. Long-term viability favors specialized flooring pure-plays with REACH and CARB compliance infrastructure over private-label assemblers exposed to commodity margin compression. Signal to watch: extended producer responsibility rule implementation under EU Green Deal circular mandates, which will force consolidation among take-back program operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVC Resin | Captive chlor-alkali supply in Sichuan insulates margins from ethylene volatility. |
| Closed-Loop Collection Infrastructure | Post-consumer vinyl recovery networks satisfy LEED recycled-content specifications. |
| Digital Specification Platform Integration | BIM library embedding captures architect attention at healthcare design stage. |
| Local Manufacturing Partnerships in India | Gujarat special economic zone facilities reduce BIS certification timeline exposure. |
| Take-Back Program Development | Extended producer responsibility compliance creates first-mover advantage in EU tenders. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant managers at compounding facilities, procurement leads at hospital network GPOs, distribution channel partners, and technical R&D directors specializing in low-VOC polymer formulations. Secondary validation drew from CARB certification databases, EPA emissions disclosures, ECHA restriction lists, and Chinese customs import records. Bottom-up volume modeling triangulated against top-down construction spending forecasts.
Granularity-level modeling disaggregated volume and value across material chemistry, building typology, installation methodology, and specification authority dimensions throughout the forecast period. CAGRs derived from regression analysis against healthcare construction spending, commercial renovation cycle frequencies, and regulatory compliance timeline assumptions. Industry-specific inputs included hospital procurement database analysis and architect specification survey data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical price spike conditions or accelerated REACH chemical restriction timelines. Forecasts reflect documented assumptions on regulatory enforcement intensity and circular-economy mandate implementation schedules. Deviation in Chinese energy rationing policy or PVC resin export controls would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
Wooden Floor Market
Flooring, Carpets, and Rugs
Germany Floor Covering Market
Flooring, Carpets, and Rugs
Europe Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
Flooring Wood Panels Market
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
Saudi Arabia Floor Covering Market
Flooring, Carpets, and Rugs
Europe Vinyl Flooring Market
Flooring, Carpets, and Rugs
Global Commercial Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
Europe Floor Covering Market
Flooring, Carpets, and Rugs
US Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
US Terrazzo Market
Flooring, Carpets, and Rugs
Europe Carpet Tile Market