
 United Kingdom Non-Resilient Floor Covering Market | 2026-2036
United Kingdom Non-Resilient Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Non-Resilient Floor Covering Market Analytics
The UK non-resilient floor covering market is recalibrating as premium porcelain and engineered stone products pull away from commodity vinyl and basic laminate in both price positioning and specification channels. Mohawk Industries leverages its integrated global manufacturing base to sustain cost discipline across ceramic and laminate portfolios in British distribution. Tarkett Ltd anchors its position through specialized healthcare and education sector flooring systems that navigate stringent performance requirements. Victoria PLC dominates mid-market residential renovation with vertically controlled UK production that competes aggressively on lead times and custom runs.
Non-resilient floor coverings comprise rigid surfacing materials including ceramic tile, porcelain, natural stone, laminate, and vinyl products that lack significant elastic deformation under load, typically manufactured through firing, high-pressure lamination, or extrusion processes with wear-layer ratings exceeding AC3 for commercial applications. The primary purpose spans aesthetic finish, structural protection, and hygienic maintenance across built environments. Tile and stone occupy the premium margin pool where specification architects control project value, while vinyl and laminate extend volume reach through retail and wholesale channels serving residential replacement cycles. The hospitality end user segment is shifting toward large-format porcelain that reduces grout maintenance in high-traffic public areas.
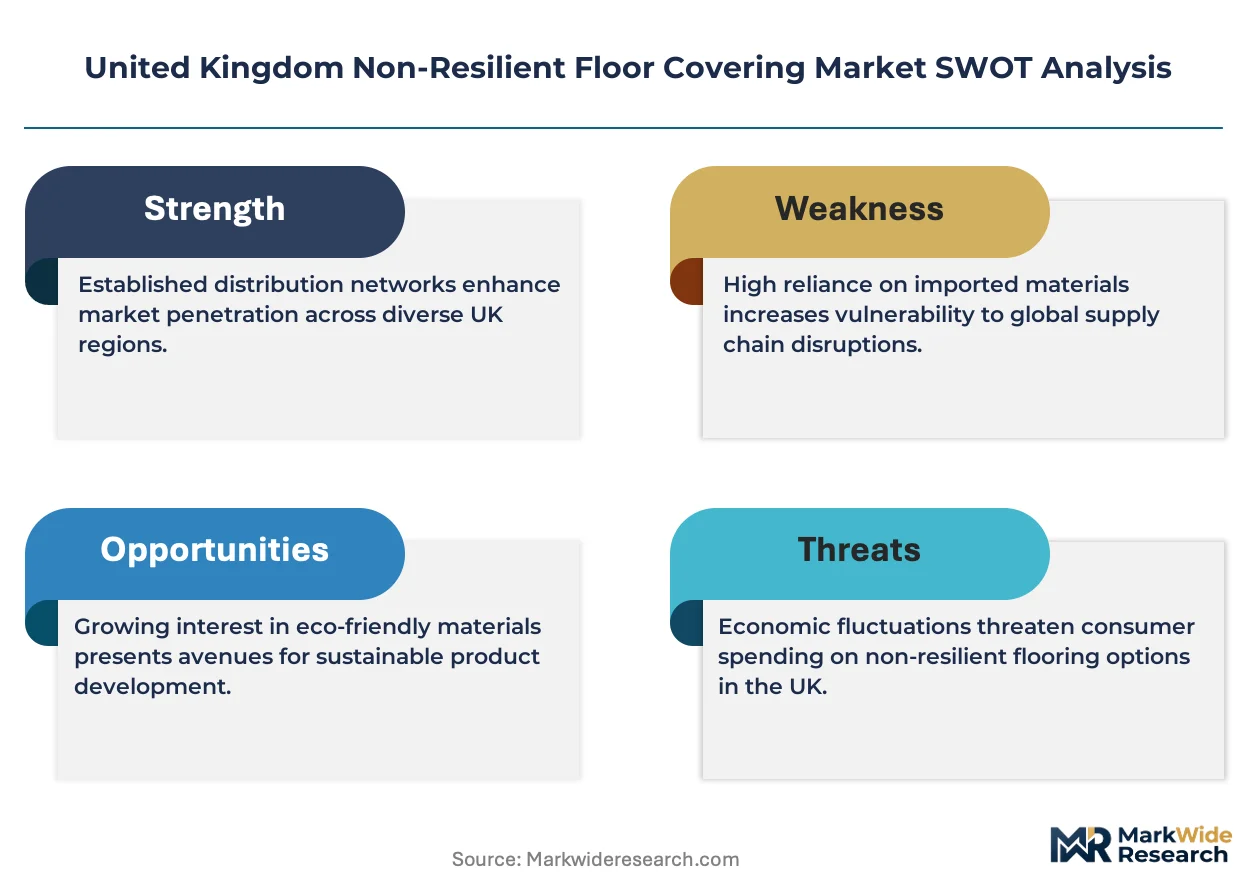
UK Building Regulations Part L and the Construction Products Regulation framework shape material thermal performance and slip-resistance standards that manufacturers must satisfy for market access. BSI certification and CE marking requirements under the UKCA transition enforce consistent quality testing that filters lower-grade imports from European and Asian suppliers. Specifiers and procurement teams must monitor evolving fire safety classifications under the Building Safety Regulator's consolidated oversight, as post-Grenfell enforcement tightens combustibility limits across commercial and institutional installations.
Market Dynamics
UK Building Regulations Part L thermal efficiency standards are compressing substrate thickness specifications while redirecting demand toward thermally conductive porcelain and engineered stone surfaces that satisfy stricter U-value calculations.
Growth Catalysts
- Part L Compliance Mandate:The updated UK Building Regulations Part L framework mandates improved thermal performance in flooring assemblies, accelerating specification of thinner, high-conductivity porcelain tiles in residential new-build and deep-retrofit projects.
- Healthcare Infrastructure Renewal:NHS estate modernization programmes are expanding demand for hygienic, slip-resistant non-resilient surfaces in acute care facilities, with infection-control specifications favoring large-format ceramic and stone over traditional vinyl sheet.
- London Commercial Refurbishment Cycle:Grade A office stock in the City and Canary Wharf is undergoing accelerated refresh cycles, driving replacement demand for premium stone and porcelain in reception, amenity, and circulation areas.
Market Restraints
- Energy Input Cost Volatility:Natural gas price fluctuations directly impact ceramic kiln and stone processing economics, compressing margins for UK-based manufacturers dependent on continuous firing operations.
- Asian Import Concentration:Substantial supply of commodity-grade porcelain and ceramic tile originates from concentrated manufacturing clusters in China and India, exposing distributors to shipping rate volatility and extended lead-time risk.
- UKCA Transition Friction:Ongoing divergence between UKCA marking requirements and retained EU CE standards creates dual certification burdens for European suppliers, slowing product registration and market entry timelines.
Strategic Opportunities
- Scotland Retrofit Pipeline:The Scottish Government's Heat in Buildings Strategy targets net-zero public housing stock by 2045, creating sustained demand for thermally efficient flooring systems in social housing renovation programmes.
- Biophilic Material Convergence:Integration of recycled content certification with natural stone aesthetics opens specification pathways in corporate wellness-focused commercial interiors seeking WELL Building Standard compliance.
- Direct-to-Specifier Digital Platforms:Emerging B2B procurement channels connecting architects and quantity surveyors to manufacturer technical data are compressing traditional merchant distribution layers in commercial project workflows.
Industry Challenges
- Technical Specification Skill Shortage:Declining numbers of qualified architectural technologists proficient in substrate compatibility and thermal bridging calculations are elongating pre-tender design phases.
- UKCA Testing Backlog:Limited UKAS-accredited laboratory capacity for fire performance and slip-resistance testing is extending product approval timelines, delaying project commencement and revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Non-Resilient Floor Covering Market |
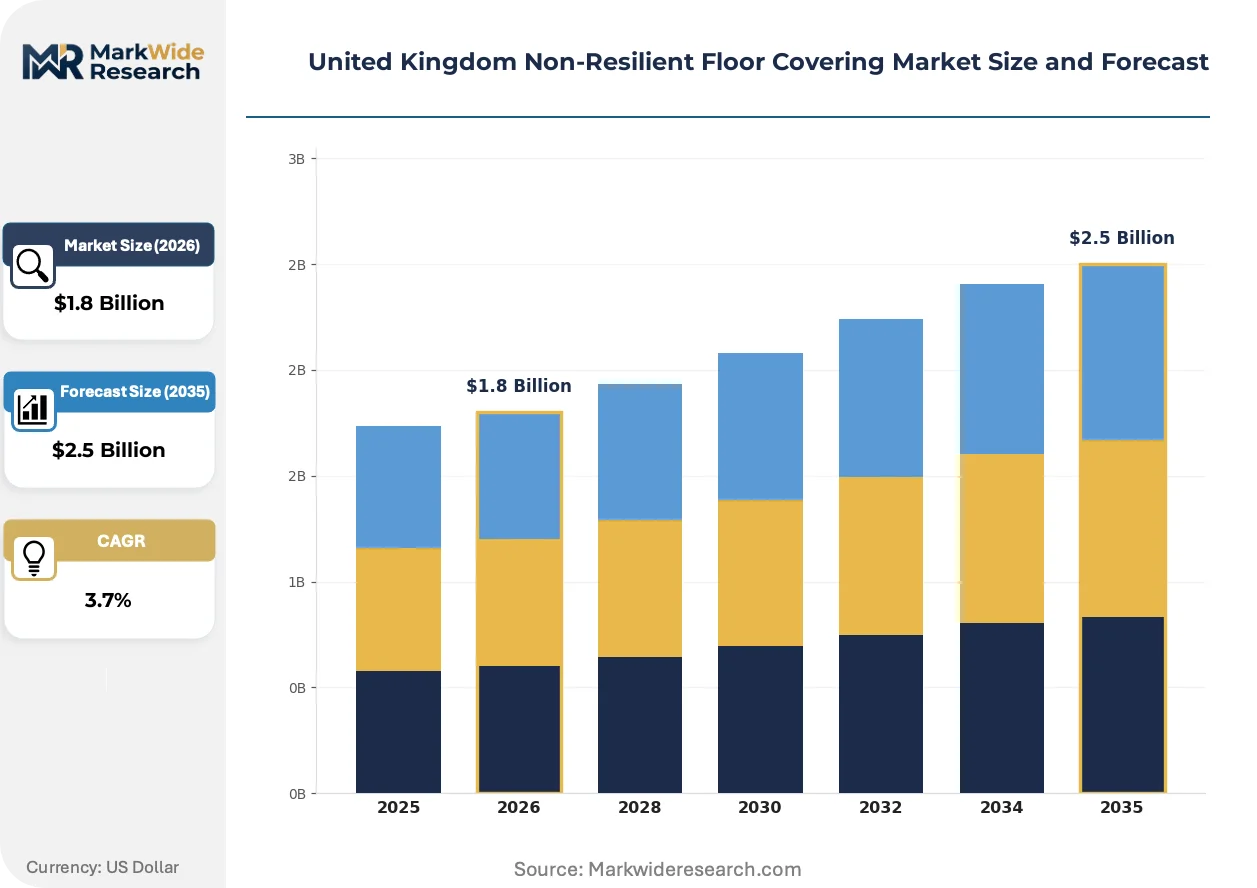
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tile, Laminate, Vinyl, Stone End User: Residential, Commercial, Hospitality, Institutional Installation Type: Glue-down, Floating, Nail-down, Interlocking Distribution Channel: Direct Sales, Retail Stores, Online, Wholesalers |
| Companies Covered | Mohawk Industries Inc, Shaw Industries, Tarkett Ltd, Porcelanosa Grupo, Ceramica Saloni, Marazzi, Victoria PLC, RAK Ceramics, Original Style, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Non-Resilient Floor Covering Market Evolving Landscape
Digital manufacturing and regulatory compression are converging to redefine product development cycles, specification workflows, and competitive positioning across British flooring supply chains.
Thin-format large porcelain slabs with integrated underfloor heating compatibility are overtaking traditional thick-bed stone installations in premium residential and hospitality segments. High-end developers in Manchester and Birmingham are specifying these systems to achieve Part L thermal targets without sacrificing aesthetic depth. The technology is compressing demand for natural stone quarried outside the UK by delivering comparable visual performance with superior thermal conductivity and reduced structural load.
UK Building Regulations Part L 2021 conservation of fuel and power standards are tightening allowable U-values for ground-floor assemblies. Flooring manufacturers must now supply lambda-rated substrates and thermal bridging calculations as standard documentation for building control approval. Commercial specifiers in the South East are responding by consolidating procurement around suppliers with pre-certified system warranties that de-risk compliance verification.
Architects and interior designers are consolidating specification authority through direct engagement with manufacturer technical teams, bypassing traditional merchant intermediaries. Merchant distributors serving the residential RMI channel are losing margin to digital platforms and manufacturer-owned showrooms in Greater London. This disintermediation is most visible in the luxury residential segment, where developers commission bespoke porcelain and stone runs directly from Italian and Spanish producers with UK logistics partnerships.
United Kingdom Non-Resilient Floor Covering Market Segmentation
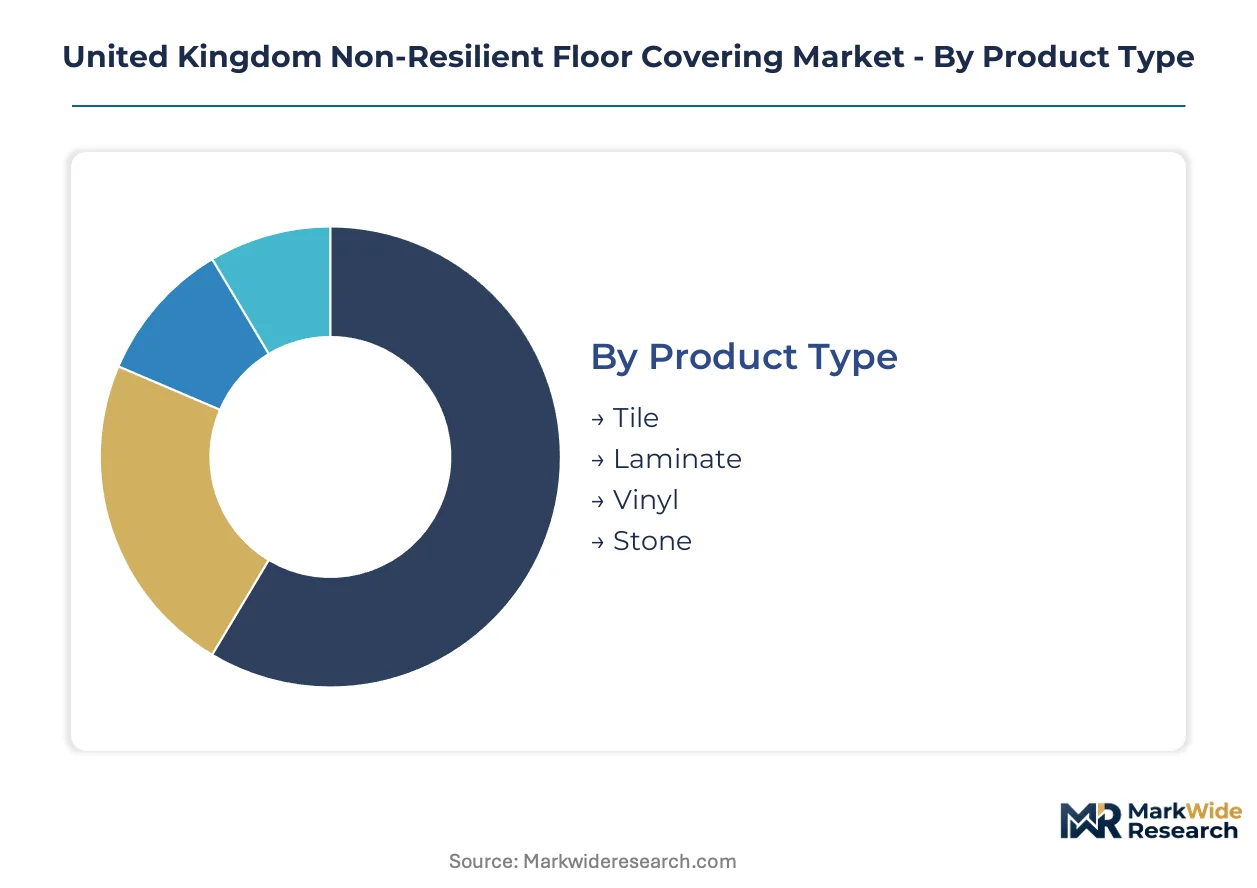
Segmentation in the UK non-resilient floor covering market reveals how certification requirements, installation complexity, and channel economics partition demand across distinct customer workflows. Understanding these divisions helps manufacturers align product development with the specific compliance and performance thresholds governing each application context.
Product Type:
UKCA marking and BSI certification burdens fall unevenly across material categories, with ceramic and stone products facing the most intensive fire-safety and slip-resistance testing regimes under the Building Safety Regulator's consolidated oversight.
- Tile:Porcelain and ceramic products manufactured through high-temperature firing deliver superior thermal conductivity for Part L compliance. Demand concentrates in Greater London commercial refurbishment, where Grade A office developers specify large-format thin slabs to reduce grout maintenance in high-traffic circulation areas.
- Laminate:High-pressure laminated fiberboard with AC3+ wear ratings serves residential renovation cycles through retail channels. The South East dominates volume as homeowners prioritize rapid installation and cost-efficient refresh of existing subfloors without structural modification.
- Vinyl:LVT and SPC rigid core products offer water resistance and acoustic dampening for healthcare and education specifications. NHS estate modernization programmes favor these surfaces for infection control in acute care environments.
- Stone:Natural and engineered stone surfaces command premium positioning in luxury residential and hospitality segments. Manchester and Birmingham high-end developers specify these for aesthetic depth despite higher structural load and thermal mass challenges.
Tile sits at the top of the volume ranking, with vinyl climbing the fastest as healthcare infrastructure renewal accelerates specification of hygienic, slip-resistant alternatives to traditional sheet flooring.
End User:
Customer type determines specification authority, procurement cycle length, and warranty complexity, with institutional buyers demanding extended system guarantees that residential channels rarely require.
- Residential:Individual homeowners and buy-to-let investors drive replacement demand through merchant retail and online channels. The South East and Greater London concentrate activity as property transactions trigger renovation spending.
- Commercial:Corporate office and retail fit-out projects in the City and Canary Wharf specify premium stone and porcelain through direct manufacturer relationships. Grade A stock refurbishment cycles compress decision timelines and consolidate procurement around pre-certified system warranties.
- Hospitality:Hotels, restaurants, and leisure venues prioritize large-format porcelain for reduced grout maintenance in public areas. Biophilic design trends favor stone aesthetics with recycled content certification for WELL Building Standard compliance.
- Institutional:NHS, education, and government estate programmes mandate rigorous slip-resistance and fire-performance documentation. Scottish Government Heat in Buildings Strategy targets create sustained demand for thermally efficient flooring in social housing retrofit.
Residential commands the largest revenue base, with institutional expanding most quickly as public sector estate modernization programmes accelerate procurement of certified hygienic surfaces.
Installation Type:
Substrate preparation and skill requirements vary dramatically, with glue-down and floating systems dominating as nail-down methods retreat in response to concrete slab prevalence in new construction.
- Glue-down:Direct adhesion to prepared subfloors delivers maximum stability for heavy commercial traffic and underfloor heating compatibility. London commercial refurbishment specifies these systems for reception and amenity areas where dimensional stability is critical.
- Floating:Click-lock and loose-lay systems enable rapid installation over existing substrates without adhesive curing time. Residential renovation in the South East favors these for minimized disruption and DIY accessibility.
- Nail-down:Mechanical fastening to timber subfloors persists in heritage property restoration and solid wood overlay applications. Declining new timber construction limits growth to specialized conservation projects.
- Interlocking:Rigid SPC and LVT systems with integrated locking profiles serve healthcare and education rapid-installation requirements. NHS facilities management teams specify these for minimized downtime in operational clinical environments.
Floating installations represent the highest volume segment, with glue-down gaining share fastest as Part L thermal efficiency standards drive specification of integrated underfloor heating systems requiring maximum substrate contact.
Distribution Channel:
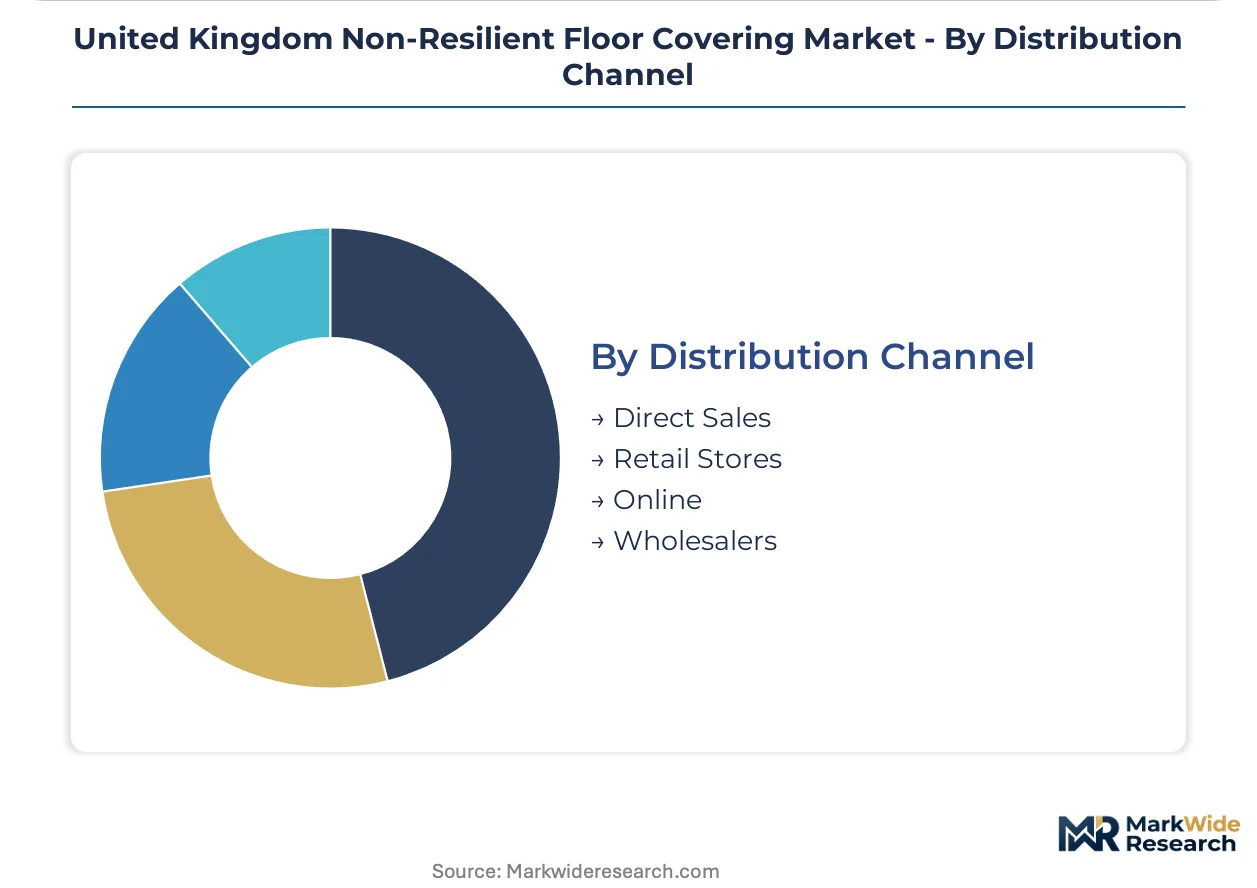
Channel economics are compressing as digital platforms and manufacturer direct engagement disintermediate traditional merchant layers, particularly in specification-driven commercial segments.
- Direct Sales:Manufacturer technical teams engage architects and quantity surveyors for complex commercial and institutional projects. This channel captures the highest margin transactions through bespoke production runs and system warranty bundling.
- Retail Stores:Merchant showrooms and DIY superstores serve residential replacement cycles with stocked inventory and immediate availability. Greater London concentration supports premium positioning through experience center formats.
- Online:Digital procurement platforms connect specifiers to technical documentation and sample ordering, compressing traditional distribution layers. Emerging B2B channels target quantity surveyors with automated specification tools.
- Wholesalers:Regional distributors stock commodity-grade laminate and vinyl for contractor bulk purchase and rapid project fulfillment. Price-sensitive residential new-build segments depend on these channels for volume procurement.
Retail stores maintain volume leadership, with direct sales expanding most quickly as architects consolidate specification authority through manufacturer technical partnerships that bypass merchant intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scotland's social housing retrofit pipeline diverges sharply from England's commercial refurbishment focus, with divergent regulatory timelines reshaping specification priorities across British sub-markets.
Greater London and the South East
Grade A office stock in the City and Canary Wharf drives premium porcelain and engineered stone demand through accelerated refresh cycles. UK Building Regulations Part L thermal efficiency standards compress substrate specifications in new-build residential towers. Developer activity concentrates in Nine Elms and Stratford regeneration zones where large-format thin slabs reduce structural load.
Midlands
Manchester and Birmingham high-end residential schemes specify stone aesthetics despite thermal mass challenges. The Heat in Buildings Strategy influences social housing procurement patterns across the West Midlands. Manufacturing clusters around Stoke-on-Trent retain ceramic production capacity serving domestic renovation channels.
Scotland
The Scottish Government's 2045 net-zero public housing target sustains demand for thermally efficient flooring systems in social housing retrofit. NHS Scotland estate modernization accelerates specification of hygienic, slip-resistant surfaces in acute care facilities. Glasgow and Edinburgh concentrate procurement authority for institutional programmes.
North England
Heritage property restoration in Yorkshire and Lancashire sustains niche demand for traditional stone and ceramic formats. Residential renovation cycles lag southern counterparts but show acceleration in Leeds and Newcastle buy-to-let markets. Merchant distribution networks maintain stronger regional presence than in London.
Wales
Social housing stock condition programmes drive volume procurement of cost-efficient laminate and vinyl through Welsh procurement frameworks. Building control authorities enforce UKCA marking compliance with limited local testing capacity. Cardiff and Newport concentrate commercial refurbishment activity.
United Kingdom Non-Resilient Floor Covering Market Competitive Landscape
Top-tier vendors anchor specification-driven commercial and institutional channels, while mid-market specialists compete on lead times and custom production runs for residential renovation. The vendor base stratifies across integrated global manufacturers, regional production specialists, and import-dependent distributors serving price-sensitive segments. Three archetypes dominate: vertically controlled UK producers, integrated multinational suppliers with captive raw material access, and European specialist brands leveraging design authority. Competitive moves concentrate on direct-to-specifier digital platform development and pre-certified system warranty bundling that de-risks Part L compliance verification.
Within the multinational tier, Mohawk Industries Inc and Shaw Industries exemplify scale-driven supply chain architectures. Tarkett Ltd occupies a position bridging healthcare specialization with institutional procurement relationships. Victoria PLC represents the vertically integrated domestic archetype with UK-based production control.
| Leading Market Players |
|---|
| Mohawk Industries Inc |
| Shaw Industries |
| Tarkett Ltd |
| Porcelanosa Grupo |
| Ceramica Saloni |
| Marazzi |
| Victoria PLC |
| RAK Ceramics |
| Original Style |
| Others |
Value Network & Pricing Analysis
Part L thermal efficiency mandates are compressing substrate specifications and forcing procurement teams toward thinner, high-conductivity porcelain systems that carry premium positioning. Supply must reconfigure around UKAS-accredited testing capacity and certified system warranties, elevating price floors for compliant products while squeezing margin on legacy inventory.
Pricing Analysis
Capacity additions in Spain and Italy are reshaping price floors for large-format porcelain slabs entering British distribution. Three-tier pricing structure across premium, standard, and economy levels separates architect-specified bespoke runs from merchant-stocked commodity tile. Cost compression in the laminate tier is intensifying because Asian fiberboard supply feeds aggressive retail positioning. Social housing procurement teams exhibit highest price sensitivity, while Grade A commercial developers prioritize thermal performance certification over unit cost.
Supply Chain Analysis
Skilled kiln operator shortages in Stoke-on-Trent and ceramic technician deficits across Spanish production zones are constraining domestic and near-shore capacity expansion. Manufacturing gravity centers on China, India, and Italy for commodity porcelain, with Spain and Turkey supplying mid-market engineered stone. Raw material dependencies span kaolin clay, feldspar, and titanium dioxide for wear-layer formulations. Single-source vulnerability concentrates in natural gas feedstock for continuous firing operations. Distribution runs through merchant networks for residential renovation, with direct manufacturer engagement capturing specification-driven commercial flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where UK Building Regulations Part L thermal efficiency standards continuously elevate compliance thresholds and redirect specification value toward certified system suppliers.
For Market Incumbents: Lock in specification authority by embedding thermal bridging calculation tools directly into architect-facing digital platforms. Cement backward integration into UKAS-accredited testing capacity to compress approval timelines against competitors dependent on bottlenecked third-party laboratories. Defend against disintermediation by merchant-bypassing direct procurement channels through exclusive system warranty bundling that de-risks Part L compliance verification for quantity surveyors. For New Entrants and Emerging Players: Capture the Scottish social housing retrofit pipeline where Heat in Buildings Strategy targets create sustained demand for thermally efficient flooring systems with compressed competitor presence. Exploit whitespace in digital B2B procurement platforms connecting NHS facilities managers to infection-control surface specifications with integrated slip-resistance documentation. Lead with rapid-install interlocking systems that minimize operational downtime in acute care environments. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically controlled UK producers possessing captive kiln capacity and direct specification relationships bypassing merchant intermediaries. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than commodity scale. Monitor UKCA transition friction as the critical inflection signal—accelerated divergence from retained EU CE standards favors domestic testing investments over import-dependent distribution models.| Strategic Initiative | Industry Significance |
|---|---|
| UKAS-Accredited Testing Capacity Expansion | Compresses product approval timelines against competitors bottlenecked at limited laboratory infrastructure. |
| Direct-to-Specifier Digital Platform Development | Bypasses merchant margin extraction by embedding thermal calculation tools in architect workflows. |
| Pre-Certified System Warranty Bundling | De-risks Part L compliance verification for quantity surveyors consolidating procurement authority. |
| Scotland Social Housing Retrofit Specialization | Captures institutional demand from Heat in Buildings Strategy targets with limited incumbent saturation. |
| Thin-Format Large Slab Manufacturing Scale-Up | Addresses Part L substrate compression mandates while displacing natural stone in premium segments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with ceramic plant managers, specification architects, NHS estates procurement leads, merchant category buyers, and building control officers with secondary validation against UK Building Regulations documentation, BSI certification records, MHCLG policy releases, and trade flow data from HMRC import statistics. Bottom-up volume modeling across product tiers triangulated against top-down sector spend analysis.
Segment-weighting distributed value and volume across tile, laminate, vinyl, and stone product categories, further disaggregated by residential, commercial, hospitality, and institutional end-user channels. Installation type and distribution channel dimensions refined the analytical framework across the projection horizon. CAGRs derived from trend extrapolation of renovation cycle intensity, regulatory compliance cost trajectories, and healthcare infrastructure renewal programme commitments.
Regulatory implementation delays, natural gas price volatility, and UKCA testing capacity constraints are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding Part L enforcement timelines and Scottish Government retrofit funding continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Asia Pacific Flooring Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
United States Commercial Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
India Carpets and Rugs Market
Flooring, Carpets, and Rugs
Bamboo Flooring Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
Wood Plastic Composite (WPC) Floorings Market
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
Egypt Floor Covering Market
Flooring, Carpets, and Rugs
Textured Variegates Market
Flooring, Carpets, and Rugs
Middle East Flooring and Carpet Market
Flooring, Carpets, and Rugs
GCC Flooring Market
Flooring, Carpets, and Rugs
Canada Terrazzo Flooring Market