
 Bamboo Flooring Market | 2026-2036
Bamboo Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Bamboo Flooring Market Analysis
Buyer fragmentation across boutique hospitality developers and eco-conscious residential renovators is repositioning procurement patterns toward certified sustainable suppliers. Moso International anchors European distribution through controlled warehouse networks in the Netherlands. Dasso Group leverages vertical integration from plantation to finished plank to sustain margin stability. Cali Bamboo differentiates through reclaimed-content blends aimed at LEED-driven commercial specifiers.
Bamboo flooring consists of laminated strips or strand-woven fibers of giant grass culms, typically finished with aluminum oxide coatings for hardness ratings exceeding traditional oak. The material serves commercial and residential spaces requiring rapid-renewable certification under green building codes. Strand woven product types command premium positioning due to density levels approaching 3,000 psi on the Janka scale. Residential application segments dominate volume flows, though commercial installations in co-working spaces are expanding fastest. Click lock installation methods are displacing glue-down systems in North American retrofit markets due to labor cost pressures.
China's SAMR enforces GB standards for formaldehyde release in wood-based panels, directly shaping export eligibility for Anhui Dasuo and Hunan Taohuajiang production facilities. The EU Green Deal and associated ECHA restrictions on volatile organic compounds are redirecting finish chemistry toward water-based matte formulations. Stakeholders must monitor certification divergence between ISO-compliant chain-of-custody documentation and emerging national ecolabel programs before committing to capacity expansion.
Market Dynamics
China's GB standards for formaldehyde emissions are compressing export eligibility windows for wood-based panel producers, forcing certification upgrades across Anhui and Hunan manufacturing zones while redirecting procurement toward ISO-compliant suppliers.
Growth Catalysts
- EU Green Deal implementation:ECHA restrictions on volatile organic compounds are accelerating water-based finish chemistry adoption across European distribution channels.
- Strand-woven density premiums:Janka hardness ratings approaching 3,000 psi are capturing specification from commercial co-working space developers seeking rapid-renewable certification.
- Vietnam export zone concentration:Manufacturing clusters near Ho Chi Minh City are consolidating capacity to serve North American retrofit demand for click-lock installation systems.
Market Restraints
- Input cost volatility:Moso bamboo culm harvesting cycles create raw material availability mismatches with European warehouse replenishment schedules.
- Supply concentration risk:China's SAMR enforcement actions disproportionately impact Anhui Dasuo and Hunan Taohuajiang production facilities.
- Substitution pressure:Engineered hardwood and luxury vinyl plank alternatives compete on installation labor familiarity in North American contractor networks.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Norway building codes are mandating rapid-renewable content thresholds that bamboo flooring satisfies.
- Reclaimed-content blending:Post-industrial fiber integration creates LEED point advantages for commercial specifiers in California and New York.
- Direct-to-renovator platforms:Boutique hospitality developers are bypassing traditional distribution tiers through controlled warehouse networks in the Netherlands.
Industry Challenges
- Certification timeline compression:Divergence between ISO chain-of-custody documentation and emerging national ecolabel programs delays capacity commitment decisions.
- Finish chemistry reconfiguration:Water-based matte formulation transitions require capital equipment replacement at existing coating facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bamboo Flooring Market |
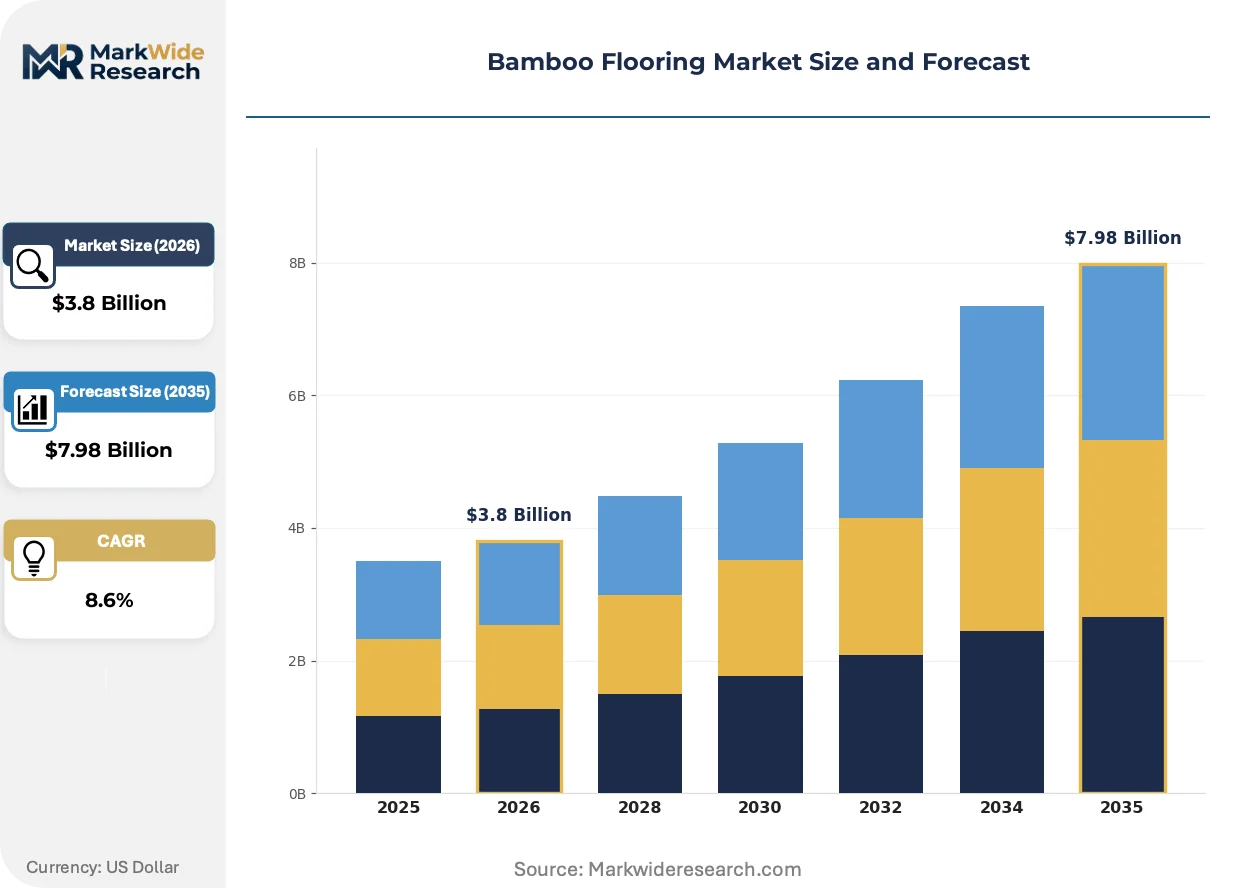
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strand Woven, Horizontal, Vertical, Carbonized Application: Residential, Commercial, Industrial, Outdoor Installation Method: Glue Down, Nail Down, Floating, Click Lock Finish Type: Pre-finished, Unfinished, Oil Finish, Matte Finish |
| Companies Covered | Teragren, Hangzhou Runzhu Technology, Moso International, Anhui Dasuo Bamboo and Wood Technology, Shaoxing Zhonghe Bamboo and Wood Products, Dasso Group, Zhejiang Zhuanghe Bamboo Industry Technology, Hunan Taohuajiang Bamboo Materials Technology, Cali Bamboo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bamboo Flooring Market Emerging Trajectories
Finish chemistry, installation mechanics, and procurement channels are undergoing simultaneous transformation as regulatory pressure and labor cost constraints reshape product specifications.
Aluminum oxide surface coatings are rewriting durability expectations for residential renovation contractors. Boutique hospitality developers specify these finishes for high-traffic lobby areas previously reserved for stone or ceramic. The technology is compressing replacement cycle timelines and expanding bamboo flooring into commercial warranty categories previously closed to grass-based materials.
REACH restrictions on solvent-based formulations are forcing coating chemistry transitions across European supply chains. Industrial finish suppliers are reformulating product lines to maintain CE marking eligibility. Water-based systems now dominate specification for Dutch distribution networks serving German and Belgian renovation markets.
Buyer fragmentation between eco-conscious residential renovators and LEED-driven commercial specifiers is unbundling traditional distribution tiers. Netherlands-based controlled warehouse networks now serve both segments through separate certification documentation streams. This bifurcation is most visible in California and New York procurement patterns where reclaimed-content blends command distinct pricing premiums.
Bamboo Flooring Market Segmentation
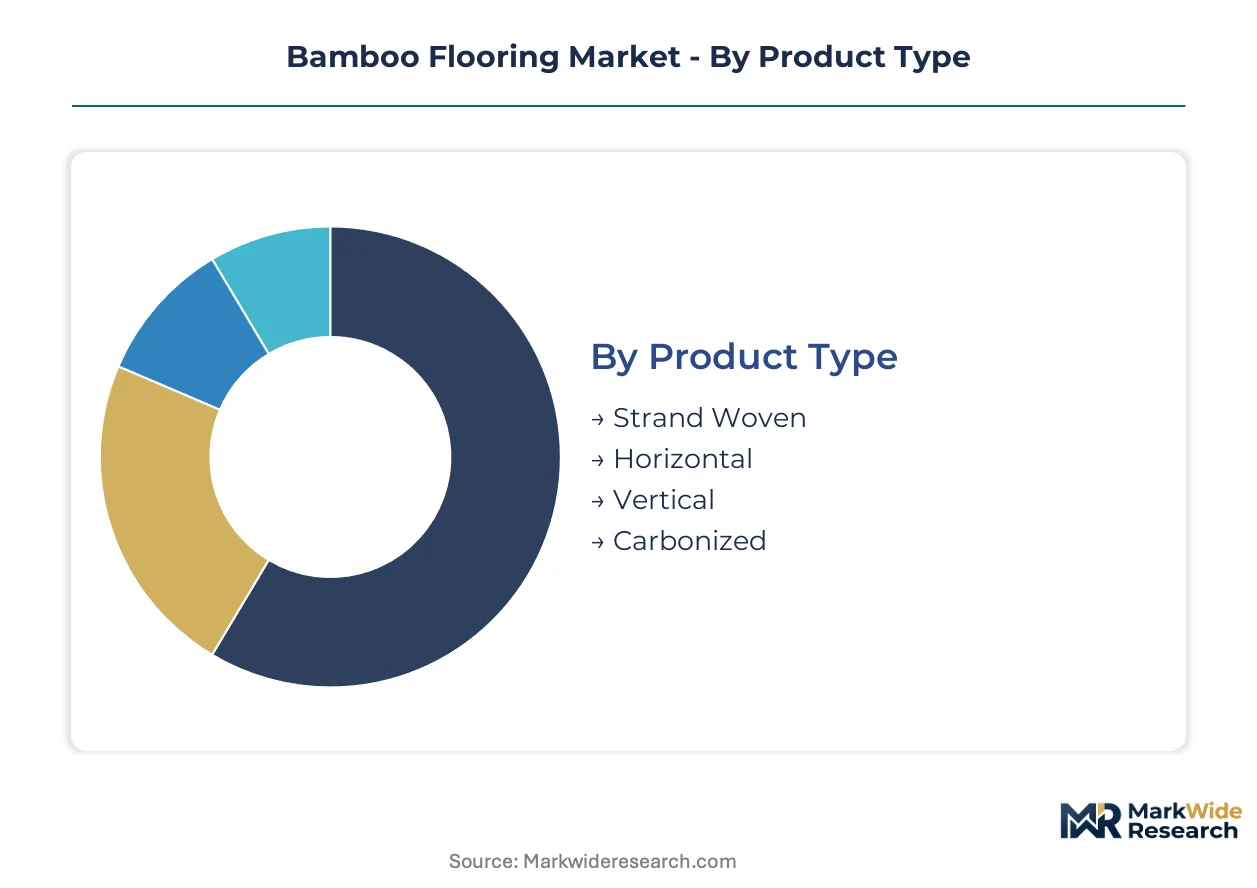
Segmentation in bamboo flooring reflects divergent buyer priorities across durability specifications, installation labor economics, and green certification pathways. Contractors, specifiers, and renovators each weight product attributes differently, creating distinct demand pockets that manufacturers must address through targeted portfolio architecture.
Product Type:
Buyers choose density and grain orientation based on traffic loads and aesthetic preferences, with hardness ratings and visual character driving specification splits.
- Strand Woven:Compressed bamboo fibers interlock under extreme pressure, producing Janka hardness ratings approaching 3,000 psi. Commercial co-working space developers in Germany and California specify this grade for high-traffic zones requiring rapid-renewable certification under LEED and BREEAM protocols.
- Horizontal:Culm strips align flat-side-up, exposing the bamboo's natural node pattern. Residential renovators in the Netherlands favor this aesthetic for boutique hospitality lobbies where visible grain character supports biophilic design narratives.
- Vertical:Strips stand on edge, creating a finer, more uniform grain line. This format suits minimalist residential interiors in Sweden where understated texture aligns with Nordic building code mandates for sustainable materials.
- Carbonized:Heat-treated culms darken through caramelized sugars, eliminating the need for surface stains. The process reduces hardness by approximately 20%, limiting placement to low-traffic residential bedrooms and light commercial offices.
Volume sits with Strand Woven; growth tilts toward Horizontal as hospitality developers expand biophilic specifications.
Application:
End-use segmentation tracks divergent performance requirements, warranty expectations, and procurement channel preferences across built environment categories.
- Residential:Single-family renovations and new construction dominate volume flows, with click-lock systems displacing glue-down methods in North American retrofit markets. Homeowners prioritize rapid installation and formaldehyde-free certifications under California Air Resources Board standards.
- Commercial:Co-working spaces, boutique hotels, and retail flagships drive specification for aluminum oxide-coated surfaces. ECHA restrictions on volatile organic compounds redirect finish chemistry toward water-based systems for Dutch distribution networks serving Belgian and German markets.
- Industrial:Light manufacturing and warehouse administrative areas specify bamboo for break rooms and office pods. China's GB standards for formaldehyde emissions in wood-based panels shape export eligibility for Anhui and Hunan production facilities serving this segment.
- Outdoor:Exterior decking and terrace applications require specialized moisture-resistant treatments. Vietnam's export manufacturing zones near Ho Chi Minh City concentrate capacity for thermally modified outdoor grades.
Residential commands absolute volume; commercial installations are climbing the fastest as co-working space developers expand footprint.
Installation Method:
Labor cost pressures and substrate conditions determine method selection, with mechanical attachment preferences varying sharply by geography and renovation versus new construction.
- Glue Down:Full-spread adhesive application delivers the most stable, quiet floor system. This method persists in German commercial specifications where acoustic performance requirements exceed floating system capabilities.
- Nail Down:Staple or cleat attachment over plywood subfloors dominates US new residential construction. Contractors in Texas and Florida prefer this familiar technique for its speed on wood-framed structures.
- Floating:Interlocking planks rest on underlayment without substrate attachment. Swedish and Norwegian markets favor this approach for retrofit compatibility with existing concrete slabs and radiant heating systems.
- Click Lock:Precision-milled tongue-and-groove edges snap together mechanically. North American renovators increasingly specify this method to reduce skilled labor dependency and accelerate project timelines.
Click Lock is gaining share fastest; Nail Down retains volume leadership in new US residential construction.
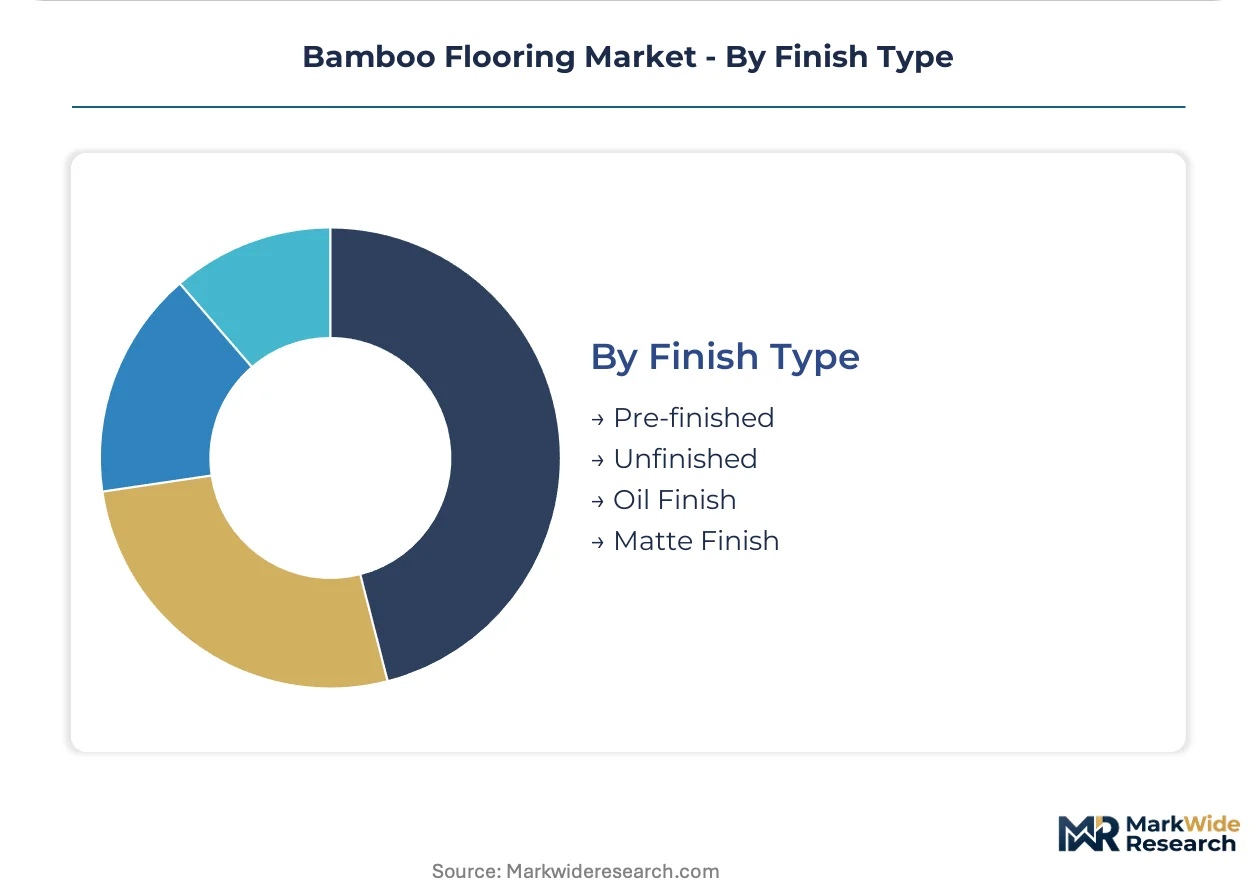
Finish Type:
Surface treatment selection balances durability, maintenance cycles, and regulatory compliance across distribution channels.
- Pre-finished:Factory-applied aluminum oxide coatings cure under controlled conditions, delivering consistent hardness and warranty terms. European distributors in the Netherlands specify these products to avoid on-site finishing complications.
- Unfinished:Bare planks allow custom staining and site-specific finish matching. High-end residential renovators in New York and California select this option for heritage restoration projects requiring color continuity.
- Oil Finish:Penetrating hardwax oils enhance natural grain depth while permitting localized repair. Danish and Swedish markets prefer this renewable surface for residential applications where maintenance access is straightforward.
- Matte Finish:Low-sheen water-based formulations satisfy EU Green Deal aesthetic preferences and ECHA volatile organic compound limits. German commercial specifiers increasingly mandate this chemistry for indoor air quality compliance.
Pre-finished dominates volume flows; Matte Finish shows the steepest expansion trajectory as water-based chemistry displaces solvent systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Anhui and Hunan provinces anchor raw material supply through controlled bamboo plantation networks, while manufacturing gravity shifts toward Vietnam's export processing zones and European distribution clusters in the Netherlands.
China
Domestic renovation contractors drive specification of engineered planks for residential retrofits. SAMR enforces GB standards for formaldehyde emissions in wood-based panels, compressing export eligibility for Anhui Dasuo and Hunan Taohuajiang production facilities. Manufacturing concentrates in Anhui and Hunan provinces near raw material harvesting zones.
Vietnam
North American retrofit demand for click-lock installation systems pulls capacity expansion. The country's national standards body aligns with ISO chain-of-custody documentation requirements for export market access. Production clusters near Ho Chi Minh City consolidate thermally modified outdoor grade capacity.
United States
LEED-driven commercial specifiers in California and New York procure reclaimed-content blends. California Air Resources Board standards shape formaldehyde-free certification requirements for residential distribution. Contractor networks in Texas and Florida favor nail-down methods for new wood-framed construction.
Germany
Co-working space developers specify strand-woven grades for high-traffic zones requiring BREEAM compliance. ECHA restrictions on volatile organic compounds redirect finish chemistry toward water-based systems. Acoustic performance requirements in commercial specifications sustain glue-down method preference.
Netherlands
Boutique hospitality developers bypass traditional distribution tiers through controlled warehouse networks. EU Green Deal implementation accelerates water-based matte formulation adoption across Belgian and German export channels. Distribution infrastructure serves dual certification documentation streams for residential and commercial segments.
Bamboo Flooring Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty finish and reclaimed-content niches. The vendor base spans vertically integrated plantation operators, regional fabricators with captive coating facilities, and distribution-anchored brands serving specification-driven segments. Two strategic archetypes dominate: upstream-controlled supply chain operators and certification-focused brand builders. Competitive moves concentrate on geographic expansion into Nordic markets and portfolio diversification toward outdoor-grade thermally modified products.
Among China-based fabricators, Anhui Dasuo Bamboo and Wood Technology and Hunan Taohuajiang Bamboo Materials Technology exemplify upstream-controlled archetypes with plantation-to-finished-plank operations. Moso International anchors European distribution positioning through Netherlands-based warehouse networks. These three occupy positions across the supply chain spectrum from raw material control to brand-driven specification.
| Leading Market Players |
|---|
| Teragren |
| Hangzhou Runzhu Technology |
| Moso International |
| Anhui Dasuo Bamboo and Wood Technology |
| Shaoxing Zhonghe Bamboo and Wood Products |
| Dasso Group |
| Zhejiang Zhuanghe Bamboo Industry Technology |
| Hunan Taohuajiang Bamboo Materials Technology |
| Cali Bamboo |
| Others |
Supply Flow & Price Mechanics
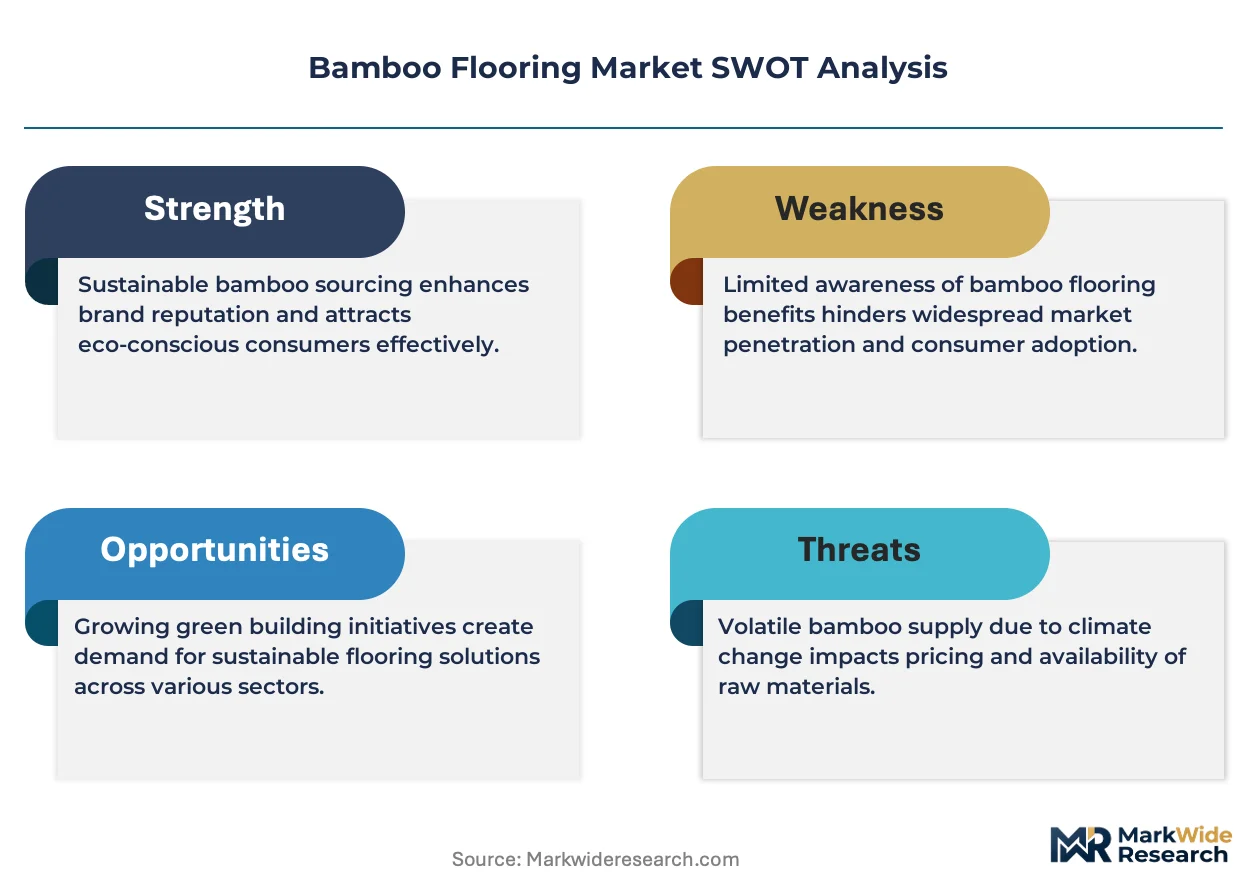
Family-owned mid-cap plantation operators in Anhui and Hunan provinces anchor raw material supply, their generational land tenure creating pricing discipline that resists spot-market volatility while sustaining margin stability through captive culm harvesting cycles.
Pricing Analysis
Volume concentrates in standard-grade horizontal and vertical planks serving residential renovators, while margin accrues to strand-woven and reclaimed-content blends commanding specification premiums from LEED-driven commercial developers. Price differentiation rests on Janka hardness ratings and formaldehyde certification tiers under China's GB standards and California Air Resources Board protocols. Cost compression in economy-grade engineered planks is intensifying as Vietnamese export zones scale click-lock capacity for North American retrofit demand. Boutique hospitality developers show least price sensitivity, prioritizing rapid-renewable documentation and aluminum oxide durability warranties over per-square-meter economics.
Supply Chain Analysis
Workforce availability constraints in Anhui and Hunan manufacturing zones are redirecting capacity expansion toward Vietnam's export processing clusters near Ho Chi Minh City, where labor pools support thermally modified outdoor grade production. Raw material supply draws from Moso bamboo culm harvesting cycles in Chinese plantation networks, aluminum oxide coating chemicals from industrial finish suppliers, and precision-milled click-lock hardware from Taiwanese machining specialists. Single-source vulnerability concentrates in China's SAMR-regulated formaldehyde certification pipeline, where enforcement actions at Anhui Dasuo and Hunan Taohuajiang facilities disrupt export eligibility windows. Distribution runs through Netherlands-based controlled warehouse networks serving European specification markets and direct-to-renovator platforms in California and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story, where China's SAMR enforcement of GB formaldehyde standards and the EU Green Deal's ECHA restrictions create barrier-to-entry moats that favor incumbent players with certified supply chain documentation.
For Market Incumbents: To counter substitution pressure from engineered hardwood and luxury vinyl plank alternatives, deepen backward integration into plantation networks securing Moso culm supply in Anhui and Hunan provinces, while accelerating water-based matte finish chemistry transitions at existing coating facilities to maintain CE marking eligibility under REACH restrictions. For New Entrants and Emerging Players: The pricing gap between premium strand-woven commercial grades and economy residential planks opens white-space targeting in Nordic markets, where Sweden and Norway building codes mandate rapid-renewable content thresholds that bamboo flooring satisfies; pursue direct-to-renovator platform partnerships bypassing traditional distribution tiers. For Investors and Strategic Acquirers: Divergence between ISO-compliant chain-of-custody documentation and emerging national ecolabel programs is the leading indicator that certification-focused brand builders with established Netherlands warehouse networks represent the most defensible acquisition profile over the medium-term horizon; monitor GB standard upgrade timelines as inflection signals for Chinese export eligibility compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Networks | Anhui and Hunan land tenure secures Moso culm supply against harvesting cycle volatility. |
| Water-Based Finish Chemistry Transition | ECHA REACH compliance preserves CE marking access across German and Belgian distribution channels. |
| Click-Lock Installation System Scale-Up | Vietnam export zones capture North American retrofit demand from labor-cost-sensitive contractors. |
| Reclaimed-Content Blend Development | Post-industrial fiber integration creates LEED point advantages for California and New York specifiers. |
| Netherlands Warehouse Network Expansion | Controlled distribution infrastructure serves bifurcated residential and commercial certification streams. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with residential renovation contractors, boutique hospitality developers, commercial specification architects, coating facility plant managers, and Netherlands-based distribution channel partners. Secondary validation drew from China's SAMR GB standard documentation, ECHA REACH restriction updates, California Air Resources Board certification databases, and EU Green Deal implementation guidance. Bottom-up project pipeline analysis and top-down macroeconomic triangulation shaped volume and value estimates.
Product type, application, installation method, and finish chemistry were modeled at the SKU level across the projection horizon, with geography-specific regulatory cluster overlays for China, Vietnam, United States, Germany, and Netherlands. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Forecast inputs incorporated Moso bamboo culm harvesting cycle timing, aluminum oxide coating capacity utilization, and click-lock hardware supply lead times.
Underlying measurement precision varies by segment; strand-woven commercial grades and pre-finished aluminum oxide products carry tighter precision than unfinished oil-finish residential lines. Forecasts reflect documented assumptions regarding GB standard enforcement intensity and ECHA formulation transition timelines. Material deviation in SAMR certification actions or EU Green Deal implementation pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Global Vinyl Flooring Market
Flooring, Carpets, and Rugs
US Wood Flooring Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
United Arab Emirates Floor Covering Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
Lightweight Acoustic Floor Systems Market
Flooring, Carpets, and Rugs
China Luxury Vinyl Tile (LVT) Market
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
Europe Carpet Tile Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
Flooring Wood Panels Market
Flooring, Carpets, and Rugs
Saudi Arabia Carpet and Rugs Market
Flooring, Carpets, and Rugs
Global Non-Resilient Flooring Market
Flooring, Carpets, and Rugs
Global Flooring and Carpet Market