
 Global Non-Resilient Flooring Market | 2026-2036
Global Non-Resilient Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Resilient Flooring Market Foresight
The gap between premium porcelain slabs and commodity-grade ceramic tile is broadening as architects specify thicker, rectified formats with digital glazing while budget housing projects absorb standard 8mm products. Mohawk Industries Inc. leverages captive quartz sourcing and North American manufacturing scale to dominate the premium stone-look segment. Kajaria Ceramics Limited anchors its position through deep distribution across tier-two Indian cities and continuous kiln investments. Porcelanosa Grupo A.I.E. differentiates via design-forward Spanish manufacturing and controlled retail channels in European capitals.
Non-resilient flooring comprises rigid surfacing materials—ceramic, porcelain, natural stone, laminate, and vinyl tile—manufactured without elastic polymer cores, typically installed with mortar, adhesive, or mechanical fastening to concrete or plywood substrates rated for deflection limits of L/360. These materials serve commercial, institutional, and residential applications where abrasion resistance, moisture tolerance, and load-bearing capacity exceed resilient alternatives. Ceramic tile retains the largest value share due to decades of installed base and replacement cycles, yet laminate and luxury vinyl tile are capturing faster growth in commercial renovation where speed of installation and lower subfloor preparation costs shift project economics. Stone commands concentrated margin pools in hospitality and high-end residential specification, though quarry-source consistency limits volume scaling.
Regulatory frameworks including the EU Green Deal's embodied-carbon thresholds, California's CARB Phase 2 formaldehyde standards for laminate core layers, and India's BIS certification for ceramic tile dimensions collectively reshape product compliance costs and market access conditions. The US EPA and OSHA silica-exposure rules for stone-cutting operations add compliance layers that favor centralized fabrication over site-based installation. Stakeholders must monitor divergence between regional carbon-accounting methodologies and evolving recycling mandates for post-consumer tile and laminate waste streams.
Market Dynamics
Embodied-carbon disclosure mandates are fragmenting procurement specifications across commercial construction, forcing suppliers to maintain parallel product lines certified under divergent regional methodologies while kiln operators absorb compliance costs ahead of enforcement deadlines.
Growth Catalysts
- EU CSRD alignment:Singapore's Building and Construction Authority and Australia's Green Building Council are mandating lifecycle carbon declarations for public projects, pulling large-format porcelain into specification pipelines.
- Morbi cluster expansion:Gujarat's ceramic belt is adding continuous roller kiln capacity with digital glazing lines, compressing lead times for export-grade rectified tile.
- Silica-safety centralization:OSHA's respirable crystalline silica standard for construction is pushing stone fabrication into controlled off-site facilities, favoring suppliers with captive cutting operations.
Market Restraints
- Natural gas price volatility:Kiln operations in Italy and Spain face input cost swings that erode margin on commodity-grade ceramic, forcing production curtailments during price spikes.
- Quarry source inconsistency:Natural stone suppliers cannot replicate color and veining across batches, limiting specification in hospitality rollouts requiring visual uniformity at scale.
- Laminate core substitution:CARB Phase 2 compliant particleboard faces displacement by SPC rigid core in commercial renovation where moisture resistance trumps cost.
Strategic Opportunities
- India tier-two penetration:Organized retail flooring formats in Jaipur, Lucknow, and Kochi remain underdeveloped, creating whitespace for branded ceramic distribution.
- Digital twin specification:BIM-integrated material libraries are unifying architect workflows with real-time embodied-carbon data, opening channel partnerships with design software vendors.
- Post-consumer recycling mandates:France's extended producer responsibility framework for building materials is creating pull for take-back programs and recycled content certification.
Industry Challenges
- Skilled installer scarcity:Large-format porcelain slabs demand certified thin-set and leveling competence that outstrips training pipeline capacity in North American construction labor markets.
- Dual certification timelines:Suppliers seeking EU CE marking plus India's BIS registration face staggered testing protocols that delay product launches by 8-14 months.
- Legacy inventory mismatch:Distributors hold 8mm ceramic stock that conflicts with architect preference for 12mm+ rectified formats, stranding working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Resilient Flooring Market |
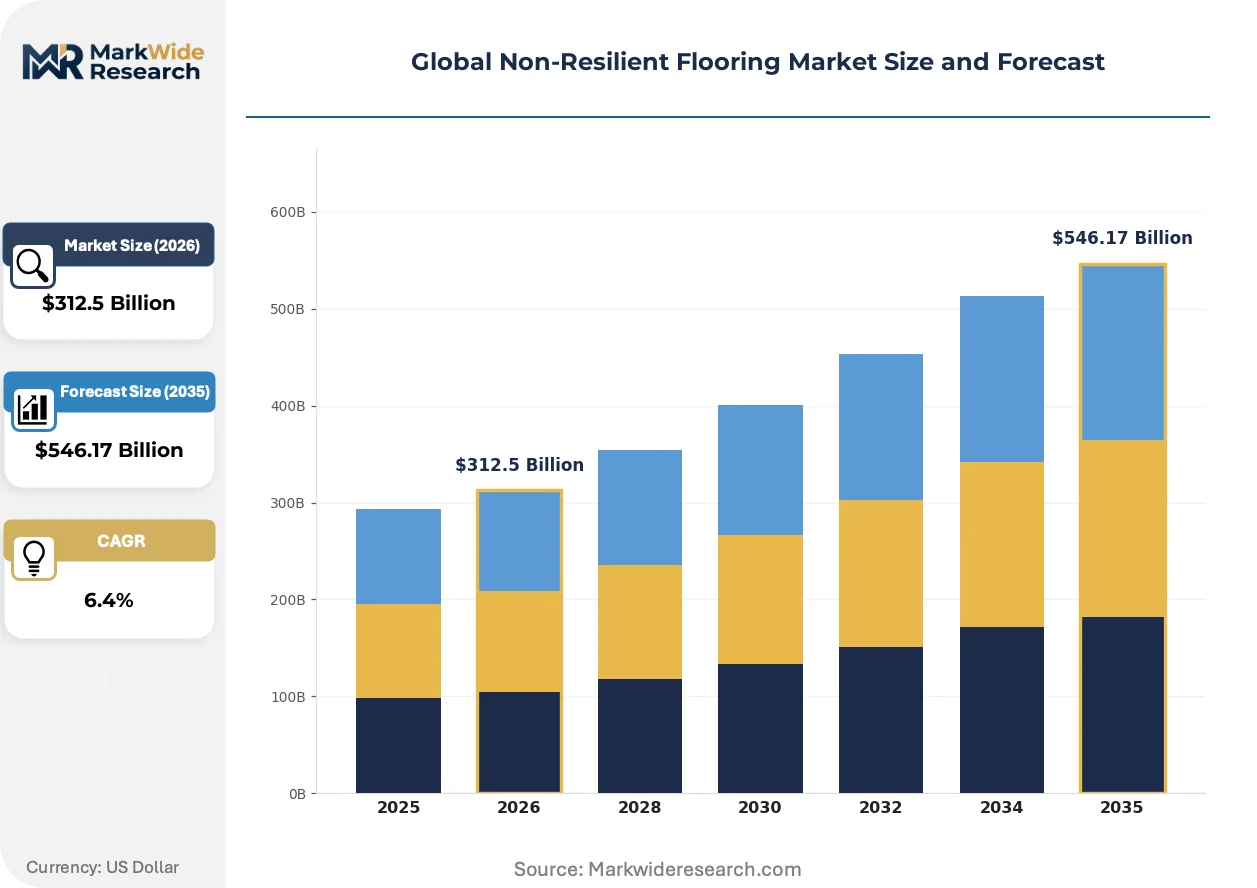
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $546.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Tile, Vinyl Tile, Laminate, Stone Application: Residential, Commercial, Industrial, Institutional Installation Type: Glue-Down, Floating, Nail-Down, Thinset Distribution Channel: Direct Sales, Wholesalers, Retail Stores, Online |
| Companies Covered | Mohawk Industries Inc., Shaw Industries Group Inc., Daltile, Kajaria Ceramics Limited, China Ceramics Co. Ltd, Mannington Mills Inc., Porcelanosa Grupo A.I.E., RAK Ceramics, Ceramica Saloni, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Resilient Flooring Market Shifts & Advancements
Digital manufacturing and carbon-accounting transparency are compressing the traditional supplier-architect relationship, replacing specification-by-sample with data-driven material selection tied to project certification targets.
Thin-body porcelain slabs with through-body color consistency are unifying the performance of natural stone with the installability of ceramic, enabling facade and flooring specification from a single material platform. Hospitality developers in Dubai and Miami are specifying 6mm gauged porcelain for both interior and exterior applications, collapsing SKU complexity for procurement teams while accelerating facade installation timelines.
REACH's restriction on per- and polyfluoroalkyl substances is forcing reformulation of stain-resistant coatings for glazed ceramic, with Spanish and Italian manufacturers shifting to sol-gel alternatives ahead of enforcement. The industrial consequence is a 15-20% coating cost increase that suppliers are passing to premium residential segments, while commercial projects absorb the shift through longer maintenance warranties.
Architects are consolidating specification authority through centralized procurement platforms that bypass traditional distributor relationships, particularly in German and Dutch commercial construction where general contractors bundle flooring into design-build contracts. This channel compression favors suppliers with direct BIM content libraries and carbon data APIs, disadvantaging smaller mills without digital infrastructure.
Global Non-Resilient Flooring Market Segmentation
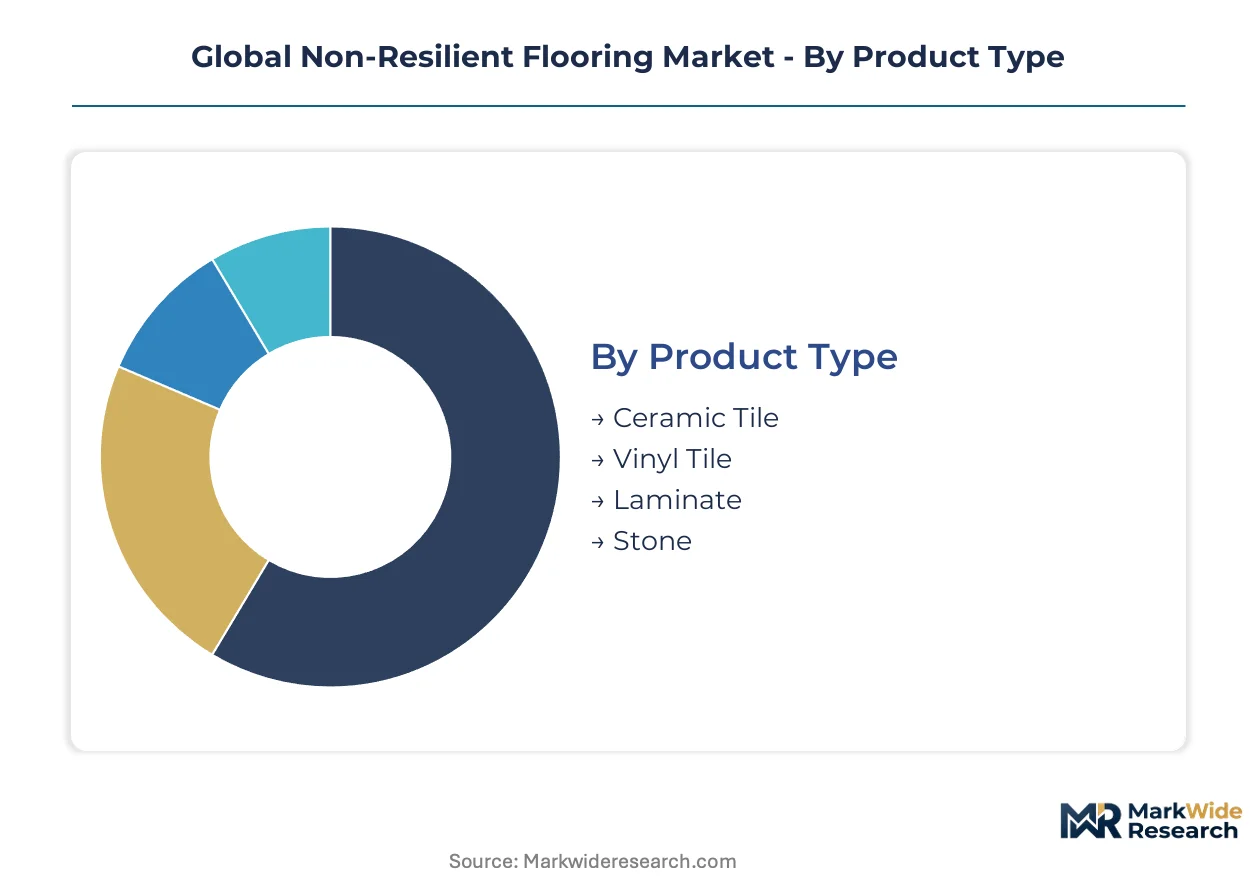
Non-resilient flooring markets fragment across material chemistry, installation physics, and procurement channel economics. Specification decisions cascade from embodied-carbon accounting through labor-skill availability to end-use performance requirements.
Product Type:
Replacement cycles and subfloor preparation costs determine upgrade velocity across material categories, with thicker formats commanding premium positioning in renovation workflows.
- Ceramic Tile:Fired clay bodies with glazed or through-body finishes dominate existing stock replacement in residential bathrooms and kitchens across India and Spain. Morbi cluster capacity expansion is compressing export lead times for rectified formats specified in Gulf Coast hospitality projects.
- Vinyl Tile:Rigid SPC and LVT cores with printed wear layers are displacing laminate in North American commercial renovation where moisture tolerance outweighs first-cost considerations. Glue-down and floating systems reduce subfloor remediation requirements in aging office stock.
- Laminate:HDF cores with melamine-impregnated decorative papers face CARB Phase 2 compliance cost absorption and core-substitution pressure from SPC alternatives.
- Stone:Natural granite, marble, and travertine command concentrated specification in Dubai and Miami luxury residential where quarry-source consistency supports facade-flooring continuity.
Volume placements concentrate in ceramic tile; the faster expansion belongs to vinyl tile.
Application:
End-use performance standards and occupancy density create divergent material selection criteria across building types.
- Residential:Single-family and multi-family housing drives ceramic and laminate volume through replacement cycles in kitchens, bathrooms, and living areas. India's tier-two cities present whitespace for organized retail distribution.
- Commercial:Office, retail, and hospitality specifications prioritize abrasion resistance and speed of installation. Large-format porcelain slabs are gaining specification in German and Dutch design-build contracts.
- Industrial:Manufacturing and warehouse flooring demands load-bearing capacity and chemical resistance that favors epoxy-modified thinset ceramic systems.
- Institutional:Healthcare and education facilities specify slip-resistant surfaces with antimicrobial glazing, subject to EU Green Deal embodied-carbon thresholds.
Residential channels move the highest unit volumes; institutional projects generate the steepest margin pools.
Installation Type:
Labor skill availability and project timeline compression shape method selection across geographies.
- Glue-Down:Direct adhesive bonding of vinyl and carpet tile dominates commercial renovation in North America where speed of installation offsets material cost premiums.
- Floating:Interlocking laminate and LVT systems enable rapid deployment over uneven substrates, reducing preparation costs in aging European office stock.
- Nail-Down:Solid and engineered hardwood fastening persists in US residential construction where plywood subfloors predominate.
- Thinset:Mortar-bed ceramic and porcelain installation demands certified labor that outstrips training pipeline capacity for large-format slab specification.
Floating systems claim the fastest share gains; thinset methods retain the highest labor dependency.
Distribution Channel:
Channel compression through BIM-integrated procurement is restructuring traditional distributor relationships.
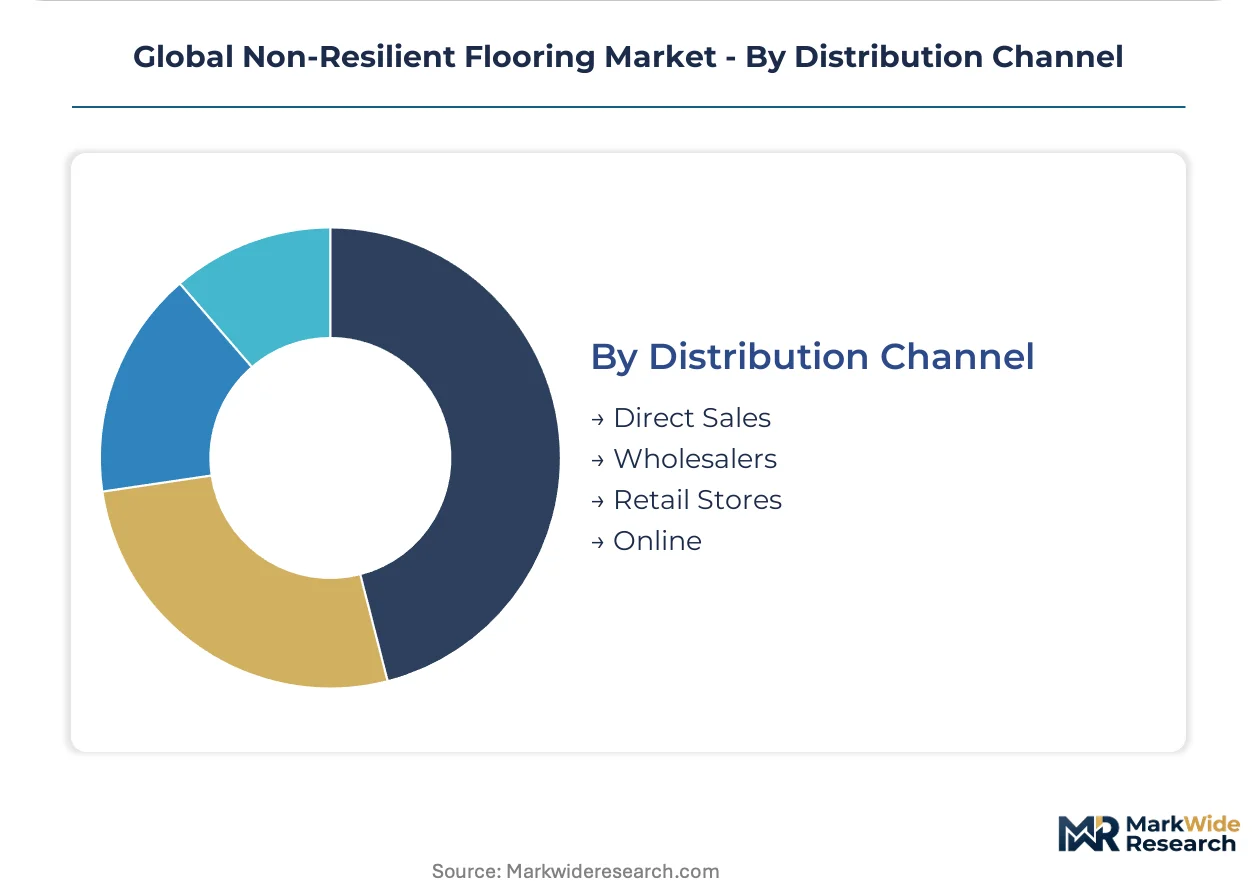
- Direct Sales:Manufacturer-to-contractor relationships bypass distributor markups in German commercial construction where general contractors bundle flooring into design-build contracts.
- Wholesalers:Regional stocking distributors serve mid-market contractors with 8mm ceramic inventory that conflicts with architect preference for 12mm+ rectified formats.
- Retail Stores:Big-box and specialty flooring retailers in US and European markets face displacement by specification platforms with real-time carbon data.
- Online:E-commerce channels for sample ordering and direct-to-consumer sales are expanding in residential renovation segments.
Wholesalers still handle the greatest throughput; direct sales channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Morbi anchors ceramic production capacity expansion while commercial specification in Dubai and Miami accelerates large-format porcelain adoption. Regulatory divergence across the EU, India, and the United States fragments compliance pathways for suppliers.
United States
Commercial renovation in aging office stock drives rigid vinyl tile specification ahead of laminate. OSHA's respirable crystalline silica standard pushes stone fabrication into controlled off-site facilities. Georgia and Tennessee host concentrated laminate and LVT manufacturing corridors serving North American distribution.
Germany
Design-build contracts bundle flooring procurement through general contractors, compressing distributor margins. The EU Green Deal's embodied-carbon thresholds mandate lifecycle declarations for public projects. Bavaria and North Rhine-Westphalia anchor engineered wood and laminate production with integrated supply chains.
India
Tier-two city retail whitespace in Jaipur, Lucknow, and Kochi creates distribution expansion opportunities for organized ceramic brands. BIS certification requirements for ceramic tile dimensions delay product launches by 8-14 months for dual-registered suppliers. Gujarat's Morbi cluster adds continuous roller kiln capacity with digital glazing lines for export-grade rectified formats.
Spain
Italian and Spanish manufacturers absorb 15-20% coating cost increases from REACH PFAS restrictions on stain-resistant glazes. Natural gas price volatility forces production curtailments on commodity-grade ceramic during price spikes. Castellón's ceramic belt maintains design-forward positioning through controlled retail channels in European capitals.
China
Domestic ceramic oversupply pressures export pricing while digital manufacturing investments compress lead times for large-format slabs. GB standards and dual carbon goals reshape kiln technology upgrade requirements. Foshan and Zibo clusters concentrate glazed ceramic production for Southeast Asian and Middle Eastern markets.
Global Non-Resilient Flooring Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and specification authority. The vendor base stratifies into three tiers: integrated multinationals with captive raw material sourcing, regional specialists with deep distribution in single geographies, and unbranded exporters competing on FOB pricing. Archetypes include quartz-integrated stone-look specialists, ceramic cluster-based volume producers, and design-forward European manufacturers with controlled retail. Dominant competitive moves encompass kiln technology upgrades for carbon compliance and BIM-integrated specification platforms that bypass traditional distributor relationships.
Among India-based ceramic specialists, Kajaria Ceramics Limited exemplifies the regional-distribution archetype with tier-two city penetration. Zhengzhou-based China Ceramics Co. Ltd occupies a position within the volume-export tier serving Middle Eastern and Southeast Asian project pipelines. Mohawk Industries Inc. anchors the North American premium segment through integrated quartz sourcing and domestic manufacturing scale. These three represent distinct strategic positions without overlapping geographic or segment focus.
| Leading Market Players |
|---|
| Mohawk Industries Inc. |
| Shaw Industries Group Inc. |
| Daltile |
| Kajaria Ceramics Limited |
| China Ceramics Co. Ltd |
| Mannington Mills Inc. |
| Porcelanosa Grupo A.I.E. |
| RAK Ceramics |
| Ceramica Saloni |
| Others |
Supply & Pricing Matrix
EU Green Deal embodied-carbon thresholds gate qualified supply access and premium-tier pricing power, compressing margins for uncertified producers while rewarding kiln operators with verified lifecycle declarations. Buyers in German design-build contracts now require carbon-accounting documentation that disqualifies commodity-grade ceramic from public project pipelines.
Pricing Analysis
Project-certification value anchors pricing power, with architects paying premiums for materials carrying EU CE marking and India's BIS registration that accelerate compliance timelines. Price differentiation separates digitally glazed rectified formats from standard 8mm ceramic, while natural gas volatility in Spain and Italy forces production curtailments that tighten spot pricing. Cost compression runs through commodity-grade laminate facing SPC substitution pressure. Budget housing developers in India exhibit highest price sensitivity; hospitality specifiers in Dubai and Miami absorb premium positioning.
Supply Chain Analysis
Dual certification requirements for CE marking and BIS registration filter supplier participation, extending product launch timelines and concentrating procurement relationships with mills maintaining parallel testing capabilities. Manufacturing gravity centers on India's Morbi cluster, Spain's Castellón belt, and China's Foshan-Zibo corridor. Raw material flows draw from Gujarat clay deposits, Italian feldspar sources, and Saudi silica sand. Single-source vulnerability concentrates in natural stone quarrying where batch consistency failures disrupt hospitality rollouts. Distribution runs through BIM-integrated specification platforms that displace traditional wholesaler relationships in German and Dutch commercial construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Large-format porcelain slab technology is displacing legacy ceramic and natural stone specification, collapsing SKU complexity while demanding certified thin-set installation competence that outstrips labor pipeline capacity.
For Market Incumbents: Acquire captive quarry or fabrication assets to secure batch consistency for hospitality rollouts threatened by visual uniformity failures. Integrate digital glazing lines with carbon-accounting APIs to defend specification authority against BIM-integrated procurement platforms. Prioritize kiln technology upgrades in Gujarat and Castellón ahead of EU CSRD enforcement deadlines. For New Entrants and Emerging Players: Enter via tier-two Indian cities—Jaipur, Lucknow, Kochi—where organized retail flooring formats remain underdeveloped and branded ceramic distribution commands whitespace. Target commercial renovation segments in aging North American office stock where speed of installation favors rigid vinyl tile over laminate. Lead with take-back program offerings aligned to France's extended producer responsibility framework. For Investors and Strategic Acquirers: Morbi cluster capacity announcements exceeding digital glazing line deployments is the leading indicator that export-grade supply is tightening and margin compression will follow for undifferentiated producers. Five-to-ten-year viability favors integrated multinationals with captive raw material sourcing and direct architect channel relationships. Watch for BIS certification backlogs exceeding fourteen months as signal that dual-registered suppliers will consolidate procurement share.| Strategic Initiative | Industry Significance |
|---|---|
| Kiln Technology Upgrade | Continuous roller kilns with digital glazing compress lead times for EU CSRD-compliant rectified formats. |
| Backward Integration into Quartz | Mohawk's captive quartz sourcing anchors premium stone-look segment positioning against import-dependent competitors. |
| BIM Content Library Development | Direct API integration with architect workflows bypasses distributor markups in German design-build contracts. |
| Tier-Two Distribution Expansion | Organized retail penetration in Jaipur and Lucknow captures whitespace before local ceramic brands consolidate. |
| Take-Back Program Launch | France's extended producer responsibility framework creates competitive differentiation through recycled content certification. |
Research Methodology
Document review covered EU ETS filings, Indian BIS certification registries, and OSHA silica-exposure compliance records, complemented by interviews with ceramic plant managers, commercial architect specification leads, and flooring distributor procurement heads. Secondary validation drew from customs trade data, SEC 10-K disclosures, and green building council project databases. Bottom-up capacity assessments across Morbi, Castellón, and Foshan clusters were triangulated against top-down construction spend projections.
Segment-level value and volume trajectories across the analysis window reflect modeled interactions between material chemistry, installation physics, and procurement channel economics. The framework incorporated product type, application end-use, installation method, and distribution channel as core segmentation dimensions. CAGRs were derived from regression-adjusted capacity expansion schedules and embodied-carbon compliance cost absorption curves. Key inputs included natural gas price volatility indices for Mediterranean kiln operations and North American construction labor availability metrics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory timeline acceleration or quarry-source depletion events. Projections reflect assumptions regarding EU CSRD enforcement consistency, India BIS registration processing rates, and silica-safety centralization adoption. A model refresh is warranted upon material change in EU Green Deal threshold calibration or Morbi cluster capacity commissioning schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Carpet Market
Flooring, Carpets, and Rugs
India Laminate Flooring Market
Flooring, Carpets, and Rugs
Resilient Flooring Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
North America Carpet Tile Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
US Terrazzo Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market
Flooring, Carpets, and Rugs
Area Rugs Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
Hard Surface Flooring Market
Flooring, Carpets, and Rugs
Europe Vinyl Flooring Market
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
Luxury Vinyl Plank (LVP) Market