
 Carpet Floor Mats Market | 2026-2036
Carpet Floor Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Carpet Floor Mats Market Analysis
Multi-source procurement of synthetic fiber substrates is expanding across the carpet floor mats supply base as manufacturers hedge against petrochemical price volatility. Mohawk Industries leverages captive nylon polymer production to sustain margin stability in residential and commercial matting lines. Shaw Industries anchors its position through vertical control over tufting and dyeing operations in the southeastern United States. Interface, Inc. differentiates via closed-loop recycling systems that recover post-consumer nylon face fiber for re-tufting applications.
Carpet floor mats are textile floor coverings constructed from tufted or woven face fibers—typically nylon, polypropylene, or polyester—bonded to primary and secondary backing layers of woven polypropylene or latex-impregnated felt, with pile weights ranging from 16 to 48 ounces per square yard depending on traffic rating. These products serve to trap soil and moisture at building entries, reduce slip hazards in commercial environments, and provide acoustic dampening and thermal insulation in residential and automotive interiors. Entrance mats and industrial mats represent the mature volume core, where polypropylene dominates due to its moisture resistance and lower unit cost, while nylon commands premium positioning in hospitality and heavy-duty safety applications where crush recovery and stain resistance justify higher replacement cycles. The automotive end-user segment is shifting toward lighter-weight polyester constructions to support vehicle lightweighting mandates without sacrificing abrasion performance.
The EPA regulates volatile organic compound emissions from carpet adhesives and backing materials under its National Emission Standards for Hazardous Air Pollutants, pushing manufacturers toward water-based latex formulations and low-VOC hot-melt systems. California's Department of Public Health maintains Section 01350 testing protocols for indoor air quality that de facto shape product specifications for any matting installed in schools, healthcare facilities, or state-leased commercial space nationwide. Stakeholders must monitor evolving state-level extended producer responsibility frameworks for carpet recycling, as these programs will increasingly dictate material choices and reverse logistics costs across the value chain.
Market Dynamics
Automotive OEMs are consolidating carpet floor mat specifications around low-VOC substrates as California's CARB Phase 2 formaldehyde limits reshape material qualification protocols across North American vehicle assembly plants.
Growth Catalysts
- Vehicle Interior Air-Quality Mandates:California's Department of Public Health Section 01350 testing protocols now de facto govern school and healthcare facility matting specifications nationwide, forcing specification upgrades.
- China Vehicle Production:Domestic automakers in China are expanding custom-fit carpet mat orders to match rising passenger vehicle output and stricter cabin air standards.
- Closed-Loop Nylon Recovery:Post-consumer face fiber re-tufting systems are lowering raw material exposure for manufacturers with captive collection infrastructure.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and nylon 6,6 polymer prices swing with crude oil and caprolactam markets, compressing margin visibility for non-integrated producers.
- Regional Supply Concentration:Tufting and dyeing capacity clusters in the southeastern United States create hurricane and logistics risk exposure for North American supply security.
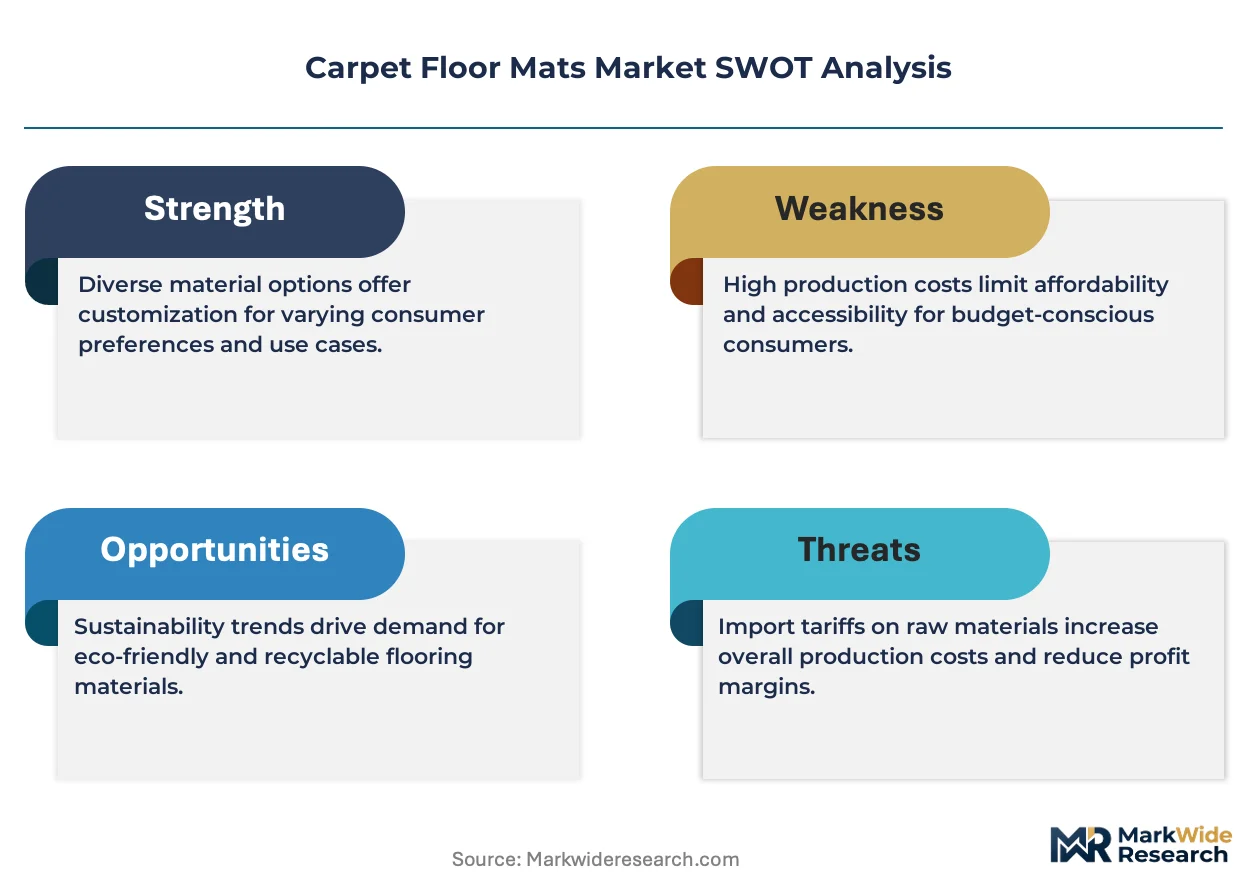
- Formaldehyde-Free Backing Cost Premium:Water-based latex and hot-melt adhesive systems required for EPA NESHAP compliance add 12-18% to substrate costs versus conventional urea-formaldehyde binders.
Strategic Opportunities
- India Commercial Real Estate:Office and retail construction in Mumbai and Bangalore is driving bulk entrance matting procurement for polypropylene moisture-trap systems.
- Extended Producer Responsibility Expansion:State-level carpet recycling frameworks in California and New York will mandate reverse logistics infrastructure, favoring early movers with collection network investments.
- Digital Specification Platforms:Building information modeling integration is compressing architect-specifier decision cycles for commercial matting projects.
Industry Challenges
- Multi-Site Certification Complexity:Manufacturers serving healthcare and education verticals must maintain parallel California Section 01350, EPA NESHAP, and LEED v4.1 documentation across product lines.
- Legacy Dyeing Asset Stranding:Waterless solution-dyed nylon capacity is displacing conventional beck-dyeing equipment, forcing capex decisions on mid-scale tufting operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carpet Floor Mats Market |
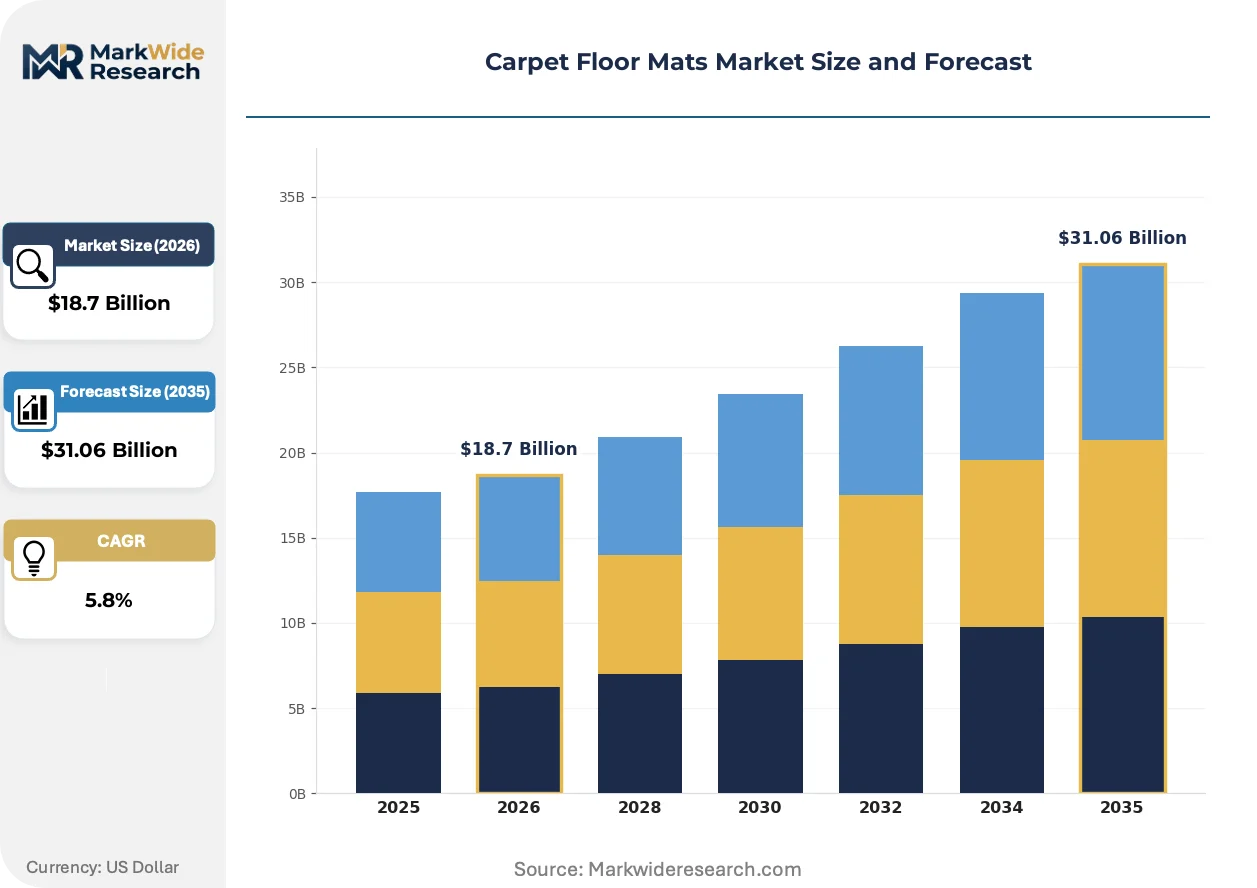
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Mats, Residential Mats, Decorative Mats, Entrance Mats Material: Polypropylene, Nylon, Rubber, Polyester End User: Commercial Spaces, Homes, Hospitality, Automotive Application: Indoor Use, Outdoor Use, Heavy-Duty, Safety |
| Companies Covered | Milliken & Company, Tarkett Group, Mohawk Industries, Bentley Mills, Forbo Flooring Systems, Shaw Industries, Beaulieu Group, Durable Corporation, Interface, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carpet Floor Mats Market Emerging Trajectories
Material science and regulatory compliance are fusing to redefine carpet floor mat construction standards, with sustainability metrics now embedded in procurement specifications ahead of price negotiation.
Solution-dyed PET face fiber is converging with automotive lightweighting mandates to displace heavier nylon constructions in passenger vehicle footwell applications. Tier 1 suppliers to Detroit and Stuttgart assembly plants are qualifying 20-30% lighter mat assemblies that retain abrasion resistance. This convergence is compressing the traditional nylon-polyester performance gap in mid-tier vehicle segments.
The EPA's National Emission Standards for Hazardous Air Pollutants for carpet adhesives is forcing formulation shifts toward water-based latex and reactive hot-melt systems. Manufacturers serving the K-12 and healthcare sectors face the tightest compliance windows as California's Section 01350 protocols extend to state-leased commercial space nationwide. Product development teams are prioritizing low-VOC backings ahead of face fiber innovation to secure specification lock-in.
Building owners are unbundling entrance matting from facilities management contracts and direct-sourcing through specification platforms that embed lifecycle cost analytics. This disintermediation is compressing distributor margins in the commercial real estate channel while rewarding manufacturers with certified environmental product declarations. The shift is most visible in Class A office developments in New York, Chicago, and San Francisco where LEED v4.1 points drive material selection.
Carpet Floor Mats Market Segmentation
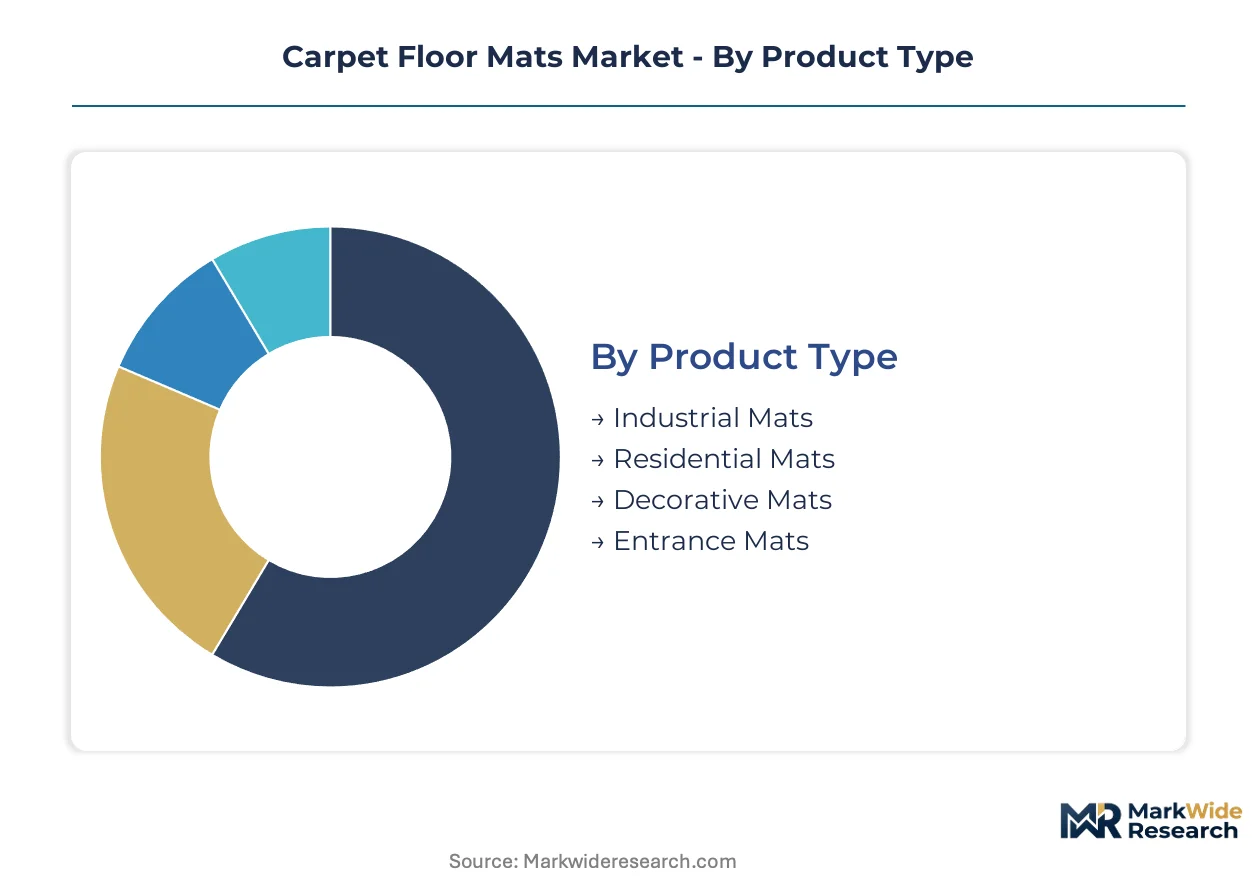
Carpet floor mat specifications fragment across certification tiers, with California Section 01350 compliance separating healthcare-grade products from general commercial offerings. Material selection and end-use application determine which regulatory pathways manufacturers must navigate.
Product Type:
California Section 01350 protocols and EPA NESHAP adhesive standards apply unevenly across product categories, with healthcare and education verticals demanding the most stringent documentation.
- Entrance Mats:Polypropylene face fiber bonded to rubber or vinyl backing dominates moisture-trap specifications for commercial building entries. Demand clusters in Class A office developments across New York, Chicago, and San Francisco where LEED v4.1 points drive material selection.
- Industrial Mats:Heavy-duty constructions with crush-resistant nylon pile and oil-resistant nitrile rubber backing serve manufacturing floors and warehouse loading docks. Anti-fatigue formulations with closed-cell foam substrates are gaining specification in automotive assembly plants and food processing facilities.
- Residential Mats:Lower pile weights and solution-dyed polyester face fiber target cost-conscious homeowners through big-box retail channels.
- Decorative Mats:Patterned and logo-imprinted options prioritize aesthetic customization over performance ratings in hospitality lobbies and corporate reception areas.
Entrance mats sit at the top of the volume ranking, with industrial mats climbing the fastest as manufacturing reshoring accelerates facility buildouts.
Material:
Cost tier stratification separates commodity petrochemical feedstocks from performance polymers with captive supply advantages.
- Polypropylene:Moisture-resistant olefin fiber with lower unit cost dominates high-volume entrance matting and residential applications. Bulk procurement from China and India leverages regional petrochemical integration.
- Nylon:Superior crush recovery and stain resistance command premium positioning in hospitality corridors and heavy-duty safety applications where replacement cycles justify higher upfront investment.
- Polyester:Lighter-weight PET constructions are displacing nylon in automotive footwell applications to meet vehicle lightweighting mandates without sacrificing abrasion performance.
- Rubber:Nitrile and SBR compounds provide slip-resistant backing substrates and solid surface industrial matting for wet environments.
Polypropylene holds the volume lead, while polyester gains share fastest in automotive lightweighting programs.
End User:
Customer type determines specification complexity, with institutional buyers embedding lifecycle cost analytics and environmental product declarations into procurement platforms.
- Commercial Spaces:Office, retail, and healthcare facilities drive demand for certified low-VOC matting systems with documented recycled content. Building owners are disintermediating distributors through direct specification platforms.
- Automotive:OEM procurement of custom-fit carpet mats is rising as manufacturers respond to stricter interior air-quality standards. Tier 1 suppliers qualify lighter-weight assemblies for Detroit and Stuttgart assembly plants.
- Hospitality:Hotels and conference centers prioritize crush-resistant nylon for high-traffic corridors and branded entrance matting.
- Homes:Price-sensitive residential demand channels through mass retail with limited certification requirements.
Commercial spaces anchor volume demand, with automotive expanding most quickly on cabin air-quality mandates.
Application:
Performance tier and environmental exposure dictate substrate engineering and regulatory compliance burden.
- Indoor Use:Low-VOC latex and hot-melt adhesive systems dominate climate-controlled environments where California Section 01350 and LEED v4.1 protocols apply. Water-based formulations add cost premium but secure specification lock-in.
- Heavy-Duty:Reinforced backing and dense pile constructions serve manufacturing, warehousing, and transportation hubs with extreme traffic loads.
- Outdoor Use:UV-stabilized polypropylene and drainage-channel designs withstand weather exposure at building perimeters and loading docks.
- Safety:Beveled edges, high-visibility borders, and anti-slip certifications address OSHA compliance in commercial kitchens and industrial walkways.
Indoor use commands the highest volume, with heavy-duty applications showing steepest expansion trajectory on logistics facility construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southeastern United States concentrates tufting and dyeing infrastructure that supplies North American automotive and commercial matting demand. Regulatory divergence across major economies is fragmenting product qualification pathways and forcing parallel certification investments.
United States
Automotive OEMs in Detroit and Stuttgart assembly plants are qualifying lighter-weight polyester mat assemblies to meet vehicle lightweighting mandates. EPA NESHAP compliance for carpet adhesives pushes manufacturers toward water-based latex formulations. The Georgia-South Carolina corridor hosts dense tufting operations serving hospitality and healthcare verticals with California Section 01350-certified production.
China
Domestic vehicle production expansion drives bulk orders for custom-fit carpet mats as cabin air standards tighten. MIIT regulations on interior air quality align with dual carbon goals to favor low-emission backing substrates. The Yangtze River Delta clusters polypropylene entrance matting manufacturing for commercial real estate construction in Shanghai and Hangzhou.
Germany
Automotive Tier 1 suppliers prioritize crush-resistant nylon constructions for premium vehicle segments where replacement cycles justify higher material investment. REACH compliance on chemical emissions shapes adhesive selection for products serving EU markets. The Stuttgart industrial region anchors development of lightweight matting systems for electric vehicle platforms.
India
Office and retail construction in Mumbai and Bangalore generates procurement volume for moisture-trap polypropylene entrance systems. BIS standards on textile floor coverings create compliance thresholds for imported and domestic products. The Gujarat petrochemical corridor supplies integrated polypropylene fiber production for cost-competitive matting exports.
Japan
Hospitality corridor applications demand stain-resistant nylon pile with documented recycled content under METI circular economy guidelines. JIS standards on slip resistance govern safety matting specifications for commercial kitchens and industrial walkways. The Nagoya automotive cluster drives qualification of low-VOC mat assemblies for domestic and export vehicle programs.
Carpet Floor Mats Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue recycled-content and closed-loop material platforms. The vendor base stratifies across integrated polymer producers, specialized tufting operations, and specification-driven architectural matting suppliers. Three archetypes dominate: captive resin producers leveraging backward integration, solution-dyed specialists with waterless coloration assets, and platform-integrated providers embedding lifecycle analytics into procurement systems. Competitive moves center on M&A to secure dyeing capacity and strategic partnerships with automotive Tier 1 suppliers for specification lock-in.
Among North American integrated manufacturers, Mohawk Industries, Shaw Industries, and Interface, Inc. represent distinct strategic positions. Mohawk Industries exemplifies the captive resin archetype through in-house nylon polymer production. Shaw Industries anchors the southeastern manufacturing cluster with control over tufting and dyeing operations. Interface, Inc. occupies the circular-economy tier with closed-loop nylon recovery infrastructure. These three entities illustrate the competitive divergence between cost stability, geographic concentration, and sustainability-driven specification capture.
| Leading Market Players |
|---|
| Milliken & Company |
| Tarkett Group |
| Mohawk Industries |
| Bentley Mills |
| Forbo Flooring Systems |
| Shaw Industries |
| Beaulieu Group |
| Durable Corporation |
| Interface, Inc. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap tufting operations concentrated in the Georgia-South Carolina corridor maintain pricing discipline through captive dyeing assets and long-term polypropylene supply contracts with Gulf Coast petrochemical producers. Their ownership structure insulates margin targets from quarterly earnings pressure, allowing sustained investment in low-VOC backing formulations despite the cost premium these substrates command against Asian imports.
Pricing Analysis
Input-cost pass-through from caprolactam and propylene feedstock markets operates on quarterly lag contracts for non-integrated producers, while captive polymer manufacturers like Mohawk Industries buffer margin volatility through backward integration. Pricing stratifies across California Section 01350-certified premium tiers, standard commercial grades, and economy residential channels with minimal certification burden. Cost compression in the standard tier intensifies as Chinese polypropylene entrance matting floods bulk procurement channels for Class A office developments. Automotive OEMs exhibit lowest price sensitivity, prioritizing lightweighting performance and cabin air-quality compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Detroit and Stuttgart assembly plants mandate qualification of at least two backing substrate suppliers to mitigate single-source vulnerability during hurricane disruptions in the southeastern United States. Raw material flows draw from caprolactam producers in the US Gulf Coast, polypropylene resin from the Gujarat petrochemical corridor, and nitrile rubber from South Korean synthetic rubber specialists. Tariff exposure on Chinese tufted products creates margin pressure for distributors serving price-sensitive residential channels. Distribution runs through specification platforms embedding lifecycle cost analytics for commercial real estate, bypassing traditional distributor networks in New York and Chicago.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between the EPA NESHAP compliance costs burdening US manufacturers and the MIIT air-quality standards driving Chinese domestic producers toward equivalent low-emission substrate investments.
For Market Incumbents: Cement specification lock-in through early California extended producer responsibility framework compliance, securing reverse logistics infrastructure before mandated collection network investments inflate capital requirements. Expand solution-dyed PET capacity to capture automotive lightweighting procurement from Tier 1 suppliers qualifying lighter assemblies. Defend against recycled-content specialists by accelerating closed-loop nylon recovery deployments.
For New Entrants and Emerging Players: The 12-18% cost premium gap between formaldehyde-free backings and conventional substrates opens white-space targeting in the education vertical, where Section 01350 compliance deadlines create urgent replacement demand. India's commercial real estate buildout in Mumbai and Bangalore offers the most penetrable geography for moisture-trap polypropylene systems. Pursue direct-to-facility specification through building information modeling integration, compressing architect decision cycles.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale tufting operations with stranded beck-dyeing assets facing waterless solution-dyed displacement. Long-term viability hinges on securing captive polymer supply or certification infrastructure that outlasts regulatory consolidation. Watch for EPA enforcement intensity on NESHAP adhesive standards as the inflection signal determining which backing formulation investments retain competitive relevance.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Captive caprolactam supply insulates Mohawk Industries from petrochemical price swings. |
| Closed-Loop Nylon Recovery Infrastructure | Interface, Inc.'s re-tufting systems lower raw material exposure and capture LEED v4.1 specification. |
| Waterless Solution-Dyed Capacity Expansion | Displacement of beck-dyeing equipment reduces water consumption and accelerates color-matching for automotive programs. |
| Extended Producer Responsibility Network Buildout | Early collection infrastructure investment in California and New York secures regulatory compliance ahead of mandates. |
| Building Information Modeling Platform Integration | Direct specification capture from Class A office developers in Chicago and San Francisco compresses distributor margins. |
Methodological Framework
Direct dialogue with automotive Tier 1 procurement managers, commercial real estate facilities directors, carpet mill operations executives, and California Department of Public Health compliance officers grounded qualitative assessment of specification trends. Secondary validation drew from EPA NESHAP regulatory filings, California Section 01350 test result databases, SEC 10-K disclosures from integrated manufacturers, and customs records tracking polypropylene fiber imports. Bottom-up triangulation across individual facility production data and top-down reconciliation against vehicle production and commercial construction forecasts ensured dimensional consistency.
Bottom-up modeling anchored volume projections to named country vehicle assembly rates, Class A office square footage completions, and hospitality corridor refurbishment cycles across the projection horizon. Segmentation dimensions included material tier, end-use vertical, certification grade, and regional regulatory cluster. CAGRs were derived from slope-consistent trajectory fitting against historical replacement cycle data and regulatory compliance deadline clustering. Industry-specific inputs encompassed MIIT cabin air-quality standard implementation timelines and REACH adhesive reformulation requirements shaping EU-bound production.
Caveats apply where caprolactam price volatility, hurricane disruption frequency in the southeastern United States, or accelerated state-level extended producer responsibility adoption could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement intensity and automotive lightweighting program continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
India Carpets and Rugs Market
Flooring, Carpets, and Rugs
Global Floor Covering Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Hardwood Flooring Market
Flooring, Carpets, and Rugs
US Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
Sheet Flooring Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
Rigid Core Flooring Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
China Luxury Vinyl Tile (LVT) Market
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Plank (LVP) Market
Flooring, Carpets, and Rugs
GCC Floor Covering Market