
 Bath Mats Market | 2026-2036
Bath Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Bath Mats Market Analysis
Natural rubber backing is decoupling from petroleum-based synthetic alternatives as volatile oil prices and sustainability mandates compress margins on PVC and polyurethane compounds. Welspun Group anchors its position through backward integration into cotton spinning and terry weaving operations in India. Williams Sonoma Inc. differentiates via curated designer collaborations and direct-to-consumer channel control in North American premium segments. American Floor Mats LLC specializes in commercial-grade anti-fatigue constructions for healthcare and institutional buyers.
Bath mats are textile floor coverings designed for moisture absorption, slip resistance, and hygiene maintenance in wet environments, typically incorporating pile heights between 15-25 millimeters and backing layers with coefficient-of-friction ratings exceeding 0.5 for safety certification. Manufacturing employs tufting, needle-punching, or woven construction with antimicrobial treatments such as silver-ion or zinc-pyrithione finishes to inhibit mold and bacterial growth. Cotton and chenille product types dominate residential value pools due to consumer preference for tactile softness and natural fiber aesthetics, while microfiber captures commercial volume through lower unit costs and faster drying properties. Memory foam segments command premium positioning in hospitality channels where guest comfort scores directly influence procurement decisions, though this category remains supply-constrained by limited domestic molding capacity.
The EU REACH regulation restricts phthalate plasticizers in rubber backing formulations, compelling reformulation investments across European supply chains. The US Consumer Product Safety Commission enforces slip-resistance testing protocols that shape product liability exposure and insurance costs for importers. China's GB standards for textile formaldehyde content create entry barriers for uncertified exporters. Stakeholders must monitor evolving chemical restriction schedules and certification reciprocity agreements between major import jurisdictions to avoid stranded inventory and compliance penalties.
Market Dynamics
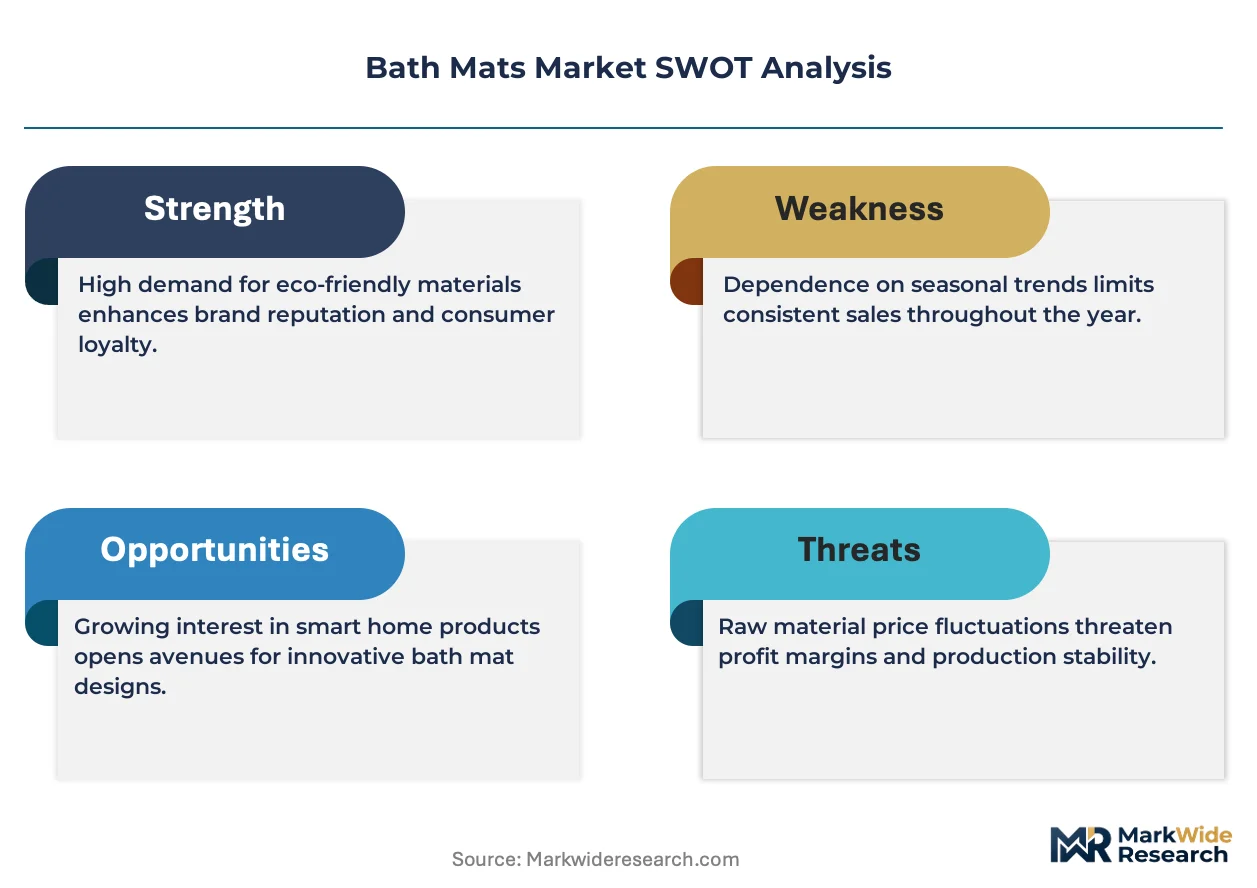
The EU Ecodesign for Sustainable Products Regulation is forcing wholesale reformulation of backing materials across European supply chains, compressing margins on conventional petroleum-based compounds while elevating recycled polyester and natural rubber alternatives into cost-competitive positions.
Growth Catalysts
- REACH chemical restrictions:Phthalate limitations in rubber backing formulations are accelerating migration toward bio-based alternatives, creating first-mover advantages for reformulated product lines.
- Hospitality hygiene protocols:Hotels are mandating antimicrobial silver-ion and zinc-pyrithione finishes, expanding procurement of certified quick-dry variants with documented mold inhibition.
- German renovation rates:Bathroom refurbishment activity exceeding regional European averages is concentrating premium home goods demand in this single national market.
Market Restraints
- Petroleum input volatility:PVC and polyurethane compound costs swing with crude oil benchmarks, eroding margin predictability for synthetic backing producers.
- Domestic molding capacity scarcity:Memory foam segments face supply constraints from limited in-house production of viscoelastic cores, throttling hospitality channel expansion.
- GB standards compliance:China's textile formaldehyde content regulations create certification barriers for uncertified exporters seeking market entry.
Strategic Opportunities
- Healthcare anti-fatigue specifications:Commercial-grade constructions with coefficient-of-friction ratings exceeding 0.5 are penetrating institutional procurement channels previously served by generic alternatives.
- Direct-to-consumer channel control:Curated designer collaborations and owned digital platforms are capturing margin pools previously ceded to wholesale intermediaries in North American premium segments.
- Backward integration into cotton spinning:Captive supply of terry weaving operations insulates against raw material cost spikes and quality variability in natural fiber segments.
Industry Challenges
- Slip-resistance certification timelines:US Consumer Product Safety Commission testing protocols extend product development cycles and elevate liability insurance costs for importers.
- Antimicrobial finish integration complexity:Silver-ion and zinc-pyrithione application processes require specialized equipment and technical expertise scarce in legacy tufting operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bath Mats Market |
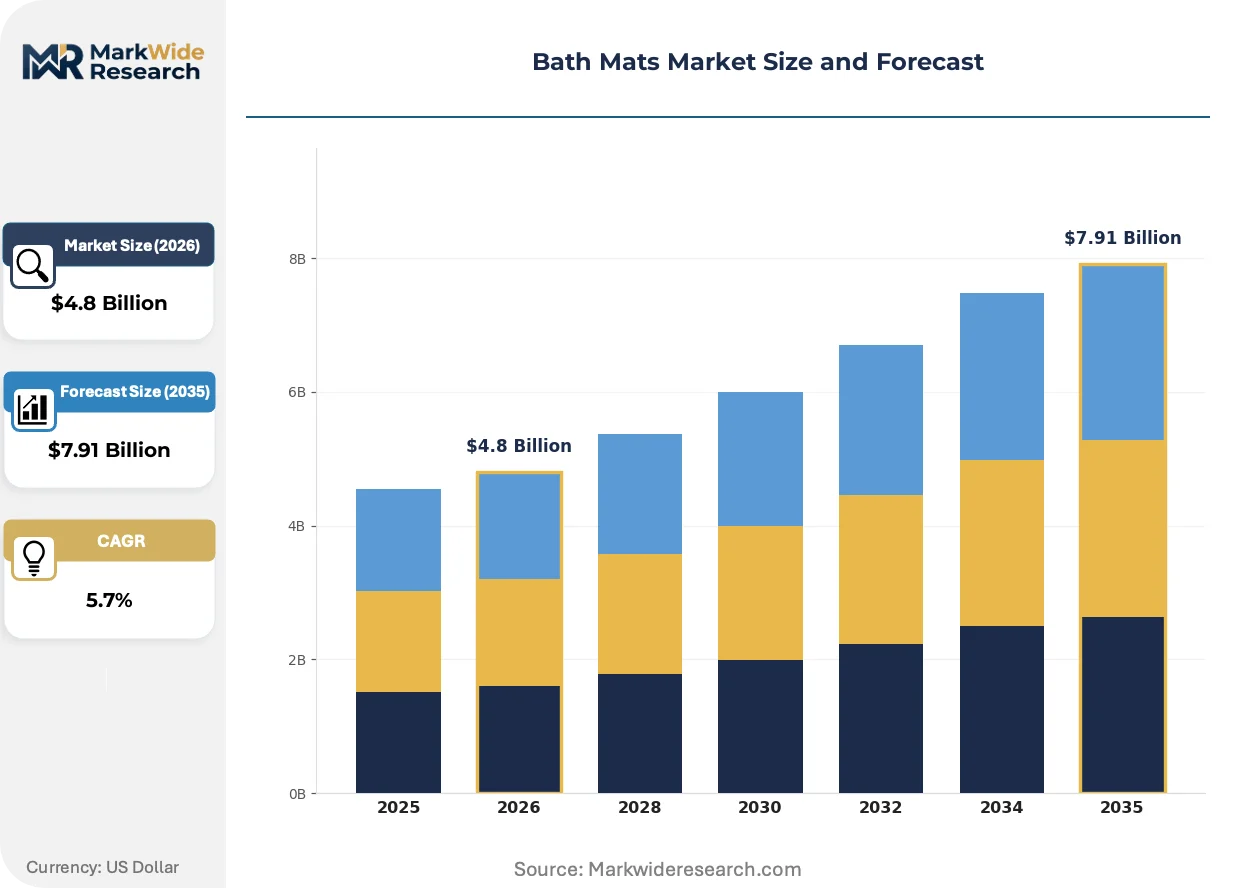
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chenille, Memory Foam, Microfiber, Cotton Material: Polyester, Nylon, Rubber, Bamboo Shape: Rectangular, Circular, Square, Oval End User: Residential, Commercial, Hospitality, Healthcare |
| Companies Covered | Inter IKEA Holding BV, Welspun Group, American Floor Mats LLC, InterDesign Inc., Williams Sonoma Inc., Apache Mills, Wayfair Inc., Kittrich Corp., Bed Bath and Beyond Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bath Mats Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to reshape competitive positioning across backing formulations, fiber selections, and antimicrobial treatment protocols in wet-environment textile applications.
Recycled polyester fiber is absorbing demand previously captured by virgin petroleum-based synthetics in commercial volume segments. Hospitality procurement teams are specifying quick-dry microfiber constructions with documented post-consumer recycled content to satisfy sustainability scorecards. This material transition is compressing margins on conventional polyester staple while elevating certified recycled alternatives into price parity through scale economies.
REACH phthalate restrictions are eliminating legacy plasticizer chemistries from European rubber backing formulations. Manufacturers are reformulating with bio-based plasticizers and natural rubber latex alternatives to maintain market access. Hospitality and healthcare segments in Germany, France, and the Netherlands are absorbing these reformulated products at premium pricing to satisfy procurement mandates.
Certification-driven specification behavior is fragmenting buyer decision criteria across safety, sustainability, and performance dimensions. Property managers and institutional procurement officers are unbundling after-sales service from product supply, selecting suppliers based on documented coefficient-of-friction test results and antimicrobial efficacy data rather than brand recognition alone. This pattern concentrates most visibly in German and US commercial renovation channels where liability exposure drives documentation requirements.
Bath Mats Market Segmentation
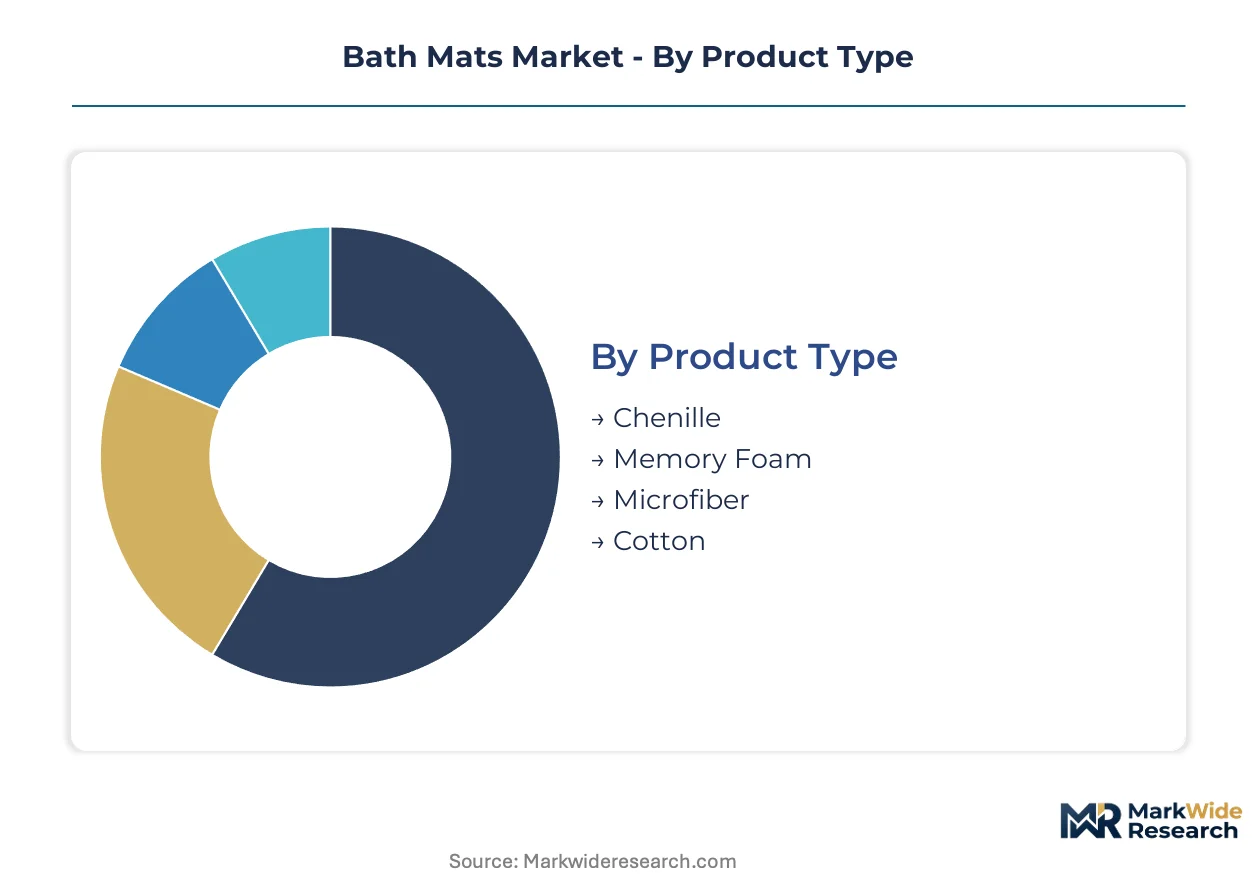
Segmentation in bath mats determines procurement specifications across divergent performance requirements. Residential buyers prioritize tactile softness and aesthetic integration, while commercial and institutional channels enforce safety certifications and antimicrobial protocols that reshape manufacturing priorities.
Product Type:
Chenille and cotton variants dominate standalone residential installations where consumer preference drives selection, while memory foam and microfiber embed into hospitality and healthcare systems with strict performance mandates.
- Chenille:Tufted polyester or acrylic yarn creates a dense, plush pile with exceptional moisture retention. German bathroom renovation channels absorb premium chenille lines at above-average price points due to consumer preference for tactile luxury. REACH-compliant dye formulations now dominate European sourcing.
- Memory Foam:Viscoelastic polyurethane cores molded to 15-25mm thickness deliver pressure relief and slip resistance. US hospitality procurement teams specify these for guest comfort scores, though domestic molding capacity scarcity constrains supply expansion. OSHA-aligned anti-fatigue specifications penetrate healthcare channels.
- Microfiber:Split-fiber polyester constructions achieve rapid drying through capillary action. Quick-dry properties satisfy commercial volume demand with lower unit economics than natural alternatives.
- Cotton:Natural fiber terry constructions absorb through hydrophilic cellulose structure. Backward integration into cotton spinning insulates major suppliers against raw material volatility.
Cotton leads volumes today; memory foam is gaining share fastest.
Material:
Material selection separates cost-driven commercial procurement from sustainability-mandated European specifications, with petroleum-based synthetics facing margin compression against bio-based alternatives.
- Polyester:Virgin and recycled staple fiber dominates commercial volume through dyeability and dimensional stability. Recycled post-consumer content now achieves price parity in hospitality sustainability scorecards.
- Nylon:Polyamide 6,6 constructions deliver superior abrasion resistance for high-traffic institutional environments. ECHA scrutiny on polymer production emissions elevates certified low-carbon alternatives.
- Rubber:Natural latex and synthetic compounds form anti-slip backing layers with coefficient-of-friction ratings exceeding 0.5. REACH phthalate restrictions force wholesale reformulation across European supply chains.
- Bamboo:Cellulose-derived viscose offers rapid renewability credentials for premium residential positioning. Limited domestic processing capacity constrains volume scaling outside Asian manufacturing clusters.
Polyester leads volumes today; bamboo is expanding most quickly.
Shape:
Geometric configurations align with bathroom fixture layouts and retail merchandising conventions, with dimensional standardization enabling mass production efficiency.
- Rectangular:Standard 17x24 inch and 21x34 inch formats align with vanity and tub placement norms. This configuration captures overwhelming residential volume through retail distribution efficiency.
- Circular:Radial symmetry accommodates pedestal sink and spa-style shower footprints. Premium positioning in designer collections commands margin premiums through aesthetic differentiation.
- Square:Modular dimensions suit compact powder rooms and European bathroom formats. German retail density concentrates demand for this geometry.
- Oval:Elongated curves soften visual lines in traditional bathroom aesthetics. Niche positioning in heritage-style residential renovations limits volume scale.
Rectangular leads volumes today; circular is climbing the fastest.
End User:
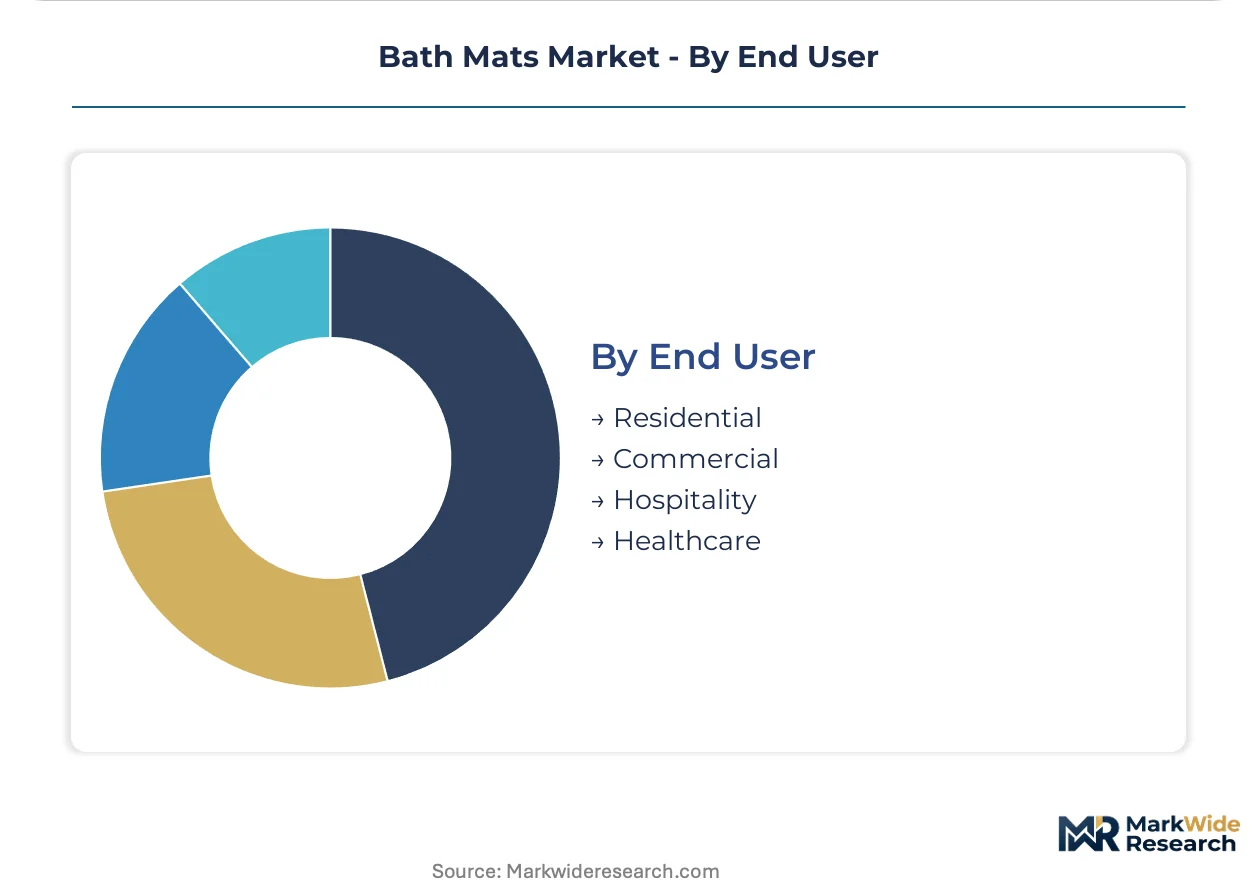
End-user categories enforce divergent certification regimes, with institutional procurement unbundling brand recognition from documented safety and antimicrobial performance.
- Residential:Consumer-driven selection prioritizes tactile softness, color coordination, and price accessibility. Cotton and chenille constructions dominate through natural fiber aesthetics and retail availability.
- Commercial:Property managers specify quick-dry microfiber with documented durability for multi-unit housing and fitness facilities. Procurement concentrates on total cost of ownership rather than unit price.
- Hospitality:Hotel chains mandate antimicrobial silver-ion finishes and slip-resistance certification. US Consumer Product Safety Commission testing protocols extend supplier qualification timelines.
- Healthcare:Anti-fatigue specifications with coefficient-of-friction ratings exceeding 0.5 penetrate hospital and long-term care procurement. Infection control protocols drive replacement frequency above residential norms.
Residential leads volumes today; healthcare is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's textile belt anchors global bath mat production through integrated cotton spinning and terry weaving clusters. Regulatory divergence across import jurisdictions is fragmenting supply chain strategies.
United States
Hospitality procurement teams mandate antimicrobial silver-ion finishes and CPSC-certified slip-resistance documentation. OSHA-aligned anti-fatigue specifications penetrate healthcare channels in California and Florida retirement corridors. Domestic molding capacity scarcity constrains memory foam expansion.
Germany
Bathroom renovation rates exceeding European averages concentrate premium chenille demand in Bavaria and North Rhine-Westphalia. REACH phthalate restrictions eliminate legacy rubber backing formulations. Hamburg retailers absorb reformulated natural rubber alternatives at premium positioning.
China
GB standards for textile formaldehyde content create certification barriers for export-oriented manufacturers in Zhejiang and Jiangsu provinces. Yangtze River Delta clusters pivot toward recycled polyester fiber production. SAMR enforcement tightens compliance timelines.
India
Welspun Group's backward integration into cotton spinning in Gujarat insulates against raw material volatility. BIS quality marks gain traction in institutional procurement. Maharashtra's hospitality construction pipeline absorbs quick-dry microfiber volumes.
United Kingdom
London property managers specify documented coefficient-of-friction ratings for multi-unit housing renovations. CE marking requirements align with EU Ecodesign pressure on backing materials. Midlands distribution hubs consolidate commercial volume procurement.
Bath Mats Market Vendor Landscape
Global majors compete with regional champions across certification capabilities and channel control. The vendor base stratifies between scale-driven integrated producers and specialist fabricators serving hospitality and healthcare niches. Three archetypes dominate: captive cotton spinners with terry weaving operations, direct-to-consumer platform operators with designer collaboration pipelines, and commercial-grade anti-fatigue specialists. Competitive moves concentrate on backward integration into fiber production and owned digital channel expansion.
Within the integrated textile tier, Welspun Group exemplifies upstream control through captive cotton operations. Williams Sonoma Inc. occupies a position on the premium-platform vector with curated designer access. American Floor Mats LLC anchors the commercial-specialist segment serving institutional procurement channels with safety-certified constructions.
| Leading Market Players |
|---|
| Inter IKEA Holding BV |
| Welspun Group |
| American Floor Mats LLC |
| InterDesign Inc. |
| Williams Sonoma Inc. |
| Apache Mills |
| Wayfair Inc. |
| Kittrich Corp. |
| Bed Bath and Beyond Inc. |
| Others |
Supply Flow & Price Mechanics
Hospitality procurement teams in Germany and the United States concentrate demand for REACH-compliant and CPSC-certified bath mat variants, anchoring a contract-based long-term offtake model that rewards documented safety credentials with pricing premiums over generic alternatives.
Pricing Analysis
Petroleum-based PVC and polyurethane compound costs swing with crude oil benchmarks, compressing margins on synthetic backing tiers while elevating natural rubber alternatives into cost-competitive positions. Three-tier pricing structure across premium, standard, and economy levels separates hospitality-grade antimicrobial finishes from residential cotton constructions and commercial microfiber volume plays. Price differentiation hinges on certification grade—REACH phthalate-compliant rubber commands premiums in Hamburg and Amsterdam channels—and volume scale, with healthcare anti-fatigue specifications absorbing cost-plus markups. Margins are tightening due to reformulation investments forced by EU Ecodesign mandates. Commercial property managers exhibit highest price sensitivity, while German bathroom renovation buyers prioritize tactile quality over unit economics.
Supply Chain Analysis
REACH phthalate restrictions and CPSC slip-resistance protocols gate supplier qualification, extending procurement timelines and elevating working capital requirements for uncertified entrants. Manufacturing concentrates in India, China, and Turkey, with Gujarat's cotton spinning clusters and Zhejiang's recycled polyester fiber plants anchoring global output. Raw material flows draw from petroleum-derived synthetic compounds, natural rubber latex, and cotton cellulose, with silver-ion antimicrobial finishes sourced from specialized chemical suppliers. Single-source vulnerability concentrates in domestic viscoelastic molding capacity for memory foam cores. Distribution runs through hospitality procurement consortiums, North American direct-to-consumer platforms, and European retail merchandising networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical restrictions in Europe and OSHA-aligned healthcare specifications in the United States create a geographic-arbitrage window for manufacturers with dual-certification capabilities, capturing margin premiums unavailable to single-jurisdiction suppliers.
For Market Incumbents: Acquire captive cotton spinning and terry weaving operations in Gujarat to insulate against raw material volatility and quality variability threatening Welspun Group's integrated position. Invest in silver-ion and zinc-pyrithione application equipment to defend hospitality channel share against emerging antimicrobial finish specialists. Backward integration into natural rubber latex processing secures REACH-compliant supply as petroleum-based alternatives face margin compression. For New Entrants and Emerging Players: EU Ecodesign for Sustainable Products Regulation in Germany, France, and the Netherlands opens a window for bio-based plasticizer formulations and recycled polyester fiber constructions previously excluded by cost barriers. Target quick-dry microfiber segments in Maharashtra's hospitality construction pipeline, where certification requirements remain less stringent than European benchmarks. Lead with documented post-consumer recycled content to satisfy sustainability scorecards penetrating procurement decisions. For Investors and Strategic Acquirers: Home goods platform operators with designer collaboration pipelines are the most active acquirer in this space, consolidating direct-to-consumer channel control and margin capture previously ceded to wholesale intermediaries. Focus on mid-scale terry weavers with BIS quality marks and latent hospitality certification capacity, positioned for institutional procurement growth. Watch German bathroom renovation permit data as an inflection indicator for premium chenille demand concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cotton Spinning | Captive terry weaving operations in Gujarat insulate Welspun Group against cellulose price spikes. |
| REACH-Compliant Rubber Reformulation | Bio-based plasticizer investments maintain Hamburg retailer access as phthalate restrictions tighten. |
| Direct-to-Consumer Platform Launch | Owned digital channels capture margin pools ceded to wholesale intermediaries in North America. |
| Antimicrobial Finish Certification | Silver-ion documentation satisfies hotel procurement mandates extending supplier qualification timelines. |
| Healthcare Anti-Fatigue Specification | OSHA-aligned constructions penetrate California and Florida retirement corridor institutional channels. |
Methodological Framework
Bottom-up hospitality and healthcare procurement modeling reconciled against top-down fiber production and terry weaving capacity tracking forms the analytical core of this study. Primary interviews with hotel procurement directors, healthcare facilities managers, cotton spinning plant operators, and antimicrobial chemical suppliers cross-validated against secondary sources including REACH restriction schedules, CPSC testing protocol filings, customs trade data for cotton and synthetic fiber flows, and EU Ecodesign implementation guidance documents. Triangulation between demand-side specification behavior and supply-side certification capacity constraints ensures segment-level precision.
Historical trendline analysis of bathroom renovation activity in Germany, hospitality construction pipelines in Maharashtra and Florida, and antimicrobial finish adoption curves in US hotel chains established baseline growth parameters. Segmentation modeling spans product type, material composition, end-user vertical, and geographic regulatory cluster, with CAGRs derived from elasticity-adjusted projection of specification-driven procurement shifts. Forecast inputs include REACH phthalate restriction phase-in timelines, domestic viscoelastic molding capacity expansion announcements, and recycled polyester fiber price parity achievement in hospitality sustainability scorecards.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden crude oil price spikes or accelerated EU chemical restriction schedules. Model assumptions reflect documented procurement behavior and certification reciprocity agreements between major import jurisdictions. A model refresh is warranted upon material change in EU Ecodesign enforcement timelines or CPSC slip-resistance protocol amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Textured Variegates Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
Decorative Rugs Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
Rugs Market
Flooring, Carpets, and Rugs
Asia Pacific Flooring Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Floor Covering Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market
Flooring, Carpets, and Rugs
United States Laminate Flooring Market
Flooring, Carpets, and Rugs
GCC Floor Covering Market