
 Global Carpet Backing Material Market | 2026-2036
Global Carpet Backing Material Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carpet Backing Material Market Foresight
Multi-source procurement for primary backing fabrics is broadening as mills hedge against polypropylene resin volatility. Shaw Industries Group sustains captive weaving capacity across Georgia and Alabama, insulating it from spot shortages in synthetic fiber supply. Mohawk Industries anchors its backing operations through backward integration into needlepunched non-woven production, while Freudenberg Performance Materials Holding GmbH competes on technical textile engineering for high-traffic commercial specifications.
Carpet backing material constitutes the structural substrate layer laminated beneath the carpet face, typically engineered from woven or non-woven polypropylene, jute, or synthetic rubber compounds to provide dimensional stability, tuft lock integrity, and moisture resistance during installation and service life. The primary industrial purpose is to secure pile yarns against delamination under rolling loads while enabling smooth seaming and adhesive bonding to subfloors. Woven polypropylene dominates volume owing to its tensile strength and recyclability in commercial recycling streams, whereas non-woven backings are gaining specification share in residential settings where cost efficiency and acoustic dampening outweigh durability premiums. Latex formulations retain entrenched positions in hospitality and public facilities despite regulatory pressure on styrene-butadiene content, while polyurethane and foam alternatives occupy niche growth corridors in healthcare and education applications seeking reduced volatile organic compound profiles.
EPA guidelines under the Toxic Substances Control Act constrain styrene-butadiene latex emissions in U.S. manufacturing facilities, compelling reformulation investments or solvent substitution programs. REACH registration requirements in Europe restrict certain phthalate plasticizers and heavy metal stabilizers in vinyl backing compounds, redirecting formulation R&D toward bio-based polyurethane precursors and recycled polyester feedstocks. Stakeholders must monitor evolving Extended Producer Responsibility frameworks in Germany and France, where carpet take-back mandates will increasingly tie backing material recyclability to market access permissions across the European Union.
Market Dynamics
REACH compliance deadlines and EPA VOC thresholds are forcing simultaneous reformulation across latex, polyurethane, and vinyl backing chemistries, compressing R&D timelines while raw material substitution costs cascade through contract pricing.
Growth Catalysts
- Commercial hospitality buildout:Hotel and resort construction across Saudi Arabia and the UAE is specifying woven polypropylene backings for durability under high foot traffic, pulling volume from traditional jute substrates.
- Extended Producer Responsibility mandates:Germany's carpet take-back legislation and France's anti-waste law are creating compliance-driven demand for recyclable mono-material backings that simplify end-of-life processing.
- Needlepunch non-woven engineering:Advances in fiber entanglement density are expanding non-woven specifications into mid-duty commercial applications previously reserved for woven constructions.
Market Restraints
- Propylene resin volatility:Woven and non-woven polypropylene backings face margin compression when feedstock prices spike, with mills unable to pass through costs under fixed-price hospitality contracts.
- Styrene-butadiene latex dependency:Despite regulatory pressure, SBR compounds retain entrenched positions in carpet tile and broadloom manufacturing due to established adhesive compatibility and tuft lock performance.
- Jute supply concentration:Bangladesh and India monopolize natural fiber backing supply, exposing buyers to monsoon-driven crop variability and port congestion risks.
Strategic Opportunities
- Healthcare specification pivot:Low-VOC polyurethane foam backings are penetrating hospital and senior living installations where indoor air quality protocols exclude traditional latex formulations.
- Captive weaving integration:Mills with in-house polypropylene fabric production can bypass merchant market volatility and customize primary backing constructions for export contract requirements.
- Bio-based polyurethane precursors:Castor oil and soy-derived polyols are gaining technical validation for backing compounds, aligning with EU Green Deal procurement preferences in public building tenders.
Industry Challenges
- Cross-functional formulation expertise:Backing suppliers must recruit chemists fluent in both polymer rheology and carpet manufacturing line speeds to optimize adhesive cure profiles without slowing tufting operations.
- Multi-jurisdiction certification lag:Simultaneous EPA, REACH, and state-level compliance testing stretches product development timelines, particularly for vinyl compounds facing phthalate restrictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carpet Backing Material Market |
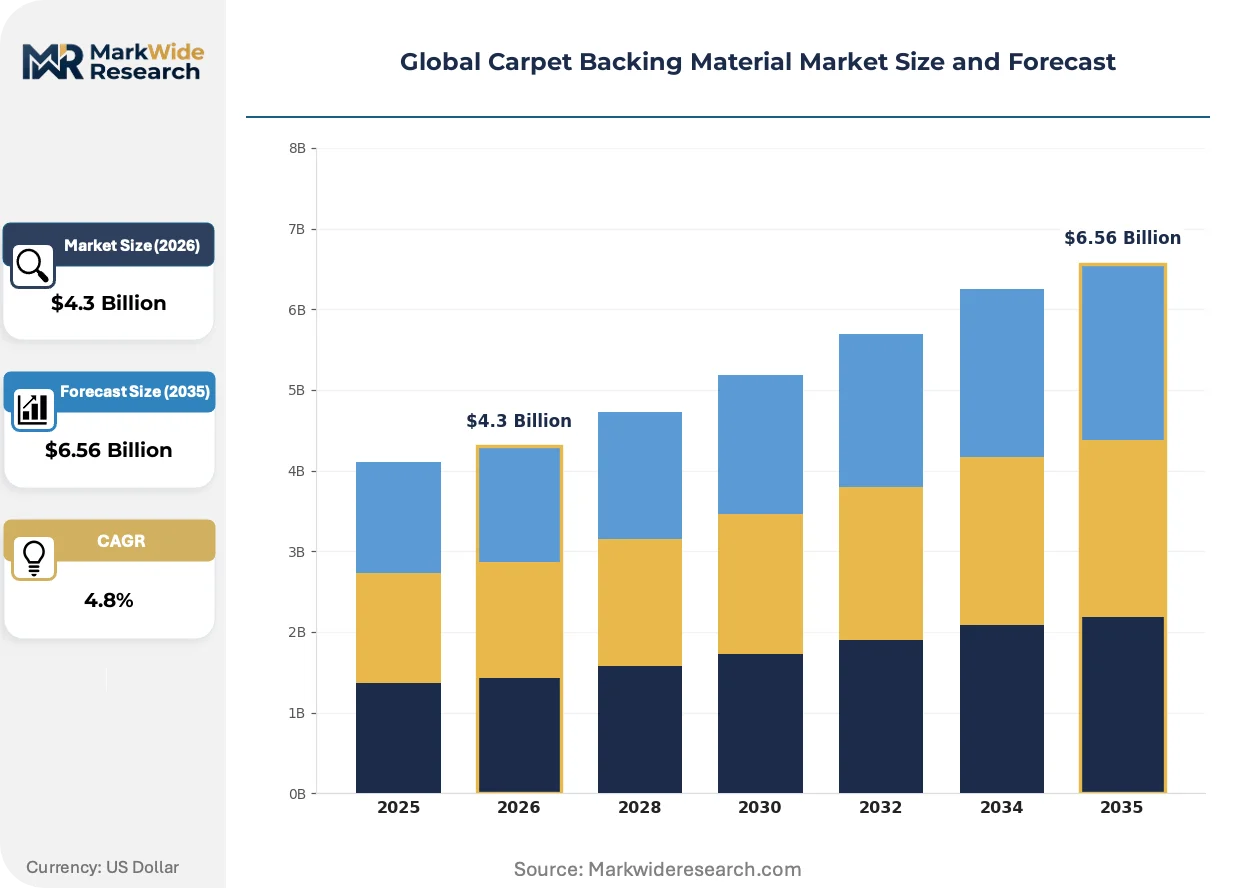
| Market Size in 2026 | $4.3 Billion |
| Market Size in 2035 | $6.56 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven, Non-Woven, Latex, Foam, Polyurethane Material Composition: Polypropylene, Polyester, Jute, Vinyl, Rubber Application: Commercial Spaces, Residential Settings, Hospitality Venues, Educational Institutions, Public Facilities End User: Interior Designers, Flooring Contractors, Distributors, Property Developers, Facility Managers |
| Companies Covered | Shaw Industries Group, Mohawk Industries, Beaulieu International Group, Interface, Inc., Tarkett, Propex, Freudenberg Performance Materials Holding GmbH, Balta Industries, Dow Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carpet Backing Material Market Shifts & Advancements
Material science advances and regulatory chemistry constraints are converging to redefine performance specifications across residential, commercial, and institutional carpet installations.
Thermoplastic polyurethane hot-melt adhesives are rewriting bonding protocols in carpet tile manufacturing. Commercial flooring contractors in North American office renovation projects are specifying TPU-backed tiles for seam integrity and dimensional stability under caster chair loads. This adhesive platform is compressing installation labor costs while eliminating solvent-based curing stations from production lines.
REACH Annex XVII restrictions on cadmium and lead stabilizers in PVC compounds are redirecting European vinyl backing production toward calcium-zinc and organotin alternatives. Compounders face reformulation validation costs without guaranteed performance parity in heavy-traffic specifications. Healthcare and education sectors in Germany and France are accelerating substitution toward TPU and bio-based alternatives ahead of enforcement deadlines.
Direct mill-to-installer procurement contracts are consolidating specification authority away from traditional distributor networks. Large hospitality and multi-family developers in China are negotiating backing performance guarantees directly with carpet manufacturers, bypassing regional stocking distributors. This channel compression is most pronounced in Guangdong and Zhejiang province manufacturing clusters where export-oriented mills maintain captive technical service teams.
Global Carpet Backing Material Market Segmentation
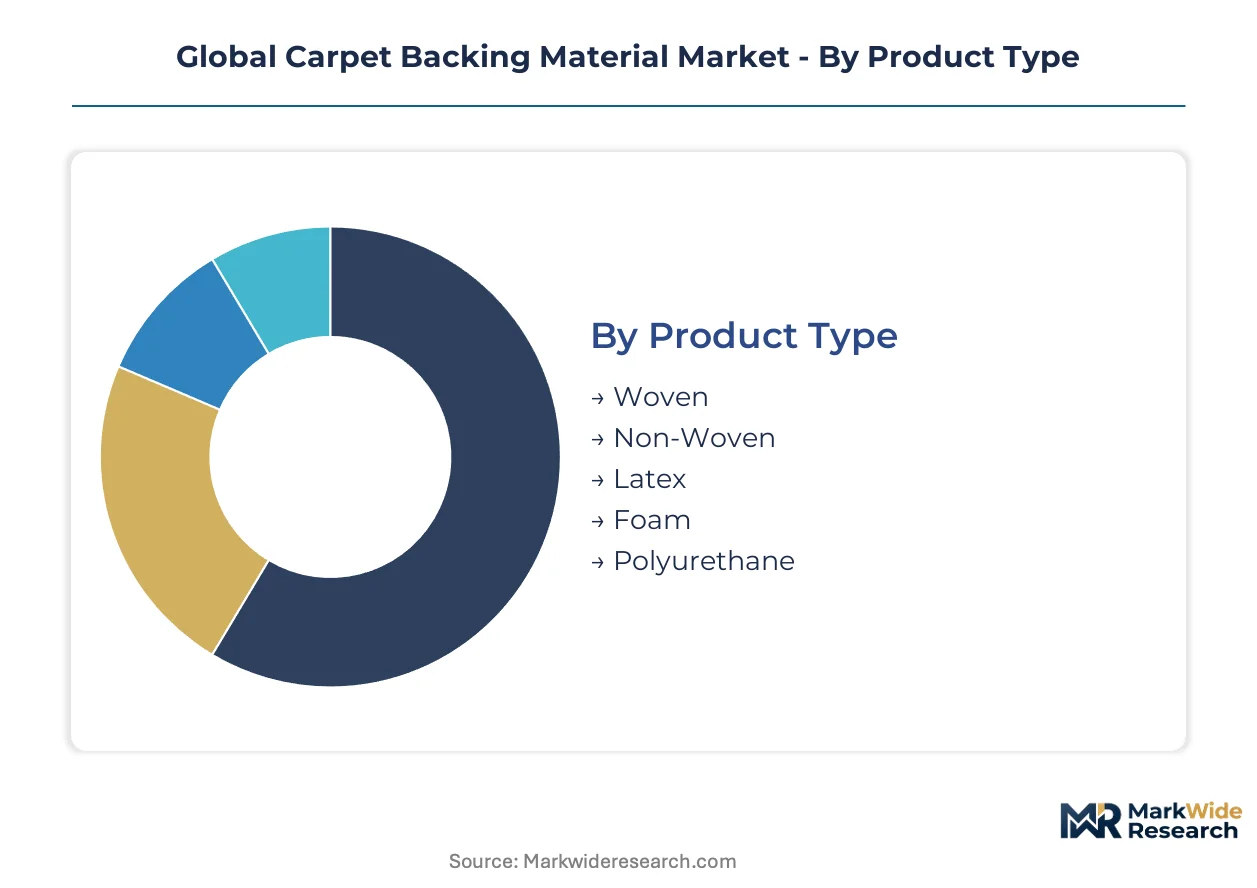
Carpet backing material selection hinges on performance specifications that vary dramatically across installation environments. Manufacturers engineer substrate layers to match durability requirements, regulatory constraints, and end-of-life processing demands specific to each use case.
Product Type:
Woven and non-woven constructions serve as standalone primary backings requiring secondary coating, while latex, foam, and polyurethane function as integrated adhesive layers bonded during lamination.
- Woven:Polypropylene tapes interlaced on shuttle looms create high-tensile substrates that withstand repeated rolling loads in airports and convention centers. Saudi Arabian hospitality developers specify woven constructions for resort lobbies and ballroom installations where dimensional stability under furniture movement is non-negotiable.
- Non-Woven:Needlepunched fiber entanglement produces cost-efficient backings with acoustic dampening properties suited to multi-family residential towers. Chinese carpet mills in Guangdong province are expanding non-woven capacity for mid-duty commercial export contracts where price sensitivity outweighs extreme durability requirements.
- Latex:Styrene-butadiene rubber compounds dominate carpet tile manufacturing despite EPA VOC constraints, with reformulation investments accelerating across U.S. production facilities.
- Foam:Polyurethane foam backings penetrate healthcare and senior living specifications where indoor air quality protocols restrict traditional adhesive chemistries.
- Polyurethane:Thermoplastic polyurethane hot-melt adhesives are displacing solvent-based systems in North American office renovation projects, compressing installation labor timelines while improving seam integrity under caster chair loads.
Woven constructions lead volumes today; polyurethane is gaining share fastest.
Material Composition:
Raw material selection determines recyclability pathways and exposure to feedstock price volatility, with synthetic fibers dominating commercial specifications and natural fibers retaining niche hospitality applications.
- Polypropylene:Dominant synthetic fiber for woven and non-woven backings, prized for tensile strength and compatibility with commercial recycling streams. Mills with captive resin processing in Georgia and Alabama insulate margins against propylene price spikes.
- Polyester:Recycled polyethylene terephthalate feedstocks are gaining technical validation for non-woven needlepunch applications, aligning with EU Green Deal procurement preferences in German public building tenders.
- Jute:Natural fiber backing concentrated in Bangladesh and India supply chains, exposed to monsoon-driven crop variability and Chittagong port congestion risks that disrupt just-in-time delivery to European weavers.
- Vinyl:PVC compounds face REACH Annex XVII restrictions on cadmium and lead stabilizers, redirecting European production toward calcium-zinc alternatives without guaranteed performance parity in heavy-traffic specifications.
- Rubber:Synthetic rubber backings retain entrenched positions in transportation and industrial matting where oil resistance and anti-fatigue properties justify material premiums.
Polypropylene commands the largest volume position; recycled polyester is climbing the fastest.
Application:
Installation environment dictates backing performance requirements across traffic density, moisture exposure, and acoustic specifications, with commercial and hospitality segments driving woven polypropylene demand.
- Commercial Spaces:Office towers and retail environments specify woven polypropylene backings for dimensional stability under rolling loads, with TPU-bonded carpet tiles penetrating North American renovation markets.
- Residential Settings:Cost-optimized non-woven backings dominate multi-family construction where acoustic dampening and installation speed outweigh extreme durability premiums.
- Hospitality Venues:Hotel and resort construction across the UAE and Saudi Arabia is pulling specification upgrades toward woven polypropylene, displacing traditional jute substrates in ballroom and corridor applications.
- Educational Institutions:K-12 and university facilities balance budget constraints with maintenance cycles, specifying mid-duty non-woven constructions for classroom and administrative areas.
- Public Facilities:Government buildings and transportation hubs face extended producer responsibility mandates in Germany and France, driving demand for mono-material backings that simplify end-of-life processing.
Commercial spaces anchor current volume; hospitality venues are expanding most quickly.
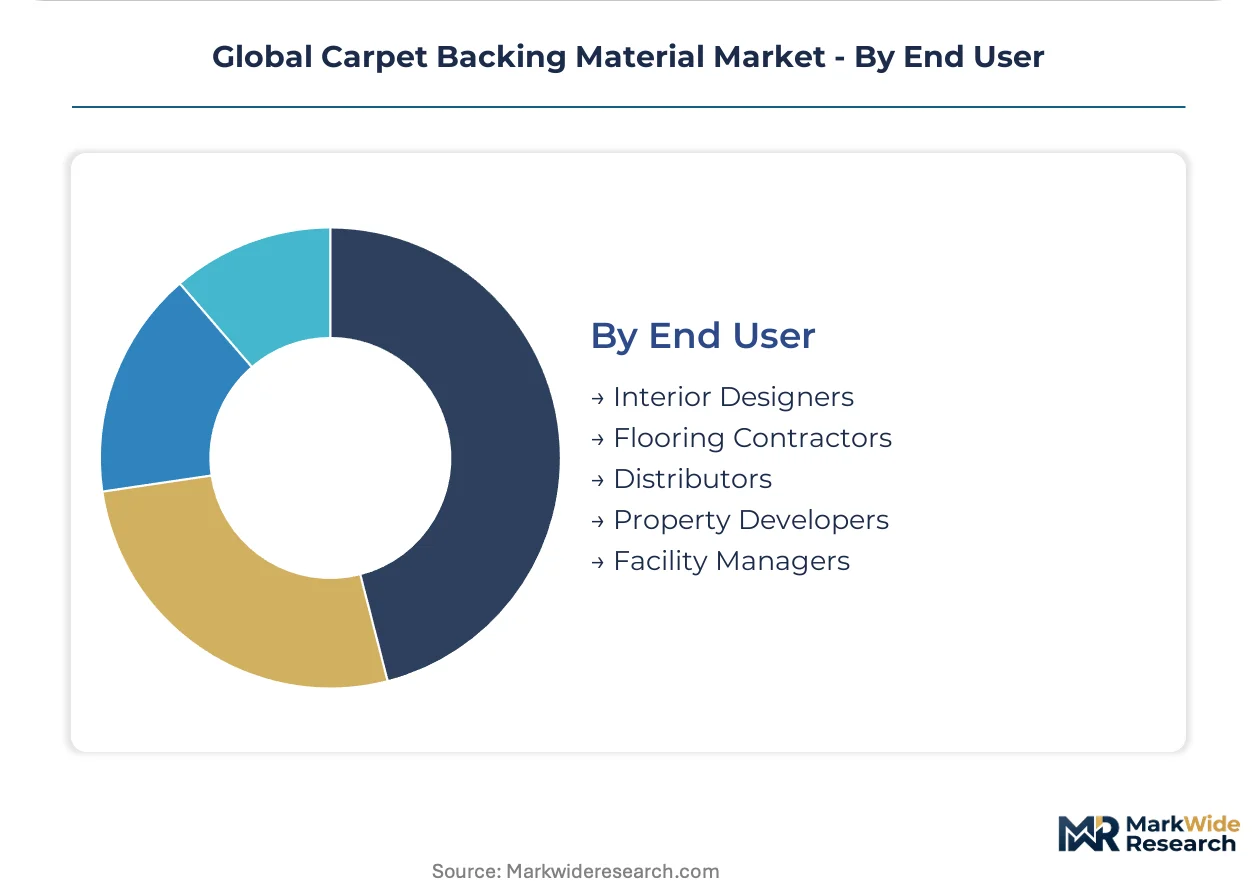
End User:
Procurement authority is consolidating toward direct mill relationships as large developers bypass traditional distributor networks, reshaping how backing specifications are negotiated and enforced.
- Interior Designers:Specification consultants increasingly prioritize low-VOC backing options for healthcare and wellness projects, influencing material selection upstream in the project timeline.
- Flooring Contractors:Installation crews favor TPU-backed carpet tiles for seam integrity and reduced adhesive curing times, compressing project schedules in competitive bid environments.
- Distributors:Regional stocking networks are losing influence as Chinese property developers negotiate directly with Guangdong and Zhejiang mills for export contract performance guarantees.
- Property Developers:Large multi-family and hospitality developers in China are consolidating procurement through captive technical service teams, bypassing traditional channel intermediaries.
- Facility Managers:Building operations teams prioritize backing durability for lifecycle cost management, with recyclable mono-material specifications gaining traction under extended producer responsibility frameworks.
Property developers are consolidating procurement authority fastest; flooring contractors remain the most specification-sensitive segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting carpet backing production toward jurisdictions with lower compliance costs, as REACH and EPA constraints compress margins in mature markets while export-oriented manufacturing clusters absorb displaced capacity.
United States
Commercial office renovation cycles in Texas and California are specifying TPU-backed carpet tiles for reduced installation timelines. EPA guidelines under the Toxic Substances Control Act constrain styrene-butadiene latex emissions, compelling reformulation investments across Georgia and Alabama weaving facilities. Shaw Industries Group sustains captive polypropylene fabric production across these southeastern states, insulating operations from merchant resin volatility.
Germany
Extended Producer Responsibility mandates under the German Packaging Act are creating compliance-driven demand for recyclable mono-material backings in public facility tenders. ECHA REACH Annex XVII restrictions on cadmium and lead stabilizers redirect vinyl backing production toward calcium-zinc alternatives. The Rhine-Ruhr industrial corridor hosts compounders validating bio-based polyurethane precursors for healthcare specifications ahead of enforcement deadlines.
China
Domestic carpet mills in Guangdong and Zhejiang provinces are expanding captive backing production for commercial export contracts to Middle Eastern hospitality developers. MEE environmental inspections tighten VOC thresholds for latex-based formulations, accelerating solvent substitution programs. The Pearl River Delta manufacturing cluster concentrates needlepunched non-woven capacity serving mid-duty commercial specifications where price sensitivity outweighs durability premiums.
Saudi Arabia
Hotel and resort construction across Riyadh and the Red Sea coast is specifying woven polypropylene backings for durability under high foot traffic, displacing traditional jute substrates. SFDA building material standards align with EU REACH frameworks for indoor air quality in hospitality venues. The King Abdullah Economic City development zone anchors specification authority as large developers negotiate directly with Guangdong mills for performance guarantees.
India
Natural fiber backing supply from Bangladesh and India faces monsoon-driven crop variability that disrupts just-in-time delivery to European weavers. BIS certification requirements for imported synthetic backings create technical barriers for Chinese exporters penetrating domestic commercial markets. The Surat textile cluster in Gujarat state processes jute and recycled polyester feedstocks for regional carpet manufacturers serving institutional and educational specifications.
Global Carpet Backing Material Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based formulation niches and captive weaving integration. The vendor base stratifies across three tiers: integrated carpet manufacturers with in-house backing operations, independent technical textile specialists, and regional compounders serving price-sensitive export markets. Strategic archetypes include backward-integrated mills controlling resin-to-fabric supply chains, formulation houses pivoting toward low-VOC polyurethane systems, and merchant market suppliers exposed to polypropylene price volatility. Competitive moves concentrate on captive capacity expansion and certification pre-positioning ahead of EPR enforcement deadlines.
Among North American integrated manufacturers, Shaw Industries Group and Mohawk Industries exemplify the backward-integrated archetype, anchoring the premium tier through in-house polypropylene weaving and needlepunched non-woven production. Freudenberg Performance Materials Holding GmbH occupies a distinct position as a European technical textile specialist, competing on engineering specifications for high-traffic commercial installations. These three entities represent contrasting strategic postures: captive supply security versus merchant market technical differentiation.
| Leading Market Players |
|---|
| Shaw Industries Group |
| Mohawk Industries |
| Beaulieu International Group |
| Interface, Inc. |
| Tarkett |
| Propex |
| Freudenberg Performance Materials Holding GmbH |
| Balta Industries |
| Dow Chemical |
| Others |
Supply & Pricing Matrix
Polymer chemist concentrations in the Rhine-Ruhr corridor and Guangdong province create labor-cost differentials that widen pricing spreads between REACH-compliant European formulations and export-oriented Chinese production. Mills with captive weaving operations in Georgia and Alabama compress these spreads through upstream control over resin-to-fabric conversion.
Pricing Analysis
Distributor margins compress as direct mill-to-developer procurement consolidates specification authority in Middle Eastern hospitality and Chinese multi-family construction. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified low-VOC polyurethane systems from reformulated latex compounds and commodity non-woven constructions. Pricing pressure stems from propylene resin volatility that mills cannot pass through under fixed-price hospitality contracts. Property developers in Saudi Arabia and the UAE demonstrate lowest price sensitivity, prioritizing woven polypropylene durability guarantees over unit cost.
Supply Chain Analysis
End-of-life carpet flows into European mechanical recycling facilities are reshaping raw material sourcing toward mono-material polypropylene constructions that bypass complex separation costs. Primary supply concentrates in China, the United States, and Germany, with Bangladesh and India anchoring natural fiber jute backing. Production draws from propylene resin, styrene-butadiene rubber compounds, and castor oil-derived polyols. Single-source vulnerability in Bangladeshi jute exposes European weavers to monsoon-driven crop failures and Chittagong port congestion. Distribution runs through direct technical service teams at Guangdong and Zhejiang mills serving export contracts, bypassing traditional regional stocking networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
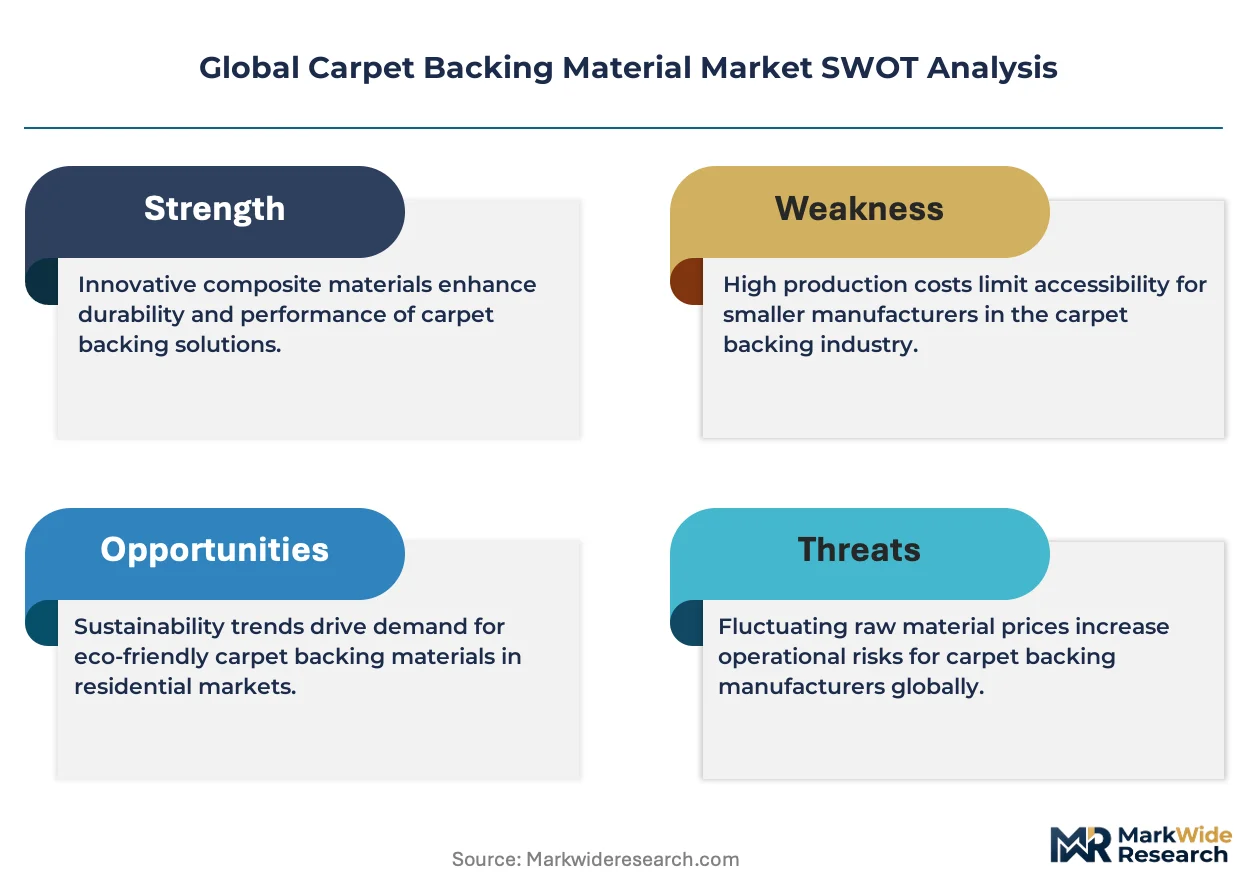
This market reads as a late-cycle quality story where hospitality specification upgrades toward woven polypropylene durability are displacing commodity jute substrates. Premium backing systems command widening spreads as regulatory compliance costs concentrate in formulation-intensive segments.
For Market Incumbents: Extend captive weaving capacity across southeastern United States manufacturing clusters to insulate margins against propylene resin spot volatility. Deepen backward integration into needlepunched non-woven production for mid-duty commercial specifications where Chinese mills are gaining export share. Prioritize REACH pre-certification investments ahead of Extended Producer Responsibility enforcement deadlines in Germany and France.
For New Entrants and Emerging Players: Healthcare facility managers represent an underserved buyer archetype seeking low-VOC polyurethane foam backings excluded from traditional latex supply relationships. Penetrate hospital and senior living specifications through indoor air quality protocol alignment. Target German public building tenders where EU Green Deal procurement preferences favor bio-based polyurethane precursors. Lead with castor oil and soy-derived polyol technical validation as the primary go-to-market angle.
For Investors and Strategic Acquirers: Integrated carpet manufacturers with in-house backing operations are the most active acquirers in this space, consolidating captive supply security ahead of formulation R&D timeline compression. Long-term viability centers on backward-integrated assets controlling resin-to-fabric conversion with multi-jurisdiction certification positioning. Watch for EPA enforcement acceleration on styrene-butadiene latex emissions as the inflection signal indicating reformulation investment urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Weaving | Shaw Industries and Mohawk Industries insulate margins against polypropylene resin volatility through in-house Georgia and Alabama fabric production. |
| REACH Pre-Certification Investment | Freudenberg Performance Materials accelerates calcium-zinc stabilizer validation ahead of ECHA Annex XVII cadmium and lead restrictions. |
| Bio-Based Polyurethane Precursor Development | Rhine-Ruhr compounders align castor oil-derived polyols with EU Green Deal procurement preferences in German healthcare tenders. |
| Direct Mill-to-Developer Technical Service | Guangdong and Zhejiang mills bypass distributor networks to negotiate performance guarantees with Saudi Arabian hospitality developers. |
| Mono-Material Backing Specification | German and French carpet take-back mandates create compliance-driven demand for recyclable polypropylene constructions simplifying end-of-life processing. |
Research Methodology
Multiple input streams — technical textile engineering directors, hospitality procurement leads at Middle Eastern developers, carpet manufacturing plant managers, and REACH compliance officers — were reconciled against secondary validation from customs trade data, ECHA registration databases, EPA Toxic Substances Control Act filings, and SEC 10-K disclosures. Primary fieldwork captured formulation R&D timelines and captive capacity expansion plans. Bottom-up segment sizing triangulated against top-down market value reconstruction across woven, non-woven, latex, foam, and polyurethane product categories.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through segmented modeling of material composition, application environment, and end-user procurement authority. Segmentation dimensions included product construction type, synthetic versus natural fiber feedstock, installation traffic density specification, and direct versus distributor channel structure. CAGRs derived from installation base growth, replacement cycle compression, and specification upgrade elasticities in hospitality and healthcare verticals. Forecast inputs incorporated propylene resin price trajectory assumptions and EPR enforcement timeline uncertainty.
Underlying measurement precision varies by segment; woven polypropylene and REACH-compliant polyurethane systems carry tighter precision than emerging bio-based alternatives and reformulated latex compounds. Forecasts reflect assumptions on regulatory enforcement acceleration and raw material substitution cost pass-through feasibility. Practitioners should monitor EPA VOC threshold announcements and German Packaging Act implementation guidance for early signals of formulation investment urgency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
North America Decor Paper Market
Paper Products
Greaseproof Paper Sheets Market
Paper Products
Global Thin Papers Market
Paper Products
Pp Synthetic Paper Market
Paper Products
Europe Thermal Paper Market
Paper Products
Medical Grade Paper Market
Paper Products
Digital Printing Paper Market
Paper Products
Filtration Paper Market
Paper Products
Semi Chemical Wood Pulp Market
Paper Products
Saturated Kraft Paper Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Asia-Pacific Thermal Paper Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Wood Paper and Paperboard Recycling Market
Paper Products
Inlay Paper Market
Paper Products
Polyester Synthetic Paper Market