
 Digital Printing Paper Market | 2026-2036
Digital Printing Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Printing Paper Market Outlook
Asset-light leasing models for high-speed inkjet presses is rewriting capital requirements for mid-size print shops entering the digital paper supply chain. Hewlett-Packard Development Company leverages its PageWide technology to dominate continuous-feed installations in North America. Canon anchors its position through integrated media certification programs that lock in substrate specifications. Seiko Epson Corporation specializes in water-based pigment systems that constrain paper porosity requirements.
Digital printing paper comprises engineered substrates optimized for toner adhesion, ink absorption, and heat stability across electrophotographic and inkjet processes, with surface energy typically calibrated between 38 and 48 dynes per centimeter for reliable image transfer. Uncoated grades lead volume in transactional and direct-mail applications where postal optimization drives lightweight specifications. Specialty segments command margin pools in security printing and pharmaceutical labeling where tamper-evidence and traceability layers add functional value. Coated stocks compete for share in commercial brochure and catalog work where color gamut and gloss uniformity determine buyer selection.
FDA regulations govern direct-contact food packaging substrates in the United States, restricting mineral oil migration from recycled fiber streams. EPA guidelines on volatile organic compound emissions from coating operations shape domestic manufacturing investment patterns. ISO 12647 color management standards harmonize print buyer expectations across continental supply chains. Stakeholders must monitor how E.U. Deforestation Regulation due diligence requirements cascade through pulp sourcing contracts for European-bound shipments.
Market Dynamics
The transition from offset to inkjet production workflows is collapsing legacy capacity planning models across commercial print operations. This substrate-technology coupling now dictates mill investment priorities and regional sourcing patterns.
Growth Catalysts
- REACH compliance mandates:European chemical disclosure requirements for coated grades are accelerating certified substrate qualification programs among pulp suppliers serving the continent.
- Direct-mail postal optimization:Lightweight uncoated specifications are driving volume demand as mailers minimize per-piece distribution costs across North American and Asian markets.
- China's installed base expansion:Production-class digital press deployments in industrial zones near Shanghai and Shenzhen are concentrating regional demand for engineered inkjet substrates.
Market Restraints
- Pulp cost volatility:Hardwood fiber price swings constrain margin stability for uncoated grade producers dependent on South American supply contracts.
- Coating chemical concentration:Specialty additive suppliers in Germany and Japan control critical surface energy modification chemistries, creating single-source vulnerability.
- Mineral oil migration limits:FDA restrictions on recycled fiber streams for food-contact applications block substrate reuse pathways in US packaging segments.
Strategic Opportunities
- Security printing applications:Tamper-evidence and traceability layer integration offers margin expansion in pharmaceutical labeling and tax stamp segments.
- India's commercial print modernization:Mid-size print shop digitization in Mumbai and Delhi corridors presents untapped demand for certified toner-compatible stocks.
- Water-based pigment convergence:Seiko Epson's ink chemistry specifications are opening substrate development partnerships with mills capable of porosity engineering.
Industry Challenges
- ISO 12647-2 certification timelines:Color management standard compliance delays market entry for regional substrate suppliers lacking accredited testing facilities.
- Legacy electrophotographic integration:Hybrid print environments require dual-certified stocks, complicating inventory management and specification harmonization.
- Heat stability engineering gaps:Toner fusion temperature requirements versus inkjet drying profiles demand separate production lines, fragmenting mill capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Printing Paper Market |
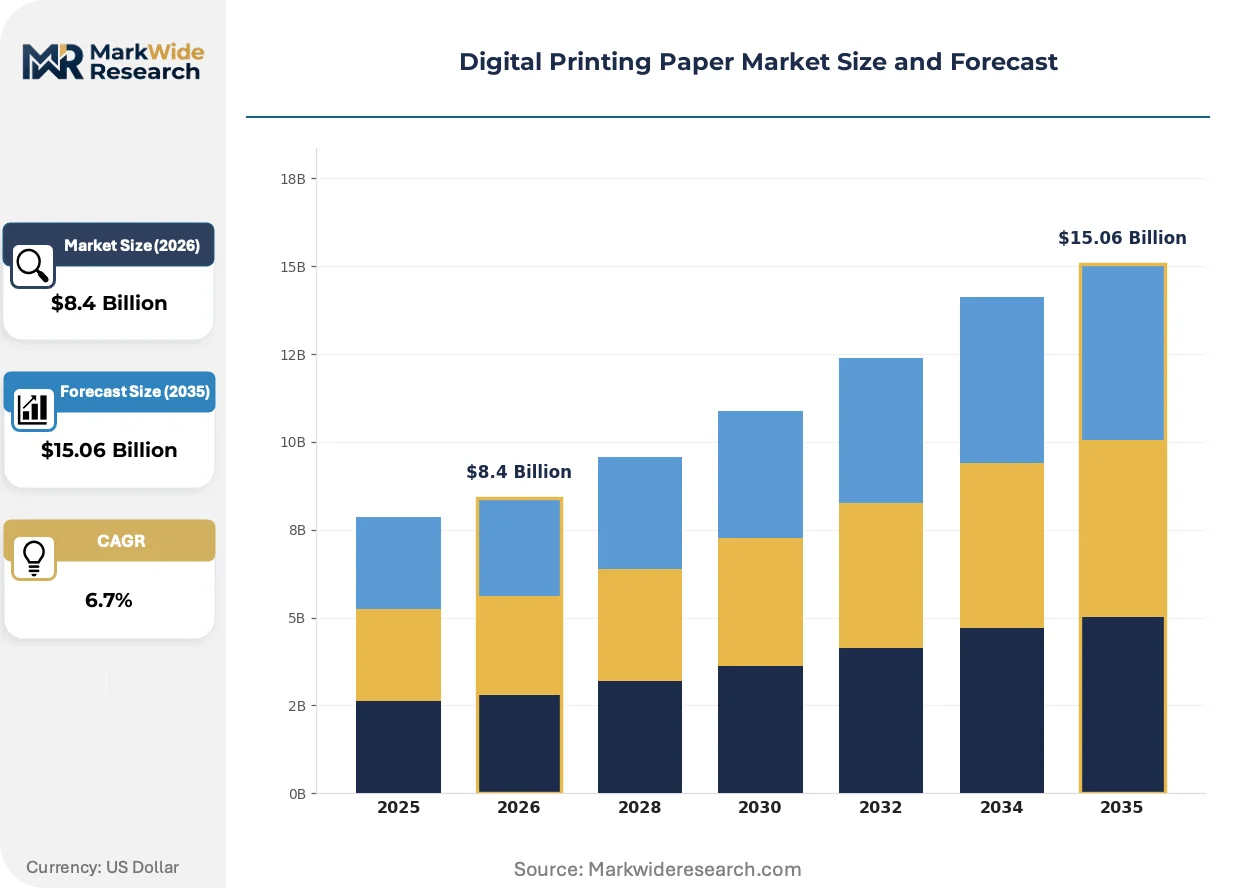
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated, Uncoated, Specialty, Recycled End User: Commercial Printing, Packaging, Publishing, Advertising Application: Brochures, Flyers, Labels, Signage Size: A4, A3, 12x18, Custom |
| Companies Covered | Hewlett-Packard Development Company, Canon, Xerox Corporation, Ricoh Company, Seiko Epson Corporation, Mimaki Engineering, Roland DG Corporation, Brother Industries, Konica Minolta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Printing Paper Market Strategic Shifts
Inkjet press manufacturers are rewriting substrate specifications faster than traditional mills can reformulate coating recipes. This velocity gap is compressing the competitive window for legacy suppliers.
Continuous-feed inkjet web technology is collapsing the distinction between transactional and commercial print quality tiers. Transactional mailers in the United States and Germany now specify coated stocks previously reserved for catalog work, forcing substrate producers to bridge price-performance gaps. Mills serving this crossover demand must retool surface chemistry lines without fully amortized offset-grade capacity.
EU Deforestation Regulation due diligence requirements are reshaping pulp sourcing contracts for European-bound shipments. The regulation mandates geolocation traceability for all fiber inputs, compelling substrate producers to audit plantation documentation across Brazilian and Indonesian supply chains. Coated grade manufacturers with integrated pulp operations gain compliance timeline advantages over merchant converters.
Print buyers are consolidating supplier relationships around media certification programs that lock in substrate specifications. Canon's integrated certification model in Japan and North America now influences procurement criteria beyond hardware compatibility, favoring mills with dedicated R&D partnerships. This behavioral shift concentrates volume among certified substrate portfolios and marginalizes independent grade suppliers lacking press manufacturer endorsements.
Digital Printing Paper Market Segmentation
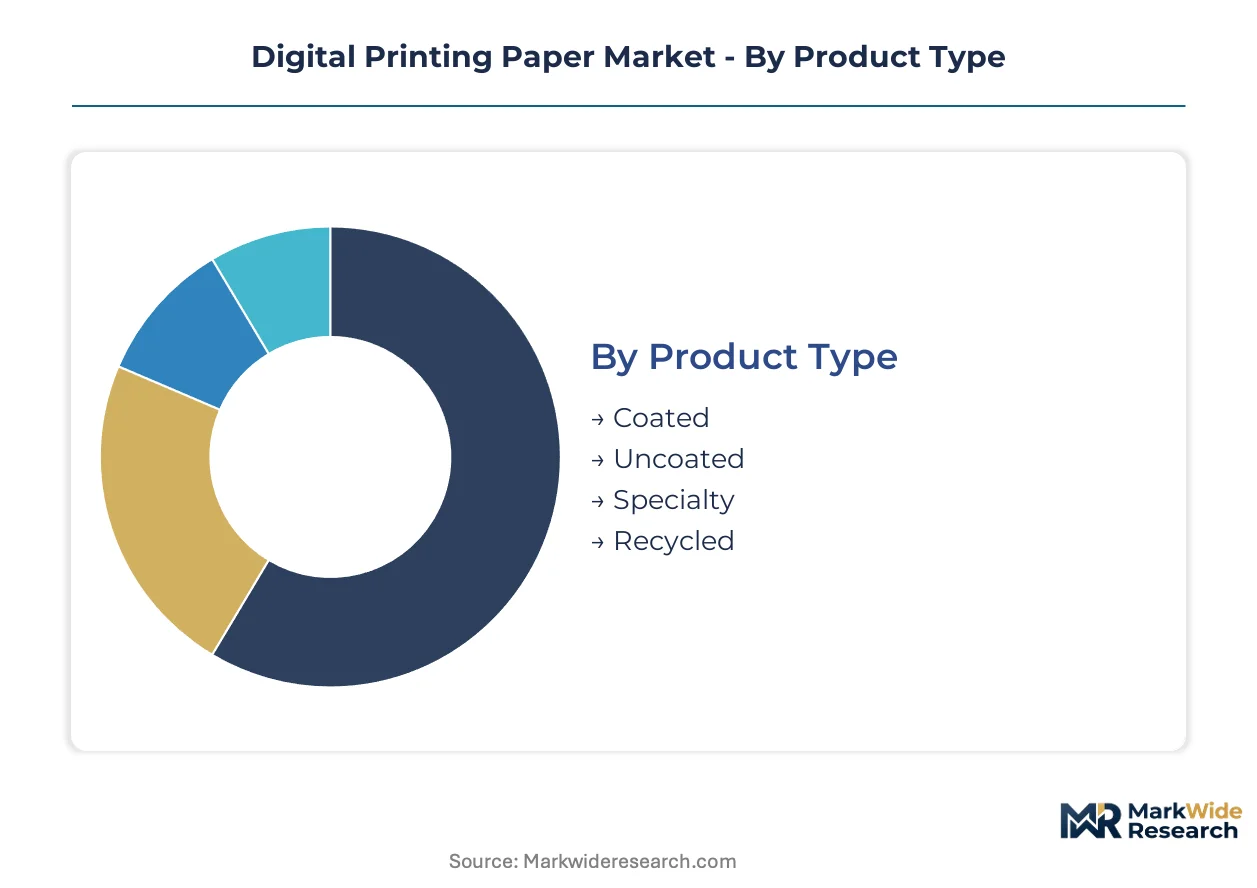
Segmentation in digital printing paper determines specification pathways, capital allocation at mills, and certification requirements for press compatibility. Each dimension carries distinct margin profiles and technical barriers that reshape competitive positioning across supply tiers.
Product Type:
After-sales service intensity varies sharply across product types, with coated grades demanding ongoing color calibration support and specialty stocks requiring application engineering consultation throughout the contract lifecycle.
- Coated:Clay and calcium carbonate surface treatments create controlled porosity for inkjet droplet fixation and toner adhesion. German commercial print clusters specify these grades for catalog work where ISO 12647-2 color conformance determines supplier selection. REACH compliance timelines for coating chemistry disclosure now stretch qualification cycles.
- Uncoated:Lightweight groundwood and freesheet constructions dominate transactional mail in the United States where postal rate optimization drives basis weight minimization. These grades bypass coating line capital but require precise fiber engineering to manage ink spread and show-through.
- Specialty:Security substrates with tamper-evidence layers serve pharmaceutical labeling and tax stamp applications in Switzerland and Brazil.
- Recycled:Post-consumer fiber streams face FDA mineral oil migration limits that block food-contact deployment in US packaging segments.
Uncoated holds the largest share; momentum sits with specialty.
End User:
Cost tier stratification separates end user segments, with packaging commanding premium pricing for regulatory-compliant substrates while commercial printing operates on thinner margins sensitive to pulp cost swings.
- Commercial Printing:Mid-size print shops in India and Mexico are digitizing workflows, creating demand for dual-certified stocks compatible with hybrid electrophotographic and inkjet environments. These buyers consolidate supplier relationships around press manufacturer certification programs.
- Packaging:Direct-contact food applications in the United States face FDA substrate restrictions that favor virgin fiber streams over recycled alternatives. E.U. Deforestation Regulation due diligence now extends to pulp sourcing for European-bound pharmaceutical cartons.
- Publishing:Educational and trade book segments in Japan specify lightweight uncoated grades for short-run digital backlist replenishment.
- Advertising:Point-of-sale display producers in China favor coated stocks with gloss uniformity for brand color matching.
Commercial printing absorbs the highest volume; packaging climbs the fastest on regulatory premium capture.
Application:
Application segmentation tracks directly to finishing equipment compatibility and postal logistics, with labels and flyers representing opposite ends of the value-add spectrum.
- Brochures:Multi-page folded formats require crease-recovery specifications and cross-grain dimensional stability. French and Italian luxury goods marketers specify heavyweight coated stocks with soft-touch lamination compatibility.
- Flyers:Single-sheet promotional formats in North American direct mail optimize for lightweight uncoated construction to minimize per-piece distribution cost. These specifications prioritize postal machinability over print fidelity.
- Labels:Pressure-sensitive and wet-glue constructions for pharmaceutical and food applications face migration testing requirements under FDA and EFSA frameworks.
- Signage:Wide-format inkjet displays specify synthetic and photo-base substrates with outdoor durability coatings.
Flyers maintain volume leadership; labels show steepest expansion trajectory on pharmaceutical traceability mandates.
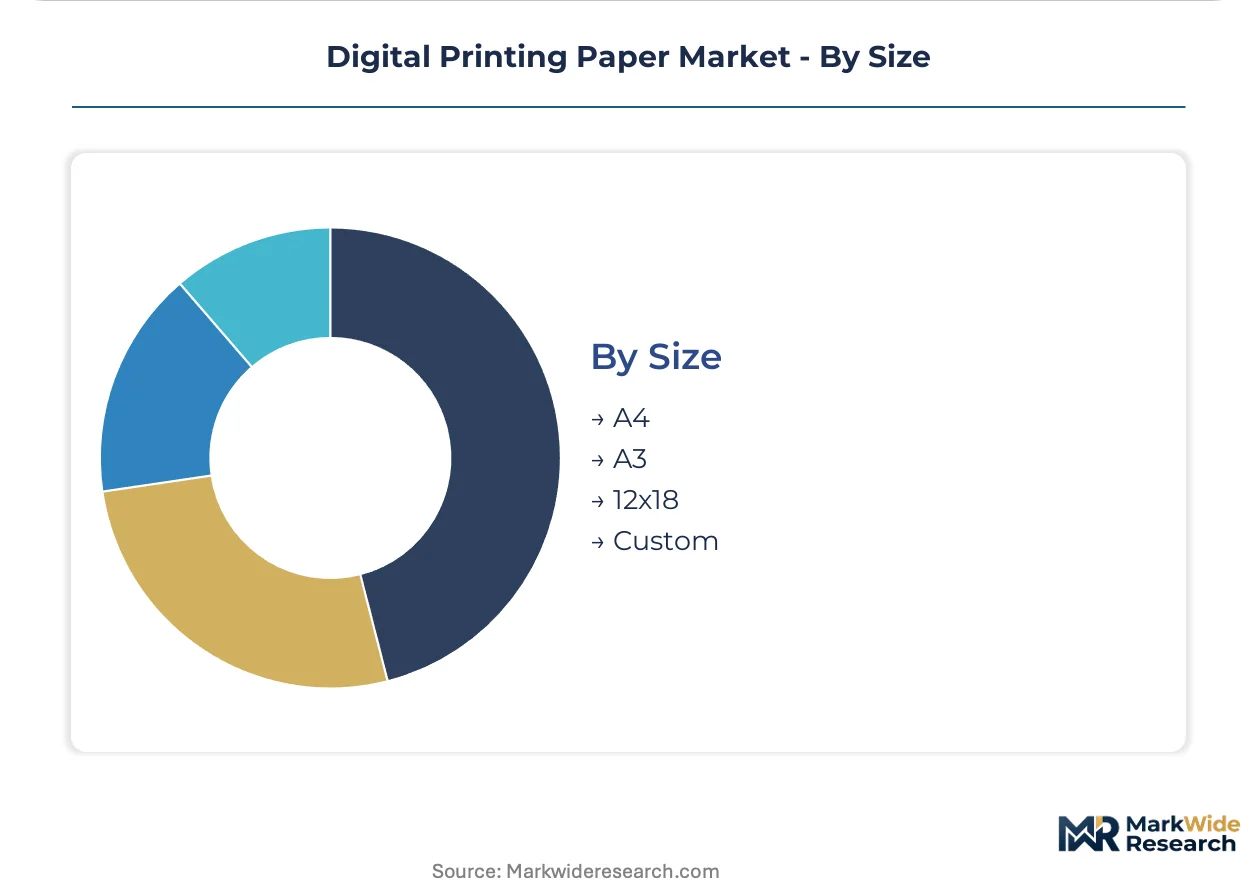
Size:
Size segmentation determines press web width utilization and finishing automation compatibility, with custom formats extracting premium pricing for die-cut and specialized binding workflows.
- A4:The ISO 216 standard dominates office and transactional applications across European and Asian markets. German and Chinese production inkjet installations optimize running schedules around this format's sheet efficiency.
- A3:Tabloid-equivalent dimensions serve marketing collateral and technical documentation where expanded visual field justifies substrate cost increase.
- 12x18:North American commercial print standard enables two-up A4 imposition with bleed allowances for cross-over campaigns.
- Custom:Die-cut dimensional formats for packaging prototypes and display graphics command specification engineering fees and extended lead times.
A4 commands the installed base; custom formats gain share on packaging sample and prototyping demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial print buyers cluster in industrial corridors where production-class digital press installations create concentrated substrate demand. Postal optimization mandates and regulatory compliance programs reshape procurement patterns across national boundaries.
United States
Direct-mail volume and transactional print sustain uncoated grade consumption as USPS rate structures reward lightweight specifications. EPA volatile organic compound guidelines constrain domestic coating operations, favoring mills with emission-controlled production lines. Chicago and Dallas-Fort Worth corridors host dense clusters of mid-size print shops converting to inkjet workflows.
Germany
Catalog and commercial brochure producers specify ISO 12647-2 compliant coated stocks with precise color conformance requirements. REACH chemical disclosure mandates extend qualification timelines for imported substrates, privileging domestic mills with integrated certification. The Rhine-Ruhr and Stuttgart industrial zones concentrate Europe's largest installed base of continuous-feed inkjet systems.
China
Packaging sample prototyping and short-run commercial work drive coated stock demand in coastal manufacturing zones. SAMR standards on food-contact paper substrates restrict recycled fiber deployment in export-bound shipments. Shanghai and Shenzhen industrial districts anchor production-class press deployments requiring engineered inkjet substrates.
Japan
Educational publishing and photobook segments sustain demand for lightweight uncoated grades with precise dimensional stability. METI guidelines on carbon footprint disclosure influence mill sourcing decisions for pulp inputs. The Kanto region around Tokyo maintains the highest density of certified media programs locking in substrate specifications.
India
Mid-size commercial print modernization in Mumbai and Delhi corridors creates demand for dual-certified stocks compatible with hybrid print environments. BIS standards on paper permanence and print durability shape qualification requirements for imported substrates. Gujarat and Maharashtra industrial zones concentrate new inkjet press installations serving domestic brand marketing campaigns.
Digital Printing Paper Market Competitive Environment
Channel-controlling players compete with product-specialist players across certification-driven procurement hierarchies. The structure tilts toward concentrated volume at the top tier, with hardware-integrated media programs capturing recurring substrate commitments. Three archetypes dominate: press manufacturers with captive certification ecosystems, merchant converters with multi-brand portfolios, and integrated mills with pulp-to-coating control. Competitive moves center on strategic partnerships with equipment vendors and backward integration into specialty coating chemistry.
Among hardware-integrated players, Hewlett-Packard Development Company and Canon exemplify the certification-lock archetype that shapes buyer procurement criteria. Seiko Epson Corporation occupies a position within the water-based pigment specialization tier, constraining substrate porosity specifications through ink chemistry requirements. These three anchors demonstrate how technology vendors translate hardware dominance into substrate supply chain influence.
| Leading Market Players |
|---|
| Hewlett-Packard Development Company |
| Canon |
| Xerox Corporation |
| Ricoh Company |
| Seiko Epson Corporation |
| Mimaki Engineering |
| Roland DG Corporation |
| Brother Industries |
| Konica Minolta |
| Others |
Value Chain & Pricing Dynamics
Specialty additive suppliers in Germany and Japan control surface energy modification chemistries, concentrating margin capture in coating-grade substrates while merchant converters of uncoated stocks compete on pulp cost pass-through efficiency.
Pricing Analysis
Certification level creates the primary spread across digital printing paper tiers, with ISO 12647-2 compliant stocks commanding premium positioning over uncertified alternatives. Three-tier pricing structure separates press-manufacturer-certified grades from merchant-converted standards and economy uncoated specifications. Pricing pressure stems from hardwood fiber cost volatility constraining margin stability at uncoated producers. Commercial printing buyers exhibit highest price sensitivity due to thin operating margins, while pharmaceutical packaging segments accept premium positioning for FDA-compliant security substrates.
Supply Chain Analysis
Export-control scrutiny on coating equipment and precision chemical manufacturing technology limits capacity expansion in certain geographies. Pulp sourcing concentrates in Brazil, Indonesia, and Canada for hardwood and softwood fiber streams. Surface energy modification chemistries draw from German and Japanese specialty additive houses. Single-source vulnerability pervades coating chemistry supply tiers. Distribution runs through merchant converters with multi-brand portfolios and direct mill relationships with certified substrate programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around press manufacturer certification programs, as Canon's integrated media certification and HP's PageWide substrate specifications concentrate procurement criteria among fewer qualified suppliers.
For Market Incumbents: Harden certification-lock positions by deepening R&D partnerships with inkjet press manufacturers against emerging water-based pigment system requirements. Prioritize backward integration into specialty coating chemistry to reduce single-source dependency on German and Japanese additive suppliers. Defend against merchant converter price erosion by embedding substrate specifications within hardware lease agreements. For New Entrants and Emerging Players: Establish a beachhead in India's mid-size commercial print modernization corridor, where BIS standards create qualification barriers that favor agile substrate engineering over legacy scale. Target dual-certified stock development for hybrid electrophotographic-inkjet environments in Mumbai and Delhi industrial zones. Pursue partnership-based market entry with regional press distributors lacking captive substrate portfolios. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed merchant converters holding multi-brand distribution networks but lacking mill integration. Long-term viability hinges on certification-program capture rather than commodity volume positioning across the analysis window. Monitor EU Deforestation Regulation compliance timeline acceleration as inflection signal for pulp-integrated mill valuations versus merchant converter discounting.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Program Partnership | Canon and HP substrate specifications now determine procurement criteria beyond hardware compatibility. |
| Backward Integration into Coating Chemistry | REACH compliance timelines favor mills with in-house surface energy modification capability. |
| Geographic Capacity Expansion | Production-class press deployments near Shanghai and Shenzhen concentrate regional substrate demand. |
| Security Substrate Development | Tamper-evidence layer integration captures pharmaceutical labeling premiums under FDA traceability mandates. |
| Pulp Sourcing Audit Infrastructure | EU Deforestation Regulation geolocation requirements compel plantation documentation systems for European-bound shipments. |
Study Parameters
Cross-validation between primary interviews with mill operations directors, print shop procurement managers, and press manufacturer substrate engineers anchors the qualitative findings against secondary validation. Secondary sources include customs and trade data on pulp flows, SEC filings from publicly traded paper companies, REACH registration databases, and ISO certification records. Bottom-up volume estimates from press installation data triangulate with top-down pulp consumption analysis across the forecast period.
Calibration against historical capacity utilization rates and substrate qualification timelines shapes the analytical framework. Segmentation dimensions span product type, end user, application, and size format across the projection horizon. CAGRs derive from installed base expansion curves and substrate consumption intensity per press class. Inkjet droplet fixation chemistry specifications and toner fusion temperature requirements inform technology-transition assumptions.
Sensitivities concentrate around REACH compliance timeline extensions, pulp cost volatility, and EU Deforestation Regulation enforcement intensity. Forecasts reflect assumptions on press manufacturer certification program expansion and hybrid print environment persistence. Cross-checking against pulp futures market positioning and regional press shipment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Dissolving Pulp Market
Paper Products
Fluff Pulp Market
Paper Products
Aramid Paper Market
Paper Products
Americas Stone Paper Market
Paper Products
North America Thermal Paper Market
Paper Products
Veneer Sheets Market
Paper Products
North America Decor Paper Market
Paper Products
Middle East and Africa Decor Paper Market
Paper Products
Printing Paper Market
Paper Products
Greaseproof Paper Market
Paper Products
GCC Stone Paper Market
Paper Products
Paper Products Market
Paper Products
Filtration Paper Market
Paper Products
Metallized Paper Market
Paper Products
Tissue Paper Market
Paper Products
Europe Thermal Paper Market