
 Medium Density Fiberboard Market | 2026-2036
Medium Density Fiberboard Market Size, Share, and Industry Trends Forecast 2026-2036
Medium Density Fiberboard Market Analysis
Southeast Asia is reshaping global MDF capacity allocation as mills expand resin-efficient production lines. Kronospan Limited leverages backward integration into wood chip supply across Central European forests. EGGER Group anchors its competitiveness through continuous press technology investments. ARAUCO dominates Latin American distribution channels with integrated pulp-to-panel logistics.
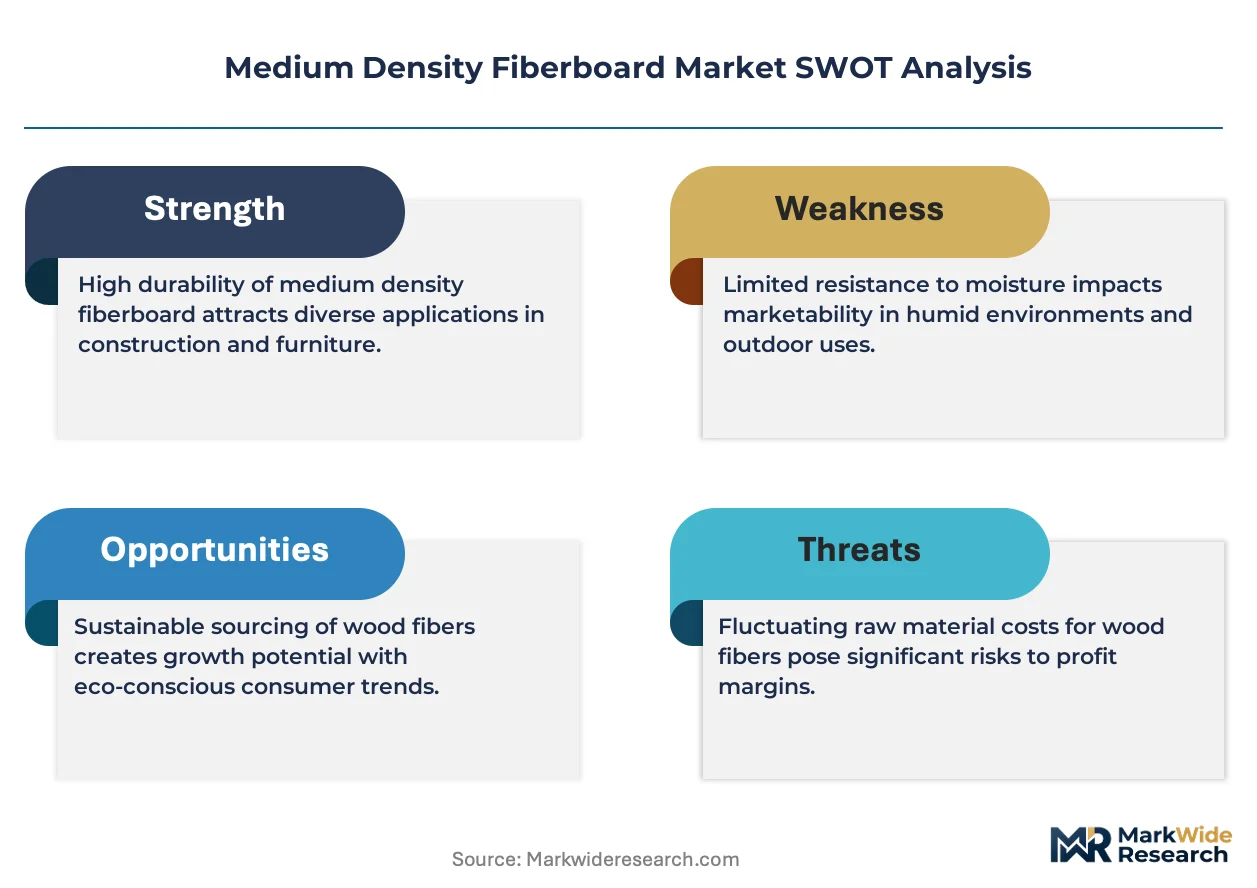
Medium density fiberboard is an engineered wood product manufactured from refined wood fibers bonded with synthetic resin under heat and pressure, typically achieving densities between 600 and 800 kilograms per cubic meter. The material provides uniform surface consistency for laminating, routing, and precision machining across furniture and interior fit-out applications. Standard MDF retains the largest volume share across residential and commercial channels, though moisture-resistant formulations command premium positioning in humid climates and kitchen cabinetry end uses. Fire-retardant grades serve commercial building codes where ASTM E84 or EN 13501-1 classifications govern wall panel specifications, concentrating margin pools in specification-driven projects.
EPA TSCA Title VI regulates formaldehyde emissions from composite wood products in the United States, while the EU Ecodesign framework and REACH restrictions on urea-formaldehyde resins tighten chemical compliance burdens. California Air Resources Board ATCM standards exceed federal thresholds, creating a dual-compliance environment for North American suppliers. Stakeholders must monitor bio-based adhesive breakthroughs and regional timber certification schemes as determinants of long-term cost structure and market access eligibility.
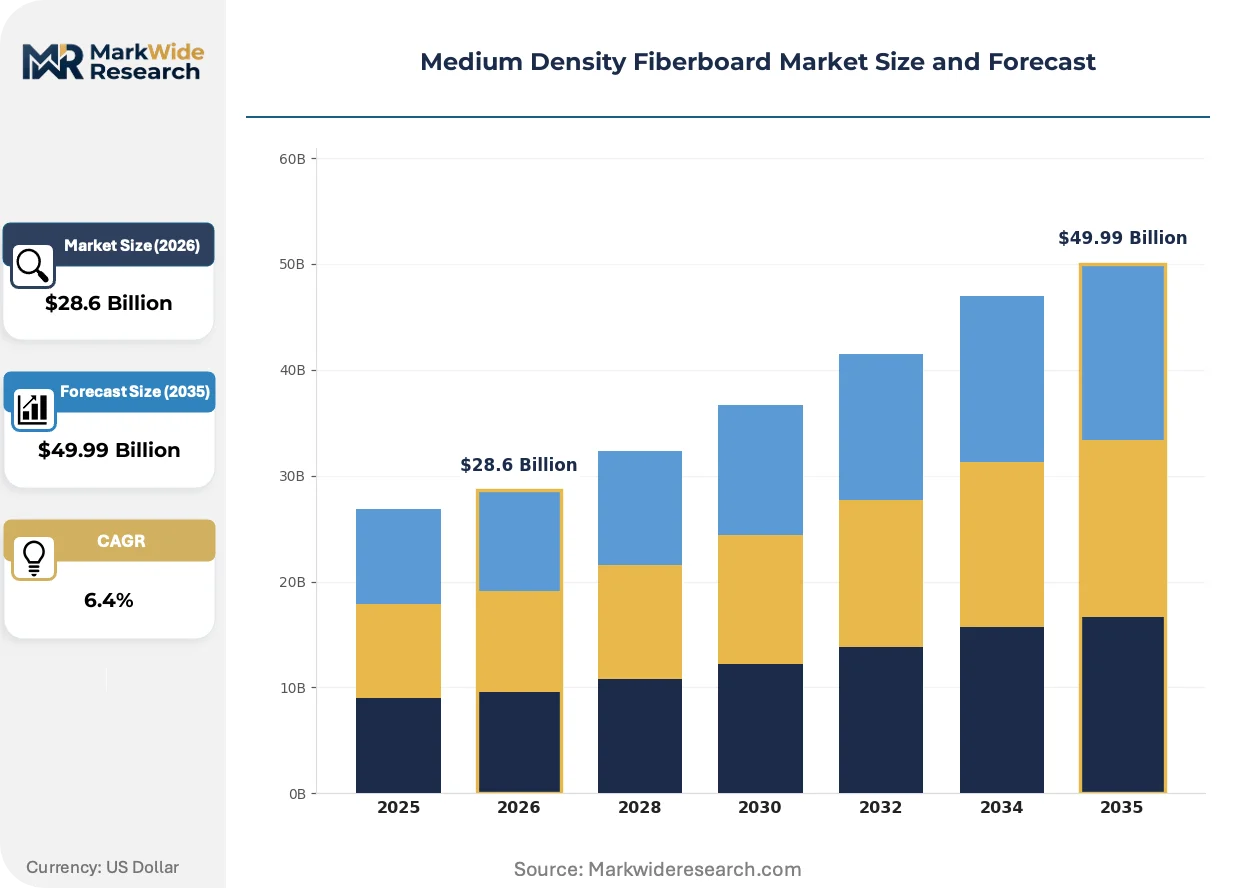
Market Dynamics
Formaldehyde emission regulations are compressing legacy resin formulations while Southeast Asian furniture exporters accelerate moisture-resistant grade adoption, reshaping capacity allocation and supplier compliance investments.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Tightened formaldehyde thresholds force resin reformulation investments that favor large-scale producers with captive R&D infrastructure.
- Vietnam export manufacturing corridors:Furniture assembly clusters near Ho Chi Minh City drive concentrated procurement of moisture-resistant MDF for containerized export to North American and European retailers.
- Continuous press technology:Capital-intensive line upgrades enable thinner panel production with reduced resin loading, cutting unit costs for standard-grade output.
Market Restraints
- Urea-formaldehyde resin cost volatility:Natural gas and methanol price swings compress margins for producers locked into conventional adhesive supply contracts.
- Central European wood chip supply concentration:Kronospan Limited's backward integration into forest assets creates sourcing asymmetries for non-integrated competitors.
- Cross-laminated timber substitution:Mass timber construction codes in commercial building segments divert structural panel demand away from fire-retardant MDF grades.
Strategic Opportunities
- India furniture manufacturing:BIS certification requirements and import substitution policies create localized production incentives for moisture-resistant panel grades.
- Bio-based adhesive convergence:Lignin-modified phenolic and soy-based resin technologies open premium positioning channels for low-emission interior fit-out specifications.
- Direct mill-to-factory procurement platforms:Digital tendering systems bypass layered distribution networks in Latin American markets where ARAUCO's integrated logistics currently dominate.
Industry Challenges
- Resin chemist talent scarcity:Formulation expertise for low-emission, high-bond-strength adhesives concentrates in Central European and Japanese technical institutes.
- EPA TSCA Title VI certification timelines:Third-party verification bottlenecks delay product launch windows for North American market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium Density Fiberboard Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard MDF, Fire-Retardant MDF, Moisture-Resistant MDF, Laminated MDF End User: Furniture, Flooring, Cabinetry, Decorative Panels Thickness: Thin, Standard, Thick, Ultra-Thick Application: Residential, Commercial, Industrial, DIY |
| Companies Covered | Kronospan Limited, EGGER Group, ARAUCO, Kastamonu Entegre, Georgia-Pacific, Dongwha Malaysia Holdings Sdn. Bhd., Norbord Inc., West Fraser Timber Co. Ltd., Dare Panel Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium Density Fiberboard Market Emerging Trajectories
Digital press control systems and bio-resin pilot lines are compressing legacy manufacturing economics while regulatory emission thresholds harden across multiple jurisdictions. These forces are accelerating capital deployment toward resin-efficient production architectures.
Continuous press technology with real-time density profiling is rendering obsolete batch-operated multi-opening presses in standard-grade MDF production. Vietnamese export furniture manufacturers now specify continuous-press panels for 0.8mm tolerance consistency in routed cabinet components. The technology is compressing viable scale thresholds, marginalizing sub-100,000 cubic meter annual capacity facilities.
REACH restrictions on urea-formaldehyde resins are tightening chemical compliance burdens for European panel producers serving kitchen cabinetry end uses. The regulation forces dual-track resin inventory management and accelerated phenolic substitution in humid-environment specifications. German and Polish mills are responding with dedicated low-emission production lines segregated from standard-grade output.
Specification-driven procurement now dominates commercial interior fit-out channels where architects mandate EN 13501-1 fire classification documentation ahead of price negotiation. General contractors in Gulf Cooperation Council markets are consolidating vendor lists to three approved suppliers per project, replacing fragmented spot purchasing. This concentration is most visible in Saudi Arabia's hospitality and healthcare construction verticals.
Medium Density Fiberboard Market Segmentation
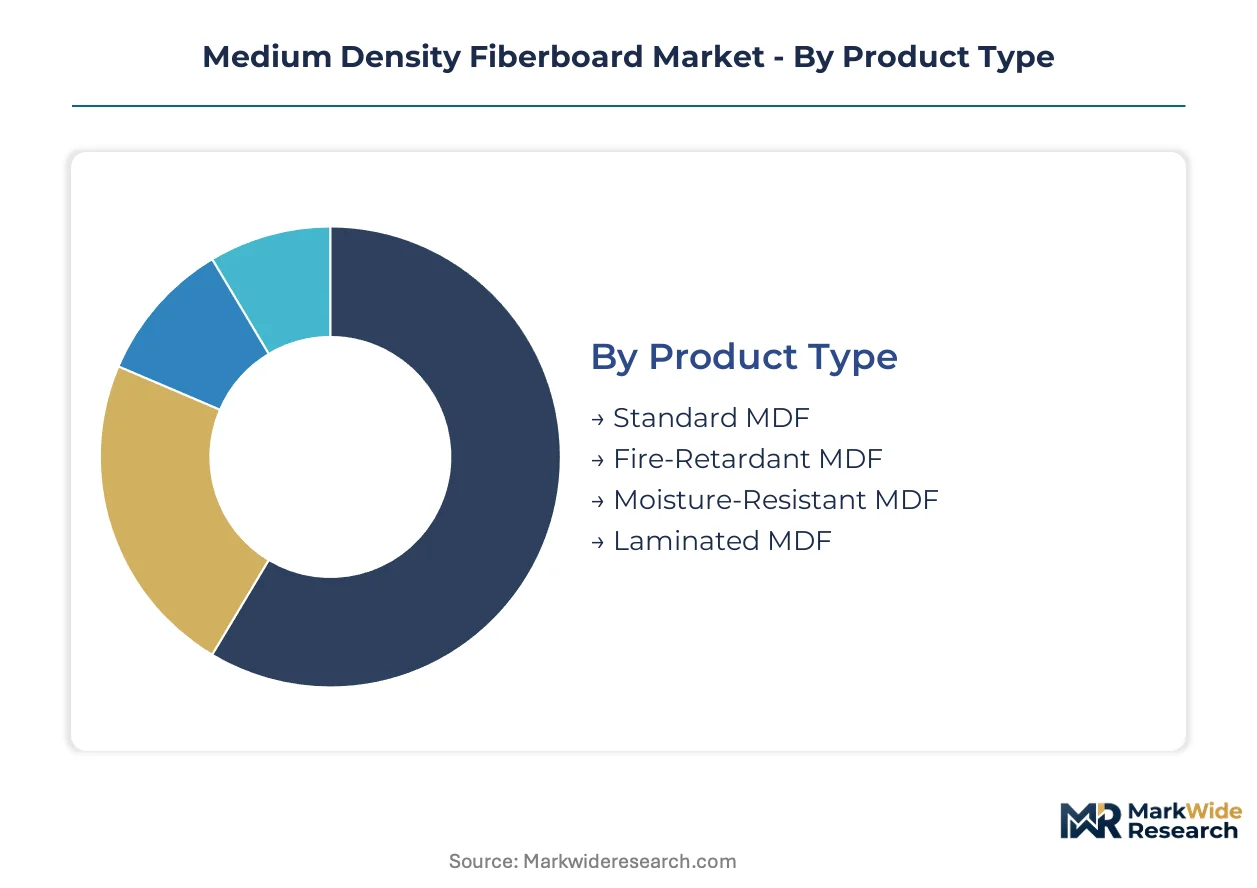
Segmentation in the Medium Density Fiberboard Market reveals how resin chemistry, density gradients, and surface treatment specifications align with distinct procurement channels. Each dimension exposes different margin structures and compliance burdens for producers.
Product Type:
Mature formulations dominate volume throughput while specialty grades capture specification premiums in regulated environments.
- Standard MDF:Manufactured from refined softwood fibers bonded with urea-formaldehyde resin at densities between 600-800 kg/m³. Furniture manufacturers in Vietnam's export corridors near Ho Chi Minh City specify this grade for routed cabinet components where surface uniformity outweighs moisture protection. EPA TSCA Title VI compliance costs are compressing margins for non-integrated producers.
- Moisture-Resistant MDF:Incorporates phenolic or melamine-modified resins with wax additives to achieve EN 321 cyclic test performance. Kitchen cabinetry fabricators in humid Southeast Asian climates specify this grade for sink bases and bathroom vanities, paying premiums of 15-25% over standard formulations.
- Fire-Retardant MDF:Treated with ammonium polyphosphate or boron compounds to meet ASTM E84 Class A or EN 13501-1 B-s1,d0 ratings.
- Laminated MDF:Pre-finished with decorative paper or vinyl foils bonded under heat and pressure, eliminating secondary finishing steps for furniture assemblers.
Standard MDF handles the majority of throughput; moisture-resistant formulations are expanding most quickly on share as humid-climate manufacturing concentrates in Southeast Asia.
End User:
Application-driven procurement patterns split between specification-heavy commercial channels and price-sensitive residential furniture.
- Furniture:Flat-pack and ready-to-assemble manufacturers in Poland, Vietnam, and Mexico consume continuous-press panels for dimensional stability in CNC-machined components. REACH restrictions on formaldehyde emissions are forcing resin reformulation investments that favor large-scale suppliers with captive R&D.
- Cabinetry:Kitchen and bathroom cabinet fabricators specify moisture-resistant or laminated grades where humid environment exposure demands enhanced dimensional stability.
- Flooring:Underlayment and engineered wood core applications favor high-density standard grades with consistent thickness tolerance.
- Decorative Panels:Wall cladding and interior fit-out channels require fire-retardant certification and surface-quality documentation for architect-specified projects.
Furniture commands the dominant procurement volume; cabinetry is climbing the fastest as residential renovation spending concentrates in premium kitchen specifications.
Thickness:
Press technology investments have compressed viable scale thresholds, marginalizing producers unable to serve the full thickness spectrum.
- Thin:Panels below 6mm enable lightweight furniture construction and curved-forming applications where flexibility matters.
- Standard:9-18mm thickness range serves the bulk of furniture, shelving, and interior fit-out applications with optimal strength-to-weight ratios.
- Thick:19-30mm panels provide structural mass for countertops, door cores, and high-load shelving systems.
- Ultra-Thick:Exceeding 30mm, these grades substitute for solid wood in architectural millwork and specialty furniture where machining depth is required.
Standard thickness handles the majority of throughput; thin panels are gaining share fastest as lightweight furniture trends accelerate in e-commerce distribution channels.
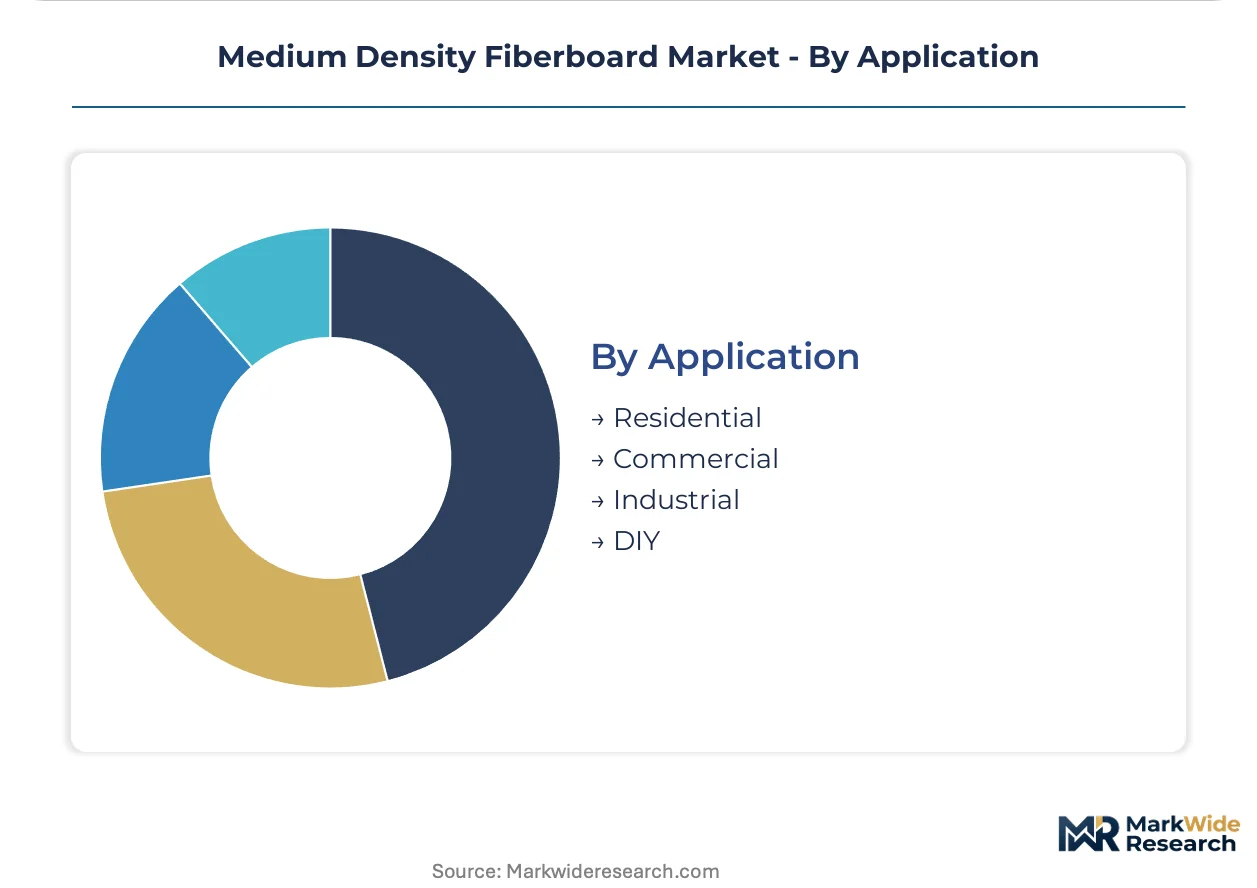
Application:
Channel segmentation separates bulk contract supply from fragmented retail distribution with divergent service requirements.
- Residential:New construction and renovation activity drives bulk procurement through distributor networks serving regional carpentry and remodeling contractors.
- Commercial:Office, hospitality, and healthcare fit-out projects mandate certified fire performance and chain-of-custody documentation, consolidating vendor lists to approved suppliers.
- Industrial:OEM manufacturers of furniture components, fixtures, and displays purchase direct from mills under annual volume agreements.
- DIY:Home improvement retailers stock cut-to-size panels and project kits for consumer pickup, requiring distinct inventory management and merchandising support.
Residential channels handle the majority of throughput; commercial applications show the steepest expansion trajectory as post-pandemic office and hospitality renovation cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA TSCA Title VI anchors North American compliance architecture while EU REACH restrictions and Southeast Asian export manufacturing reshape capacity allocation across three continents.
United States
California Air Resources Board ATCM standards exceed federal EPA thresholds, creating dual-compliance burdens for panel importers. Furniture assemblers in the Southeast and Pacific Northwest specify certified low-emission grades for retail distribution through big-box channels. The EPA's third-party certification bottlenecks delay product launch windows for new market entrants.
Germany
REACH restrictions on urea-formaldehyde resins force dual-track resin inventory management at mills serving kitchen cabinetry fabricators. German producers operate dedicated low-emission production lines segregated from standard-grade output. The country's technical institutes concentrate scarce resin chemist expertise for low-emission, high-bond-strength adhesive formulation.
Vietnam
Export-oriented furniture manufacturers near Ho Chi Minh City drive concentrated procurement of moisture-resistant MDF for containerized shipment to North American and European retailers. BIS-equivalent import standards from destination markets force upstream compliance investments. The Dong Nai-Binh Duong industrial corridor hosts the densest clustering of panel-consuming CNC machining operations.
Brazil
Integrated pulp-to-panel logistics dominate Latin American distribution channels, with eucalyptus fiber supply anchoring cost competitiveness. ANVISA-aligned formaldehyde monitoring supports export eligibility to regulated markets. São Paulo state's furniture manufacturing belt consumes the majority of regional fire-retardant and laminated grade specifications.
India
BIS certification requirements and import substitution policies create localized production incentives for moisture-resistant panel grades. Residential renovation spending concentrates in premium kitchen specifications across Mumbai, Delhi-NCR, and Bangalore. The country's national standards body tightens emission thresholds in alignment with EU Ecodesign frameworks.
Medium Density Fiberboard Market Vendor Landscape
Backward-integrated forest owners and continuous-press technology specialists split the market between captive fiber supply and capital-intensive manufacturing scale. The vendor base concentrates around three strategic archetypes: European multi-site operators with in-house resin research, Southeast Asian export-focused fabricators serving furniture assembly clusters, and North American building products conglomerates with distribution network control. Dominant competitive moves include geographic expansion through greenfield continuous-press lines and portfolio diversification into moisture-resistant and fire-retardant specialty grades.
Within the European multi-site tier, Kronospan Limited and EGGER Group exemplify scale-driven positioning anchored in Central European forest assets and captive R&D infrastructure. ARAUCO represents the integrated pulp-to-panel model in Latin American markets. Kastamonu Entegre occupies a position bridging European technical standards with emerging market cost structures.
| Leading Market Players |
|---|
| Kronospan Limited |
| EGGER Group |
| ARAUCO |
| Kastamonu Entegre |
| Georgia-Pacific |
| Dongwha Malaysia Holdings Sdn. Bhd. |
| Norbord Inc. |
| West Fraser Timber Co. Ltd. |
| Dare Panel Group Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Containerized freight corridors linking Vietnam's Dong Nai-Binh Duong industrial belt to North American West Coast ports transmit cost volatility directly into landed price spreads between Southeast Asian and European suppliers, compressing margins for non-integrated mills while amplifying pricing power for backward-integrated producers with captive fiber supply.
Pricing Analysis
Geographic price spreads between Central European and Southeast Asian supply widen during energy cost spikes, with phenolic-modified moisture-resistant grades commanding premiums of 15-25% over standard urea-formaldehyde formulations. Price differentiation centers on certification tier—EPA TSCA Title VI and EU Ecodesign compliance—and continuous-press manufacturing scale. Cost compression in standard-grade output is intensifying because resin-efficient production lines marginalize sub-100,000 cubic meter annual capacity facilities. Furniture assemblers in Vietnam's export corridors show highest price sensitivity, while Gulf Cooperation Council hospitality contractors purchasing fire-retardant grades for architect-specified projects demonstrate lowest sensitivity.
Supply Chain Analysis
Softwood fiber supply concentrates in Germany, Poland, and the Czech Republic, where Kronospan Limited and EGGER Group maintain backward integration into forest assets. Production draws from urea-formaldehyde resins, phenolic adhesives, and wax additives, with methanol and natural gas price volatility feeding into input cost instability. Single-source vulnerability in Central European wood chip supply creates sourcing asymmetries for non-integrated competitors. Distribution runs through direct mill-to-factory procurement platforms in Latin America and layered distributor networks serving regional carpentry contractors in North American residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA, EU Ecodesign, and BIS certification regimes fragments procurement standards, creating white-space opportunities for specialized producers capable of multi-jurisdictional compliance without scale-disadvantage.
For Market Incumbents: Insulate margin pools by accelerating phenolic substitution in dedicated low-emission production lines segregated from standard-grade output, while deepening backward integration into wood chip supply to neutralize Kronospan Limited's sourcing asymmetries. Cross-laminated timber substitution in commercial building segments threatens fire-retardant grade demand, making certification investment in EN 13501-1 documentation the priority defensive lever. For New Entrants and Emerging Players: Establish a beachhead in India's moisture-resistant panel segment where BIS certification requirements and import substitution policies create localized production incentives without incumbent scale advantages. Vietnam's CNC machining clusters near Ho Chi Minh City represent the most penetrable demand concentration for containerized export supply. A mill-direct digital tendering platform bypassing ARAUCO's integrated logistics dominance offers the clearest go-to-market angle in Latin American markets. For Investors and Strategic Acquirers: Carve-out targets emerge from building products conglomerates with non-core panel operations lacking captive R&D infrastructure for low-emission adhesive formulation. Long-term viability over a 5-10 year window hinges on resin chemist talent access and continuous-press technology deployment. Bio-based adhesive breakthroughs achieving commercial scale serve as the critical inflection indicator for premium positioning in specification-driven interior fit-out channels.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Press Technology Deployment | Enables 0.8mm tolerance consistency for Vietnamese CNC-machined cabinet components. |
| Resin-Efficient Production Line Segregation | Allows German mills to serve REACH-restricted kitchen cabinetry without cross-contamination. |
| Backward Integration into Forest Assets | Neutralizes wood chip supply concentration asymmetries in Central European markets. |
| Bio-Based Adhesive Pilot Scaling | Opens premium positioning for lignin-modified phenolic specifications in low-emission fit-out. |
| Direct Mill-to-Factory Procurement Platform | Bypasses layered distribution networks where ARAUCO's integrated logistics currently dominate. |
Methodological Framework
Cross-validation between trade association production statistics and customs export declarations anchors the qualitative findings, with primary interviews involving resin formulation chemists, continuous-press operations managers, furniture procurement directors, and architect specification consultants triangulated against secondary sources including EPA TSCA Title VI certification databases, EU ECHA REACH restriction notices, and BIS standard publication records. Bottom-up capacity utilization data from mill operators reconciles with top-down consumption estimates from end-use sector associations.
Calibration against historical capacity expansion cycles and resin cost pass-through patterns informs the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end-use application, thickness grade, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections and supply-side capacity response functions, with continuous-press technology diffusion rates and formaldehyde emission threshold tightening schedules serving as industry-specific forecast inputs.
Sensitivities concentrate around methanol price volatility, EPA third-party certification timeline delays, and bio-resin commercialization breakthroughs. Cross-checking against timber certification scheme adoption rates and regional furniture export shipment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Coated Wood Free Papers Market
Paper Products
Clay Coated Paper Market
Paper Products
Glassine Paper Market
Paper Products
Global Thin Papers Market
Paper Products
Bleached Softwood Kraft Pulp Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Paper Machinery Market
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
Global Kraft Paper Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Global Wood Pulp Market
Paper Products
Latex-Saturated Paper Market
Paper Products
Drum Pulper Market
Paper Products
Thermal Paper Market
Paper Products
Decor Paper Market
Paper Products
Hardwood Pulp Market