
 Greaseproof Paper Sheets Market | 2026-2036
Greaseproof Paper Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Greaseproof Paper Sheets Market Foresight
Asset-light leasing models for specialty paper converting equipment are reshaping competitive entry in the greaseproof paper sheets sector. Nordic Paper leverages its integrated pulp-to-paper operations across Scandinavian mills to sustain cost advantages in unbleached grades. Delfortgroup anchors its position through deep specialization in coated barrier papers for premium bakery applications. Krpa Paper competes by controlling distribution networks across Central European foodservice channels.
Greaseproof paper sheets are cellulose-based papers treated through dense calendering or fluorochemical-free coating to achieve oil and moisture resistance without plastic lamination, typically rated for grease holdout above kit number 12. The primary commercial purpose centers on direct food contact packaging where visual presentation and barrier performance must coexist without synthetic films. Unbleached paper commands the largest volume share across European bakery supply chains where natural aesthetic aligns with clean-label positioning. Coated paper captures the fastest expansion as fluorine-free barrier formulations replace legacy perfluorinated chemistries under tightening food-contact regulations. Pre-cut sheet formats concentrate margin pools through SKU consolidation and labor savings in high-throughput fast-food kitchens.
The FDA maintains food-contact substance notifications under 21 CFR while EPA scrutiny of PFAS chemistries is reshaping coating formulation choices across US manufacturing. EU REACH restrictions on perfluorinated compounds and the F-Gas Regulation's indirect pressure on synthetic barrier alternatives are accelerating migration toward bio-based greaseproof solutions. EFSA migration limits for mineral oil saturated hydrocarbons in recycled fiber applications are tightening specification requirements for food-grade papers. Stakeholders must monitor regulatory divergence between US and European PFAS phase-out timelines when planning coating R&D investment and regional product registration strategies.
Market Dynamics
Fluorochemical-free barrier coatings are compressing legacy PFAS-dependent supply chains while EU REACH and EPA scrutiny accelerate formulation turnover across converting operations worldwide.
Growth Catalysts
- EU Single-Use Plastics Directive:National transposition laws in Germany, France, and Italy mandate fiber-based alternatives for foodservice packaging, redirecting quick-service restaurant procurement toward greaseproof paper sheets.
- Artisan bakery expansion:Unbleached grades align with clean-label positioning as craft bread chains in the United States and United Kingdom replace plastic window bags with cellulose-based display packaging.
- Fluorine-free coating chemistry:Bio-based barrier formulations using plant-derived waxes and polysaccharides achieve kit 12+ grease holdout without perfluorinated compounds, satisfying tightening food-contact standards.
Market Restraints
- Pulp cost volatility:Northern bleached softwood kraft pulp prices fluctuate with energy and logistics costs, squeezing converter margins on unbleached greaseproof grades.
- Scandinavian supply concentration:Integrated pulp-to-paper operations in Sweden and Finland control upstream fiber supply, creating bottleneck risk for independent converters elsewhere.
- Mineral oil migration limits:EFSA thresholds for saturated hydrocarbons in recycled fiber applications restrict post-consumer content in food-grade papers, limiting circular material inputs.
Strategic Opportunities
- Central European foodservice penetration:Poland and Czech Republic quick-service restaurant chains remain underpenetrated relative to Western European adoption rates for pre-cut sheet formats.
- Coated barrier premiumization:Fluorine-free formulations command price premiums in Japanese convenience store bakery packaging where visual clarity and grease resistance must coexist.
- Asset-light converting equipment:Leasing models for specialty calendering and coating lines lower capital barriers for regional players entering niche barrier paper segments.
Industry Challenges
- PFAS phase-out timeline divergence:EPA state enforcement actions in Michigan and Maine run ahead of federal rulemaking, forcing manufacturers to maintain multiple coating SKUs for regulatory compliance.
- Food-contact notification backlogs:FDA 21 CFR substance clearances for novel bio-based barrier chemistries extend 18-24 months, delaying product launches.
- Calendering operator scarcity:Dense calendering expertise for unbleached grades concentrates among aging workforces at legacy European mills, constraining quality output expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greaseproof Paper Sheets Market |
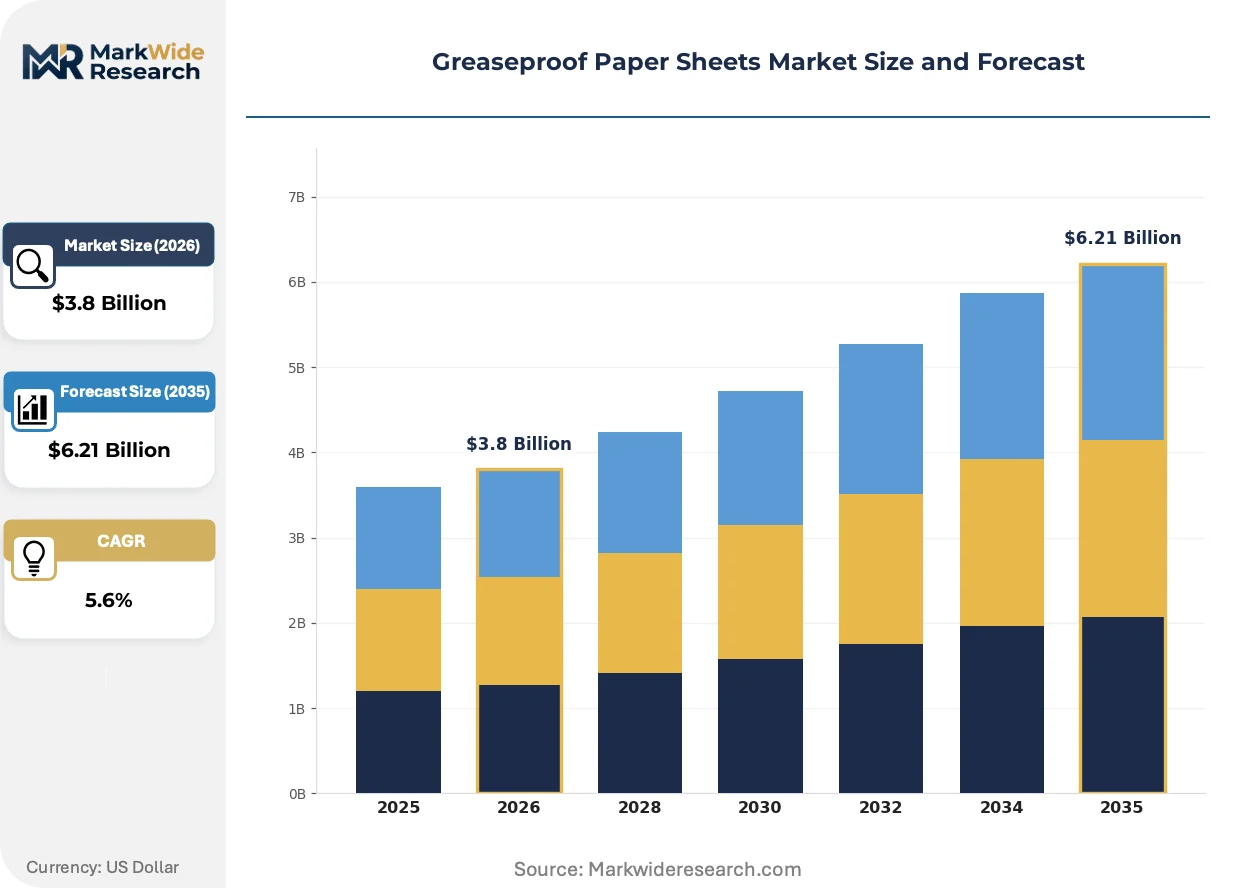
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bleached Paper, Unbleached Paper, Coated Paper, Waxed Paper End User: Food Industry, Bakery, Fast Food Chains, Catering Services Packaging Type: Sheets, Rolls, Custom Sizes, Pre-Cut Application: Food Packaging, Bakery Products, Takeaway Containers, Wraps |
| Companies Covered | Ahlstrom-Munksjö, Nordic Paper, Metsä Tissue, Domtar, Delfortgroup, Krpa Paper, Simpac, Vicat Group, Pudumjee Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greaseproof Paper Sheets Market Shifts & Advancements
Barrier technology convergence and regulatory chemistry bans are compressing traditional supply chains while procurement patterns favor consolidated SKU portfolios and certified sustainable sourcing.
Plant-derived polysaccharide coatings are hybridizing with conventional calendered cellulose substrates to achieve grease resistance without synthetic films. Quick-service restaurant chains in Germany and the United Kingdom are specifying these hybrid constructions for burger wraps and fry cartons. The technology is hybridizing procurement specifications, collapsing the distinction between unbleached aesthetic grades and high-performance coated barriers.
EPA scrutiny of PFAS under TSCA Section 6 and state-level prohibitions in California and New York are eliminating perfluorinated chemistry options for domestic food-contact applications. Converters must reformulate coating stacks or source imported fluorine-free alternatives, raising working capital requirements. Bakery supply chains serving US coastal markets face the most compressed compliance timelines and highest reformulation costs.
Pre-cut sheet formats are displacing roll stock in high-throughput fast-food kitchens where labor savings and portion consistency outweigh per-unit material premiums. Distribution is consolidating through broadline foodservice distributors who bundle greaseproof sheets with disposable tableware and cleaning supplies. This pattern concentrates most visibly in US quick-service and convenience store channels where operational speed dominates procurement criteria.
Greaseproof Paper Sheets Market Segmentation
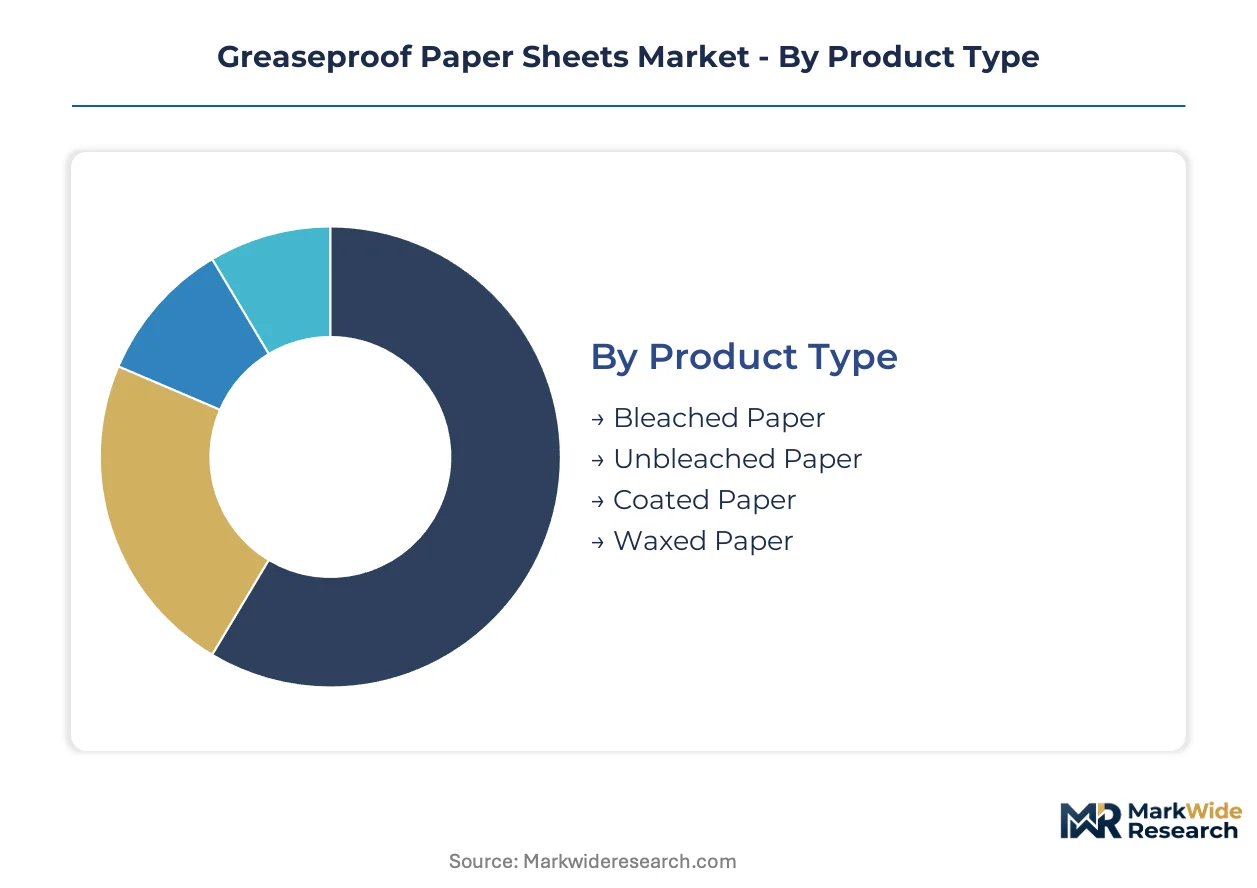
Greaseproof paper sheets fragment across four dimensions that shape procurement patterns and margin structures. Product chemistry determines regulatory compliance pathways. End-user concentration drives volume scale and format specifications.
Product Type:
Cost tier differentiation separates commodity cellulose grades from engineered barrier constructions with specialized coating stacks.
- Unbleached Paper:Dense calendered cellulose retains natural lignin content for artisan bakery display packaging. German and French bakery chains specify this grade for clean-label positioning where visible fiber texture signals authenticity. Pulp cost volatility squeezes converter margins on this volume-leading segment.
- Coated Paper:Fluorine-free barrier formulations using plant-derived waxes and polysaccharides achieve kit 12+ grease holdout. Japanese convenience store bakery packaging commands premium pricing where visual clarity must coexist with oil resistance. EPA and ECHA regulatory pressure on PFAS alternatives accelerates formulation R&D investment.
- Bleached Paper:Whitened cellulose substrates serve foodservice applications requiring neutral background for printed branding.
- Waxed Paper:Paraffin or vegetable wax impregnation provides moisture barrier for chilled food applications with lower heat tolerance requirements.
Unbleached paper holds installed capacity. Coated paper is rotating up the share rankings.
End User:
Customer type concentration determines format specifications, with quick-service procurement favoring labor-saving pre-cut configurations over roll stock.
- Fast Food Chains:High-throughput kitchens specify pre-cut sheet formats for burger wraps and fry cartons where portion consistency outweighs per-unit material premiums. US and UK chains bundle greaseproof sheets through broadline foodservice distributors alongside disposable tableware. Operational speed dominates procurement criteria.
- Bakery:Artisan bread chains in the United States and United Kingdom replace plastic window bags with cellulose-based display packaging. Unbleached grades align with craft positioning and natural aesthetic requirements. EU Single-Use Plastics Directive compliance redirects European bakery procurement toward fiber-based solutions.
- Food Industry:Processed food manufacturers specify coated barriers for extended shelf-life applications requiring grease and moisture resistance.
- Catering Services:Event and institutional foodservice favors roll stock for flexible portioning across variable menu configurations.
Fast food chains anchor volume demand. Bakery applications are climbing the fastest as artisan expansion accelerates.
Packaging Type:
Format selection trades labor efficiency against material flexibility, with pre-cut configurations gaining share in high-throughput environments.
- Pre-Cut:Standardized dimensions eliminate on-site cutting labor in quick-service kitchens. US convenience store channels concentrate procurement through bundled distributor relationships. SKU consolidation reduces inventory complexity for multi-location operators.
- Sheets:Flat-packed configurations serve bakery display and deli counter applications where presentation quality matters. European bakery supply chains favor this format for artisan bread packaging.
- Rolls:Continuous formats retain flexibility for variable portion sizes in catering and institutional settings.
- Custom Sizes:Specialty dimensions address equipment-specific requirements in automated packaging lines.
Sheets hold installed capacity. Pre-cut formats are gaining share fastest as labor costs rise.
Application:
Functional requirements vary by food contact duration, temperature exposure, and visual presentation demands.
- Food Packaging:Direct contact applications require FDA 21 CFR or EFSA compliance for barrier coatings. Migration limits for mineral oil saturated hydrocarbons tighten specification requirements for recycled fiber content.
- Wraps:Folded constructions for handheld foods demand pliability without tearing. Fluorine-free coating formulations satisfy tightening food-contact standards across US coastal markets facing compressed PFAS phase-out timelines.
- Bakery Products:Display packaging for breads and pastries prioritizes grease resistance and natural aesthetic. Unbleached grades dominate European applications.
- Takeaway Containers:Structural rigidity requirements favor heavier basis weights and coated barriers for hot food applications.
Food packaging holds installed capacity. Wraps are rotating up the share rankings as quick-service formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in greaseproof paper sheets tilt toward net-exporting Scandinavian mills and net-importing foodservice hubs across North America and Southern Europe. Trade patterns reflect pulp proximity, converting capacity, and regulatory alignment on barrier chemistry standards.
Germany
Artisan bakery chains and quick-service restaurants drive unbleached sheet consumption. The EU Single-Use Plastics Directive transposition mandates fiber-based packaging alternatives by national deadline. Munich and Stuttgart clusters concentrate converting operations serving Central European foodservice distribution networks.
United States
Fast-food chains specify pre-cut formats for labor efficiency in high-throughput kitchens. EPA state enforcement actions in Michigan and Maine accelerate PFAS phase-out ahead of federal rulemaking. California and New York coastal markets face compressed compliance timelines for fluorine-free barrier adoption.
Japan
Convenience store bakery packaging demands coated barriers combining visual clarity with grease resistance. METI guidance on sustainable materials procurement favors bio-based barrier formulations. Tokyo-Osaka logistics corridors concentrate distribution for pre-cut sheet formats in retail foodservice.
United Kingdom
Craft bread chains replace plastic window bags with cellulose-based display packaging for clean-label positioning. Post-Brexit divergence from EU REACH timelines creates regulatory friction for coating formulation registration. London and Manchester anchor importing and converting activity for bakery supply chains.
Sweden
Integrated pulp-to-paper operations supply unbleached grades to European converters. EU F-Gas Regulation pressure on synthetic barrier alternatives accelerates fiber-based solution adoption. Gothenburg and Sundsvall mill complexes control upstream fiber supply for Nordic Paper and regional exporters.
Greaseproof Paper Sheets Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with captive fiber supply or proprietary coating chemistry. Market structure consolidates around Scandinavian integrated producers and Central European converters with foodservice distribution control. Three archetypes dominate: pulp-integrated manufacturers, specialty coating developers, and regional converting specialists. Competitive moves center on fluorine-free formulation R&D and pre-cut format capacity expansion.
Among Nordic integrated producers, Nordic Paper and Metsä Tissue exemplify pulp-to-paper control over unbleached grade supply. Delfortgroup anchors the specialty coating tier with barrier paper focus for premium bakery applications. Krpa Paper represents regional distribution specialists leveraging Central European foodservice channel relationships.
| Leading Market Players |
|---|
| Ahlstrom-Munksjö |
| Nordic Paper |
| Metsä Tissue |
| Domtar |
| Delfortgroup |
| Krpa Paper |
| Simpac |
| Vicat Group |
| Pudumjee Group |
| Others |
Supply & Pricing Matrix
Gothenburg and Sundsvall mill complexes in Sweden concentrate upstream pulp-to-paper capacity, translating Scandinavian fiber proximity into pricing leverage over Central European converters dependent on spot pulp markets. This geographic supply asymmetry compresses margins for independent sheet converters while integrated producers capture value through captive raw material access.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across unbleached grades, with price differentiation resting on certification tier and volume scale. Premium-mid-economy pricing differentiation separates fluorine-free coated barriers from commodity calendered cellulose, with bakery chains in Germany and Japan least sensitive due to clean-label positioning requirements. Cost compression in unbleached tiers is intensifying because Nordic integrated producers control upstream fiber supply.
Supply Chain Analysis
EU REACH restrictions on perfluorinated compounds limit coating chemistry flows into food-contact applications, redirecting converter sourcing toward bio-based barrier developers. Supply concentrates in Sweden, Finland, and Germany for pulp and base paper, with converters drawing from plant-derived wax and polysaccharide feedstocks for fluorine-free formulations. Single-source vulnerability concentrates in Scandinavian pulp supply, with distribution running through broadline foodservice distributors bundling sheets with disposable tableware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as regulatory chemistry bans splinter coating supply chains and artisan bakery expansion creates niche demand for aesthetic-grade unbleached sheets.
For Market Incumbents: Entrench fluorine-free formulation R&D leadership before EPA state enforcement actions in Michigan and Maine accelerate compliance timelines. Deepen backward integration into plant-derived barrier chemistries to offset pulp cost volatility squeezing converter margins. Secure pre-cut format capacity expansion in Poland and Czech Republic foodservice channels where penetration lags Western European adoption rates. For New Entrants and Emerging Players: Pursue asset-light leasing models for specialty calendering equipment to bypass capital barriers in Central European markets. Target Polish quick-service restaurant chains with bundled distributor relationships as the most penetrable geography. Lead with fluorine-free coating certification as the go-to-market angle to satisfy tightening EU REACH and emerging US state-level PFAS prohibitions. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty coating developers with proprietary bio-based barrier IP over commodity cellulose converters. Long-term viability hinges on regulatory chemistry transition completion and food-contact notification clearance timelines. Watch FDA 21 CFR substance clearance backlogs as the inflection signal indicating which coating platforms achieve scalable market access.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Coating R&D Investment | EPA and ECHA regulatory pressure on PFAS alternatives accelerates formulation turnover across converting operations. |
| Backward Integration into Pulp Supply | Nordic integrated producers sustain cost advantages in unbleached grades through captive Scandinavian fiber access. |
| Pre-Cut Format Capacity Expansion | US and UK fast-food chains prioritize labor-saving configurations where portion consistency outweighs material premiums. |
| Central European Distribution Partnerships | Poland and Czech Republic quick-service channels remain underpenetrated relative to Western European adoption benchmarks. |
| Food-Contact Regulatory Certification | FDA 21 CFR and EFSA compliance clearance determines market access for novel bio-based barrier chemistries. |
Research Methodology
A spread of perspectives from paper mill operations directors, foodservice procurement managers at quick-service chains, converting equipment specialists, and regulatory affairs consultants converged on the working assumptions. Primary fieldwork combined with secondary validation from FDA food-contact substance notifications, EU REACH regulatory filings, customs trade data for pulp and specialty paper flows, and SEC disclosures from integrated paper producers. Bottom-up volume modeling triangulated against top-down market sizing across product chemistry, end-user concentration, and format specifications.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeling spanning unbleached versus coated versus bleached chemistry tiers, fast-food versus bakery versus catering end-use channels, and pre-cut versus roll versus sheet format configurations. CAGRs derived from trajectory fitting to historical pulp price cycles and regulatory compliance timeline acceleration. Industry-specific forecast inputs incorporated EU Single-Use Plastics Directive national transposition deadlines and EPA PFAS enforcement action sequencing.
Macroeconomic conditions sit as an overlay; deviation in energy costs, pulp futures volatility, or logistics rates would shift the trajectory. Forecasts reflect documented assumptions about regulatory chemistry phase-out timelines and food-contact clearance durations. Cross-checking against Nordic Paper and Metsä Tissue production disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Coated Wood Free Papers Market
Paper Products
Glassine Paper Market
Paper Products
Clay Coated Paper Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Functional and Barrier Coatings for Paper Market
Paper Products
Polyester Synthetic Paper Market
Paper Products
Thermal Paper Market
Paper Products
High-Speed Production Inkjet Printer Paper Market
Paper Products
Decorative Plastic and Paper Laminates Market
Paper Products
Hardwood Pulp Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Europe Paper Market
Paper Products
Compressed Fiberboard Market
Paper Products
Pulp Market
Paper Products
North America Decor Paper Market