
 Industrial Anti-Fatigue Mat Market | 2026-2036
Industrial Anti-Fatigue Mat Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Anti-Fatigue Mat Market Insights
The capital-intensity divergence between foam-injection specialists and commodity rubber converters is unwinding competitive stability in the industrial anti-fatigue mat space. 3M leverages its materials science portfolio to command premium positioning in electronics assembly cleanrooms. Wearwell sustains domestic manufacturing scale that anchors its presence across North American warehousing contracts. M+A Matting differentiates through modular tile systems that dominate food processing installations requiring frequent sanitation cycles.
Industrial anti-fatigue mats are engineered floor surfaces constructed from rubber, foam, gel, vinyl, polyurethane, or cork, typically measuring three-quarters to one inch in thickness with compressibility ratings calibrated to reduce spinal compression during prolonged standing. These mats function as ergonomic interventions that mitigate musculoskeletal disorders in environments where workers remain stationary for extended durations. Polyurethane segments lead value contribution due to superior resilience and chemical resistance, while interlocking installation types capture the fastest growth trajectory as facilities prioritize reconfigurable layouts. Foam formulations retain mature volume share in price-sensitive warehousing applications where replacement cycles are shorter and margin pools remain compressed.
OSHA workplace ergonomic guidelines directly shape procurement specifications by establishing standing-surface performance thresholds that influence buyer compliance budgets. The EPA oversees volatile organic compound emissions from polyurethane curing processes, constraining domestic manufacturing configurations and elevating certification costs for new entrants. ISO 340 slip-resistance standards govern product acceptance in European automotive OEM supply chains, creating divergent testing requirements across export destinations. Stakeholders must monitor regulatory harmonization pressures between regional ergonomic mandates and evolving material sustainability protocols to anticipate compliance-driven specification shifts.
Market Dynamics
Polyurethane injection molding is decomposing the legacy rubber mat supply base as automotive OEMs in Germany and electronics cleanrooms in the US enforce compressibility specifications that foam formulations cannot meet. This materials transition concentrates margin capture among chemical compounders with captive polymer science capabilities while marginalizing commodity converters.
Growth Catalysts
- OSHA ergonomic enforcement:The US Department of Labor's expanding inspection protocols for standing-duration workplaces are mandating certified anti-fatigue surfaces in warehousing and distribution facilities, converting discretionary safety spending into compliance-driven procurement.
- Automotive final-assembly mandates:German OEMs now require anti-fatigue matting across all permanent standing stations, creating specification lock-in for suppliers meeting ISO 340 slip-resistance and compressibility thresholds.
- Polyurethane formulation advances:Closed-cell injection processes are delivering 40% longer service life than rubber alternatives in high-wear zones, shifting replacement cycle economics toward premium materials despite higher upfront outlays.
Market Restraints
- Petrochemical input volatility:Isocyanate and polyol feedstock prices fluctuate with crude oil indices, compressing margins for polyurethane specialists unable to pass through cost swings to long-term contract customers.
- Regional supply concentration:Polyurethane mat production clusters in the US Midwest and German industrial corridors, exposing buyers to logistics cost spikes and extended lead times during freight market disruptions.
- End-of-life disposal friction:EPA hazardous waste classifications for polyurethane curing byproducts elevate disposal costs versus recyclable rubber alternatives, creating total-cost-of-ownership disadvantages in price-sensitive segments.
Strategic Opportunities
- India manufacturing expansion:The country's PLI scheme for electronics assembly and automotive component production is generating greenfield facility construction where ergonomic matting penetration remains below Western benchmarks.
- Interlocking tile systems:Modular installation formats are capturing food processing and pharmaceutical cleanroom demand where frequent sanitation cycles require rapid reconfiguration without full-floor replacement.
- EU Green Deal material protocols:Emerging bio-based polyurethane certifications are creating premium positioning for compounders investing in renewable feedstock supply chains ahead of mandated sustainability disclosures.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with polyurethane process expertise command premium compensation, constraining R&D velocity for mid-scale manufacturers competing against diversified materials conglomerates.
- Multi-jurisdiction certification complexity:Simultaneous compliance with OSHA workplace standards, EPA VOC emissions limits, and ISO 340 European slip-resistance protocols extends product launch timelines and elevates testing expenditures.
- Legacy flooring integration:Retrofitting anti-fatigue surfaces into existing concrete or epoxy floor systems without elevation mismatches or trip hazards demands custom fabrication capabilities that stretch installation contractor capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Anti-Fatigue Mat Market |
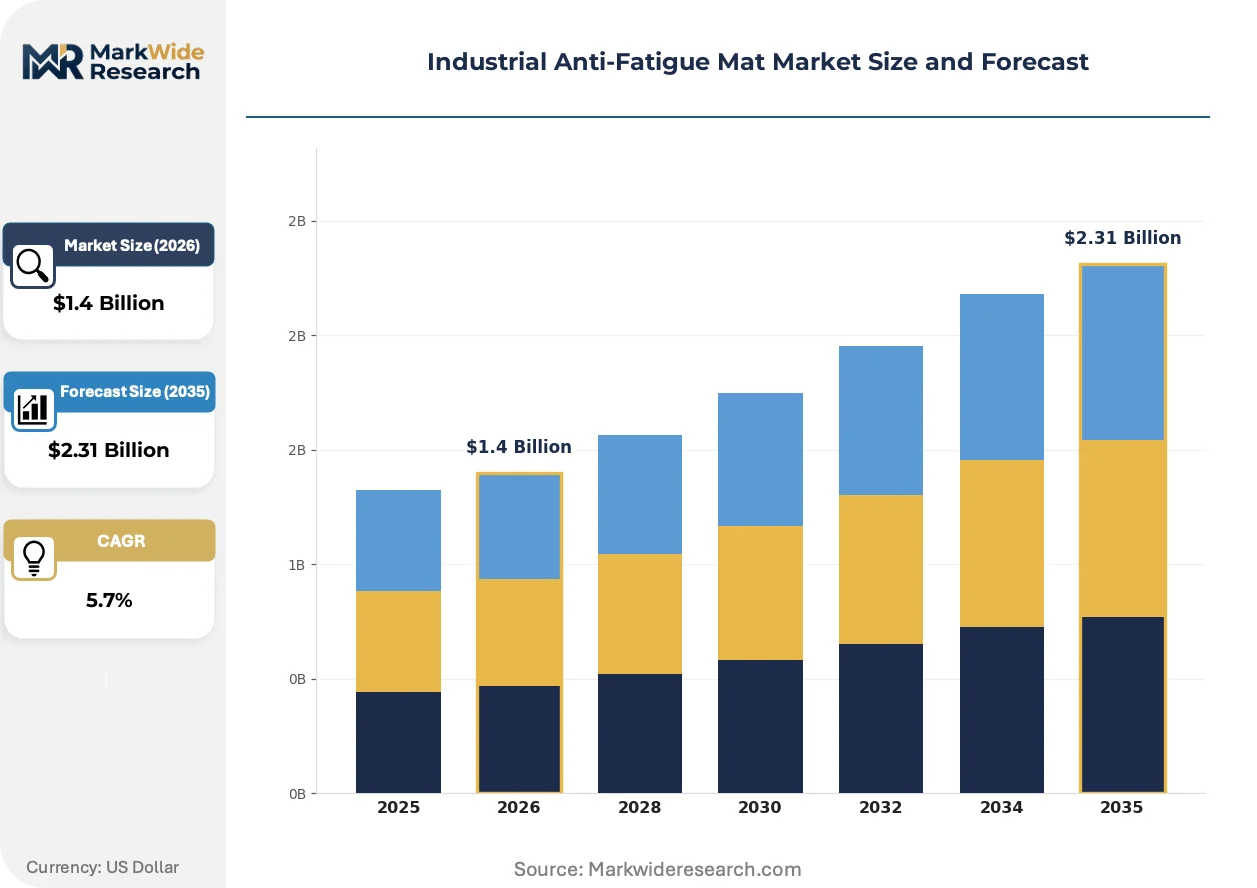
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber, Foam, Gel, Vinyl, Polyurethane, Cork Industry Vertical: Manufacturing, Warehousing, Food Processing, Automotive OEMs, Electronics Assembly, Pharmaceuticals Surface Texture: Smooth, Ribbed, Pebbled, Raised Dots, Crosshatch, Grooved Installation Type: Interlocking, Roll-Out, Modular Tile, Adhesive Backed, Custom Cut |
| Companies Covered | 3M, Cintas Corporation, Wearwell, NoTrax, Crown Matting Technologies, American Floor Mats, Eagle Mat and Floor Products, M+A Matting, UniFirst Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Anti-Fatigue Mat Market Trends and Innovations
Active materials science investment is fragmenting the competitive map as performance specifications diverge across end-use verticals. Three concurrent developments are compressing legacy supply structures while opening specialized niches.
Closed-cell polyurethane foam is decomposing the rubber mat installed base in high-compression applications. Electronics assembly cleanrooms and automotive final-assembly stations in Germany and the US are specifying 0.75-inch thickness with calibrated rebound rates that nitrile rubber cannot achieve. This specification escalation is compressing margin pools for commodity converters while concentrating value capture among injection molding specialists with captive polymer formulation capabilities.
REACH chemical registration requirements in Europe are constraining polyurethane curing agent formulations and elevating compliance documentation burdens for exporters. The European Chemicals Agency's expanding substance restrictions are forcing reformulation cycles that extend product development timelines by 12-18 months. Automotive OEM supply chains are responding by consolidating supplier relationships toward compounders with dedicated regulatory affairs functions and pre-certified material libraries.
Buyer consolidation among third-party logistics operators is compressing vendor counts and extending contract durations. Large warehousing operators in the US are unbundling installation services from product supply, forcing mat manufacturers to certify regional installation networks or sacrifice specification control. This channel restructuring is most visible in e-commerce fulfillment centers where facility standardization across national footprints favors single-source national contracts over regional supplier fragmentation.
Industrial Anti-Fatigue Mat Market Segmentation
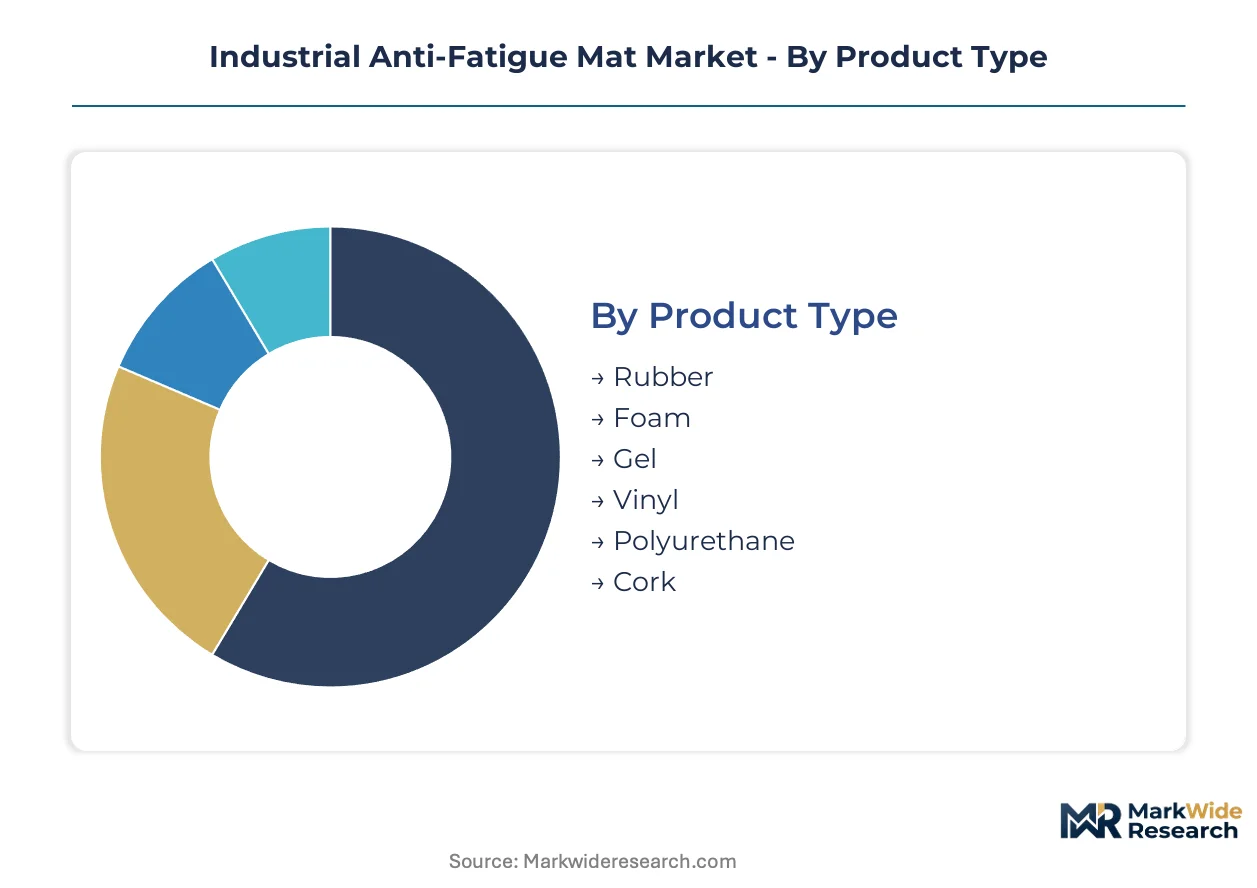
Industrial anti-fatigue mat procurement splits sharply between domestic specification-driven buyers and export-oriented contract manufacturers. Segmentation reveals how material chemistry, installation logistics, and end-use compliance requirements reshape vendor positioning across divergent supply channels.
Product Type:
Polyurethane and rubber formulations anchor domestic production in the US Midwest and German industrial corridors, while foam and vinyl variants flow through Asian export hubs serving price-sensitive warehousing contracts.
- Polyurethane:Closed-cell injection formulations deliver calibrated compressibility ratings and 40% extended service life versus rubber alternatives. German automotive OEMs and US electronics cleanrooms specify these surfaces for permanent standing stations where ISO 340 slip-resistance certification is mandatory.
- Rubber:Nitrile and natural rubber compounds retain mature volume in warehousing and distribution facilities with shorter replacement cycles. US logistics operators favor these surfaces where upfront cost compression outweighs longevity premiums.
- Foam:Open-cell polyurethane and EVA formulations serve budget-constrained applications with 12-18 month replacement horizons.
- Gel:Viscoelastic polymer cores target specialized medical and laboratory environments requiring pressure distribution mapping.
- Vinyl:PVC-backed surfaces dominate food processing installations where chemical resistance and heat tolerance intersect.
- Cork:Natural composite layers capture sustainability-focused buyers in European markets under EU Green Deal procurement protocols.
Polyurethane commands the established base. The steepest expansion runs through cork as bio-based certification requirements harden.
Industry Vertical:
Cost tier stratification separates premium-specification automotive and electronics segments from commoditized warehousing procurement where margin pools remain compressed.
- Automotive OEMs:Final-assembly stations in Germany mandate calibrated rebound surfaces meeting compressibility thresholds foam formulations cannot achieve. OEM specification lock-in concentrates supplier relationships toward compounders with captive polymer science capabilities.
- Electronics Assembly:Cleanroom-grade polyurethane mats with static-dissipative properties command premium positioning in US and German semiconductor fabrication facilities.
- Manufacturing:General assembly lines mix rubber and polyurethane deployments based on standing-duration intensity and chemical exposure profiles.
- Warehousing:Third-party logistics operators standardize across national footprints using foam and rubber surfaces with 18-24 month replacement cycles.
- Food Processing:Modular tile systems with drainage channels and antimicrobial treatments dominate poultry and dairy processing environments.
- Pharmaceuticals:ISO-classified cleanrooms specify seamless polyurethane surfaces with welded installation to eliminate contamination vectors.
Automotive OEMs anchor premium revenue concentration. Electronics assembly is gaining share fastest as semiconductor fabrication capacity expands.
Surface Texture:
Volume concentration in ribbed and pebbled textures reflects their dominance across warehousing and general manufacturing, while specialized textures capture narrow premium niches.
- Ribbed:Longitudinal ridges channel liquids and debris in food processing and outdoor applications. German meat processing facilities specify these surfaces for drainage compliance under EU hygiene regulations.
- Pebbled:Raised spherical patterns deliver omnidirectional slip resistance across warehousing and distribution floors. US OSHA inspection protocols favor these textures for general-purpose standing surfaces.
- Smooth:Non-textured surfaces serve pharmaceutical cleanrooms and electronics assembly where particulate shedding must be minimized.
- Raised Dots:Isolated protrusions target heavy-grease environments in automotive component stamping operations.
- Crosshatch:Intersecting groove patterns capture specialized machine-tending stations requiring multi-directional traction.
- Grooved:Deep channel designs dominate wet-processing environments in beverage manufacturing facilities.
Pebbled textures hold the volume base. Raised dots are climbing fastest as automotive component processing expands.
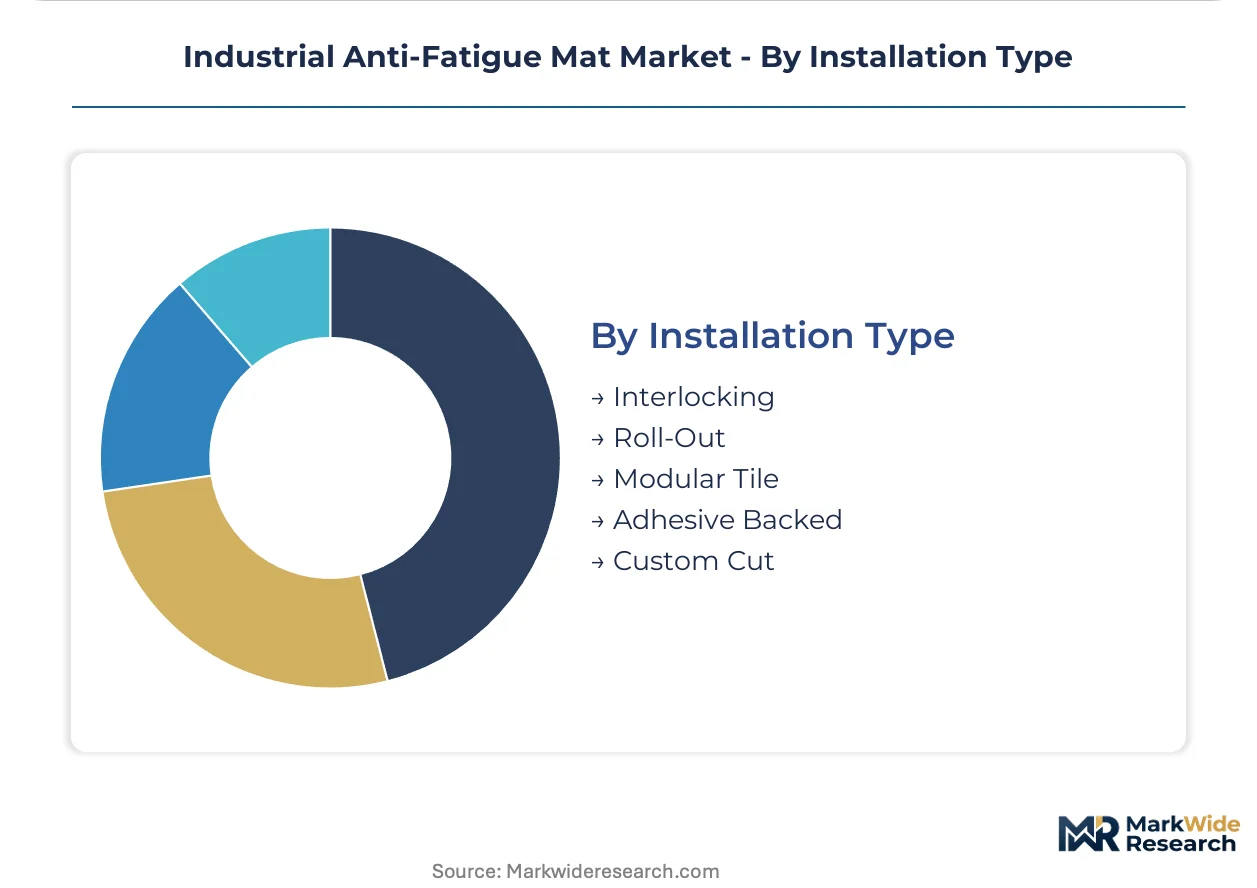
Installation Type:
Customer type bifurcation separates national contract buyers demanding interlocking standardization from regional operators using roll-out formats for rapid deployment.
- Interlocking:Puzzle-edge tile systems enable rapid reconfiguration without full-floor replacement. US food processing and pharmaceutical facilities specify these formats for sanitation cycle efficiency.
- Modular Tile:Rigid panel systems with integrated edging support heavy equipment loads in automotive final-assembly stations. German OEMs mandate these installations for ergonomic compliance documentation.
- Roll-Out:Continuous sheet formats serve warehousing and distribution where speed of installation outweighs reconfiguration flexibility.
- Adhesive Backed:Pressure-sensitive mounting targets temporary workstations and seasonal capacity expansions in e-commerce fulfillment.
- Custom Cut:CNC-fabricated shapes integrate with existing floor penetrations and equipment footprints in retrofit manufacturing environments.
Roll-out formats retain the installed base. Modular tile systems are expanding most quickly as facility standardization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German automotive OEMs absorb polyurethane premiums without volume contraction, while US warehousing operators trade service life for upfront cost compression in rubber and foam alternatives.
United States
OSHA ergonomic enforcement is converting discretionary safety spending into compliance-driven procurement across third-party logistics networks. The EPA oversees volatile organic compound emissions from polyurethane curing processes, constraining domestic manufacturing configurations. E-commerce fulfillment centers in the Midwest and Southeast are standardizing anti-fatigue surfaces across national footprints.
Germany
Automotive final-assembly stations mandate calibrated rebound surfaces meeting ISO 340 slip-resistance thresholds. REACH chemical registration requirements constrain polyurethane curing agent formulations and elevate compliance documentation burdens. Industrial corridors in Bavaria and Baden-Württemberg concentrate specification-driven demand from BMW, Mercedes-Benz, and Volkswagen assembly operations.
China
Electronics assembly expansion in semiconductor fabrication is generating cleanroom-grade surface demand. The Ministry of Ecology and Environment regulates industrial chemical emissions from polymer processing facilities. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou are absorbing polyurethane matting for precision assembly environments.
India
The PLI scheme for electronics assembly and automotive component production is generating greenfield facility construction with below-Western ergonomic matting penetration. Bureau of Indian Standards certification requirements are elevating product launch timelines for imported formulations. Gujarat and Tamil Nadu industrial corridors are emerging as concentrated demand nodes for assembly line installations.
Japan
Precision manufacturing and semiconductor fabrication sustain premium-specification surface demand. METI industrial safety guidelines shape procurement specifications for prolonged standing workstations. Kyushu and Chubu regional manufacturing clusters are specifying static-dissipative polyurethane surfaces for electronics cleanroom environments.
Industrial Anti-Fatigue Mat Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Polyurethane injection molding specialists with captive polymer science capabilities capture premium margins in automotive and electronics segments, while commodity rubber converters retain volume share in price-sensitive warehousing applications. The market organizes around three strategic archetypes: diversified materials conglomerates leveraging cross-divisional R&D, domestic-scale manufacturers anchoring regional installation networks, and modular system specialists serving reconfiguration-intensive verticals. Competitive dynamics center on M&A activity consolidating formulation capabilities and strategic partnerships certifying regional installation capacity.
Among diversified materials conglomerates, 3M exemplifies technology leadership through materials science portfolio leverage. Wearwell and M+A Matting occupy positions within the specialist tier, with the former representing domestic manufacturing scale and the latter exemplifying modular system architecture for sanitation-intensive environments. These three anchors illustrate how competitive positioning fragments across performance specification vectors rather than consolidating around unified market leadership.
| Leading Market Players |
|---|
| 3M |
| Cintas Corporation |
| Wearwell |
| NoTrax |
| Crown Matting Technologies |
| American Floor Mats |
| Eagle Mat and Floor Products |
| M+A Matting |
| UniFirst Corporation |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day polyurethane formulation lead times in the US Midwest and German industrial corridors tether pricing power to captive polymer science capabilities, compressing margin pools for commodity converters while elevating premiums for compounders with in-house R&D.
Pricing Analysis
After-sales installation and certification services now drive lifetime value capture as facilities unbundle product supply from deployment. Three-tier pricing structure across premium, standard, and economy levels separates ISO 340-certified polyurethane systems for German automotive OEMs from nitrile rubber roll-outs favored by US warehousing operators. Cost compression in foam formulations is intensifying because petrochemical input volatility prevents margin pass-through to long-term contract customers. Third-party logistics networks exhibit highest price sensitivity, while semiconductor cleanroom procurement shows lowest elasticity due to specification lock-in.
Supply Chain Analysis
Isocyanate and polyol feedstock chokepoints in the US Gulf Coast and German chemical corridors expose polyurethane specialists to crude oil-indexed cost swings. Manufacturing gravity centers on the US Midwest, Germany, and China's Yangtze River Delta, drawing from toluene diisocyanate and methylene diphenyl diisocyanate precursor streams. Single-source vulnerability concentrates in German automotive OEM supply chains where REACH-compliant curing agents face reformulation delays. Distribution runs through certified regional installation networks rather than direct product shipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from installation certification and compliance documentation is expanding faster than hardware margins as facilities outsource ergonomic audits and ISO 340 verification to mat suppliers.
For Market Incumbents: Consolidate formulation capabilities through targeted acquisition of mid-scale polyurethane compounders facing REACH compliance burdens, while anchoring regional installation networks against unbundling pressures from national warehousing contracts. Captive polymer science R&D serves as the critical defensive lever against margin erosion from commodity rubber converters. For New Entrants and Emerging Players: Lead with interlocking tile systems targeting India's PLI-funded electronics assembly greenfields, where ergonomic matting penetration remains below Western benchmarks and Bureau of Indian Standards certification creates incumbent vulnerability. White-space capture runs through modular reconfiguration formats for pharmaceutical cleanrooms requiring rapid sanitation cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming flooring divisions lacking dedicated polyurethane injection molding capabilities. Long-term viability hinges on regulatory affairs functions pre-positioned for EU Green Deal bio-based certification mandates. Watch for REACH substance restriction announcements as inflection indicators forcing supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstocks | Captive isocyanate supply secures margin stability against crude oil volatility for German automotive OEM contracts. |
| Regional Installation Network Certification | OSHA-compliant deployment capabilities unlock national warehousing contracts unbundling product from service procurement. |
| Bio-Based Polyurethane Certification | EU Green Deal alignment creates premium positioning ahead of mandated sustainability disclosures in European markets. |
| Interlocking Tile System Expansion | Modular formats capture food processing and pharmaceutical demand for rapid reconfiguration without full-floor replacement. |
| India Manufacturing Partnership | PLI scheme electronics assembly greenfields offer first-mover positioning in below-penetrated ergonomic matting markets. |
Research Methodology
Operator-level perspectives from plant engineers, EHS compliance officers, OEM procurement leads, and third-party logistics facility managers anchored the qualitative base, cross-referenced with OSHA enforcement records, EPA VOC emission filings, ISO certification databases, and customs trade data for polyurethane and rubber mat imports. Bottom-up facility deployment estimates triangulated against top-down chemical industry production figures.
Sensitivity analysis across petrochemical price bands, regulatory compliance cost escalations, and replacement cycle assumptions shaped the analytical framework. Segmentation dimensions spanned material chemistry, installation format, end-use vertical, and regional regulatory cluster. CAGRs derived from installed base turnover rates and greenfield facility absorption curves, with inputs from automotive OEM production schedules and semiconductor fabrication capacity expansion timelines.
Forecasts assume regulatory continuity in OSHA workplace ergonomic enforcement and REACH chemical registration requirements; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as EU Green Deal bio-based mandates and India PLI scheme implementation pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
Extruders and Compounding Machines Market
Industrial Materials
Steel Cord Market
Industrial Materials
Industrial Pails and Drums Market
Industrial Materials
Global Polycarbonate Sheets Market
Industrial Materials
Injection Mold Hot Runners Market
Industrial Materials
Saudi Arabia Industrial Insulation Market
Industrial Materials
Isotropic Graphite Market
Industrial Materials
Hose Reinforcement Wire Market
Industrial Materials
Plain Bearing Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
Tension Spring Market
Industrial Materials
Flat Enameled Wires Market
Industrial Materials
Plastic Gears Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
Precipitated Silica Market