
 Europe Thermal Paper Market | 2026-2036
Europe Thermal Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Thermal Paper Market Insights
Project finance and leasing arrangements for coating lines is fragmenting the competitive landscape, allowing mid-tier entrants to access production capacity without full capital commitment. Koehler Paper Group leverages its integrated pulp-to-paper operations to sustain margin control across specialty grades. Lecta competes through geographic dominance in Southern European markets. Mitsubishi Paper Mills anchors its position via R&D intensity in bisphenol-A-free thermal coatings.
Thermal paper comprises a base paper substrate coated with a color-developing layer containing leuco dyes and developers, activated by precise heat application from thermal print heads to produce images without ink or ribbons. Direct thermal dominates volume flows across European retail and logistics channels due to lower operational complexity at the point of use. Thermal transfer segments command premium positioning in healthcare labeling where archival durability and chemical resistance justify higher unit economics. Specialty paper variants occupy niche margin pools in ticketing and event access applications where custom security features differentiate supply.
REACH regulations and the EU Green Deal framework constrain developer chemistry choices while accelerating substitution toward phenol-free coating systems across the value chain. ECHA substance evaluations and national implementations in Germany, France, and Italy create layered compliance thresholds that filter market access for non-conforming imports. Stakeholders must monitor evolving restricted substance lists and print-system compatibility requirements as coating chemistry transitions reshape supplier qualification protocols.
Market Dynamics
REACH chemical restrictions and the EU Green Deal are forcing coating chemistry transitions across European thermal paper manufacturing, reshaping supplier qualification protocols and raw material sourcing patterns throughout the value chain.
Growth Catalysts
- Retail checkout modernization:German and French supermarkets are replacing legacy POS hardware with thermal-enabled systems, sustaining volume demand for direct thermal grades.
- Logistics labeling mandates:E-commerce fulfillment centers across the United Kingdom require high-speed thermal printing for parcel tracking and last-mile delivery documentation.
- Bisphenol-free coating R&D:Developer innovations in phenol-free chemistry are opening compliance pathways under ECHA substance evaluations and national implementations.
Market Restraints
- Leuco dye cost volatility:Specialized dye precursors face supply concentration from Asian chemical manufacturers, compressing margin stability for European coaters.
- Digital receipt substitution:Mobile payment platforms and email receipt systems are displacing thermal paper in premium retail segments across Nordic markets.
- REACH compliance layering:Divergent national implementations in Germany, France, and Italy create fragmented approval timelines for new coating formulations.
Strategic Opportunities
- Eastern European logistics expansion:Poland and Romania present underpenetrated demand for shipping labels as fulfillment infrastructure scales.
- Healthcare specimen labeling:Thermal transfer grades with archival durability are capturing share in clinical laboratory workflows requiring chemical resistance.
- EU circular economy incentives:Green public procurement criteria favor certified recyclable thermal papers in municipal and institutional purchasing.
Industry Challenges
- Coating line retrofit capex:Transitioning production to bisphenol-A-free systems requires significant capital deployment for reactor and drying equipment upgrades.
- Print-head compatibility testing:New phenol-free formulations must validate performance across diverse thermal printer installed bases, extending qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Thermal Paper Market |
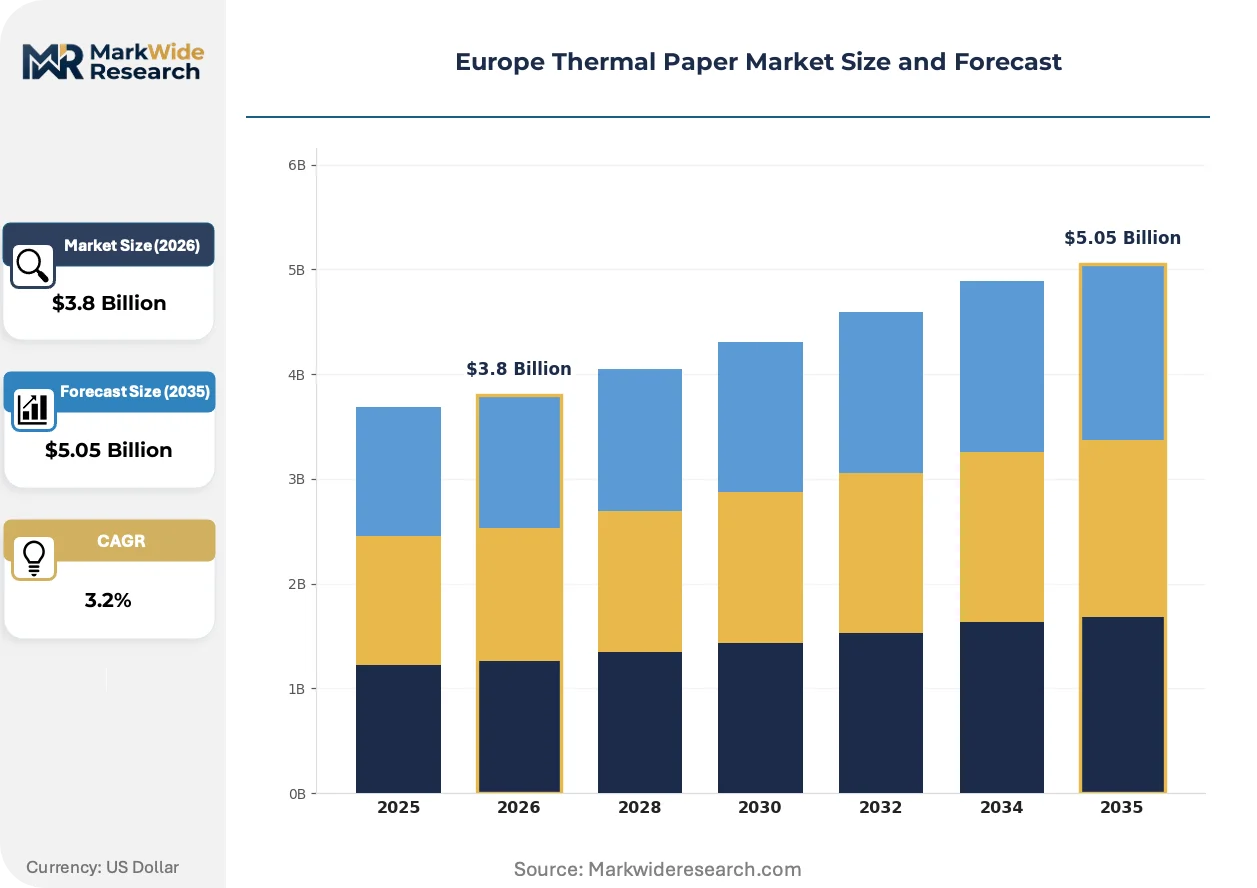
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.05 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Thermal, Thermal Transfer, Specialty Paper, Adhesive Paper End User: Retail, Logistics, Healthcare, Financial Services Thickness: 50 GSM, 60 GSM, 70 GSM, 80 GSM Application: Labeling, Printing, Tickets, Receipts |
| Companies Covered | Koehler Paper Group, Oji Holdings Corporation, Mitsubishi Paper Mills, Hansol Paper, Appvion, Jujo Thermal Ltd., Lecta, Domtar Corporation, Ricoh Company, Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Thermal Paper Market Trends and Innovations
Coating chemistry virtualization and regulatory compliance automation are restructuring how European thermal paper manufacturers formulate, test, and bring products to market.
Digital formulation platforms are virtualizing laboratory-scale coating trials, compressing development cycles for REACH-compliant thermal layers. Koehler Paper Group and specialized coaters are adopting simulation tools to predict leuco dye-developer interactions before physical production. This virtualization is reducing raw material waste and accelerating time-to-market for bisphenol-free grades.
REACH substance evaluations are tightening developer chemistry restrictions across the European Economic Area. ECHA's expanded candidate list and sunset date mechanisms are forcing coaters to pre-qualify alternative developers years ahead of formal restrictions. Healthcare labeling segments face the steepest compliance burden due to extended product liability exposure.
Consolidated procurement by retail chains is compressing supplier margins and shifting volume toward integrated pulp-to-paper manufacturers. French and German supermarket groups are reducing vendor counts and demanding certified sustainability documentation. This concentration favors suppliers with captive pulp supply and in-house coating capacity over merchant coaters dependent on spot substrate purchases.
Europe Thermal Paper Market Segmentation
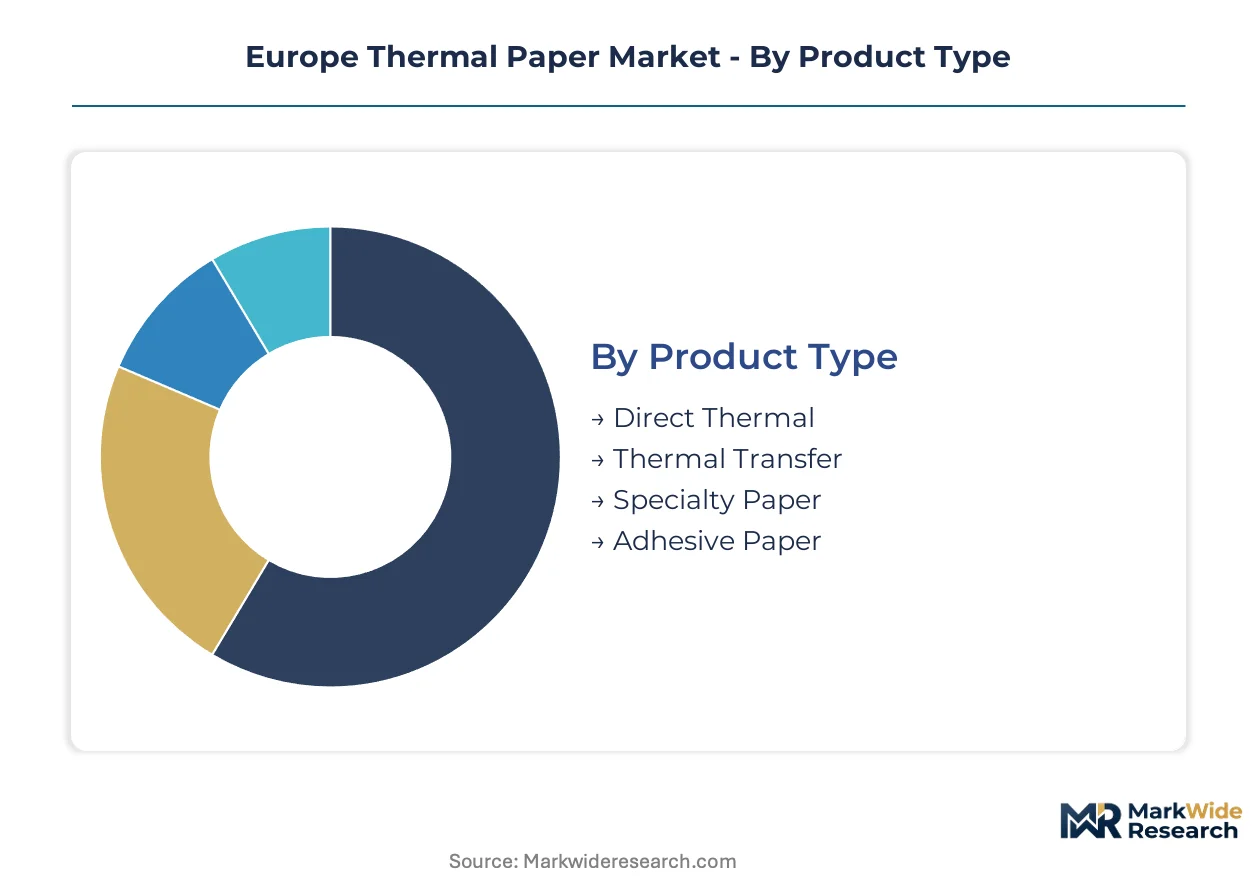
Segmentation reveals how coating chemistry requirements and print-system compatibility fragment demand across European thermal paper procurement. Distinct specification tiers create divergent margin pools and supplier qualification barriers throughout the value chain.
Product Type:
After-sales service intensity varies sharply by product type, with direct thermal demanding minimal field support while specialty paper requires ongoing print-head calibration assistance and formulation troubleshooting.
- Direct Thermal:Base paper substrate coated with leuco dye and developer layers that react to thermal print-head heat without ribbons or ink. German and French supermarket POS modernization sustains volume flows for this grade. Retail chains consolidate procurement around certified bisphenol-free formulations to satisfy ECHA compliance timelines.
- Thermal Transfer:Requires ribbon-mediated image transfer onto substrate, delivering archival durability and chemical resistance for extended retention mandates. United Kingdom healthcare specimen labeling and pharmaceutical supply chain tracking drive premium positioning. REACH substance evaluations impose steeper qualification burdens on ribbon chemistry than direct thermal alternatives.
- Specialty Paper:Custom security features for ticketing and access control applications.
- Adhesive Paper:Pressure-sensitive backing for logistics label applications.
Direct Thermal holds the largest share; momentum sits with Thermal Transfer.
End User:
Cost tier stratification separates end-user segments, with healthcare and financial services absorbing premium pricing for compliance-grade specifications while retail and logistics optimize for unit economics.
- Retail:Checkout receipt and shelf-label consumption concentrated in German, French, and United Kingdom supermarket chains. Mobile payment displacement accelerates fastest in Nordic markets, compressing volume growth in premium retail segments.
- Logistics:Parcel tracking and last-mile documentation requirements across United Kingdom e-commerce fulfillment centers. Poland and Romania infrastructure expansion opens underpenetrated demand for shipping-grade direct thermal.
- Healthcare:Specimen labeling and pharmacy dispensing with archival durability requirements.
- Financial Services:ATM receipts and transaction documentation with extended retention mandates.
Logistics commands the greatest volume concentration; healthcare delivers the steepest expansion trajectory.
Thickness:
Volume distribution across thickness grades tracks application durability requirements and print-system feed mechanism specifications.
- 50 GSM:Lightweight grade for short-duration receipts and low-durability labeling. United Kingdom quick-service restaurant and retail POS applications dominate consumption. Cost optimization pressures favor this grade in price-sensitive procurement.
- 60 GSM:Intermediate specification balancing feed reliability and material economy. German logistics labeling standardizes around this thickness for parcel tracking applications.
- 70 GSM:Enhanced durability for extended handling requirements.
- 80 GSM:Maximum rigidity for archival and security applications.
60 GSM anchors procurement volumes; 50 GSM faces displacement pressure from digital receipt substitution.
Application:
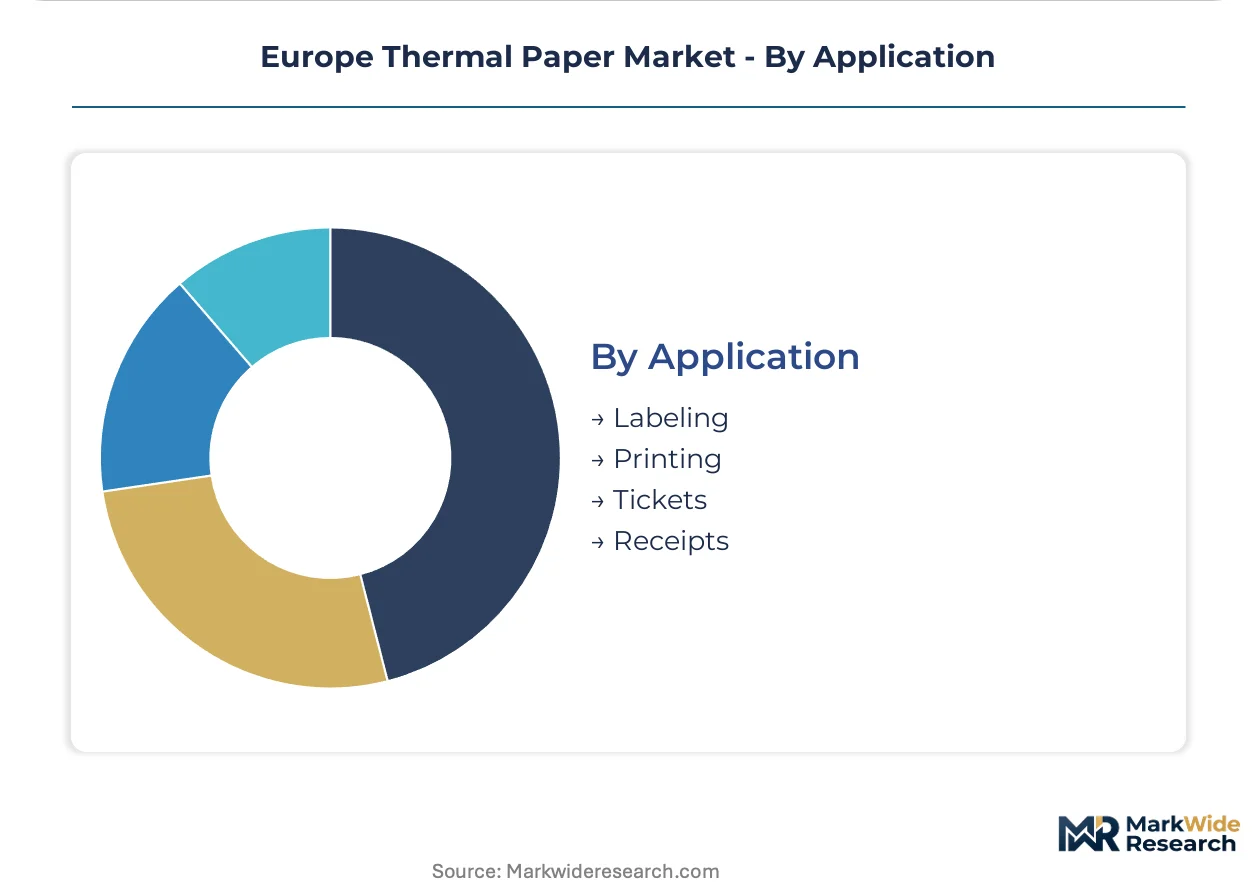
Application segmentation reflects divergent performance specifications and end-user retention requirements across European thermal paper consumption.
- Labeling:Logistics parcel identification and healthcare specimen tracking with barcode readability mandates. United Kingdom e-commerce fulfillment scaling sustains demand concentration.
- Printing:Variable information output for transactional and operational documentation.
- Tickets:Event access and transport boarding with security feature integration.
- Receipts:POS transaction documentation facing digital substitution headwinds in Nordic premium retail.
Labeling generates the greatest volume; receipts confront the most severe displacement risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's thermal paper trade flows reflect a structural deficit in specialty coating capacity, with coated substrate imports from East Asian manufacturers offsetting regional production concentrated in Germany and France. Export demand for uncoated base paper sustains Nordic pulp operations while finished thermal grades move westward into Iberian and Italian markets. Currency volatility and ECHA regulatory divergence fragment procurement patterns across national borders.
Germany
Supermarket POS modernization and logistics fulfillment automation drive thermal paper consumption across German retail and distribution channels. The country's Federal Environment Agency enforces stricter national implementations of REACH candidate list substances than baseline EU requirements. The Rhine-Main industrial corridor hosts integrated pulp-to-paper operations where manufacturers retrofit coating lines for bisphenol-A-free formulations.
France
French retail chains consolidate vendor relationships around certified sustainable thermal paper grades for checkout receipt applications. ANSM and CNIL oversight extends chemical safety evaluations beyond ECHA minimums for consumer-facing applications. The Lyon-Grenoble cluster supports specialty coating R&D facilities developing phenol-free developer alternatives.
United Kingdom
E-commerce fulfillment center expansion sustains high-volume demand for shipping labels and parcel tracking documentation. Post-Brexit regulatory divergence from REACH creates parallel compliance pathways for coating chemistry approvals. The Midlands logistics belt concentrates thermal label consumption at distribution hubs serving domestic and cross-border delivery networks.
Italy
Italian pharmaceutical supply chains and ticketing applications anchor demand for thermal transfer and specialty paper grades. National implementations of EU Green Deal procurement criteria favor certified recyclable thermal papers in public sector purchasing. The Lombardy-Veneto manufacturing triangle houses coating operations serving Southern European markets with customized security-feature substrates.
Poland
Emerging logistics infrastructure and retail modernization create underpenetrated demand for direct thermal grades in shipping and POS applications. Polish environmental inspections align with EU Green Deal timelines while maintaining transitional periods for coating chemistry substitution. The Warsaw-Łódź corridor attracts distribution center investments from cross-border e-commerce operators scaling thermal label consumption.
Europe Thermal Paper Market Competitive Landscape
On the supply side, the industry is consolidating around integrated manufacturers with captive pulp supply and in-house coating capacity, compressing margins for merchant coaters dependent on spot substrate purchases. Three strategic archetypes dominate: vertically integrated pulp-to-paper groups controlling raw material costs, specialized coating operations focusing on REACH-compliant formulation R&D, and diversified paper conglomerates leveraging geographic scale. Competitive intensity centers on coating line retrofit investments for bisphenol-free production and qualification partnerships with thermal printer OEMs.
Within the integrated manufacturing tier, Koehler Paper Group and Mitsubishi Paper Mills exemplify archetypes combining substrate control with coating specialization. Lecta occupies a position representing geographic-focused competition in Southern European markets. These three entities anchor the competitive structure through differentiated approaches to regulatory compliance and supply chain configuration.
| Leading Market Players |
|---|
| Koehler Paper Group |
| Oji Holdings Corporation |
| Mitsubishi Paper Mills |
| Hansol Paper |
| Appvion |
| Jujo Thermal Ltd. |
| Lecta |
| Domtar Corporation |
| Ricoh Company, Ltd. |
| Others |
Pricing and Supply Chain Analysis
Coating line undercapacity in the Rhine-Main corridor is forcing German manufacturers to prioritize bisphenol-free thermal grades while accepting compressed margins on legacy formulations. This utilization squeeze transfers pricing power toward integrated pulp-to-paper groups with captive substrate supply, squeezing merchant coaters dependent on spot base paper purchases.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in European thermal paper procurement. Price differentiation rests on REACH certification tier and volume scale, with healthcare labeling commanding premium positioning for archival-grade thermal transfer specifications. Cost compression in economy-tier direct thermal is intensifying because retail chains consolidate procurement around certified sustainable grades. Logistics operators exhibit the sharpest price sensitivity, while healthcare specimen labeling absorbs premium pricing for compliance-mandated durability.
Supply Chain Analysis
Leuco dye precursors feed from concentrated Asian chemical manufacturing, with developer formulations anchored in German and French coating operations. Raw material dependencies center on specialized dye intermediates, phenol-free developer alternatives, and high-purity base paper substrates. Single-source vulnerability in leuco dye supply creates exposure to input cost volatility and qualification delays. Distribution runs through consolidated retail chain procurement offices and third-party logistics label converters serving e-commerce fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European thermal paper manufacturing is narrowing around coating chemistry expertise and REACH pre-qualification capabilities that mid-tier merchants cannot replicate. The gap between integrated manufacturers with in-house R&D and spot-market coaters is widening as ECHA substance evaluations accelerate.
For Market Incumbents: Pre-empt coating line obsolescence by accelerating bisphenol-A-free reactor upgrades in German and French facilities before sunset date enforcement tightens. Lock in multi-year supply agreements with Nordic pulp operators to secure substrate cost advantage against emerging Polish logistics demand. Defensive consolidation around captive leuco dye-developer formulation capabilities will filter out merchant competitors unable to fund parallel qualification cycles. For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian logistics labeling where fulfillment infrastructure scaling outpaces local coating capacity. Target direct thermal shipping grades for e-commerce parcel tracking, where specification tolerance allows entry without archival-grade certification burden. A go-to-market partnership with regional label converters bypasses the capital barrier of integrated pulp-to-paper investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated manufacturers with long-term retail chain contracts and certified sustainable grade portfolios. Five-to-ten year viability favors coating operations with pre-qualified phenol-free formulations and established print-head compatibility testing relationships. Watch ECHA candidate list expansion velocity as the inflection signal for accelerated industry consolidation around compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Line Retrofit for Bisphenol-Free Production | REACH compliance deadlines in Germany and France mandate reactor upgrades to maintain market access. |
| Backward Integration into Leuco Dye Formulation | Captive developer chemistry reduces exposure to Asian precursor supply concentration and cost volatility. |
| Long-term Supply Agreement with Nordic Pulp Suppliers | Base paper cost stability secures margin control against spot-market merchant coaters. |
| Joint Venture with Thermal Printer OEMs | Print-head compatibility testing partnerships accelerate qualification cycles for new coating formulations. |
| Geographic Expansion into Polish Logistics Infrastructure | E-commerce fulfillment center investments in the Warsaw-Łódź corridor drive underpenetrated label demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA substance evaluation databases, EU customs trade records, and coating equipment manufacturer technical specifications. Primary interviews engaged thermal paper plant managers, retail chain procurement directors, logistics label converters, and REACH compliance officers across Germany, France, and the United Kingdom. Secondary validation drew from Cefic chemical industry reports, national environment agency implementation notices, and thermal printer OEM technical documentation. Bottom-up volume modeling triangulated against top-down market sizing across coating chemistry transitions.
Forecast inputs considered coating grade segmentation by bisphenol-free certification status, end-use industry durability requirements, and regional logistics infrastructure buildout. The analytical framework modeled product type, thickness specification, application, and end-user industry across the projection horizon. CAGRs were derived from installed base replacement cycles for POS hardware and e-commerce fulfillment center expansion trajectories. Leuco dye cost curves and REACH sunset date schedules informed chemistry transition pacing assumptions.
Stress conditions across leuco dye supply disruption, accelerated ECHA restriction timelines, and digital receipt substitution velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about coating line retrofit completion rates and retail chain procurement consolidation patterns. Cross-checking against national customs data for coated paper trade flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Pigment Market
Paper Products
Paper and Board Technologies Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Paper Machine Systems Market
Paper Products
Global Cellulose Sponge Market
Paper Products
Woodfree Paper Market
Paper Products
Synthetic Paper Market
Paper Products
Global Electrical Insulation Paper Market
Paper Products
Thermal Paper Market
Paper Products
Graphic Paper Market
Paper Products
Canada Honeycomb Paper Market
Paper Products
Global Molded Pulp Products Market
Paper Products
Sawn Wood Market
Paper Products
Paper Coating Materials Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Global Direct Thermal Ticket Paper Market