
 North America Decor Paper Market | 2026-2036
North America Decor Paper Market Size, Share, and Industry Trends Forecast 2026-2036
North America Decor Paper Market Analytics
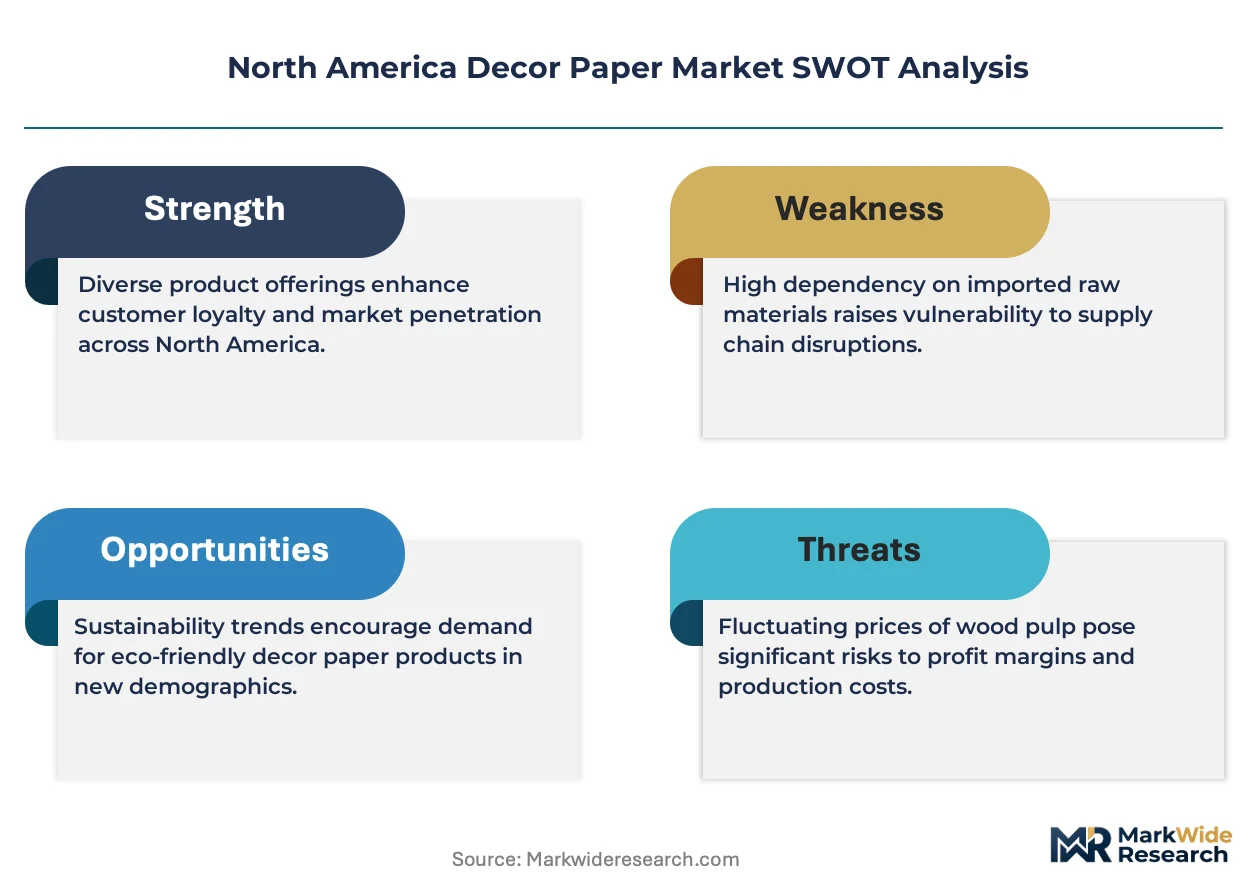
Subscription-based color-matching and digital design libraries is consolidating how decor paper specifications reach architects and interior designers. International Paper leverages its integrated pulp-to-paper infrastructure to sustain cost advantages across bulk decorative sheet orders. WestRock Company anchors its position through specialized coating technologies that enhance print fidelity on high-end vinyl wraps. Ahlstrom-Munksjö competes by dominating niche segments with advanced fiber formulations for moisture-resistant applications.
Decor paper comprises base papers impregnated with melamine, urea, or phenolic resins, then printed with gravure or digital processes to create surfacing materials for furniture, flooring, and wall panels. The base paper typically weighs 60-130 gsm and accepts resin loads of 30-60% by weight to achieve scratch resistance and thermal stability for lamination presses. Wallpaper and decorative sheets lead volume, while vinyl wraps capture expanding margin pools in commercial refurbishment cycles. The hospitality end-use segment shows structural momentum as hotel chains prioritize rapid-guestroom renovation programs. Material-grade segmentation reveals paper substrates retaining dominance, though composite blends gain traction where dimensional stability requirements exceed traditional offerings.
EPA regulates volatile organic compound emissions from resin curing operations, while CARB Phase 2 in California enforces stringent formaldehyde emission limits that directly constrain adhesive and impregnation chemistry choices. OSHA workplace exposure standards for formaldehyde and methanol further shape manufacturing plant configurations and automation investments across the region. Stakeholders must monitor evolving state-level chemical disclosure requirements and assess whether digital printing migration can reduce resin dependency without sacrificing surface performance benchmarks.
Market Dynamics
CARB Phase 2 and EPA emissions standards are compressing formaldehyde allowances in resin systems, forcing manufacturers to reformulate impregnation chemistry while maintaining surface performance benchmarks for lamination presses.
Growth Catalysts
- Residential renovation cycles:United States homeowners are accelerating kitchen and bathroom refresh programs, pulling decorative sheet demand through big-box retail and contractor channels.
- Low-emission resin mandates:California's CARB Phase 2 regulations are creating competitive differentiation for manufacturers with certified low-formaldehyde adhesive systems.
- Digital gravure hybridization:Print houses are blending traditional cylinder gravure with inkjet heads to reduce setup waste and enable shorter production runs for custom hospitality interiors.
Market Restraints
- Melamine price volatility:Urea-formaldehyde resin feedstock costs fluctuate with natural gas pricing, squeezing margin predictability for impregnation specialists.
- Southeastern supply concentration:Tennessee and North Carolina furniture manufacturing clusters create geographic vulnerability to localized weather disruptions and logistics bottlenecks.
- Performance ceiling in traditional substrates:Standard 60-130 gsm base papers face dimensional stability limits that constrain high-humidity commercial flooring applications.
Strategic Opportunities
- Mexico manufacturing expansion:Untapped production capacity near Guadalajara offers tariff-advantaged export positioning into United States cabinetry markets.
- Composite fiber blends:Aramid and glass fiber hybrid substrates are opening moisture-resistant specification slots in cruise ship and healthcare interiors.
- Subscription design libraries:Cloud-based color-matching platforms are disintermediating traditional sample fulfillment for architectural specification teams.
Industry Challenges
- Skilled press operator shortage:Gravure cylinder engraving and digital RIP calibration expertise is aging out faster than vocational programs replenish talent pipelines.
- Legacy ERP integration:Batch-oriented manufacturing execution systems resist real-time connectivity with cloud-based design-to-print workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Decor Paper Market |
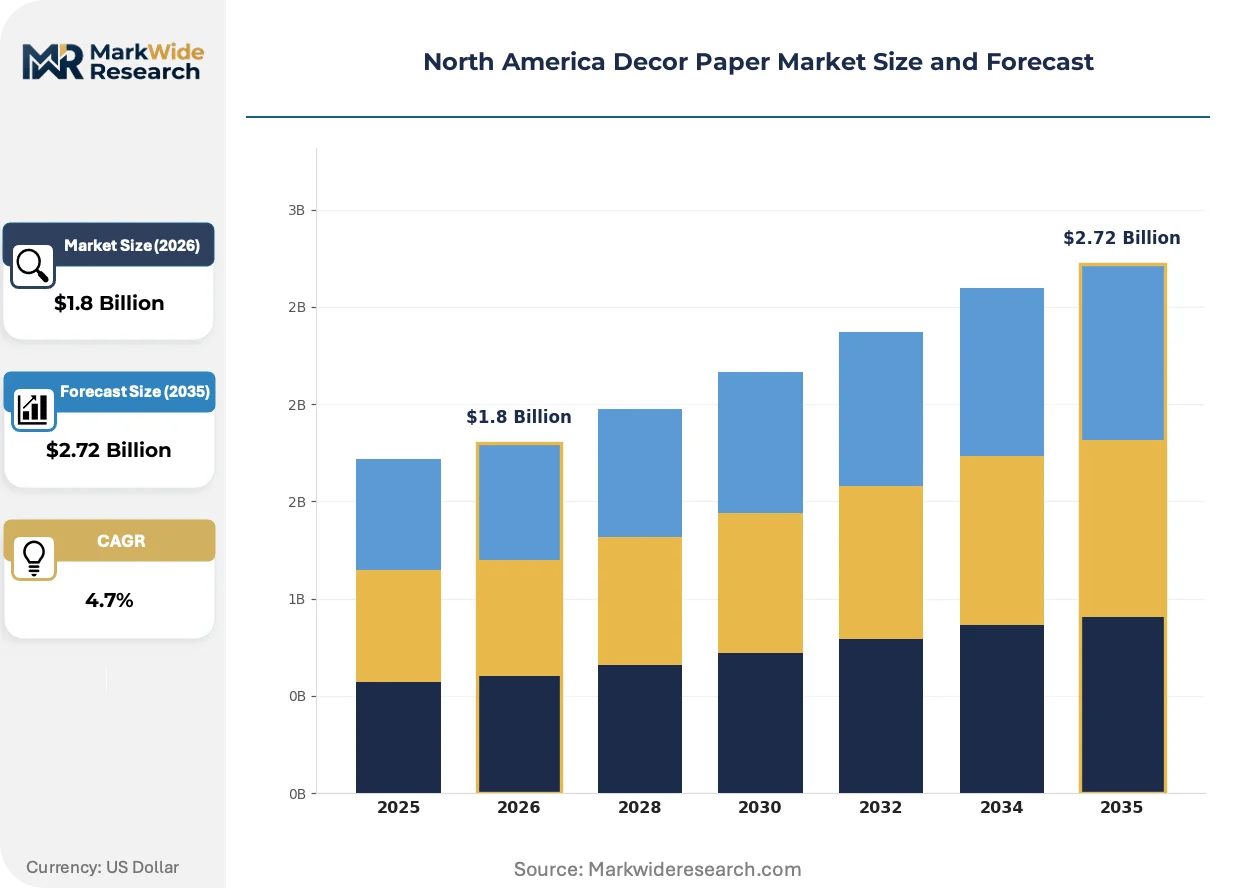
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wallpaper, Decorative Sheets, Vinyl Wraps, Printing Paper End Use: Residential, Commercial, Institutional, Hospitality Material: Paper, Plastic, Fabric, Composite Distribution Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | International Paper, WestRock Company, Domtar Corporation, Ahlstrom-Munksjö, Felix Schoeller Group, Surteco Group, Glatfelter, Koehler Paper, Interprint, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Decor Paper Market Evolving Landscape
Digital printing architectures are rewriting production economics for short-run decorative surfacing, while regulatory chemistry constraints and hospitality procurement centralization reshape competitive positioning across the value chain.
Inkjet deposition systems for melamine-compatible aqueous inks are converging with traditional gravure infrastructure in hybrid press configurations. Hotel renovation contractors are specifying these shorter-run digital outputs for guestroom refresh cycles. This technology pairing is compressing minimum order quantities from thousands of linear meters to hundreds, enabling just-in-time inventory models for regional distributors.
EPA volatile organic compound rules for resin curing operations are tightening thermal oxidizer requirements in existing manufacturing plants. Compliance investments are diverting capital from capacity expansion toward emissions control retrofits. Southeastern United States facilities face the steepest retrofit timelines given their concentration of legacy impregnation lines commissioned before current standards.
Hospitality procurement teams are consolidating specification authority at corporate headquarters, displacing individual property-level purchasing autonomy. Brand-standard color palettes are narrowing approved supplier lists to mills with certified resin systems and digital proofing capabilities. Canada and the United States hotel chains are leading this centralization, with procurement committees now mandating chain-of-custody documentation for formaldehyde compliance.
North America Decor Paper Market Segmentation
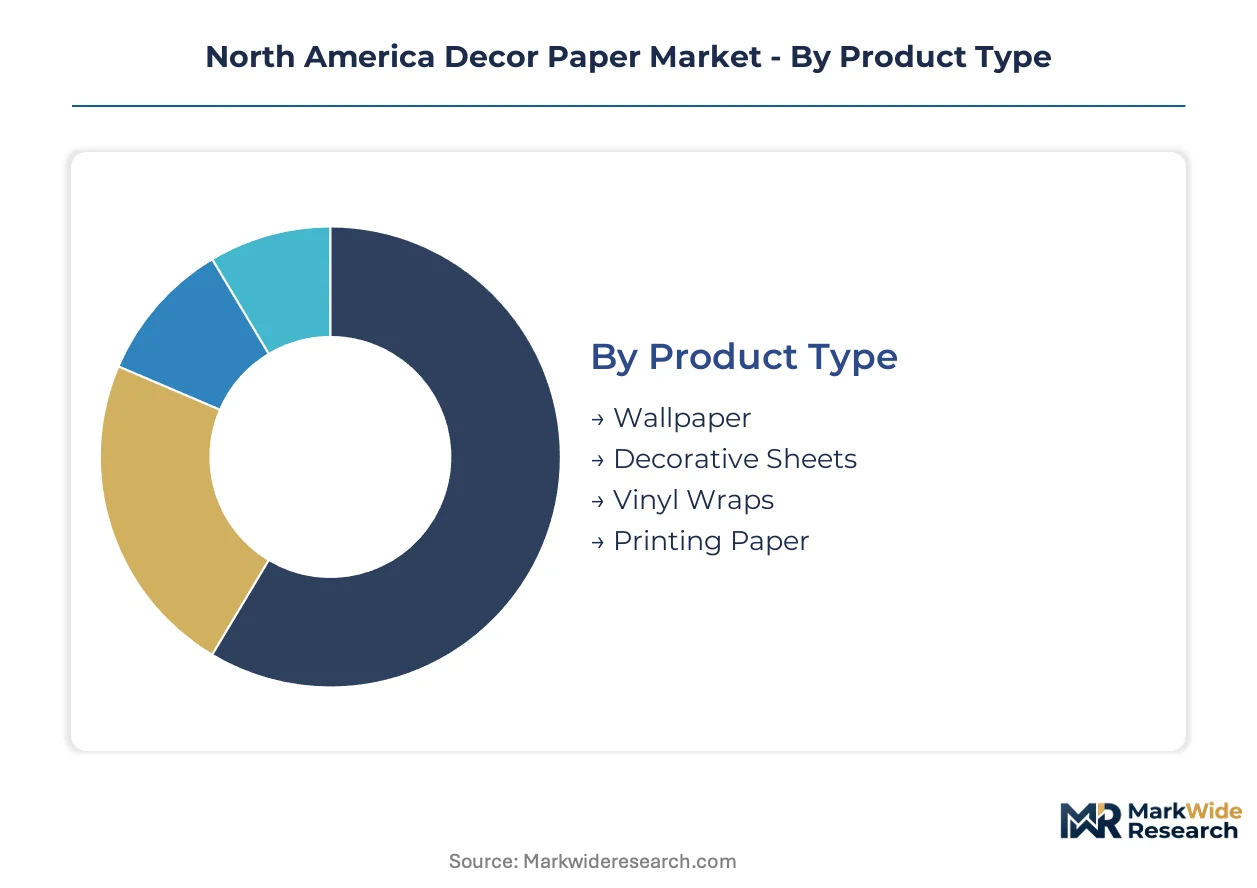
Decor paper segmentation reveals how resin chemistry, substrate engineering, and distribution economics split the market into distinct competitive arenas. Each category carries unique margin profiles and regulatory exposure that reshape supplier priorities across United States and Canadian demand centers.
Product Type:
Standalone decorative products dominate specification workflows, while embedded surfacing materials integrate deeper into manufacturing supply chains with longer qualification cycles.
- Wallpaper:Non-woven and vinyl-backed substrates carry 60-130 gsm base weights with surface-printed or through-dyed color layers. Demand clusters in United States residential renovation corridors, where big-box retail channels and contractor direct programs pull volume through southeastern distribution hubs.
- Decorative Sheets:Melamine-impregnated papers engineered for thermal lamination onto particleboard and MDF substrates. Furniture manufacturers in North Carolina and Tennessee specify these for kitchen cabinetry and closet systems, with CARB Phase 2 compliance now a baseline qualification.
- Vinyl Wraps:Calendered PVC and polyolefin films with pressure-sensitive or heat-activated adhesives.
- Printing Paper:Uncoated and coated stocks for gravure and digital decor paper production.
Decorative sheets lead volumes today; vinyl wraps are gaining share fastest.
End Use:
Cost-tier segmentation separates specification-driven commercial procurement from price-sensitive residential replacement cycles.
- Residential:Homeowner-directed kitchen and bathroom refresh programs. United States renovation contractors source through lumberyard and home center channels, with digital design tools accelerating color selection velocity.
- Commercial:Office and retail fit-out specifications. Corporate real estate teams prioritize rapid-install surfacing for tenant improvement budgets, with vinyl wraps capturing share in open-plan flooring and wall applications.
- Institutional:Healthcare and education facilities requiring enhanced durability and cleanability standards.
- Hospitality:Hotel chain renovation programs with centralized procurement authority.
Residential commands absolute volume; hospitality is climbing the fastest.
Material:
Volume concentration sits with traditional substrates, while margin expansion follows engineered alternatives that solve dimensional stability failures.
- Paper:Cellulosic base stocks ranging from 60-130 gsm, impregnated with melamine, urea-formaldehyde, or phenolic resins. Southeast United States furniture clusters consume bulk tonnage, though humidity-driven dimensional limits constrain high-performance flooring specs.
- Plastic:PVC, PET, and polyolefin films for vinyl wrap and thermoformed applications.
- Fabric:Textile-backed vinyl and non-woven wallcoverings.
- Composite:Aramid, glass fiber, and hybrid substrates engineered for moisture resistance. Cruise ship and healthcare interior specifications in Florida and California drive adoption where traditional paper substrates fail dimensional stability requirements.
Paper retains volume dominance; composite is expanding most quickly.
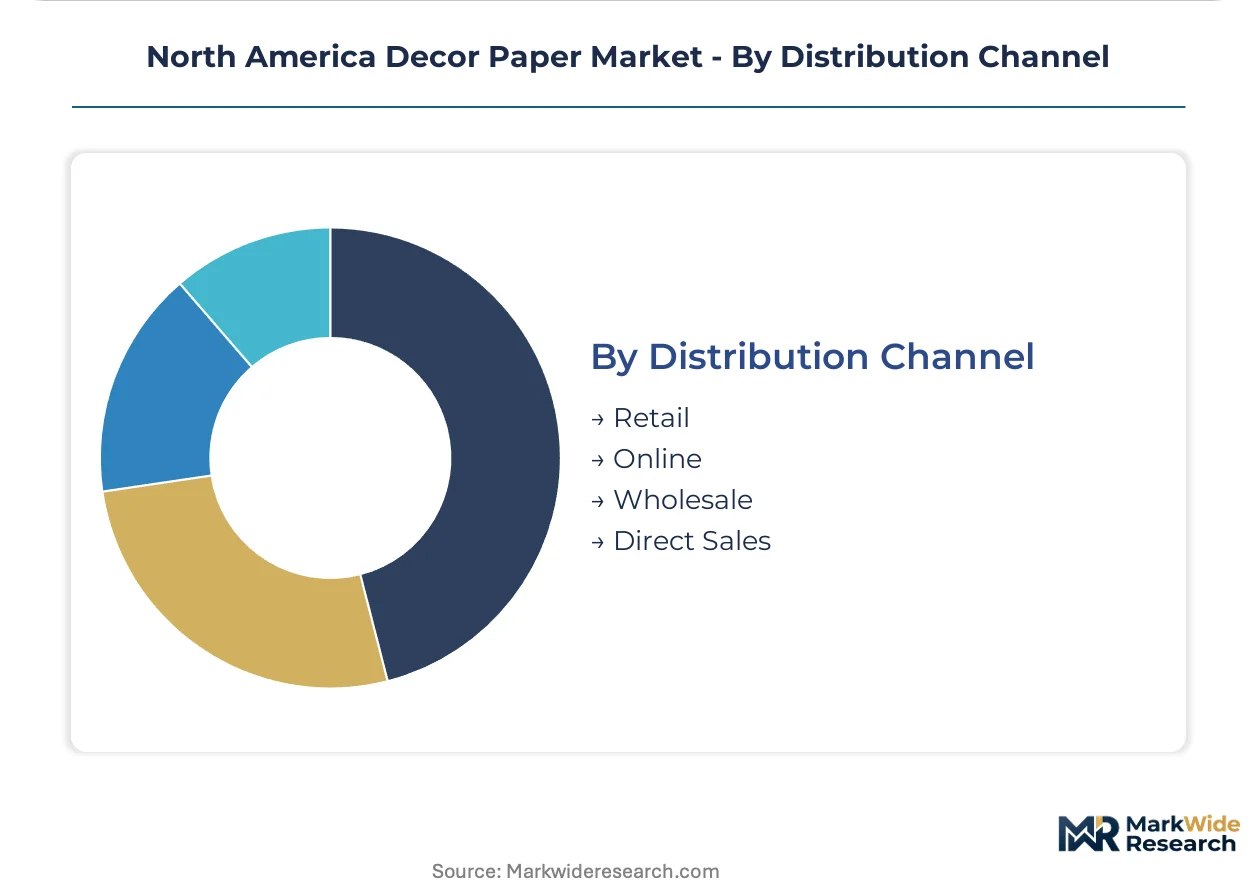
Distribution Channel:
Customer-type segmentation splits transactional retail from relationship-driven wholesale and specification channels.
- Retail:Home centers and specialty décor stores serving do-it-yourself homeowners. United States big-box chains stock limited color palettes with rapid inventory turns, pushing suppliers toward high-volume, low-SKU production economics.
- Online:Direct-to-consumer and business-to-business platforms.
- Wholesale:Distributor networks supplying lumberyards, cabinet shops, and commercial contractors. Southeastern United States wholesale hubs maintain regional inventory positions to serve Tennessee and North Carolina manufacturing clusters with two-day fulfillment.
- Direct Sales:Mill-direct relationships with large furniture OEMs and hospitality procurement groups.
Wholesale leads channel volumes today; direct sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are reshaping production geography across North America as manufacturers weigh EPA compliance costs against Mexican operational savings. Cost-of-compliance gaps between jurisdictions are accelerating facility relocation decisions for resin-impregnation operations.
United States
Residential renovation cycles in the Southeast are pulling decorative sheet demand through Tennessee and North Carolina furniture clusters. EPA volatile organic compound rules and OSHA formaldehyde exposure standards constrain existing plant configurations. Charlotte and Nashville manufacturing corridors concentrate impregnation capacity serving cabinet and closet OEMs.
Canada
Healthcare and cruise ship interior specifications in British Columbia and Ontario are driving moisture-resistant composite substrate adoption. Health Canada and PMRA chemical disclosure requirements shape import documentation for resin systems. Toronto-area distributors maintain cross-border inventory positions serving Great Lakes cabinetry markets.
Mexico
Untapped production capacity near Guadalajara offers tariff-advantaged export positioning into United States cabinetry channels. Mexican environmental regulations present lower compliance burdens for thermal oxidizer investments. Nuevo León and Jalisco industrial zones attract resin-impregnation lines seeking proximity to southeastern US demand centers.
Southeastern United States
Furniture manufacturing concentration in North Carolina and Tennessee creates geographic vulnerability to weather disruptions and logistics bottlenecks. CARB Phase 2 formaldehyde limits from California influence specifications even in non-regulated states. High Point and Memphis distribution hubs coordinate just-in-time fulfillment for big-box retail channels.
California
Stringent CARB Phase 2 formaldehyde emission limits directly constrain adhesive and impregnation chemistry choices for suppliers serving western markets. Digital printing migration accelerates here as manufacturers seek resin-dependency reductions. Los Angeles and San Francisco specification offices drive hospitality procurement centralization for hotel chain renovation programs.
North America Decor Paper Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pulp-to-paper conglomerates commanding bulk decorative sheet volumes while coating technology specialists capture premium vinyl wrap margins. The vendor base organizes around three strategic archetypes: integrated forest products giants with captive fiber supply, specialized coating and impregnation houses with formulation expertise, and digital print service providers with hybrid gravure-inkjet capabilities. Consolidation pressures favor M&A activity among mid-tier impregnation specialists, while capacity expansion concentrates in Mexico to exploit tariff and regulatory arbitrage.
Among North American integrated producers, International Paper, WestRock Company, and Ahlstrom-Munksjö occupy positions that exemplify divergent competitive vectors. International Paper represents the scale-driven archetype leveraging pulp-to-paper infrastructure for cost position. WestRock Company anchors the specialized coating tier where print fidelity commands premium positioning. Ahlstrom-Munksjö sits within the niche formulation segment targeting moisture-resistant and high-performance substrate applications.
| Leading Market Players |
|---|
| International Paper |
| WestRock Company |
| Domtar Corporation |
| Ahlstrom-Munksjö |
| Felix Schoeller Group |
| Surteco Group |
| Glatfelter |
| Koehler Paper |
| Interprint |
| Others |
Value Network & Pricing Analysis
CARB Phase 2 formaldehyde emission limits gate qualified supply for premium-tier decorative sheet specifications across North American cabinetry markets. Mills bearing certified low-emission resin systems command pricing premiums from hospitality procurement committees and furniture OEMs seeking baseline qualification for California and de facto national distribution.
Pricing Analysis
Capacity additions in Mexico are reshaping price floors for standard-grade decorative sheets entering southeastern United States cabinetry channels. Three-tier pricing structure across premium, standard, and economy levels separates CARB-certified mills from legacy operators and spot-market importers. Price differentiation hinges on certification tier and volume scale, with bulk furniture OEMs extracting steepest discounts. Cost compression in standard grades is intensifying because Mexican thermal oxidizer compliance burdens trail EPA requirements. Residential renovation contractors show highest price sensitivity; hospitality procurement committees demonstrate least.
Supply Chain Analysis
CARB certification and EPA emissions compliance gate qualified supplier lists for North American furniture and hospitality procurement. Raw material flows center on melamine resin feedstocks, urea-formaldehyde precursors, and 60-130 gsm base paper stocks sourced from integrated pulp producers. Supply chain risk concentrates in tariff exposure for Mexican export routes serving Tennessee and North Carolina manufacturing clusters. Distribution runs through southeastern wholesale hubs maintaining two-day fulfillment positions for big-box retail and contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Decor Paper Market functions as a stable compounder anchored by residential renovation cycles that refresh kitchen and bathroom specifications regardless of macroeconomic volatility.
For Market Incumbents: Anticipate digital gravure hybridization displacing pure cylinder gravure capacity as hospitality procurement committees mandate shorter-run capabilities. Defend position by deepening backward integration into low-emission resin formulation and securing CARB Phase 2 certification ahead of potential federal adoption. Channel control through mill-direct relationships with furniture OEMs in North Carolina and Tennessee remains the priority lever against Mexican import competition. For New Entrants and Emerging Players: Launch via subscription-based color-matching platforms targeting architectural specification teams disintermediated from traditional sample fulfillment. White-space concentrates in moisture-resistant composite substrates for Florida cruise ship and California healthcare interiors where traditional paper fails dimensional stability requirements. Direct sales to hospitality procurement committees offers the most penetrable go-to-market angle given centralized specification authority. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier impregnation specialists because regulatory compliance investments are diverting capital from capacity expansion toward emissions control retrofits. Long-term viability frames around mills with hybrid digital-gravure capabilities and certified resin systems. Monitor EPA formaldehyde rulemaking expansion as the signal to watch for inflection in qualified supply scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Mexican resin-impregnation lines near Guadalajara exploit tariff advantages into US cabinetry markets. |
| Backward Integration | Captive melamine resin production insulates margin predictability from natural gas price volatility. |
| Green Manufacturing Transition | Low-emission thermal oxidizer retrofits qualify southeastern plants for hospitality procurement lists. |
| Long-term Supply Agreement | Multi-year contracts with North Carolina furniture OEMs lock volume through renovation cycle downturns. |
| Joint Venture | Hybrid press partnerships between gravure incumbents and inkjet specialists accelerate digital migration. |
Research Methodology
Direct dialogue with resin formulation chemists, gravure press operators, hospitality procurement directors, furniture OEM purchasing managers, and southeastern wholesale distributors anchored qualitative findings. Secondary validation drew from EPA enforcement actions, CARB certified product listings, SEC 10-K disclosures of integrated paper producers, and customs trade data for decorative sheet imports. Bottom-up demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation outputs disaggregated volume and value across product type, end-use vertical, substrate material, and distribution channel dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical renovation spending correlation with decorative sheet consumption. Industry-specific inputs included natural gas price trajectories affecting melamine resin costs and hospitality capital expenditure cycles for guestroom refresh programs.
Several conditions sit outside the modeled scope, including potential federal adoption of California CARB Phase 2 standards and disruptive substitution by thermoplastic surfacing films. Forecasts reflect assumptions regarding sustained residential renovation activity and stable trade policy for Mexican exports. A model refresh is warranted upon material change in EPA formaldehyde rulemaking or hospitality procurement centralization velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Printing Paper Market
Paper Products
Functional and Barrier Coatings for Paper Market
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
Global Copier Paper Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
Filtration Paper Market
Paper Products
Aramid Paper Market
Paper Products
Tissue Paper Market
Paper Products
Unbleached Hardwood Kraft Pulp Market
Paper Products
Overlay Paper Market
Paper Products
Paper Core Market
Paper Products
Compressed Fiberboard Market
Paper Products
Paper Glass Market
Paper Products
Household Paper Market
Paper Products
Pulp Market
Paper Products
Bleached Softwood Kraft Pulp Market