
 Semi Chemical Wood Pulp Market | 2026-2036
Semi Chemical Wood Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Semi Chemical Wood Pulp Market Analytics
The EU Green Deal is rebalancing semi-chemical pulp procurement toward mills with verified carbon intensity disclosures. International Paper leverages its southeastern US mill network to supply packaging-grade NSSC pulp with integrated forestry operations. Stora Enso Oyj anchors Nordic demand through its Oulu bioproduct mill, which competes on energy-efficient pulping configurations.
Semi-chemical wood pulp combines mechanical fiber liberation with limited chemical treatment, typically yielding 65-85% pulp from wood input while retaining lignin content that strengthens packaging papers. The material primarily serves corrugating medium and molded fiber applications where stiffness and crush resistance outweigh brightness requirements. Unbleached semi-chemical pulp dominates volume flows into containerboard furnish, while bleached grades command premium positioning in food-contact paperboard. Biomechanical processing variants are gaining traction as mills seek to reduce sulfur-based chemical loading without sacrificing yield targets.
The EPA enforces effluent limitations under the Cluster Rule that constrain sulfite and kraft pulping chemistry choices in US mill upgrades. REACH compliance through ECHA governs chemical inputs for European pulp imports, while China's MEE applies dual carbon goals to domestic pulp capacity expansions. Stakeholders must monitor how regulatory tightening on Scope 3 emissions reshapes supplier qualification criteria for multinational packaging buyers.
Market Dynamics
Amazon and Walmart sustainability mandates are concentrating semi-chemical pulp procurement among mills with verified Scope 3 carbon disclosures, reshaping supplier qualification criteria across North American corrugated packaging supply chains.
Growth Catalysts
- EU Green Deal industrial emissions benchmarks:European mills are accelerating adoption of lower-carbon pulping chemistries to maintain access to multinational packaging buyer networks.
- Southeastern US pine plantation supply chains:Integrated packaging complexes in Georgia and South Carolina are expanding capacity to serve e-commerce fulfillment center demand.
- Biomechanical processing variants:Sulfur-reduced pulping configurations are attracting investment from mills seeking yield retention without full chemical loading.
Market Restraints
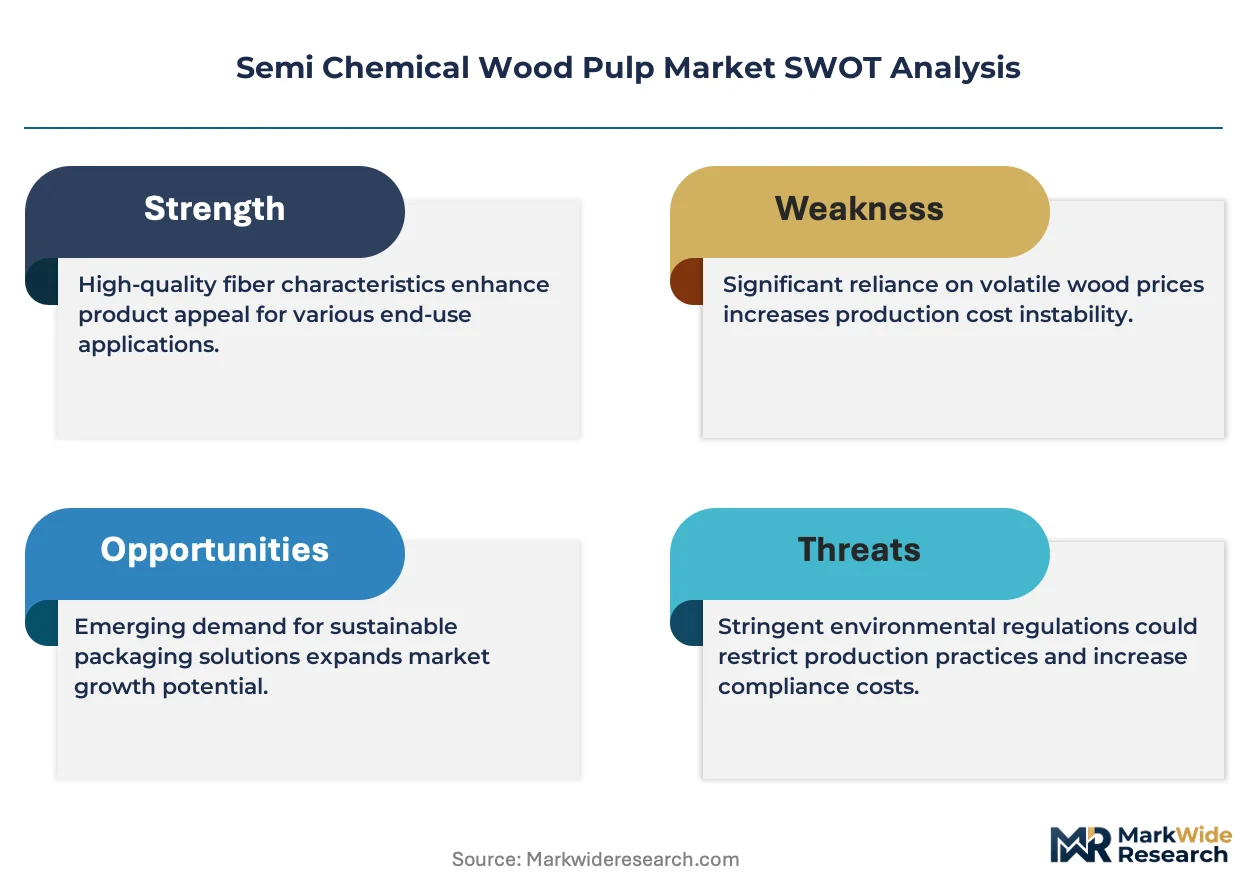
- Sulfur chemical input cost volatility:Sodium sulfite and sulfuric acid price swings compress operating margins for NSSC mills dependent on spot chemical markets.
- Supply concentration in Nordic and southeastern US mill networks:Limited geographic diversification of bleached semi-chemical capacity creates single-source risk for food-contact paperboard buyers.
- Mechanical pulp yield ceiling:Lignin retention requirements for corrugating medium strength prevent yield improvements beyond 85% without fiber quality degradation.
Strategic Opportunities
- India's packaging board capacity expansion:Domestic containerboard mills present unmet demand for semi-chemical pulp imports as local furnish quality struggles with recycled fiber contamination.
- Molded fiber food service applications:Bleached semi-chemical grades are penetrating single-use plastic replacement markets through compostable tray and clamshell formats.
- EPA Cluster Rule effluent technology:US mills investing in closed-loop water systems can capture regulatory preference under tightened sulfite discharge limits.
Industry Challenges
- Process control engineering talent scarcity:NSSC pulping requires specialized expertise in liquor chemistry balance that retiring workforces are not replenishing.
- Carbon accounting system integration:Mills face execution friction connecting forestry operations data to buyer-mandated Scope 3 disclosure platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semi Chemical Wood Pulp Market |
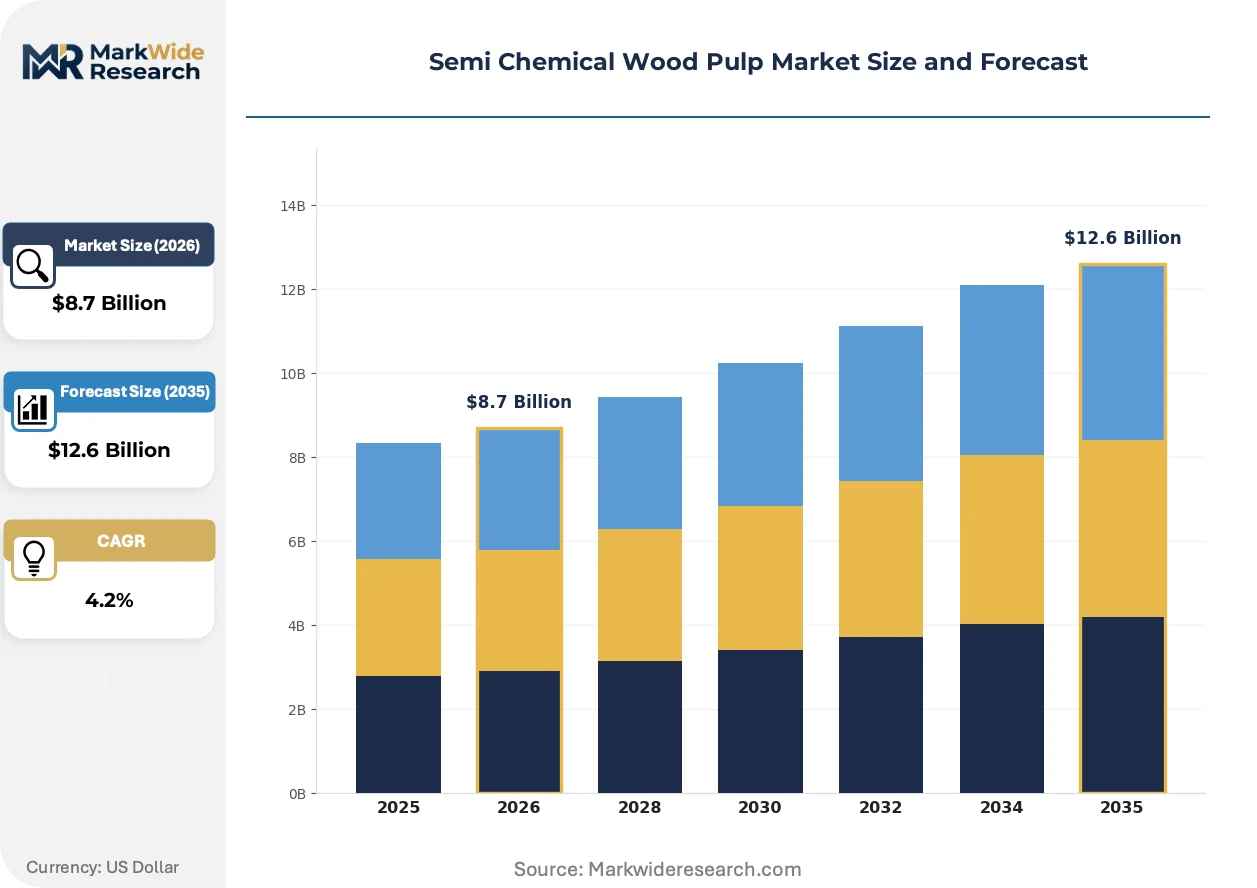
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bleached Semi-Chemical Pulp, Unbleached Semi-Chemical Pulp, High Yield Pulp, Low Yield Pulp End Use Industry: Packaging, Paperboard, Tissue, Specialty Papers Technology: Mechanical Processing, Chemical Processing, Biomechanical Processing, Hybrid Processing Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | JK Paper Ltd., Ilim Group, China Haisum Engineering Co., Ltd., Andritz Pulp and Paper, Arkhangelsk PPM, International Paper, WestRock Company, Stora Enso Oyj, UPM-Kymmene Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semi Chemical Wood Pulp Market Evolving Landscape
Semi-chemical pulp processing is converging with digital process control and closed-loop chemistry recovery, compressing the gap between mechanical yield efficiency and environmental compliance benchmarks.
Extended delignification pre-treatments are consolidating control over fiber stiffness variability in corrugating medium production. Packaging converters in the southeastern United States are adopting these modified NSSC sequences to reduce basis weight while maintaining crush resistance. The technology is consolidating procurement decisions around mills with demonstrated energy-per-ton performance transparency.
REACH compliance through ECHA is tightening chemical input documentation requirements for European pulp imports. Mills exporting to EU containerboard producers must now disclose full substance inventories across pulping liquor cycles. Food-contact paperboard segments are responding by qualifying alternative biocide treatments ahead of scheduled restriction reviews.
Buyer consortiums are consolidating volume commitments around mills with integrated forestry certification. Large corrugated packaging groups are displacing fragmented spot purchasing with multi-year offtake agreements tied to verified carbon intensity thresholds. This pattern is most visible among Amazon and Walmart tier-one suppliers in the southeastern United States.
Semi Chemical Wood Pulp Market Segmentation
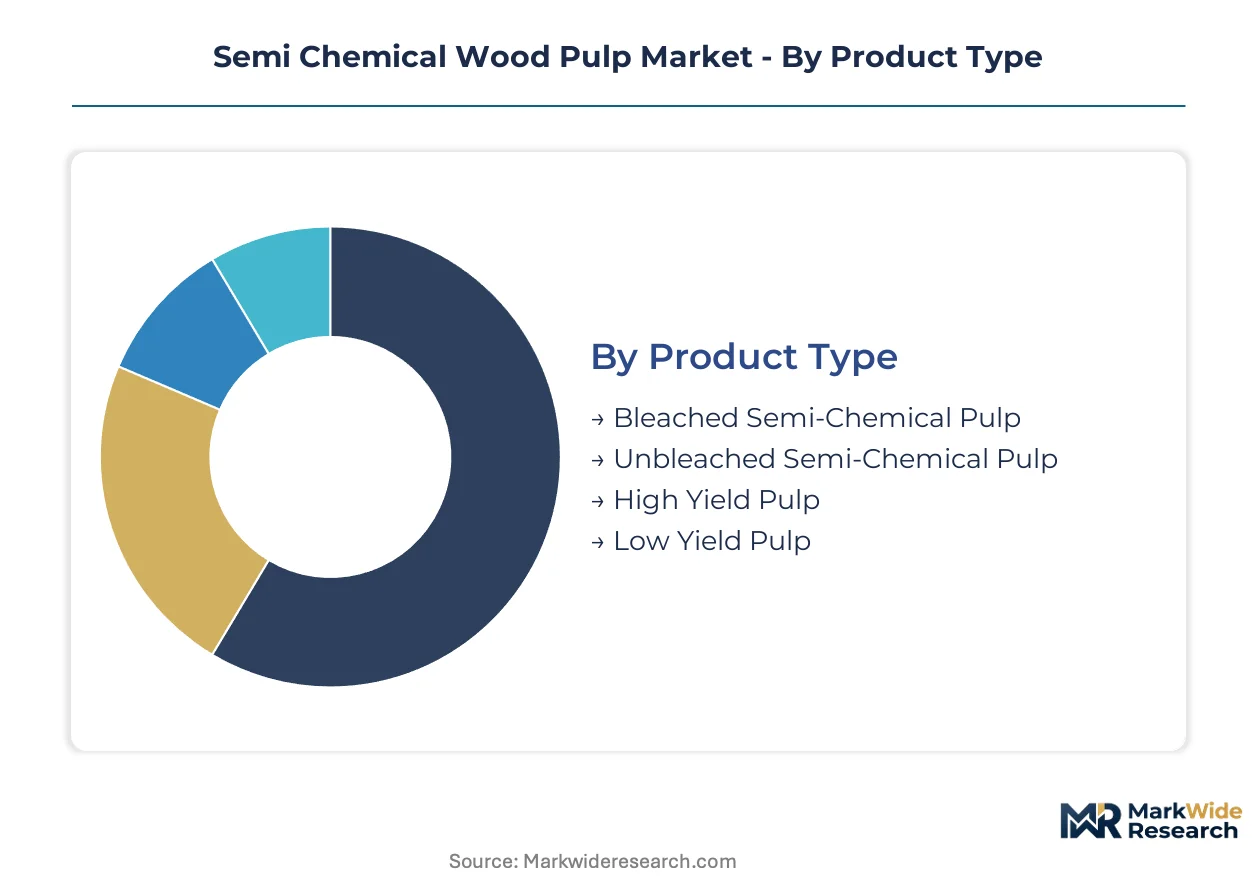
Segmentation in semi-chemical wood pulp reveals how yield chemistry and brightness specifications map to divergent margin structures across packaging and food-contact applications. Buyers qualify suppliers through different technical gateways depending on whether stiffness or purity commands the furnish decision.
Product Type:
Unbleached grades dominate tonnage flows while bleached variants capture premium positioning in regulated food-contact segments.
- Unbleached Semi-Chemical Pulp:Retains native lignin content at 65-85% yield, delivering the crush resistance and stiffness that corrugating medium specifications demand. Amazon and Walmart tier-one suppliers in Georgia and South Carolina concentrate procurement here for e-commerce box performance. This grade anchors volume economics through integrated pine plantation supply chains.
- Bleached Semi-Chemical Pulp:Partial lignin removal via oxygen or peroxide stages achieves brightness thresholds above 80% ISO for food-contact paperboard and molded fiber tray applications. REACH compliance through ECHA tightens chemical disclosure requirements for European imports of this grade. Molded fiber food service converters specify bleached NSSC for compostable clamshell formats replacing single-use plastics.
- High Yield Pulp:Pushes mechanical fiber liberation toward the 85% ceiling with minimized chemical loading for lightweight containerboard furnish.
- Low Yield Pulp:Accepts higher chemical intensity and fiber loss for specialty paper applications where surface uniformity outweighs yield economics.
Today's leader: Unbleached Semi-Chemical Pulp. Tomorrow's challenger: Bleached Semi-Chemical Pulp.
End Use Industry:
Packaging applications command the heaviest volume flows while specialty papers extract maximum margin per ton through technical specification premiums.
- Packaging:Corrugating medium consumes the majority of unbleached NSSC output, with stiffness-to-weight ratios determining machine-direction crush resistance for boxboard performance. Extended delignification pre-treatments are consolidating control over fiber variability in southeastern US mill complexes.
- Paperboard:Folding carton and liquid packaging board specifications require bleached semi-chemical furnish with controlled extractives content for food-contact compliance. India's expanding domestic containerboard capacity presents unmet demand for imported semi-chemical pulp as local recycled fiber contamination degrades furnish quality.
- Tissue:Limited penetration due to softness requirements that conflict with lignin-retained fiber stiffness; niche applications in industrial wipers persist.
- Specialty Papers:Electrical grade papers and filter media specify controlled porosity through precise yield chemistry, commanding the highest per-ton premiums in the category.
Packaging absorbs the volume. Specialty Papers capture the margin.
Technology:
Biomechanical configurations are displacing conventional NSSC sequences as sulfur chemical cost volatility and effluent constraints tighten.
- Biomechanical Processing:Enzyme-assisted fiber liberation reduces sodium sulfite loading by 30-50% while maintaining yield targets above 75%, attracting investment from mills seeking EPA Cluster Rule compliance. The Oulu bioproduct mill configuration demonstrates energy-efficient pulping performance that Nordic buyers qualify preferentially.
- Chemical Processing:Conventional NSSC with controlled sulfite liquor concentration remains the yield benchmark for high-volume corrugating medium production. Sulfuric acid and sodium sulfite price swings compress operating margins for mills dependent on spot chemical procurement.
- Mechanical Processing:Lowest chemical intensity but limited to applications accepting higher shive content and brightness penalties.
- Hybrid Processing:Sequential mechanical-chemical stages optimize energy input against yield retention for specific packaging paper grades.
Chemical Processing holds the installed base. Biomechanical Processing is climbing the fastest.
Distribution Channel:
Direct mill relationships are displacing fragmented spot purchasing as carbon accounting requirements reshape supplier qualification.
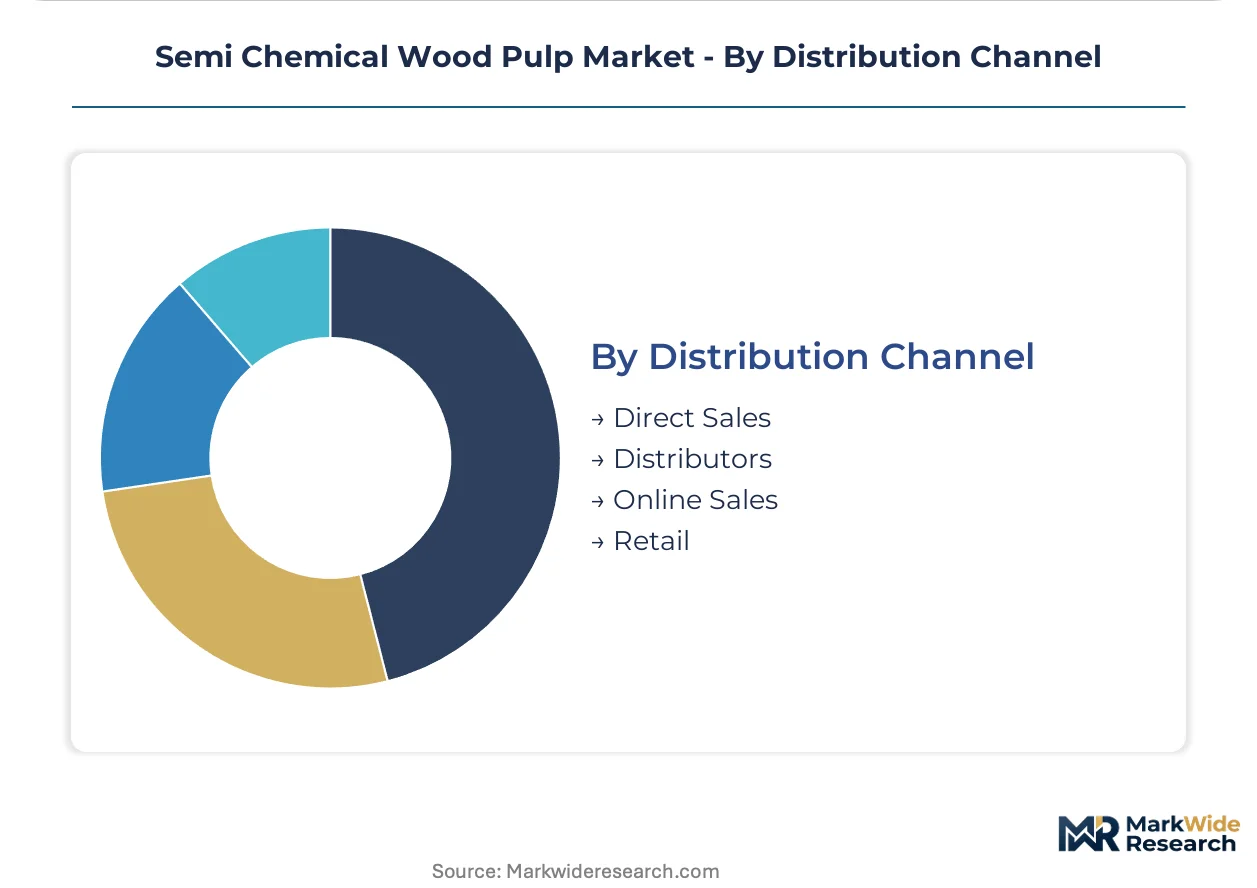
- Direct Sales:Multi-year offtake agreements tie volume commitments to verified Scope 3 carbon intensity disclosures, consolidating procurement among Amazon and Walmart tier-one corrugated suppliers. Integrated forestry certification data flows directly into buyer-mandated sustainability platforms.
- Distributors:Maintain inventory positions for mid-tier packaging converters lacking capital to commit to mill-direct contracts, though margin compression from chemical cost volatility limits their credit exposure.
- Online Sales:Emerging for specialty paper grade spot purchases where technical specifications are standardized and shipment sizes fall below mill-direct minimums.
- Retail:Negligible for industrial pulp; limited to artisan paper craft segments with trivial volume significance.
Direct Sales owns the strategic accounts. Distributors defend the fragmented middle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semi-chemical wood pulp production first scaled in the Nordic region during the mid-20th century, leveraging abundant softwood reserves and integrated hydroelectric power for energy-intensive pulping operations. The industry subsequently dispersed to North American pine belt regions and Asian manufacturing corridors.
United States
Amazon and Walmart sustainability mandates are concentrating procurement among southeastern mills with verified Scope 3 disclosures. The EPA enforces Cluster Rule effluent limitations that constrain sulfite chemistry choices in Georgia and South Carolina mill upgrades. Integrated packaging complexes around Savannah and Charleston are expanding capacity to serve e-commerce fulfillment center demand.
Finland
Nordic energy-efficient pulping configurations anchor European supply for multinational packaging buyer networks. The EU Green Deal's industrial emissions benchmarks push Oulu-area mills toward lower-carbon chemistries with integrated bioproduct recovery. Stora Enso Oyj leverages its northern mill network to compete on carbon intensity transparency.
Sweden
REACH compliance through ECHA tightens chemical input documentation for bleached grade exports to EU containerboard producers. UPM-Kymmene Corporation's integrated forestry certification data flows directly into buyer-mandated sustainability platforms. Mills in the Västerbotten region are qualifying alternative biocide treatments ahead of scheduled restriction reviews.
China
Domestic containerboard capacity expansion is driving unmet demand for imported semi-chemical pulp as local recycled fiber contamination degrades furnish quality. The MEE applies dual carbon goals to pulp capacity expansions in the Yangtze River Delta corridor. China Haisum Engineering Co., Ltd. anchors technology transfer for biomechanical processing configurations in Shandong Province.
India
Packaging board mills present emerging demand for semi-chemical pulp imports as e-commerce logistics infrastructure scales. BIS quality standards govern food-contact paperboard specifications for domestic and export markets. JK Paper Ltd. is expanding integrated pulp-paperboard complexes in Gujarat and Odisha to capture regional containerboard growth.
Semi Chemical Wood Pulp Market Competitive Landscape
Capital-heavy pulp producers compete with asset-light engineering and technology licensors for margin capture across the value chain. The market structure concentrates around integrated forestry-paper groups with captive wood supply and regional specialists serving spot packaging markets. Three archetypes dominate: Nordic multinationals with bioproduct mill configurations, North American integrated packaging suppliers with southeastern US pine belt access, and Asian engineering firms licensing process technology. Competitive dynamics center on multi-year offtake agreements tied to carbon intensity thresholds and capacity expansions in high-growth packaging corridors.
Among Nordic-based integrated producers, Stora Enso Oyj and UPM-Kymmene Corporation exemplify the energy-efficient bioproduct mill archetype with forestry certification integration. International Paper represents the North American integrated packaging supplier model with southeastern mill network concentration. These three companies anchor the competitive structure through differentiated approaches to Scope 3 disclosure and regional market access.
| Leading Market Players |
|---|
| JK Paper Ltd. |
| Ilim Group |
| China Haisum Engineering Co., Ltd. |
| Andritz Pulp and Paper |
| Arkhangelsk PPM |
| International Paper |
| WestRock Company |
| Stora Enso Oyj |
| UPM-Kymmene Corporation |
| Others |
Value Network & Pricing Analysis
Amazon and Walmart tier-one corrugated suppliers concentrate procurement decisions among mills with verified Scope 3 carbon disclosures, anchoring contract-based long-term offtake agreements as the dominant pricing model across North American packaging supply chains.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates bleached food-contact grades from unbleached corrugating medium and high-yield lightweight furnish. Price differentiation hinges on certification grade for EU Green Deal compliance and volume scale commitments from integrated packaging complexes. Cost compression in standard-tier unbleached NSSC is intensifying because sodium sulfite and sulfuric acid spot market volatility compresses operating margins. Food-contact paperboard buyers demonstrate the lowest price sensitivity due to regulatory qualification barriers, while independent corrugating converters exhibit acute sensitivity to chemical input cost pass-through.
Supply Chain Analysis
Dual-sourcing requirements from multinational packaging buyers mandate multi-supplier qualification across Finland, Sweden, and the southeastern United States to mitigate single-source vulnerability. Raw material dependencies draw from pine plantation fiber supply, sodium sulfite chemical inputs, and sulfuric acid for liquor chemistry balance. Supply chain risk centers on sulfur chemical price volatility and limited geographic diversification of bleached semi-chemical capacity. Distribution runs through direct mill relationships for strategic accounts, with distributors maintaining inventory positions for mid-tier converters lacking capital for mill-direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in semi-chemical wood pulp rests on biomechanical processing adoption that reduces sulfur chemical loading by 30-50% while preserving yield targets above 75%.
For Market Incumbents: Anchor carbon intensity transparency through integrated forestry certification data flowing directly into buyer-mandated Scope 3 disclosure platforms. Defend against biomechanical processing entrants by investing in closed-loop water systems that capture regulatory preference under tightened EPA Cluster Rule sulfite discharge limits. Prioritize capacity additions in Georgia and South Carolina pine belt regions where Amazon and Walmart fulfillment center demand concentrates. For New Entrants and Emerging Players: Begin with India's packaging board capacity expansion corridor, where domestic containerboard mills present unmet demand for imported semi-chemical pulp as local recycled fiber contamination degrades furnish quality. Target molded fiber food service applications in compostable tray and clamshell formats replacing single-use plastics, where bleached NSSC grades command premium positioning. Pursue technology licensing partnerships with established engineering firms to bypass process control engineering talent scarcity. For Investors and Strategic Acquirers: Integrated packaging suppliers with southeastern US pine belt access are the most active acquirer in this space, seeking captive pulp supply to secure volume commitments from Amazon and Walmart tier-one networks. Mills with demonstrated energy-per-ton performance transparency and verified carbon intensity disclosures represent the highest-probability acquisition targets. Watch for EPA Cluster Rule enforcement tightening as the inflection indicator that would accelerate capital deployment toward closed-loop chemistry recovery systems.| Strategic Initiative | Industry Significance |
|---|---|
| Biomechanical Processing Adoption | Enzyme-assisted fiber liberation reduces sodium sulfite loading while maintaining yield targets for EPA compliance. |
| Integrated Forestry Certification | Captive pine plantation supply chains in Georgia and South Carolina secure volume commitments from Amazon tier-one suppliers. |
| Closed-Loop Water Systems | Mills investing in liquor chemistry recovery capture regulatory preference under tightened EPA Cluster Rule discharge limits. |
| Multi-Year Offtake Agreements | Direct mill relationships displace fragmented spot purchasing as carbon accounting requirements reshape supplier qualification. |
| Molded Fiber Capacity Expansion | Bleached NSSC grades penetrate food service applications through compostable tray and clamshell formats. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with pulp mill operations directors, packaging converter procurement leads, chemical supply specialists, and sustainability compliance officers with secondary validation from customs trade data, EPA effluent discharge records, SEC filings from integrated paper groups, and EU ETS carbon intensity disclosures. Bottom-up capacity and production estimates triangulate against top-down demand modeling from corrugating medium and food-contact paperboard consumption patterns.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type (unbleached, bleached, high-yield, low-yield), end-use industry (packaging, paperboard, tissue, specialty papers), technology configuration (biomechanical, chemical, mechanical, hybrid), and distribution channel (direct sales, distributors, online sales). CAGRs derive from weighted average of historical capacity utilization trends and projected demand elasticity from e-commerce packaging growth. Industry-specific forecast inputs include pine plantation fiber supply expansion rates and sulfur chemical spot price volatility indices.
Several conditions sit outside the modeled scope, including unannounced mill closures, abrupt regulatory shifts in REACH chemical restriction schedules, and geopolitical disruptions to pulp trade flows. Deviation in Amazon or Walmart sustainability mandate enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Products Market
Paper Products
Graphic Paper Market
Paper Products
Europe Decor Paper Market
Paper Products
Tissue Paper Market
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
Metallized Paper Market
Paper Products
Sawn Wood Market
Paper Products
Hardwood Pulp Market
Paper Products
Liquid Paperboard Market
Paper Products
Saturated Kraft Paper Market
Paper Products
Recovered Paper Market
Paper Products
Unbleached Kraft Pulp Market
Paper Products
Global Copier Paper Market
Paper Products
Europe Paper Market
Paper Products
Aramid Paper Market
Paper Products
Paper and Board Technologies Market