
 Global Pulp and Paper Machinery Market | 2026-2036
Global Pulp and Paper Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pulp and Paper Machinery Market Outlook
Packaging converters are unwinding historical reliance on printing and writing paper producers as e-commerce corrugated demand accelerates. Valmet Corporation leverages its integrated automation-to-drying technology stack to anchor large-format board machine contracts across Northern Europe. Andritz AG sustains its R&D intensity in chemi-thermomechanical pulping systems that reduce specific energy consumption. Kadant Inc. competes through its dominance in doctoring and cleaning systems that extend machine runnability between planned shuts.
Pulp and paper machinery encompasses the engineered equipment systems that convert fibrous raw materials into continuous paper webs through stock preparation, forming, pressing, drying, and finishing operations, with modern machines operating at speeds exceeding 2,000 meters per minute and widths spanning 10 meters for packaging grades. Paper machines represent the most capital-intensive segment where margin pools concentrate in headbox and press section upgrades that improve dryness without additional drying energy. Automated technology is displacing conventional configurations as mills prioritize reduced labor exposure and predictive maintenance integration across dryer sections and rewinders.
The EPA enforces Maximum Achievable Control Technology standards for pulp mill air emissions that directly shape bleached pulp equipment specifications in the United States, while REACH and the EU Green Deal impose chemical restriction and carbon intensity thresholds on machinery supplied to European integrated mills. China's MEE enforces dual carbon goals that tighten energy efficiency benchmarks for new paper machine installations. Stakeholders must monitor how divergent regional compliance timelines reshape equipment standardization strategies and supplier certification burdens.
Market Dynamics
Automated paper machine installations are compressing the operational gap between integrated pulp mills and independent converters, as predictive maintenance integration and reduced labor exposure become non-negotiable specifications in new capital projects.
Growth Catalysts
- E-commerce corrugated demand:Packaging converters across Asia-Pacific are accelerating capital expenditure on large-format board machines to capture parcel volume growth from fulfillment networks.
- REACH chemical restrictions:EU Green Deal compliance requirements are reshaping equipment specifications toward lower-emission pulping technologies in bleached pulp production.
- Digital twin integration:Machine learning-enabled dryer section optimization is reducing specific energy consumption in tissue and specialty paper grades.
Market Restraints
- Stainless steel input volatility:Press section roll manufacturing faces margin compression from nickel and chromium price swings in metallurgical supply chains.
- Specialized component concentration:Precision headbox slice geometries rely on a limited supplier base concentrated in German and Japanese machining clusters.
- Extended EPA MACT compliance timelines:Bleached pulp equipment specifications in the United States face certification delays from overlapping federal and state air quality standards.
Strategic Opportunities
- India domestic capacity scaling:BIS-certified manufacturers are expanding to serve regional tissue mills with localized stock preparation and finishing systems.
- Retrofit automation bundles:Legacy machine rebuilds integrating IoT sensors and edge computing create aftermarket revenue pools in European integrated mills.
- Biomass pulping incentives:China's MEE dual carbon goals tighten energy efficiency benchmarks that favor chemi-thermomechanical system upgrades.
Industry Challenges
- Control systems integration:Legacy DCS architectures from 1990s-era paper machines resist seamless connectivity with modern predictive maintenance platforms.
- Specialized technician scarcity:Hydraulic press section calibration and headbox rheology adjustment require skills concentrated among retiring European and North American engineering cohorts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pulp and Paper Machinery Market |
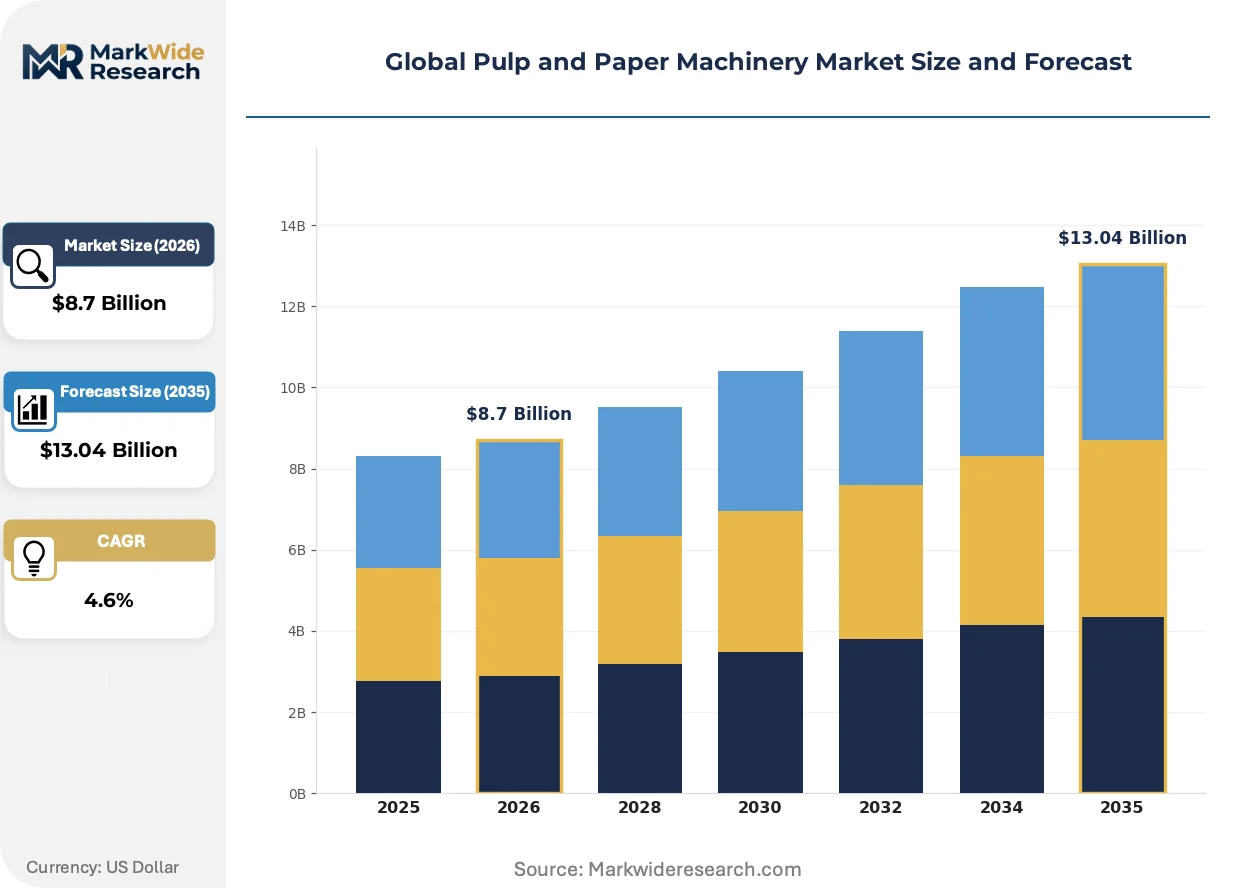
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Machine, Pulper, Dryer, Rewinder Material: Wood Pulp, Recycled Fiber, Chemical Pulp, Bleached Pulp End User: Packaging, Printing, Tissue, Specialty Papers Technology: Conventional, Digital, Automated, Hybrid |
| Companies Covered | Metso Outotec Corporation, Zhengzhou Leizhan Technology Paper Machinery Co. Ltd., Valmet Corporation, Bellmer GmbH, Toscotec S.p.A., Andritz AG, Kugler-Womako GmbH & Co. KG, Kadant Inc., Voith Paper Holding GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pulp and Paper Machinery Market Strategic Shifts
Sensor density and edge computing deployment are transforming machine runnability from scheduled maintenance cycles toward condition-based intervention models.
Machine vision defect detection is miniaturizing quality control infrastructure from standalone scanner booths to integrated web inspection arrays mounted directly on forming and press sections. Board producers in Northern Europe are adopting these compact systems at replacement cycles of 18-24 months. The technology is miniaturizing capital barriers for mid-scale packaging converters that previously outsourced quality verification.
REACH authorization requirements for pulp mill biocides and process chemicals are forcing equipment suppliers to validate compatibility with restricted substance lists before contract execution. Bleached pulp machinery destined for European integrated mills now carries extended certification timelines. Finnish and Swedish producers are responding by front-loading ECHA pre-submission dialogue into their vendor qualification processes.
Converter procurement teams are unbundling after-sales service contracts from initial equipment purchases, negotiating predictive maintenance subscriptions separately from machine delivery. This behavior disrupts traditional bundled pricing in the dryer section and rewinder categories. The shift is most visible among Asia-Pacific packaging converters with centralized procurement functions in Singapore and Shanghai.
Global Pulp and Paper Machinery Market Segmentation
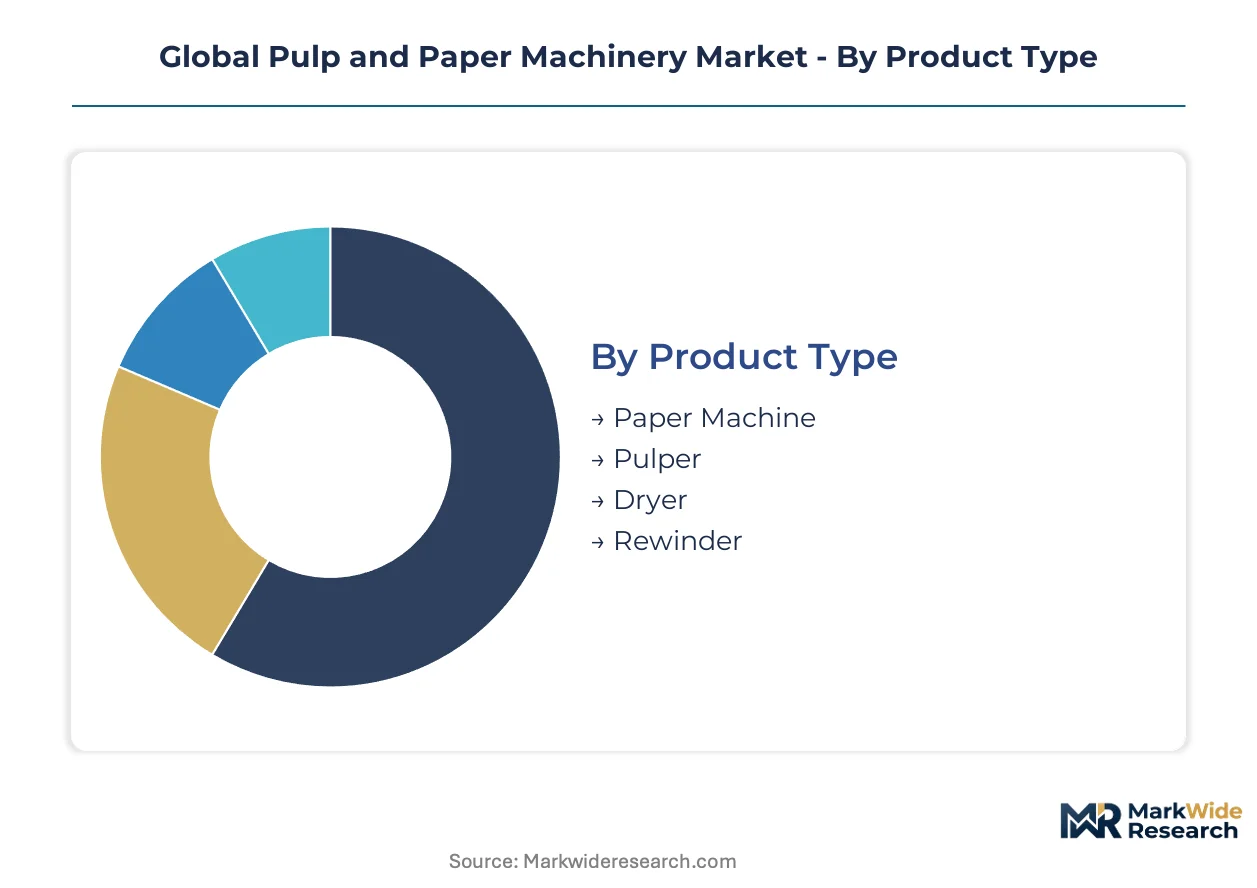
Pulp and paper machinery segmentation reveals divergent capital deployment patterns across integrated mills and independent converters. Equipment specifications vary sharply by fiber source, end-use quality requirements, and regional labor cost structures.
Product Type:
Paper machines dominate export-led procurement from Finnish and German engineering clusters, while pulpers and rewinders see stronger domestic manufacturing in India and China.
- Paper Machine:These capital-intensive systems integrate headbox, forming, pressing, and drying sections into continuous web production lines operating above 2,000 meters per minute. Demand concentrates in Asia-Pacific packaging converters seeking large-format board machines for e-commerce corrugated expansion.
- Pulper:Hydrapulper and drum pulper configurations handle virgin and recycled fiber slushing with specific energy targets. European integrated mills prioritize chemi-thermomechanical pulping upgrades to meet EU Green Deal carbon intensity thresholds.
- Dryer:Multi-cylinder and Yankee dryer sections remove moisture through steam-heated contact drying. Indian tissue mills drive regional demand for compact, high-efficiency configurations.
- Rewinder:Slitter-rewinder systems convert parent rolls into finished product formats. Mid-scale converters in Southeast Asia favor automated tension control models to reduce labor exposure.
Paper Machine holds the largest share; momentum sits with Pulper as fiber preparation efficiency gains priority in energy-constrained mills.
Material:
Cost tier differentiation separates high-specification bleached pulp machinery from standardized recycled fiber equipment serving price-sensitive converters.
- Wood Pulp:Softwood and hardwood kraft pulping systems handle long-fiber strength requirements for packaging and printing grades. Scandinavian producers anchor global supply of softwood pulp machinery with integrated chemical recovery.
- Recycled Fiber:Deinking and dispersion equipment processes post-consumer wastepaper into pulp suitable for newsprint and containerboard. Chinese mills under MEE dual carbon goals drive fastest capacity expansion in this segment.
- Chemical Pulp:Sulfate and sulfite pulping systems achieve high purity for specialty paper applications. North American mills face EPA MACT compliance timelines that extend equipment certification cycles.
- Bleached Pulp:ECF and TCF bleaching sequences require chlorine dioxide or oxygen-based delignification stages. REACH authorization requirements for biocides reshape European equipment specifications toward closed-loop chemical systems.
Wood Pulp machinery retains dominant installed base; Recycled Fiber equipment is climbing the fastest as circular economy mandates tighten across jurisdictions.
End User:
Application intensity varies by sector, with packaging converters demanding highest machine speeds and tissue producers prioritizing energy efficiency in drying sections.
- Packaging:Corrugators and board machines produce linerboard, medium, and folding carton grades. Asia-Pacific fulfillment network expansion drives capital concentration in this segment.
- Printing:Coated and uncoated woodfree paper machines face declining demand in North American and European markets as digital media displaces publication papers.
- Tissue:Creping and through-air drying systems manufacture bathroom tissue, towels, and napkins. Indian regional mills under BIS certification requirements scale domestic machinery sourcing.
- Specialty Papers:Filter, label, and release liner grades require customized forming and coating configurations. Japanese producers maintain technology leadership in precision headbox design for these applications.
Packaging commands the largest capital allocation; Specialty Papers machinery is gaining share fastest as technical grades command premium pricing.
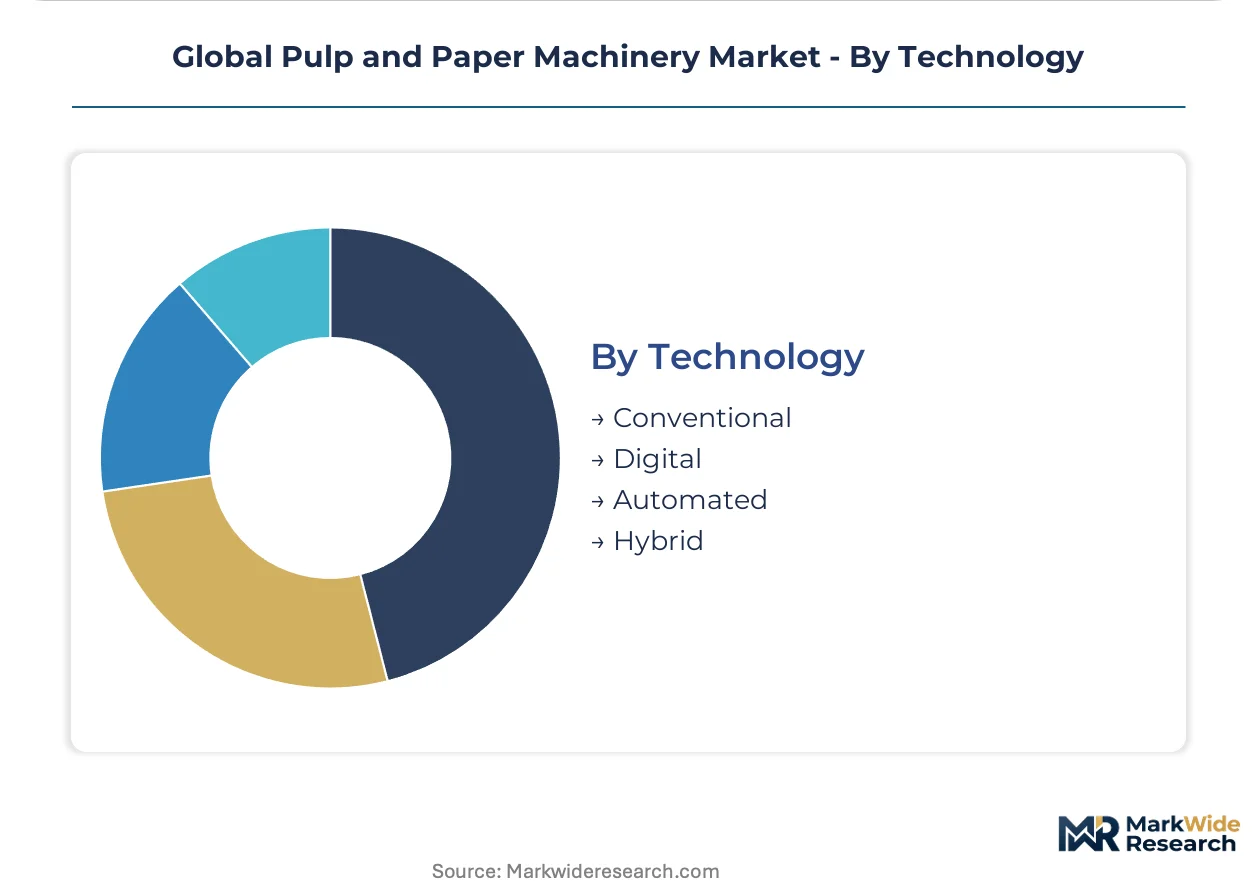
Technology:
Customer type segmentation separates integrated mills with in-house engineering capabilities from converters dependent on turnkey automation packages.
- Conventional:Mechanical control systems and fixed-speed drives characterize legacy installations predating 2010. European mills face control systems integration challenges when retrofitting predictive maintenance platforms.
- Digital:Machine vision inspection and model-based process control enable real-time quality adjustment. Board producers in Northern Europe adopt these systems at 18-24 month replacement cycles.
- Automated:Integrated DCS platforms with IoT sensor networks enable condition-based maintenance. Asia-Pacific packaging converters with centralized procurement functions unbundle predictive maintenance subscriptions from equipment purchases.
- Hybrid:Combinations of mechanical and digital subsystems allow phased upgrade paths for capital-constrained mills. This configuration dominates rebuild projects in North American integrated facilities.
Conventional technology retains largest installed base; Automated systems are expanding most quickly as labor cost and safety pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Gothenburg's Ro-Ro terminals anchor Scandinavian pulp machinery exports to Asia, while the Rhine-Main-Danube waterway network enables German engineering clusters to serve Central European paper mills with heavy-lift cargo capacity.
United States
EPA MACT enforcement for bleached pulp air emissions extends equipment certification timelines as mills retrofit sulfur dioxide scrubbers and particulate controls. Integrated producers in the Pacific Northwest face overlapping state-level carbon pricing mechanisms in California and Washington. Georgia-Pacific and International Paper operate modernization programs across the Southeast, converting legacy newsprint machines to packaging-grade board production.
Germany
REACH authorization requirements for pulp mill biocides reshape vendor qualification processes toward closed-loop chemical recovery systems. ECHA pre-submission dialogue now front-loads equipment procurement cycles by 12-18 months. Voith Paper and Bellmer anchor engineering concentration in the Baden-Württemberg and North Rhine-Westphalia precision machining belt.
China
MEE dual carbon goals tighten energy efficiency benchmarks for new paper machine installations above 5,000 tons per day capacity. Yangtze River Delta mills under Zhejiang and Jiangsu provincial environmental quotas accelerate chemi-thermomechanical pulping upgrades. Shandong Peninsula containerboard producers source stock preparation systems from domestic fabricators scaling toward BIS-equivalent certification standards.
India
BIS certification requirements for domestic tissue machinery manufacturers unlock import substitution opportunities as regional mills expand beyond 100 tons per day capacity. Tamil Nadu and Maharashtra state industrial policies offer capital subsidies for automated rewinder installations. Ahmedabad and Pune engineering clusters scale pulper and dryer fabrication for specialty paper grades serving pharmaceutical packaging demand.
Finland
EU Green Deal carbon intensity thresholds drive Valmet and Andritz R&D concentration in lower-emission drying technologies. Kotka-Hamina port infrastructure supports heavy equipment export logistics for Asia-Pacific board machine contracts. Ostrobothnian integrated mills pilot digital twin integration across Yankee dryer sections for tissue energy optimization.
Global Pulp and Paper Machinery Market Competitive Environment
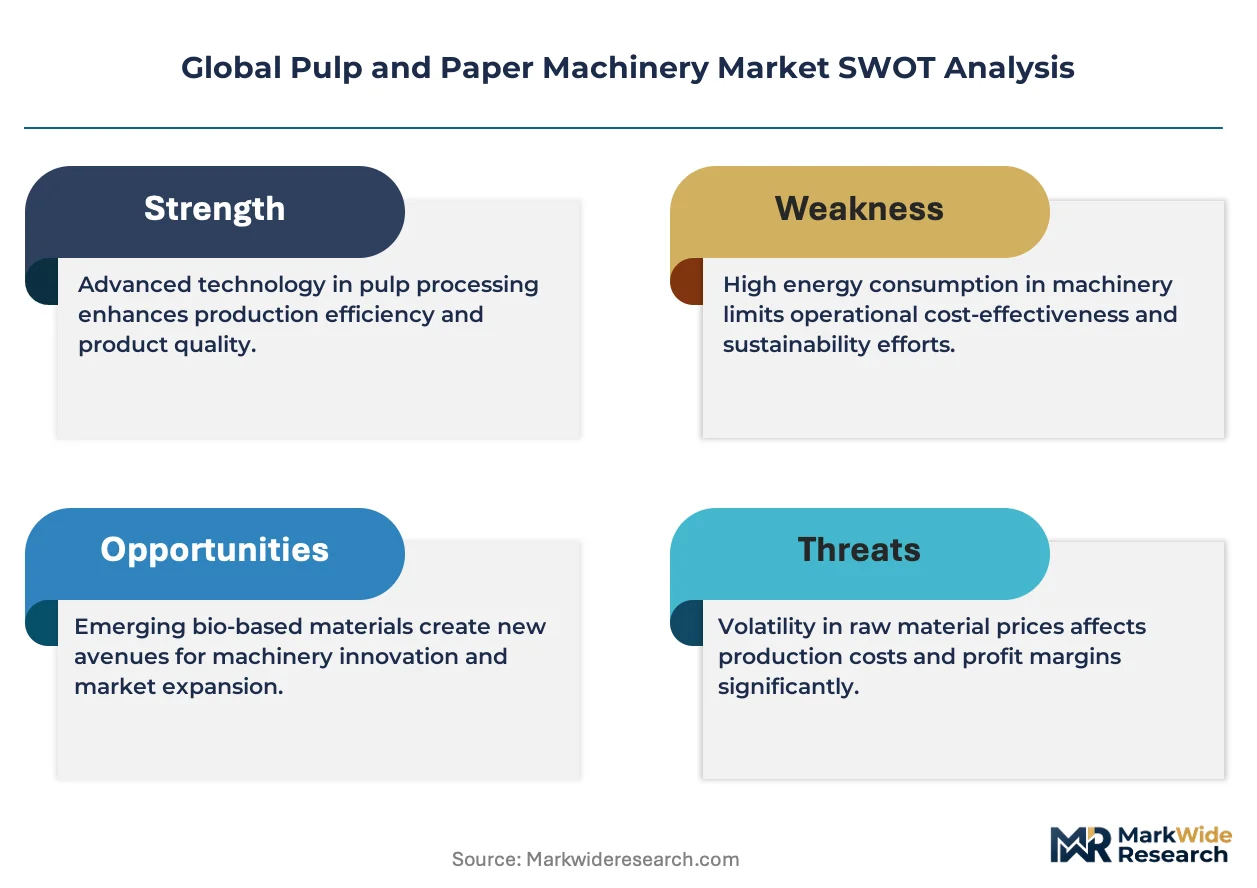
Listed leaders compete with private specialists across automation-to-drying technology stacks, creating a tiered structure where scale-driven engineering conglomerates anchor premium contracts while regional fabricators capture mid-market rebuild opportunities. Three archetypes dominate: integrated automation providers bundling DCS platforms with mechanical systems; component specialists concentrating in doctoring, cleaning, or headbox subsystems; and emerging Asian fabricators scaling toward European certification equivalence. Competitive intensity concentrates in predictive maintenance subscription unbundling and retrofit IoT sensor integration for legacy machine rebuilds.
Among Nordic-listed engineering groups, Valmet Corporation and Metso Outotec Corporation occupy positions spanning full-line paper machine integration to mineral processing equipment diversification. Andritz AG represents the Austrian-German precision machining archetype with chemi-thermomechanical pulping system concentration. Kadant Inc. anchors the North American component specialist tier. Zhengzhou Leizhan Technology Paper Machinery Co. Ltd. exemplifies Chinese fabricators scaling stock preparation and screening equipment toward export market certification alignment.
| Leading Market Players |
|---|
| Metso Outotec Corporation |
| Zhengzhou Leizhan Technology Paper Machinery Co. Ltd. |
| Valmet Corporation |
| Bellmer GmbH |
| Toscotec S.p.A. |
| Andritz AG |
| Kugler-Womako GmbH & Co. KG |
| Kadant Inc. |
| Voith Paper Holding GmbH & Co. KG |
| Others |
Value Chain & Pricing Dynamics
Recycled fiber pulping equipment substituting for virgin kraft machinery is redrawing procurement geography toward Chinese and Indian fabricators while compressing margin structures in European premium tiers. This substitution dynamic simultaneously concentrates supply-side bargaining power among nickel-chromium roll suppliers and fragments pricing authority across three distinct equipment tiers.
Pricing Analysis
Volume-discount tiering structures separate Asia-Pacific packaging converters negotiating multi-machine contracts from European integrated mills purchasing single-unit specialty rebuilds. Pricing stratifies across premium, standard, and economy tiers defined by automation density and REACH certification status. Cost compression in the standard tier is intensifying because Shandong and Jiangsu fabricators are scaling toward BIS-equivalent standards. Mid-scale Indian tissue mills exhibit highest price sensitivity; Nordic board producers demonstrate lowest sensitivity due to bundled predictive maintenance subscriptions.
Supply Chain Analysis
Inbound logistics costs from Port of Gothenburg congestion and Asia-Europe container tightness are elevating landed costs for Finnish and German precision-machined headbox components. Manufacturing concentrates in Germany, Finland, and China for complete paper machines; Japan and South Korea anchor precision control system supply. The supply chain draws from stainless steel metallurgical inputs, ceramic roll coverings, and specialized hydraulic actuators. Single-source vulnerability concentrates in German-Japanese machining clusters for headbox slice geometries. Distribution runs through engineering-procurement-construction contractors for integrated mills and direct OEM relationships for independent converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: EPA MACT, REACH authorization, and BIS certification timelines create structural barriers that extend incumbent sales cycles and protect installed-base aftermarket revenue.
For Market Incumbents: Consolidate aftermarket service revenue by unbundling predictive maintenance subscriptions from initial equipment sales, mirroring Asia-Pacific converter procurement patterns. Deepen backward integration into nickel-chromium roll casting to offset metallurgical price volatility threatening press section margins. Prioritize ECHA pre-submission dialogue investments to extend certification timelines that deter emerging Asian competitors. For New Entrants and Emerging Players: Anchor in India's BIS-certified domestic manufacturing segment where regional tissue mills exceed 100 tons per day capacity and import substitution incentives apply. Target mid-scale Southeast Asian packaging converters seeking automated rewinder configurations with reduced labor exposure. Pursue joint-venture structures with Ahmedabad engineering clusters to access pharmaceutical packaging specialty paper demand. For Investors and Strategic Acquirers: EU Green Deal carbon intensity thresholds reshaping bleached pulp equipment specifications reshape the acquisition landscape toward chemi-thermomechanical pulping system specialists. Long-term viability centers on energy efficiency technology ownership rather than mechanical fabrication scale. Target acquisition archetype: component specialists with doctoring, cleaning, or drying subsystem dominance and embedded predictive maintenance IP. Monitor MEE dual carbon goal enforcement tightness as inflection signal for Chinese domestic capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Roll Manufacturing | Captive stainless steel casting capacity insulates margins from nickel price volatility. |
| Predictive Maintenance Subscription Unbundling | Asia-Pacific converter procurement patterns validate recurring revenue model separation. |
| REACH Pre-Certification Investment | ECHA dialogue front-loading extends competitive moats through regulatory entrenchment. |
| Digital Twin Platform Development | Machine learning-enabled dryer optimization commands premium in tissue energy contracts. |
| Indian Domestic Fabrication Scaling | BIS certification alignment unlocks regional tissue mill import substitution demand. |
Study Parameters
Operator-level perspectives from paper mill maintenance directors, OEM procurement teams, aftermarket service heads, and EPC contractors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through customs trade data, engineering association capacity surveys, SEC equipment supplier filings, and MEE environmental compliance disclosures. Bottom-up equipment shipment tallies triangulated against top-down pulp and paper capacity expansion announcements.
Sensitivity analysis tested forecast robustness across stainless steel price scenarios, REACH authorization timeline variations, and MEE enforcement intensity assumptions. Segmentation modeling spanned product type, fiber source, automation technology tier, end-use application intensity, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, greenfield capacity announcements, and retrofit automation penetration curves. Energy efficiency benchmark tightening and biocide restriction lists served as industry-specific demand shifters.
Underlying assumptions cover EPA MACT compliance timeline stability, EU Green Deal carbon threshold trajectory continuity, and BIS certification equivalence recognition, with deviation risk concentrated in nickel-chromium metallurgical supply disruptions and container shipping rate volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Europe Paper Market
Paper Products
Medical Grade Paper Market
Paper Products
Printing Paper Market
Paper Products
Wood-Based Sheet Materials Market
Paper Products
Global Electrical Insulation Paper Market
Paper Products
Metallized Paper Market
Paper Products
Pharma Grade Paper Market
Paper Products
Saturated Kraft Paper Market
Paper Products
Recovered Paper Market
Paper Products
Graphic Paper Market
Paper Products
Middle East and Africa Decor Paper Market
Paper Products
Pulp Market
Paper Products
Digital Printing Paper Market
Paper Products
North America Decor Paper Market
Paper Products
Inlay Paper Market
Paper Products
Paper Core Market