
 Asia-Pacific Thermal Paper Market | 2026-2036
Asia-Pacific Thermal Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Thermal Paper Market Insights
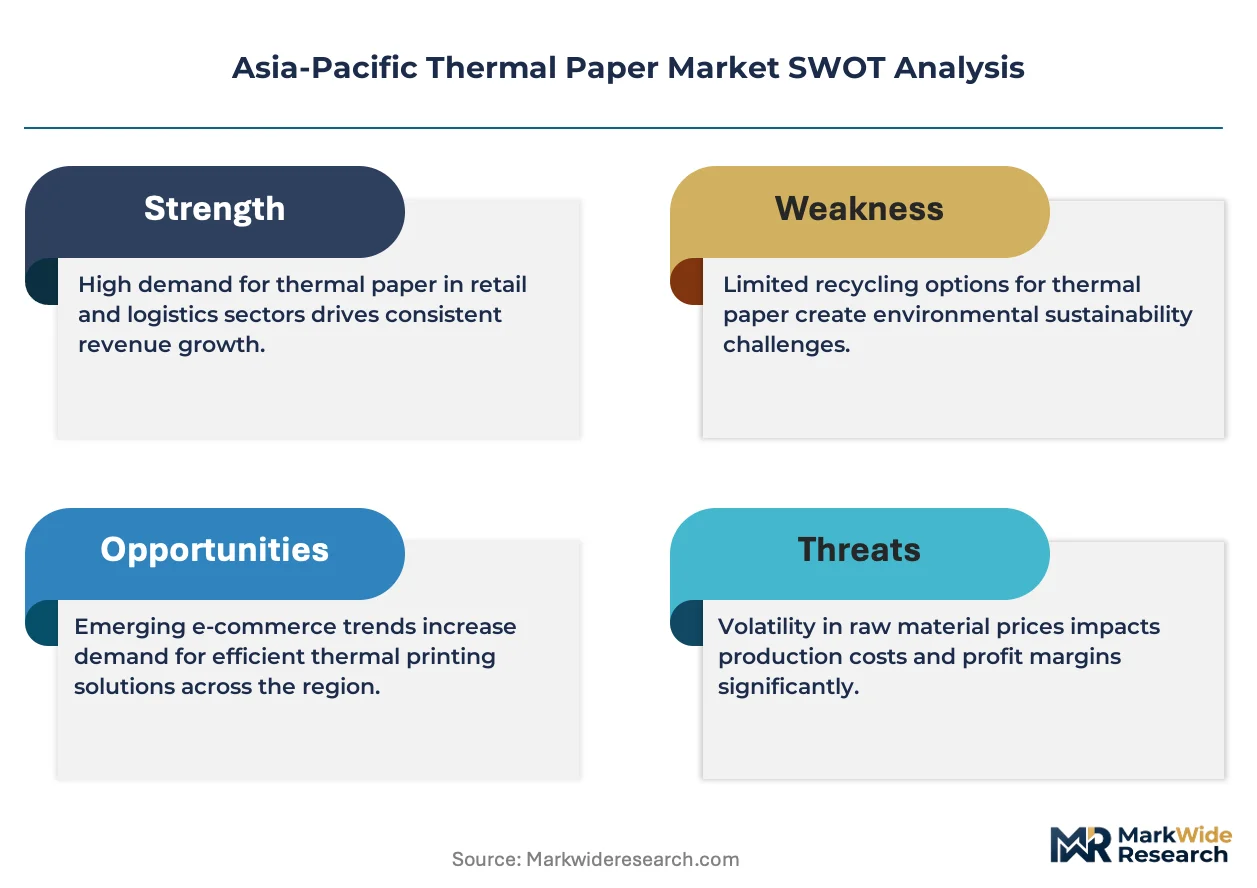
Specialty paper distribution through bonded warehouse networks is rewriting procurement economics across Asia-Pacific. Mitsubishi HiTec Paper leverages its coating technology leadership to command premium positioning in Japan's pharmaceutical labeling segment. Henan Province JiangHe Paper Co., Ltd. anchors volume supply for domestic Chinese retail chains through integrated pulp-to-coating operations. Oji Holdings Corporation extends its reach across Southeast Asia via converted product partnerships with local ticket printers.
Thermal paper comprises a base stock coated with heat-sensitive layers containing leuco dyes and developers that darken on thermal print head contact without ink. The substrate typically spans 45-80 gsm weights, with topcoats protecting against environmental fading and abrasion in logistics applications. Direct thermal formulations dominate receipt and ticket volumes where short archive life suffices, while thermal transfer substrates capture label demand requiring solvent resistance and extended readability. Specialty grades incorporating RFID inlays represent the fastest-expanding margin pool, though barcode-compatible coatings still occupy the broadest application footprint across retail and transportation end users.
China's SAMR enforces evolving GB standards restricting bisphenol-A content in thermal coatings, forcing reformulation investments across domestic mills. Japan's METI and South Korea's MFDS both maintain chemical substance reporting frameworks that affect coating import approvals and product registration timelines. India's BIS certification requirements for paper products create incremental compliance layers for suppliers targeting organized retail modernization. Stakeholders must monitor how divergent national chemical regulations reshape regional supply configurations and determine where centralized coating production retains cost advantage against localized compounding.
Market Dynamics
China's GB standards for bisphenol-free thermal coatings are forcing wholesale reformulation across Asia-Pacific mills, while Japan's METI energy-efficiency labeling rules redirect capital toward low-temperature coating technologies. These dual regulatory vectors are compressing legacy supply configurations and accelerating specialty grade migration.
Growth Catalysts
- Convenience store POS expansion:Southeast Asian retail chains are rolling out standardized receipt systems across franchise networks, pulling thermal paper volumes into bonded warehouse distribution channels.
- Japan's pharmaceutical labeling mandates:METI and PMDA traceability requirements for drug packaging are expanding demand for archive-grade thermal substrates with extended readability.
- RFID-thermal hybrid substrates:Logistics operators in eastern China are adopting combined barcode-RFID ticket formats for warehouse automation, creating premium coating opportunities.
Market Restraints
- Leuco dye supply concentration:Three Japanese chemical houses control fluoran dye precursor supply, exposing mills to input cost volatility and allocation risk during demand spikes.
- China's SAMR bisphenol-A restrictions:Reformulation timelines for GB-compliant developers are extending product registration cycles by 8-14 months for domestic suppliers.
- Digital receipt substitution:South Korean and Australian retailers are deploying QR-code mobile receipts for low-value transactions, compressing thermal paper attach rates at point-of-sale.
Strategic Opportunities
- India's organized retail modernization:BIS certification requirements for paper products are creating tiered supply windows for mills with pre-certified coating lines.
- Thermal transfer label convergence:Food and beverage exporters are migrating from direct thermal to thermal transfer substrates for cold-chain compliance, expanding solvent-resistant coating demand.
- Indonesia's e-commerce logistics buildout:Last-mile delivery networks are standardizing thermal waybill formats, opening volume contracts for regional converters with local slitting capacity.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise for bisphenol-free developer systems is concentrated among retiring specialists at Japanese and German chemical firms.
- Capex intensity for topcoat lines:Micro-encapsulation equipment for fade-resistant archival grades requires 24-36 month payback periods at current specialty pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Thermal Paper Market |
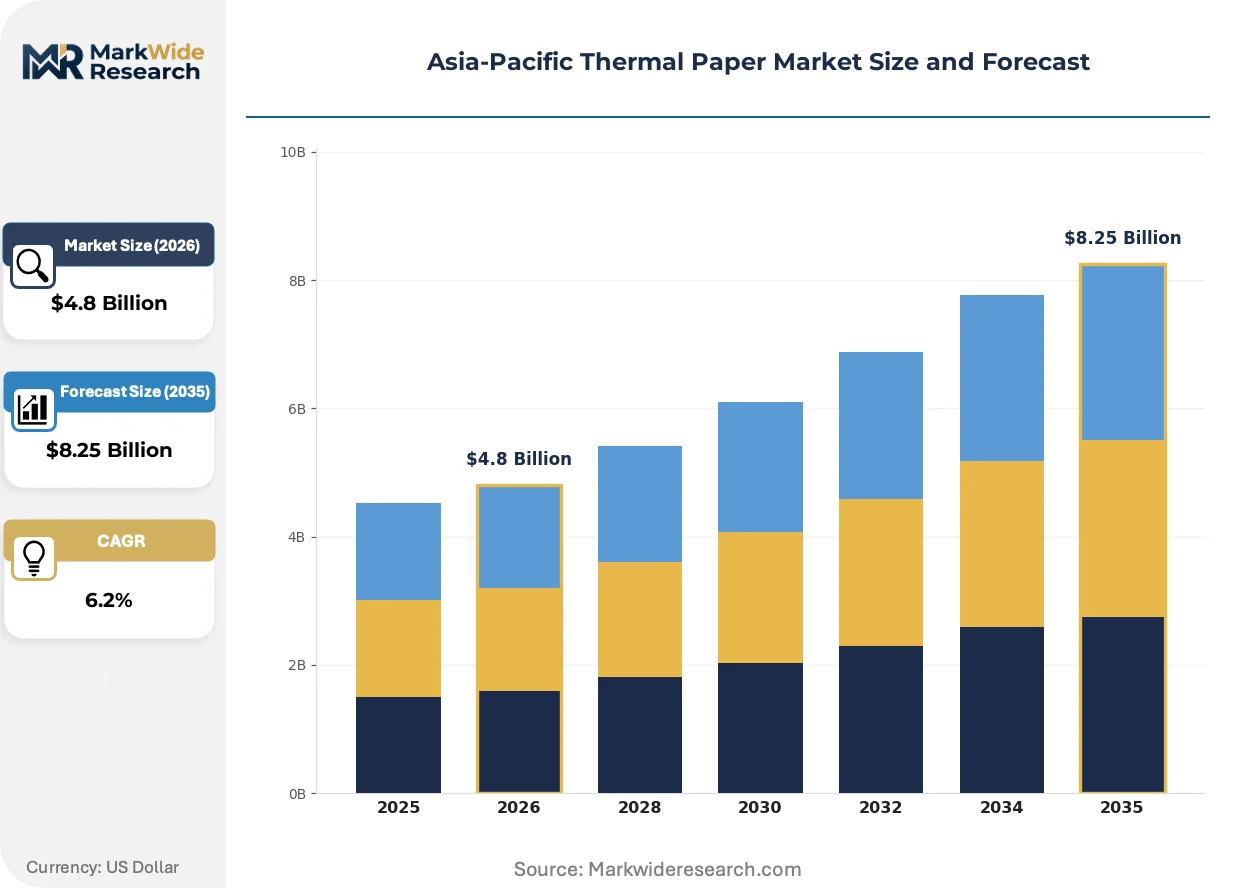
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Thermal, Thermal Transfer, Multi-layer, Specialty End User: Retail, Healthcare, Transportation, Entertainment Application: Labels, Receipts, Tickets, Packaging Technology: Heat-sensitive, Inkjet Compatible, Barcode Printing, RFID |
| Companies Covered | Hansol Paper, Panda Paper Roll, Mitsubishi HiTec Paper, Henan Province JiangHe Paper Co., Ltd., Shandong Chenming Paper Holdings Ltd, Oji Holdings Corporation, Nippon Paper Industries, Xiandai Paper Production, Ricoh Company Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Thermal Paper Market Trends and Innovations
Digital receipt infrastructure is virtualizing traditional thermal paper demand patterns across Asia-Pacific retail, while regulatory chemistry mandates and logistics automation are rewiring coating technology roadmaps and procurement specifications simultaneously.
Leuco dye micro-encapsulation is virtualizing the thermal paper value chain by embedding developer chemistry directly into substrate fibers rather than surface coatings. Pharmaceutical label converters in Japan are adopting these substrates for 15-25 year archive requirements. This architecture is virtualizing the traditional coating mill role and compressing margins for standalone chemical applicators.
China's SAMR enforcement of evolving GB standards is eliminating bisphenol-A developers from domestic supply chains by 2027. Mills are investing in phenol-free formulations using alternative color developers. Domestic retail chains are responding by consolidating procurement around pre-certified suppliers with established SAMR registration dossiers.
Buyer consolidation among Southeast Asian convenience store operators is compressing supplier negotiation cycles from annual to quarterly frameworks. Regional distributors with bonded warehouse networks are displacing direct mill relationships. This pattern is most visible in Thailand and Vietnam where 7-Eleven and FamilyMart franchise systems are centralizing label and receipt procurement.
Asia-Pacific Thermal Paper Market Segmentation
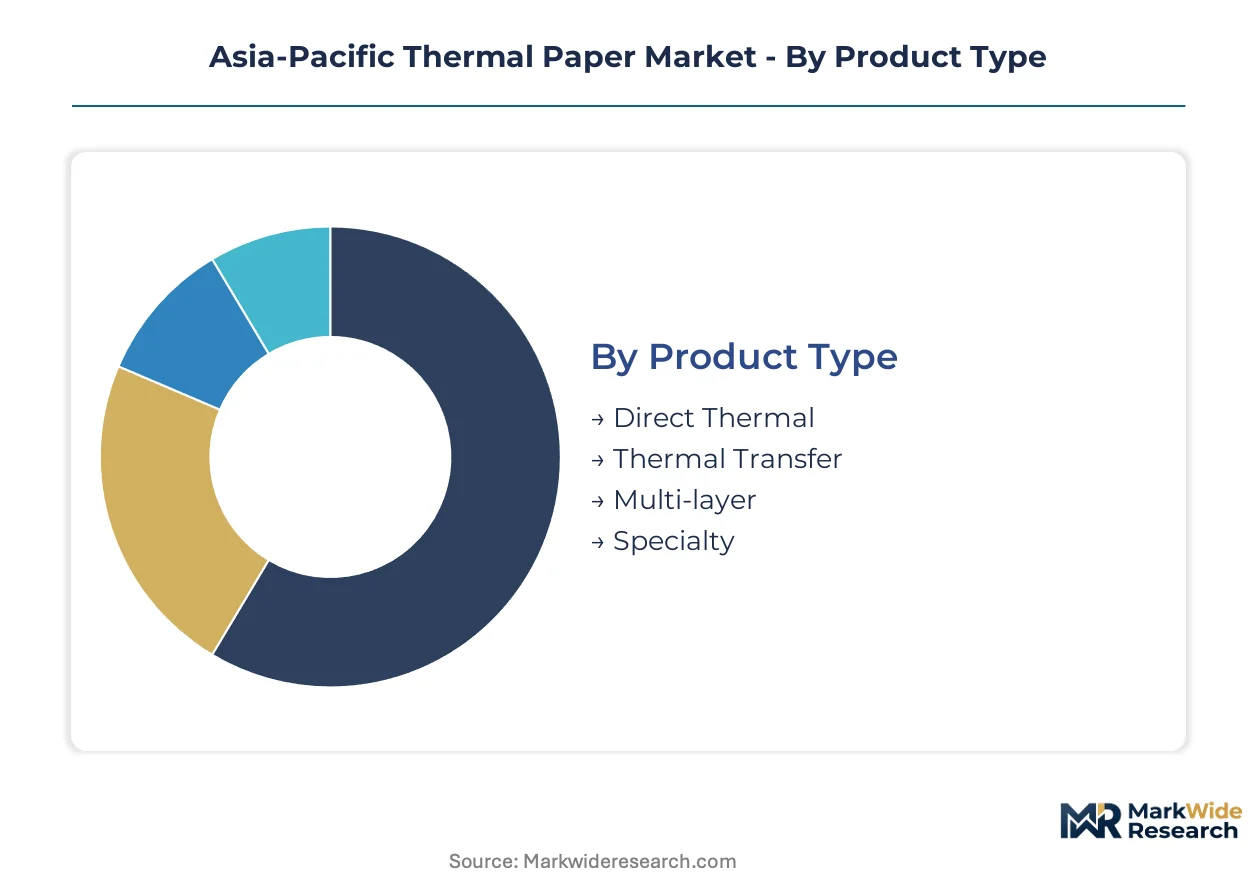
Thermal paper segmentation in Asia-Pacific tracks divergent coating chemistries, print technologies, and regulatory compliance tiers that reshape procurement specifications across convenience retail, pharmaceutical labeling, and logistics automation. Understanding these segment boundaries clarifies where formulation investments concentrate and which substrate specifications command premium positioning.
Product Type:
Mature direct thermal grades anchor volume throughput, while emerging multi-layer and specialty formulations capture reformulation premiums driven by bisphenol-free mandates and extended archive requirements.
- Direct Thermal:Single-layer substrates with leuco dye and developer coatings that darken on thermal print head contact without ribbon or ink. Convenience store chains across Thailand and Vietnam pull these volumes through bonded warehouse networks for standardized POS receipt systems.
- Thermal Transfer:Coated substrates requiring ribbon-based imaging for solvent resistance and extended readability. Food and beverage exporters in eastern China are migrating to these grades for cold-chain compliance labels requiring 5-7 year archive life.
- Multi-layer:Composite constructions combining thermal imaging layers with protective topcoats or adhesive backings. Logistics operators adopt these for warehouse waybills needing simultaneous barcode scannability and environmental durability.
- Specialty:Custom formulations incorporating RFID inlays, micro-encapsulated dyes, or pharmaceutical-grade purity. Japanese pharmaceutical label converters specify these for METI and PMDA traceability mandates requiring 15-25 year readability.
Direct Thermal retains volume leadership; Specialty holds the steepest expansion curve.
End User:
Cost tier stratification separates high-specification regulated segments from price-sensitive standardized procurement.
- Retail:Franchise convenience store operators across Southeast Asia centralize receipt and label procurement through quarterly negotiation frameworks. 7-Eleven and FamilyMart systems in Thailand and Vietnam are displacing direct mill relationships with regional distributor networks.
- Healthcare:Pharmaceutical packaging and patient identification wristbands requiring archive-grade substrates. Japan's PMDA traceability rules and South Korea's MFDS reporting frameworks extend registration timelines for coating import approvals.
- Transportation:Airlines, rail operators, and logistics providers standardizing thermal ticket and waybill formats. Indonesia's e-commerce logistics buildout is opening volume contracts for regional converters with local slitting capacity.
- Entertainment:Event ticketing and gaming receipts where short archive life suffices. Australia's retail sector is deploying QR-code mobile receipts for low-value transactions, compressing thermal attach rates in this segment.
Retail commands the broadest procurement scale; Healthcare generates the highest per-unit margins.
Application:
Volume concentration clusters in high-frequency transactional formats, while margin expansion concentrates in compliance-driven labeling.
- Labels:Adhesive-backed substrates for product identification, shipping, and inventory management. Thermal transfer grades are gaining share fastest among food exporters requiring solvent resistance and extended readability.
- Receipts:Point-of-sale rolls for retail transaction documentation. China's SAMR bisphenol-A restrictions are forcing reformulation investments and consolidating procurement around pre-certified domestic suppliers.
- Tickets:Transport and event admission formats requiring rapid imaging and tear resistance. Logistics operators in eastern China are adopting combined barcode-RFID ticket formats for warehouse automation.
- Packaging:Flexible packaging applications and protective wrapping with thermal-printable surfaces. This application remains nascent in Asia-Pacific relative to receipt and label volumes.
Receipts retain volume leadership; Labels hold the steepest expansion curve.
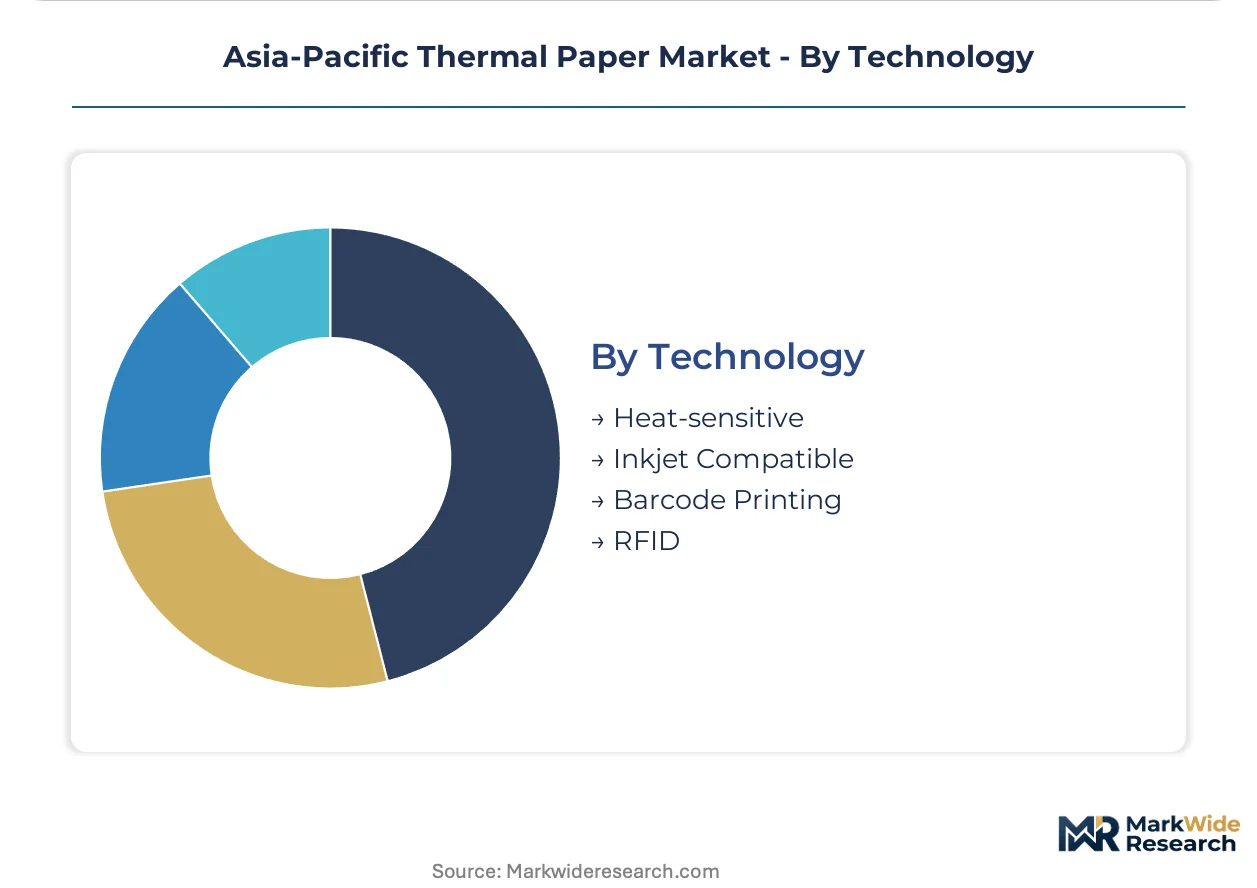
Technology:
Customer type differentiation separates legacy heat-sensitive installations from integrated automation requiring multi-modal data capture.
- Heat-sensitive:Conventional leuco dye chemistry responding to thermal print head temperature. This technology dominates convenience store POS installations across Southeast Asia where short archive life meets cost minimization priorities.
- Inkjet Compatible:Surface-treated substrates accepting aqueous or solvent-based inkjet imaging. These grades serve hybrid print environments in logistics and healthcare where thermal and inkjet systems coexist.
- Barcode Printing:Optimized coatings ensuring scannability across 1D and 2D symbologies. Last-mile delivery networks in Indonesia are standardizing thermal waybill formats with barcode-compatible specifications.
- RFID:Hybrid substrates embedding radio-frequency identification inlays with thermal-printable surfaces. RFID-thermal combinations represent the fastest-expanding margin pool in logistics automation, though deployment remains concentrated among large operators in eastern China and Japan.
Heat-sensitive retains volume leadership; RFID holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing belt commands pricing leverage over Southeast Asian converters, while Japanese suppliers extract premiums through pharmaceutical-grade certification. This asymmetry shapes procurement flows across the Asia-Pacific thermal paper market.
China
Henan and Shandong provinces anchor domestic volume supply for retail chains through integrated pulp-to-coating operations. SAMR enforcement of evolving GB standards is eliminating bisphenol-A developers from supply chains by 2027, consolidating procurement around pre-certified mills. The Yangtze River Delta cluster near Shanghai concentrates coating chemical suppliers and thermal paper mills in tight geographic proximity.
Japan
Pharmaceutical labeling mandates from METI and PMDA are expanding demand for archive-grade substrates with 15-25 year readability requirements. Japanese chemical houses control fluoran dye precursor supply, exposing regional mills to input cost volatility. The Kanto region around Tokyo hosts specialty coating operations serving domestic pharmaceutical and logistics end users.
South Korea
Digital receipt substitution is compressing thermal paper attach rates as retailers deploy QR-code mobile systems for low-value transactions. MFDS maintains chemical substance reporting frameworks that affect coating import approvals and product registration timelines. Seoul-based converters are repositioning toward thermal transfer grades for export-oriented food and beverage labeling.
Thailand
7-Eleven and FamilyMart franchise systems are centralizing receipt and label procurement through quarterly negotiation frameworks. Bonded warehouse networks are displacing direct mill relationships across convenience store distribution channels. Bangkok-based regional distributors are capturing procurement consolidation from standardized POS rollout across Southeast Asian franchise networks.
Indonesia
E-commerce logistics buildout is standardizing thermal waybill formats across last-mile delivery networks. BIS certification requirements for paper products create incremental compliance layers for suppliers targeting organized retail modernization. Java-based converters with local slitting capacity are opening volume contracts for regional logistics automation.
Asia-Pacific Thermal Paper Market Competitive Landscape
Integrated chemical-paper conglomerates and standalone coating specialists split the market along vertical control lines. Japanese and South Korean groups command premium positioning through dye chemistry ownership, while Chinese mills compete on scale and domestic supply chain density. Three archetypes dominate: captive chemical producers, integrated pulp-coating operators, and regional conversion specialists. Capacity expansion and strategic partnerships with local ticket printers represent the dominant competitive moves across Southeast Asia.
Within the integrated pulp-coating tier, Henan Province JiangHe Paper Co., Ltd. and Shandong Chenming Paper Holdings Ltd exemplify Chinese scale-driven positioning through captive supply chain control. Mitsubishi HiTec Paper occupies a premium-tier position representing Japanese chemical-technology leadership in pharmaceutical-grade applications. Oji Holdings Corporation anchors the regional conversion specialist archetype, with its geographic footprint spanning domestic Japanese operations and Southeast Asian partnership networks.
| Leading Market Players |
|---|
| Hansol Paper |
| Panda Paper Roll |
| Mitsubishi HiTec Paper |
| Henan Province JiangHe Paper Co., Ltd. |
| Shandong Chenming Paper Holdings Ltd |
| Oji Holdings Corporation |
| Nippon Paper Industries |
| Xiandai Paper Production |
| Ricoh Company Ltd. |
| Others |
Pricing and Supply Chain Analysis
Single-source fluoran dye precursor dependency determines both the premium-to-economy pricing spread and the geographic clustering of coating operations across Asia-Pacific. Japanese chemical houses control leuco dye supply, forcing mills to absorb input volatility or pass through costs while concentrating procurement around pre-certified suppliers with SAMR registration dossiers.
Pricing Analysis
Configured-to-order pricing for pharmaceutical-grade specialty substrates commands substantial premiums over standard POS receipt grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier, with archive-grade formulations for Japan's METI mandates at the top and convenience store receipt volumes at the base. Cost compression in direct thermal grades is intensifying because buyer consolidation among Southeast Asian franchise operators compresses negotiation cycles to quarterly frameworks. Convenience store chains exhibit highest price sensitivity; pharmaceutical label converters demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Export-control scrutiny on fluoran dye precursor technology limits coating chemistry flows from Japan to Chinese mills. Supply concentrates in eastern China's Yangtze River Delta manufacturing belt, South Korea's chemical processing corridor, and Japan's Kanto specialty coating region. Raw material dependencies encompass leuco dye precursors, phenol-free developer systems, and micro-encapsulation polymers. Single-source vulnerability in fluoran dye supply exposes regional mills to allocation risk during demand spikes. Distribution runs through bonded warehouse networks displacing direct mill relationships across Southeast Asian convenience store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific thermal paper is a high-growth disruption anchored by bisphenol-free regulatory mandates forcing wholesale reformulation across domestic Chinese supply chains.
For Market Incumbents: Insulate formulation capabilities through backward integration into phenol-free developer chemistry or exclusive supply agreements with Japanese dye houses. Prioritize SAMR pre-certification investments to capture procurement consolidation among domestic retail chains. Defend against digital receipt substitution by expanding thermal transfer label capacity for cold-chain compliance applications. For New Entrants and Emerging Players: Indonesia's underpenetrated e-commerce logistics segment offers volume entry points through local slitting partnerships with last-mile delivery networks. Target BIS certification gaps in India's organized retail modernization to establish tiered supply windows before incumbent mills complete registration cycles. Pursue bonded warehouse distribution partnerships rather than direct mill relationships to reduce capital intensity. For Investors and Strategic Acquirers: Regional conversion specialists with Southeast Asian slitting capacity and local ticket printer partnerships represent the most defensible acquisition archetype. Long-term viability hinges on coating chemistry ownership or exclusive access to fluoran dye supply channels. Watch for SAMR enforcement acceleration as the signal indicating consolidation timing among pre-certified domestic Chinese mills.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol-Free Developer Chemistry | Captures SAMR-compliant supply chain positioning ahead of 2027 GB standard enforcement. |
| Bonded Warehouse Network Expansion | Displaces direct mill relationships across Thailand and Vietnam convenience store distribution channels. |
| Thermal Transfer Label Capacity Addition | Serves food exporter migration from direct thermal to solvent-resistant cold-chain grades. |
| RFID-Thermal Hybrid Substrate Development | Addresses logistics automation demand in eastern China warehouse automation deployments. |
| Local Slitting Partnership in Indonesia | Opens volume contracts for standardized thermal waybill formats in e-commerce logistics buildout. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across coating mills, chemical suppliers, and retail procurement functions. Primary interviews captured thermal paper mill technical directors, convenience store chain procurement managers, pharmaceutical label converters, and logistics automation engineers. Secondary validation drew from SAMR GB standard filings, METI energy-efficiency labeling databases, customs trade flow records, and SEC 10-K disclosures from listed paper conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, and technology segments.
Calibration against historical price realizations and volume trajectories anchored projections across the analysis window. Segmentation dimensions modeled encompass coating chemistry tier, print technology, regulatory compliance grade, and regional production cluster. CAGRs derived from slope analysis of normalized growth curves applied to each segment's base-year positioning. Industry-specific inputs included leuco dye precursor allocation patterns, SAMR registration cycle timelines, and bonded warehouse throughput capacities.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Chinese state-affiliated paper groups would shift outcomes. Material shifts in SAMR enforcement timelines or fluoran dye export licensing from Japan would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Uncoated White Top Testliner Market
Paper Products
Speciality Pulp and Paper Chemicals Market
Paper Products
Thin Printing Paper Market
Paper Products
White Top Testliner Market
Paper Products
Inkjet Papers and Films Market
Paper Products
Global Kraft Paper Market
Paper Products
Pp Synthetic Paper Market
Paper Products
Paper Goods Market
Paper Products
Carbonless Paper Market
Paper Products
Paper Based Laminates Market
Paper Products
Duplex Paper and Board Market
Paper Products
Metallized Paper Market
Paper Products
Pulp and Paper Market
Paper Products
Paper Glass Market
Paper Products
Loose Leaf Paper Market
Paper Products
Paper Making Machine Market