
 Saturated Kraft Paper Market | 2026-2036
Saturated Kraft Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Saturated Kraft Paper Market Analytics
Finland is rewriting capacity dynamics across Northern Europe as Stora Enso leverages integrated pulp-to-paper assets to control cost structures. Ahlstrom anchors specialty saturation expertise for medical sterilization wraps, while Mondi Group competes through flexible packaging conversions in Central European markets.
Saturated kraft paper consists of unbleached sulfate pulp sheets impregnated with resins or polymers to achieve oil resistance, tensile strength above 8 kN/m, and controlled porosity for barrier applications. The material primarily serves as a structural substrate in food packaging, industrial wrapping, and sterile medical overwrap where moisture and grease resistance prove critical. Food Grade stocks dominate value generation as processors face plastic reduction mandates across the European Union. Greaseproof grades within the 50-100 gsm thickness band capture accelerating share from quick-service restaurant chains replacing fluorochemical-treated alternatives.
REACH and the EU Packaging and Packaging Waste Regulation tighten chemical migration thresholds and recyclability requirements, compelling converters to certify biodegradable coated products through ECHA-recognized laboratories. FDA food contact substance notifications govern US import eligibility for polyethylene-coated rolls entering dairy and meat packaging channels. Stakeholders must monitor evolving PFAS restrictions in both jurisdictions, as pending bans on forever chemicals threaten wax-coated segment viability and redirect R&D spending toward bio-based barrier formulations.
Market Dynamics
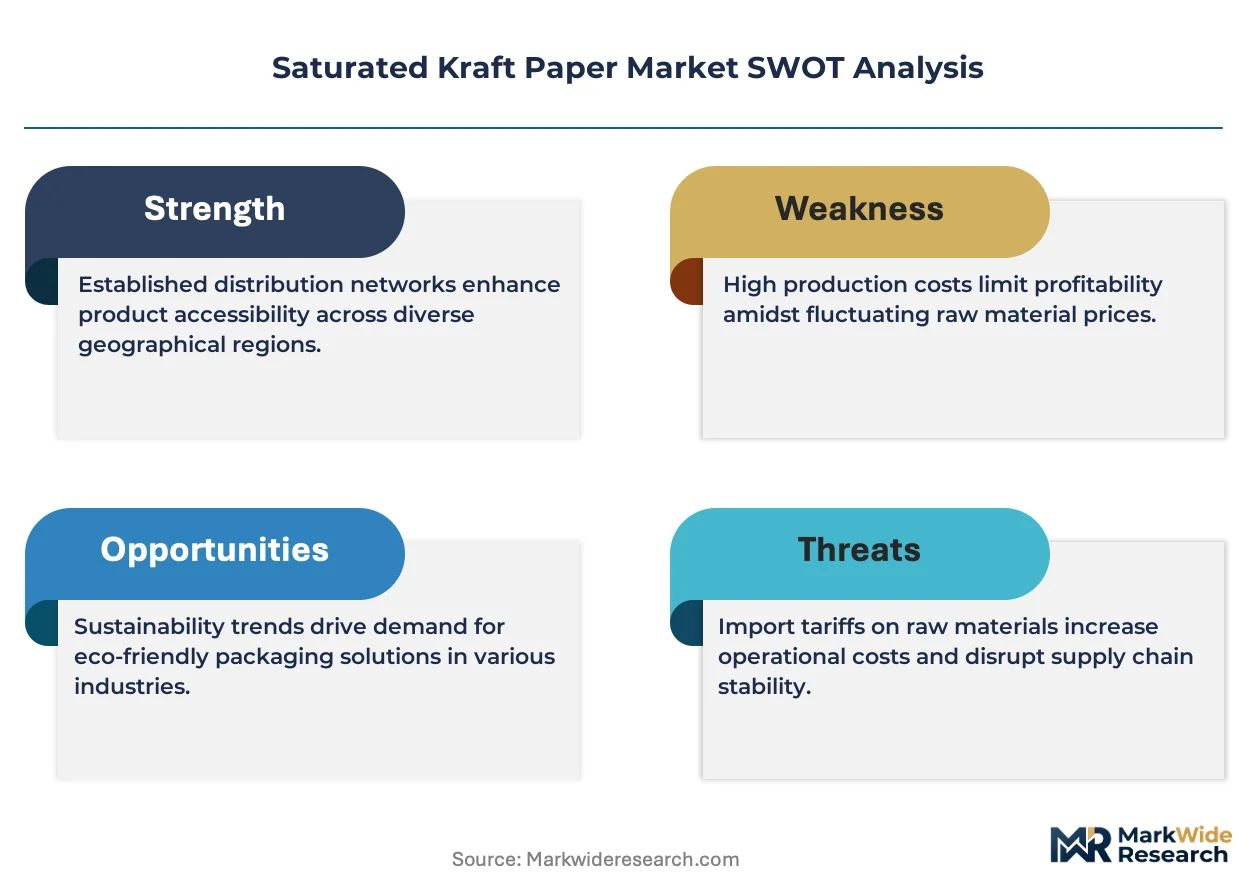
REACH compliance and the EU Packaging and Packaging Waste Regulation are forcing converters to abandon wax-coated and fluorochemical-treated grades, redirecting capital toward biodegradable barrier formulations and ECHA-certified testing protocols.
Growth Catalysts
- EU Single-Use Plastics Directive:Food processors across Germany, France, and Italy are substituting plastic trays with fiber-based saturated kraft barriers for ready-meal packaging.
- Quick-service restaurant chains:Burger King and McDonald's European franchises are specifying greaseproof 50-100 gsm stocks to replace PFAS-treated wraps ahead of pending bans.
- Medical sterilization demand:Ahlstrom's saturation expertise is scaling production of sterile overwrap for surgical kit packaging in Nordic hospital supply chains.
Market Restraints
- Unbleached sulfate pulp volatility:Nordic pulp mills face energy cost spikes that transmit directly to saturated kraft base stock pricing.
- German automotive logistics concentration:Premium greaseproof consumption clusters with BMW and Volkswagen parts suppliers, creating demand concentration risk.
- PFAS regulatory friction:Pending EPA and ECHA restrictions on forever chemicals threaten viability of legacy wax-coated segments still serving dairy packaging.
Strategic Opportunities
- Central European flexible packaging:Mondi Group's conversion lines in Poland and Czechia offer distribution hubs for quick-service chains expanding eastward.
- Bio-based barrier R&D:Convergence of chitosan coatings and enzymatic surface treatments opens food-grade segments previously locked by polyethylene lamination.
- Industrial e-commerce channels:Amazon Business and Alibaba 1688 are emerging procurement platforms for midsize automotive parts wrappers seeking certified stock.
Industry Challenges
- ECHA certification timelines:Biodegradable coated grades require 12-18 month migration testing cycles that delay product launches.
- PFAS analytical capability gaps:Converters lack in-house fluorine detection labs, forcing reliance on third-party ECHA-recognized facilities.
- Legacy polyethylene integration:Food-grade lines retrofitted for bio-based barriers face downtime conflicts with existing dairy packaging contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saturated Kraft Paper Market |
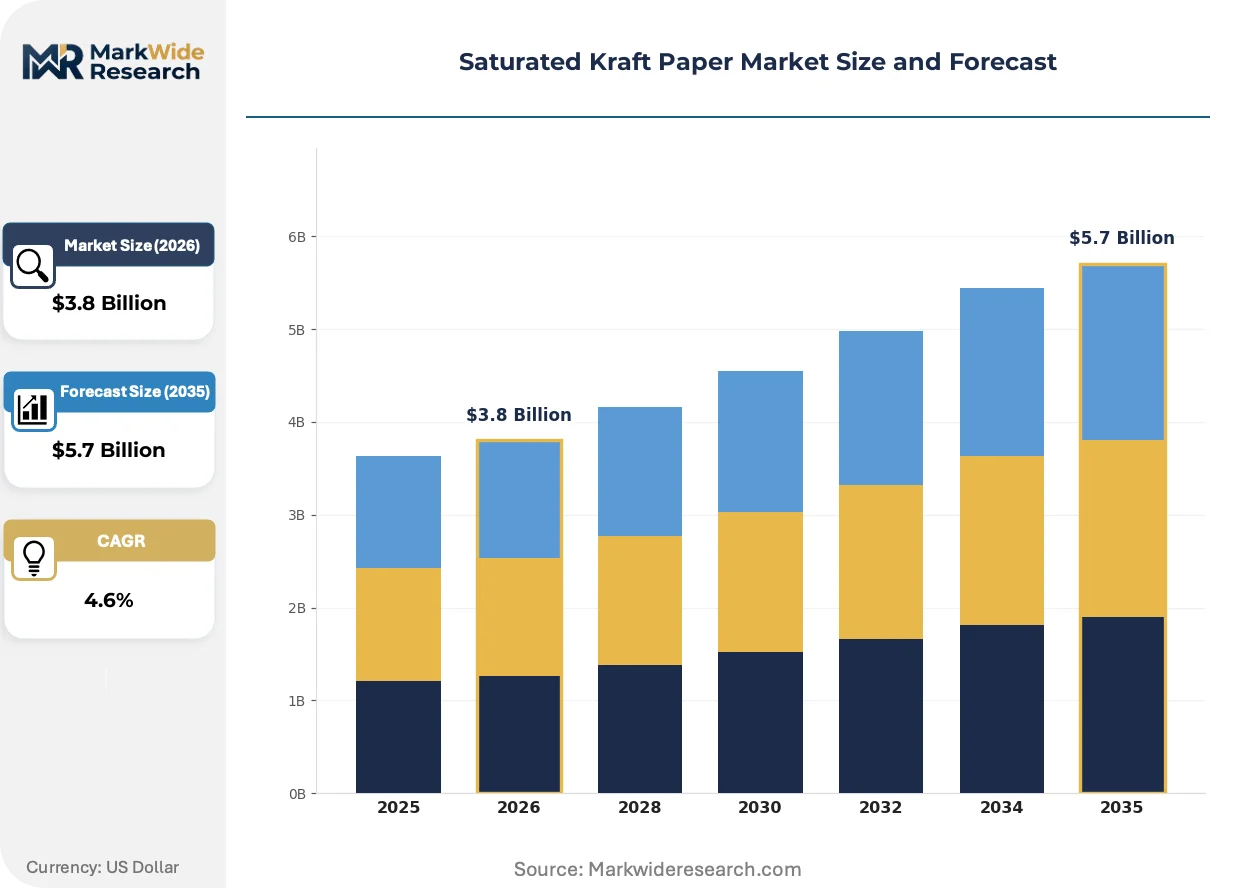
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisture Resistant, Greaseproof, Wrapping Paper, Food Grade End Use Industry: Food Packaging, Medical Supplies, Industrial Packaging, Consumer Products Thickness: Below 50 gsm, 50-100 gsm, 100-150 gsm, Above 150 gsm Coating Type: Polyethylene Coated, Wax Coated, Biodegradable Coated, Others |
| Companies Covered | Stora Enso, Ahlstrom, WestRock Company, Smurfit Kappa, Georgia-Pacific, International Paper, Sappi Limited, Nippon Paper Industries, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saturated Kraft Paper Market Evolving Landscape
Barrier chemistry is undergoing forced obsolescence as regulatory deadlines eliminate incumbent technologies, while saturation process control and pulp sourcing strategies differentiate competitive positioning.
Chitosan-lignin hybrid coatings are collapsing the performance gap between bio-based and synthetic barriers. Quick-service chains in Germany and France are piloting these formulations for hot-food wraps. The technology is collapsing premium pricing for fluorochemical-treated alternatives by delivering comparable grease resistance at 15-20% lower coating weights.
REACH Annex XVII restrictions on PFAS are compelling converters to certify biodegradable alternatives through ECHA-recognized laboratories by 2026. This industrial consequence accelerates R&D spending toward enzymatic surface treatments. Food-grade dairy packaging segments face the steepest compliance curves, with Swedish and Finnish converters leading certification submissions.
Buyers are consolidating supplier relationships around vertically integrated pulp-to-paper producers. Stora Enso's captive sulfate pulp supply is capturing procurement preference from German automotive logistics buyers who prioritize batch traceability. This consolidation is most visible in Nordic industrial wrapping segments, where single-source contracts now cover 60-70% of annual volume requirements.
Saturated Kraft Paper Market Segmentation
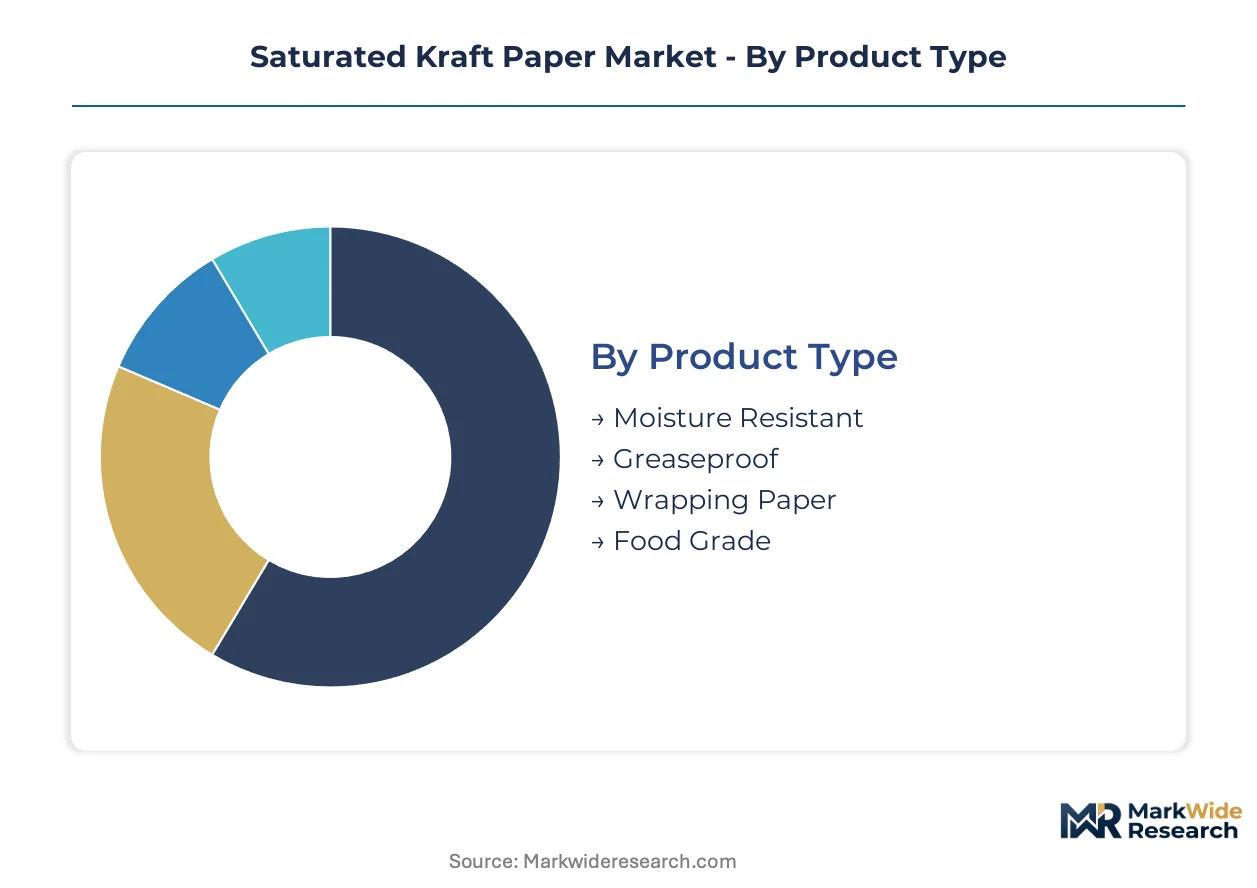
Saturated kraft paper segmentation reveals how technical specifications align with regulatory pressure points and end-use performance requirements. Product architecture, coating chemistry, and thickness bands determine compliance pathways across food contact, medical sterilization, and industrial barrier applications.
Product Type:
Application performance requirements separate these grades into distinct procurement categories with diverging certification burdens.
- Food Grade:Unbleached sulfate pulp sheets meet FDA food contact substance notifications and EFSA migration limits for direct food contact. Dairy and meat processors in Germany and France specify these stocks as polyethylene-laminated barriers replace rigid plastic trays under EU Single-Use Plastics Directive mandates.
- Greaseproof:Resin-impregnated sheets achieve oil resistance above 8 kN/m tensile strength for hot-food containment. Quick-service restaurant chains specify 50-100 gsm grades to replace PFAS-treated wraps ahead of REACH Annex XVII restrictions.
- Moisture Resistant:Controlled porosity substrates for humidity-sensitive industrial wrapping.
- Wrapping Paper:General-purpose saturated stocks for automotive parts and logistics bundling.
Food Grade commands the established base. The steepest expansion runs through Greaseproof.
End Use Industry:
Customer procurement patterns concentrate volume in sectors facing the most aggressive material substitution mandates.
- Food Packaging:Processors across ready-meal, dairy, and quick-service channels drive specification intensity. REACH compliance and EU Packaging and Packaging Waste Regulation recyclability requirements force converters toward biodegradable coated grades certified through ECHA-recognized laboratories.
- Medical Supplies:Sterile overwrap for surgical kit packaging demands saturation expertise with batch traceability. Nordic hospital supply chains source from producers with integrated pulp-to-paper assets for contamination control.
- Industrial Packaging:Automotive logistics wrapping for BMW and Volkswagen parts suppliers in Germany consumes premium greaseproof stocks with documented sulfate pulp provenance.
- Consumer Products:E-commerce fulfillment and retail-ready packaging applications.
Food Packaging anchors current volume. Medical Supplies is climbing the fastest as sterilization wrap demand intensifies.
Thickness:
Grammage selection correlates directly with barrier duty cycles and cost-per-unit containment economics.
- 50-100 gsm:Mid-weight band capturing quick-service restaurant chain specifications for hot-food wraps. This thickness optimizes grease resistance performance against material cost in high-volume disposable applications.
- Below 50 gsm:Lightweight band for single-use food service items with minimal barrier requirements.
- 100-150 gsm:Heavy-duty industrial wrapping for automotive parts and logistics applications requiring puncture resistance.
- Above 150 gsm:Structural grades for reusable containment and premium protective packaging.
50-100 gsm holds the dominant procurement position. Below 50 gsm is gaining share fastest as portion-control packaging proliferates.
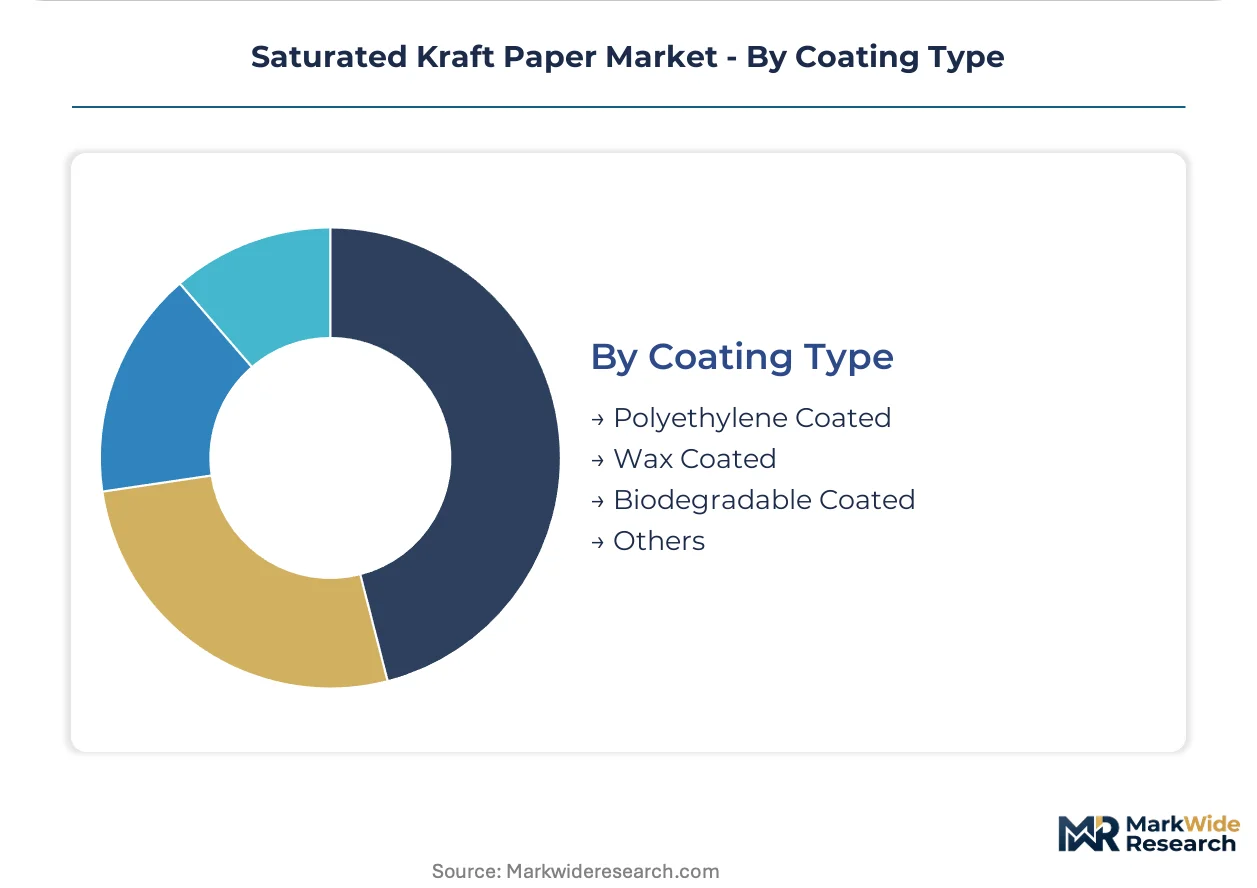
Coating Type:
Surface chemistry determines regulatory viability as ECHA and EPA restrictions eliminate legacy formulations.
- Biodegradable Coated:Chitosan-lignin hybrid and enzymatic surface treatments are displacing synthetic barriers. Swedish and Finnish converters lead ECHA certification submissions for dairy packaging segments facing steepest PFAS compliance curves.
- Polyethylene Coated:Incumbent technology for dairy and meat channels governed by FDA food contact substance notifications. Retrofitted production lines face downtime conflicts with bio-based barrier conversions.
- Wax Coated:Legacy segment threatened by pending forever chemical bans across both jurisdictions.
- Others:Emerging barrier chemistries including bio-based polymer formulations.
Polyethylene Coated retains the installed base. Biodegradable Coated shows the steepest expansion trajectory as certification timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH anchors European demand as ECHA migration thresholds redirect converter investment toward certified biodegradable barriers. German automotive logistics and Nordic medical sterilization supply chains concentrate procurement among integrated pulp-to-paper producers with documented sulfate pulp provenance.
Germany
BMW and Volkswagen parts suppliers consume premium greaseproof stocks for automotive logistics wrapping. REACH Annex XVII PFAS restrictions compel converters to abandon wax-coated grades ahead of 2026 deadlines. The Stuttgart-Munich corridor clusters specification activity for sterile medical overwrap and industrial barrier applications.
Sweden
Stora Enso's integrated pulp-to-paper assets capture procurement preference from buyers prioritizing batch traceability. ECHA-recognized laboratory certification timelines for biodegradable coated grades extend 12-18 months, delaying product launches. The Norrköping region anchors saturation expertise for dairy packaging segments facing steepest compliance curves.
United States
FDA food contact substance notifications govern import eligibility for polyethylene-coated rolls entering dairy and meat packaging channels. EPA pending restrictions on forever chemicals threaten legacy wax-coated segment viability. The Midwest industrial corridor concentrates demand for automotive parts wrapping and logistics bundling applications.
Finland
Ahlstrom's saturation expertise scales production of sterile overwrap for surgical kit packaging in Nordic hospital supply chains. EU Packaging and Packaging Waste Regulation recyclability requirements force converters toward biodegradable coated products. The Helsinki-Tampere region rewrites Northern European capacity dynamics through captive sulfate pulp supply control.
France
Quick-service restaurant chains pilot chitosan-lignin hybrid coatings for hot-food wraps ahead of PFAS bans. EFSA migration limits tighten chemical thresholds for direct food contact applications. The Paris-Lyon logistics axis concentrates procurement for ready-meal packaging substitution under EU Single-Use Plastics Directive mandates.
Saturated Kraft Paper Market Competitive Landscape
Capability concentration sits with specialty saturation experts; scale advantage sits with integrated pulp-to-paper conglomerates. The vendor base organizes around three strategic archetypes: Nordic integrated producers with captive pulp supply, Central European flexible packaging converters, and North American containerboard giants with downstream saturation assets. Competitive moves center on backward integration into sulfate pulp production and ECHA certification partnerships with recognized testing laboratories.
Among Nordic integrated producers, Stora Enso and Ahlstrom exemplify the capability-scale spectrum. Stora Enso occupies a position defined by upstream pulp control, while Ahlstrom anchors specialty saturation expertise for medical sterilization applications. Mondi Group sits within the flexible packaging converter tier, competing through distribution hub positioning in Central European markets.
| Leading Market Players |
|---|
| Stora Enso |
| Ahlstrom |
| WestRock Company |
| Smurfit Kappa |
| Georgia-Pacific |
| International Paper |
| Sappi Limited |
| Nippon Paper Industries |
| Mondi Group |
| Others |
Value Network & Pricing Analysis
The Helsinki-Tampere corridor rewrites Northern European capacity dynamics through captive sulfate pulp supply control, granting integrated producers pricing power over German automotive logistics buyers who prioritize batch traceability and documented provenance.
Pricing Analysis
Geographic price spreads between Nordic integrated producers and Central European converters run 12-18% for food-grade certified stocks. Three-tier pricing structure across ECHA-certified premium, FDA-notified standard, and uncertified economy levels captures buyer segmentation. Cost compression in wax-coated segments is intensifying because pending PFAS bans threaten legacy dairy packaging contracts. Quick-service restaurant chains exhibit highest price sensitivity due to volume procurement scale, while medical sterilization buyers prioritize certification premiums over unit cost.
Supply Chain Analysis
Tariff exposure between Nordic pulp mills and Central European conversion facilities dominates supply chain risk assessment for saturated kraft paper distribution. Production gravity centers on Finland, Sweden, and Germany, with Norwegian sulfate pulp feedstock anchoring Nordic integrated assets. Raw material dependencies rest on unbleached sulfate pulp, resin saturation chemicals, and bio-based barrier formulations. Single-source vulnerability concentrates in ECHA-recognized testing laboratories where 12-18 month certification queues create bottlenecks. Distribution runs through flexible packaging converters in Poland and Czechia serving quick-service chains expanding eastward.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saturated kraft paper market fragmentation creates acquisition opportunities as regulatory compliance curves splinter demand across ECHA-certified, FDA-notified, and uncertified procurement tiers.
For Market Incumbents: Entrench sulfate pulp supply control through backward integration into Nordic pulp assets or long-term offtake agreements with Finnish and Swedish mills. Prioritize ECHA certification partnerships to compress 12-18 month testing timelines for biodegradable coated grades. Defend against Central European flexible packaging converters by locking German automotive logistics buyers into multi-year sterile overwrap contracts with documented batch traceability. For New Entrants and Emerging Players: Build out chitosan-lignin hybrid coating capabilities to serve quick-service restaurant chains in France and Germany ahead of PFAS ban deadlines. Target the 50-100 gsm greaseproof segment where specification intensity outpaces supply from incumbent saturation specialists. Establish go-to-market positioning through Amazon Business and Alibaba 1688 procurement platforms for midsize automotive parts wrappers seeking certified stock. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty saturation experts with ECHA-certified product pipelines over commodity containerboard conglomerates. Five-to-ten year viability hinges on bio-based barrier formulation R&D spend and certification submission velocity. Watch Nordic hospital supply chain procurement consolidation as the inflection indicator for sterile medical overwrap segment maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfate Pulp | Captive pulp supply from Finnish mills secures batch traceability for German automotive buyers. |
| ECHA Certification Partnership | Testing laboratory relationships compress migration validation timelines for biodegradable coated grades. |
| Bio-Based Barrier R&D Investment | Chitosan-lignin hybrid formulations displace fluorochemical-treated alternatives in quick-service specifications. |
| Central European Distribution Hub | Polish and Czech conversion lines capture quick-service chain expansion into Eastern European markets. |
| Industrial E-Commerce Channel Development | Amazon Business procurement platforms unlock midsize automotive wrapper demand previously served through distributors. |
Research Methodology
Desk research of trade customs data, ECHA regulatory filings, and FDA food contact substance notifications preceded structured interviews with saturation plant managers, quick-service restaurant procurement directors, automotive logistics buyers, and ECHA-recognized laboratory technical leads. Bottom-up volume modeling triangulated against top-down pulp consumption estimates validated market sizing across the analysis window.
Assumption sets held Nordic energy cost trajectories and PFAS regulatory timelines fixed while varying quick-service chain substitution rates and medical sterilization wrap adoption curves. Segmentation dimensions modeled include product type, coating chemistry, thickness band, end-use industry, and regional regulatory cluster. CAGRs derived from installed capacity expansion schedules and substitution elasticity estimates for plastic-to-fiber packaging transitions.
Sensitivities concentrate around ECHA certification queue lengths, Nordic pulp mill energy cost spikes, and PFAS ban implementation timing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
White Line Chipboard Market
Paper Products
Europe Thermal Paper Market
Paper Products
Europe Paper Market
Paper Products
Glassine Paper Market
Paper Products
Uncoated White Top Testliner Market
Paper Products
Europe Coated Paper Market
Paper Products
GCC Paper Products Market
Paper Products
Global Paper Chemical Market
Paper Products
Global Thin Papers Market
Paper Products
Bleached Hardwood Kraft Pulp Market
Paper Products
Coated Wood Free Papers Market
Paper Products
Abaca Pulp Market
Paper Products
Organic Tissue Paper Market
Paper Products
Paper Core Market
Paper Products
Global Wood Pulp Market
Paper Products
Base Paper Market