
 Australia Patient Monitoring Market | 2026-2036
Australia Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Patient Monitoring Market Outlook
TGA compliance under the Essential Principles and software-as-a-medical-device guidance is unwinding the competitive landscape for patient monitoring systems in Australia. Koninklijke Philips N.V. leverages its established hospital contracting relationships to sustain installed-base expansion across major metropolitan health networks. Mindray Medical International Co. Ltd. competes aggressively on price-performance metrics in the mid-tier clinic segment. Medtronic Plc anchors its position through deep integration with cardiac implantable ecosystems that feed data into longitudinal monitoring platforms.
Australia patient monitoring encompasses electronic systems that acquire, process, display, and transmit physiological parameters including electrocardiography waveforms, pulse oximetry saturation levels, respiratory rates, and invasive blood pressure readings with sampling frequencies typically exceeding 250 Hz for diagnostic-grade devices. These systems serve the primary commercial purpose of enabling early detection of patient deterioration, reducing unplanned intensive care admissions, and supporting decentralized care delivery outside traditional acute settings. Bedside monitors occupy the largest revenue pool within product categories due to mandatory deployment in perioperative and critical care wards, while wearable devices represent the fastest-expanding segment as battery longevity extends past 14 days and form factors shrink below 15 grams. Telehealth technology underpins the structural shift toward remote monitoring by enabling real-time clinician oversight of patients discharged to home care environments.
The Therapeutic Goods Administration enforces conformity assessment procedures aligned with the Medical Device Regulations, while the Australian Commission on Safety and Quality in Health Care mandates minimum monitoring capabilities through its National Safety and Quality Health Service Standards. These frameworks elevate barriers for unvalidated imports and create preference for vendors with established local regulatory affairs capabilities. Stakeholders must weigh capital deployment between centralized hospital infrastructure and distributed home-based monitoring architectures as reimbursement pathways for remote patient management mature through the National Health Reform Agreement.
Market Dynamics
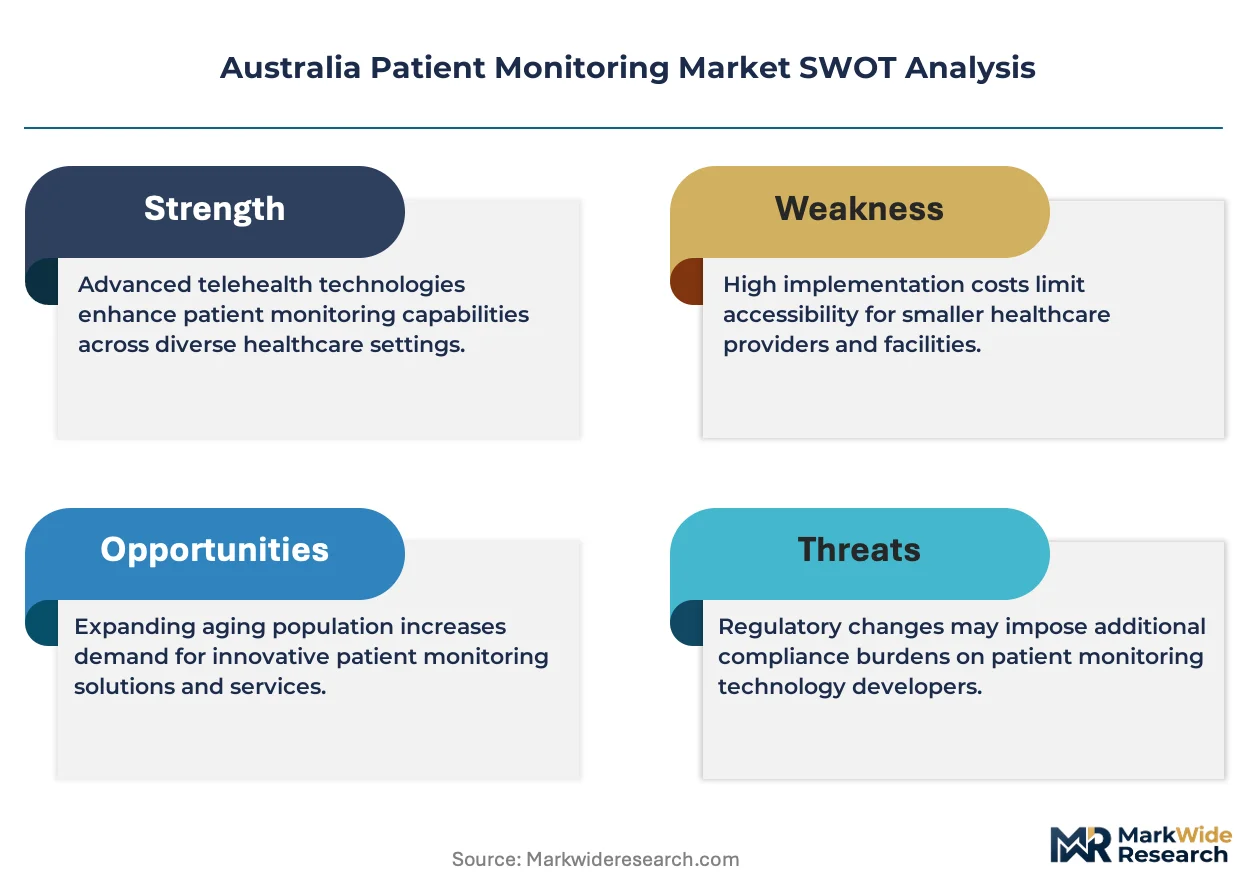
Post-acute care decentralization is compressing traditional hospital-centric procurement models, forcing vendors to rearchitect distribution and service delivery around home care provider networks and remote clinical oversight platforms.
Growth Catalysts
- National Health Reform Agreement:Reimbursement pathway maturation for remote patient management is pulling capital toward distributed monitoring architectures beyond traditional acute settings.
- Wearable form factor miniaturization:Battery longevity exceeding 14 days and device weights below 15 grams is unlocking continuous physiological surveillance in ambulatory and residential aged care environments.
- New South Wales and Victoria health networks:Accelerated public hospital procurement of connected monitoring systems is consolidating demand around vendors with established integration capabilities.
Market Restraints
- Semiconductor component concentration:Reliance on specialized ASIC suppliers for high-frequency physiological signal processing creates vulnerability in diagnostic-grade device manufacturing.
- TGA software-as-a-medical-device framework:Extended conformity assessment timelines for algorithm-driven monitoring platforms are elevating regulatory friction for AI-enabled diagnostic features.
- Disposable electrode and sensor costs:Recurring consumable expenditure for multi-parameter monitoring is compressing margins in high-volume clinic deployments.
Strategic Opportunities
- Queensland and Western Australia regional health districts:Underpenetrated procurement of centralized patient monitoring infrastructure presents whitespace for vendors with remote installation and training capabilities.
- Cardiac implantable ecosystem convergence:Integration between pacemaker and defibrillator data streams with longitudinal monitoring platforms is opening subscription-based revenue models.
- Home care provider channel expansion:Direct-to-provider distribution bypassing traditional hospital procurement committees is accelerating sales cycles for wearable and telehealth-enabled systems.
Industry Challenges
- Biomedical engineering talent scarcity:Shortage of specialists capable of servicing networked monitoring architectures across dispersed geographic footprints is constraining vendor service coverage.
- Legacy bedside monitor interoperability:Integration complexity with proprietary data protocols from incumbent installed bases is delaying replacement cycles and elevating switching costs for health networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Patient Monitoring Market |
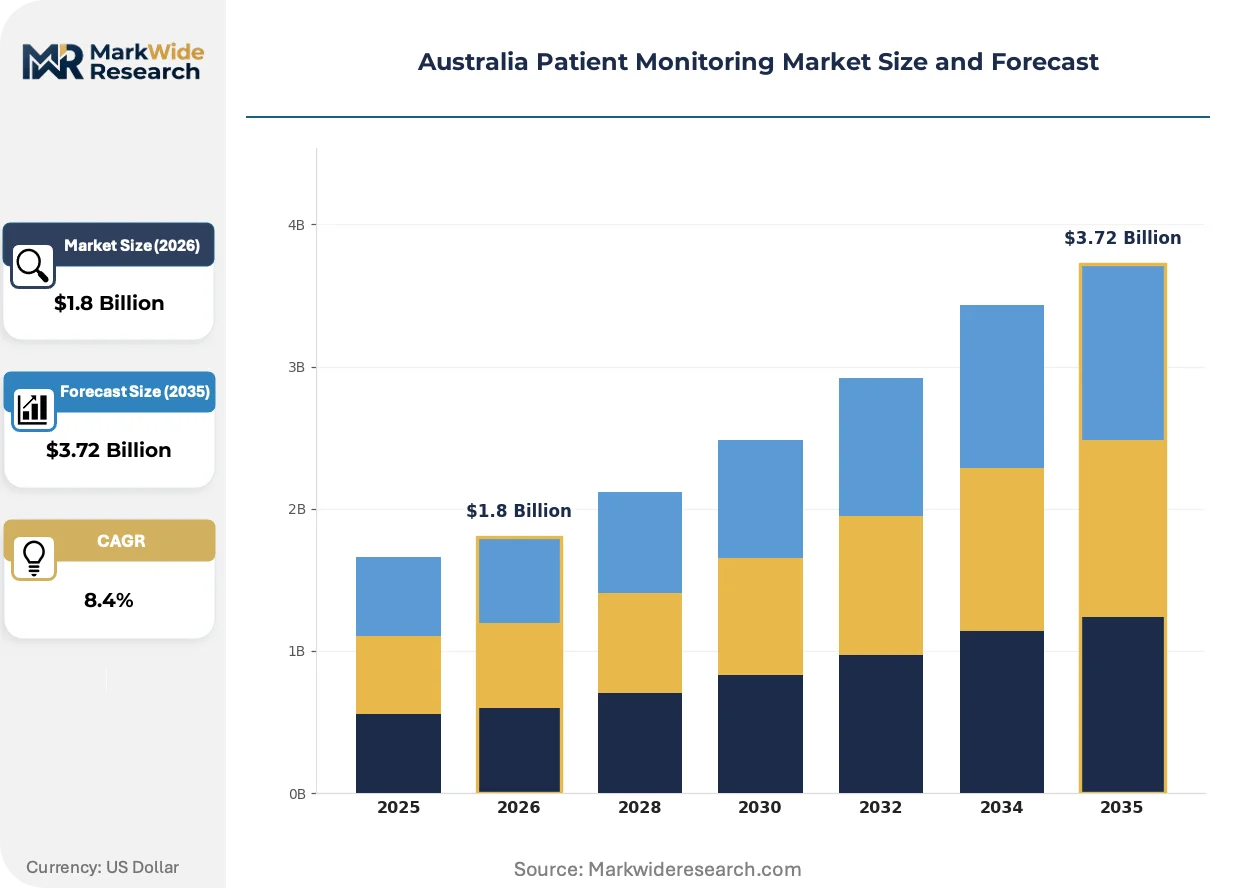
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Bedside Monitors, Implantable Monitors, Handheld Monitors Technology: Telehealth, IoT, Wireless Communication, Cloud-Based Solutions End User: Clinics, Hospitals, Home Care Providers, Rehabilitation Centers Application: Chronic Disease Management, Post-Operative Care, Remote Monitoring, Vital Signs Monitoring |
| Companies Covered | Koninklijke Philips N.V, Mindray Medical International Co. Ltd., Nihon Kohden Corporation, Baxter International Inc., Siemens Healthineers, Medtronic Plc, GE Healthcare, Abbott Laboratories, Masimo Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Patient Monitoring Market Strategic Shifts
Clinical validation requirements and reimbursement granularity are forcing technology roadmaps toward demonstrable outcome metrics rather than feature accumulation, reshaping how vendors prioritize development spend.
Artificial intelligence-enabled arrhythmia detection is bifurcating the competitive landscape between algorithm-native entrants and hardware-incumbent retrofit strategies. Cardiology departments in tertiary hospitals are piloting these systems for overnight telemetry substitution. The structural consequence is compressing standalone hardware margins while elevating software licensing and clinical decision support revenue pools.
TGA's updated guidance on software-as-a-medical-device is mandating clinical evidence packages for algorithm updates that modify diagnostic thresholds. This elevates compliance costs for machine learning-based monitoring platforms. Vendors are responding by establishing captive clinical validation operations within Australian jurisdictions to maintain iteration velocity.
Subscription-based remote monitoring contracts are displacing capital-intensive equipment purchases in home care provider segments. Equipment-as-a-service models bundle hardware, connectivity, and clinical oversight into per-patient-per-month fee structures. This shift is most visible in Victoria's aged care provider networks, where occupancy pressures favor operational expenditure over balance sheet expansion.
Australia Patient Monitoring Market Segmentation
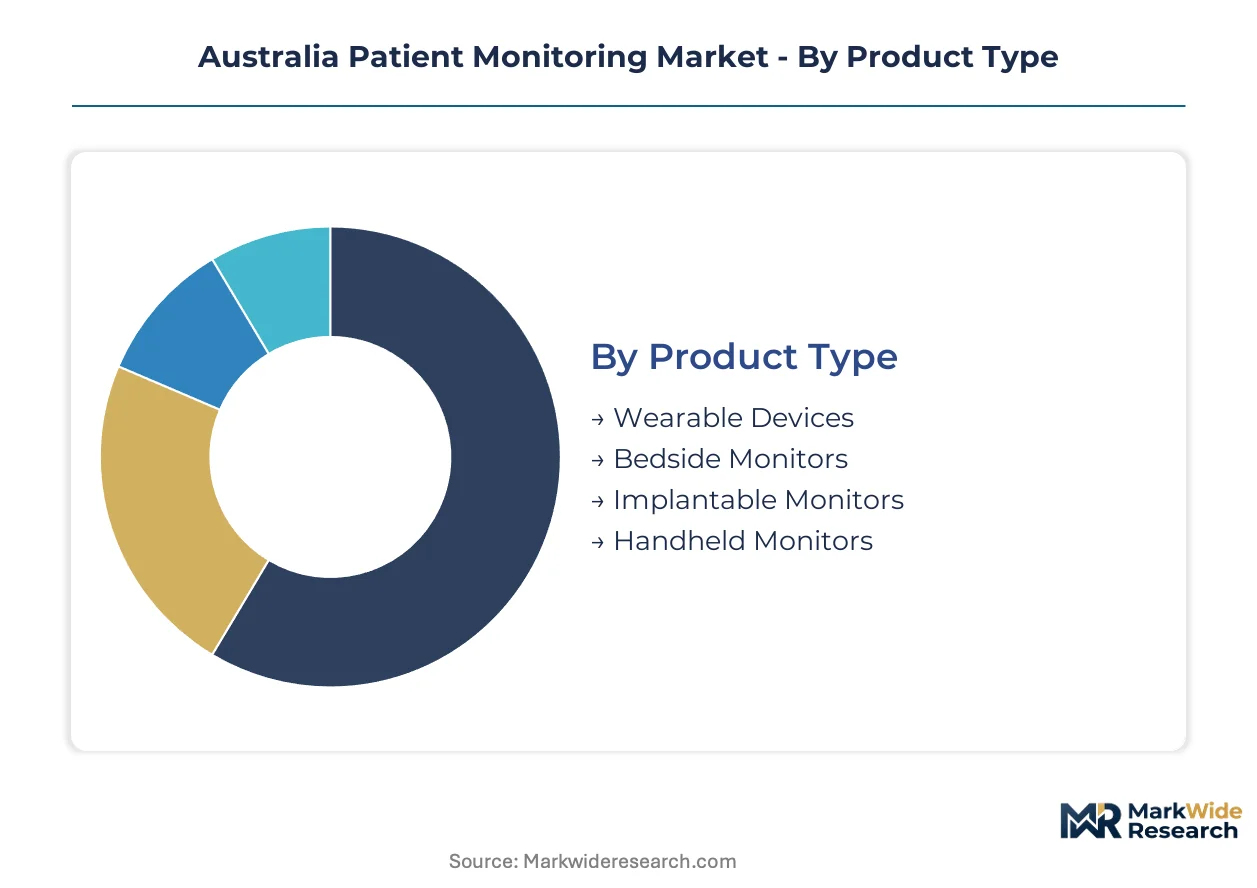
Product architecture in the Australia patient monitoring market fragments across four distinct dimensions that shape procurement patterns and margin structures. Technology choices determine integration complexity with existing health network infrastructure. End-user channel selection dictates whether vendors compete through capital equipment sales or recurring service contracts.
Product Type:
Wearable devices face the most acute substitution pressure from consumer-grade health trackers as TGA software-as-a-medical-device guidance tightens clinical-grade differentiation requirements.
- Bedside Monitors:Fixed multi-parameter systems acquire electrocardiography, pulse oximetry, respiratory rate, and invasive blood pressure at sampling frequencies exceeding 250 Hz. Demand concentrates in New South Wales and Victoria public hospital networks where perioperative and critical care wards mandate continuous surveillance. Mandatory deployment in these settings insulates the segment from price erosion despite capital budget pressures.
- Wearable Devices:Battery-powered physiological sensors now achieve longevity past 14 days with form factors below 15 grams, enabling ambulatory and residential aged care surveillance. Home care providers in Victoria are accelerating procurement as post-acute care decentralization pulls monitoring beyond hospital walls. TGA conformity assessment timelines for algorithm-driven features create regulatory friction that favors established vendors with local clinical validation capabilities.
- Implantable Monitors:Cardiac rhythm management devices feed data streams into longitudinal monitoring platforms through deep integration with pacemaker and defibrillator ecosystems.
- Handheld Monitors:Portable spot-check devices serve mid-tier clinic segments where price-performance metrics dominate procurement decisions and disposable electrode costs compress margins.
Bedside monitors retain volume leadership; wearable devices hold the steepest expansion curve.
Technology:
Cost tier stratification separates enterprise-grade health network integrations from budget-conscious clinic deployments, with connectivity architecture as the primary price determinant.
- Cloud-Based Solutions:Centralized data repositories enable real-time clinician oversight of patients discharged to home care environments, with subscription-based per-patient-per-month fee structures displacing capital-intensive equipment purchases. Queensland and Western Australia regional health districts present whitespace for vendors with remote installation capabilities.
- Telehealth:Real-time video and audio interfaces underpin structural shifts toward remote monitoring by enabling synchronous clinical consultation alongside asynchronous physiological data review. The National Health Reform Agreement's maturing reimbursement pathways for remote patient management are pulling capital toward these distributed architectures.
- IoT:Networked sensor ecosystems connect bedside, wearable, and implantable devices through standardized data protocols that reduce integration complexity with proprietary incumbent systems.
- Wireless Communication:Bluetooth and proprietary radio protocols enable device mobility within hospital wards and residential aged care facilities without tethering to fixed infrastructure.
Cloud-based solutions command premium pricing; telehealth infrastructure is expanding most quickly across home care provider networks.
End User:
Customer type determines sales cycle length and contract structure, with direct-to-provider distribution bypassing traditional hospital procurement committees in the fastest-growing channel.
- Home Care Providers:Aged care and post-acute service organizations favor operational expenditure models that bundle hardware, connectivity, and clinical oversight. Equipment-as-a-service contracts are most visible in Victoria's provider networks where occupancy pressures constrain balance sheet expansion.
- Hospitals:Metropolitan health networks in New South Wales and Victoria consolidate demand around vendors with established integration capabilities and local biomedical engineering service coverage.
- Clinics:Mid-tier outpatient facilities compete aggressively on price-performance metrics, with disposable electrode and sensor costs compressing margins in high-volume deployments.
- Rehabilitation Centers:Post-operative and chronic disease recovery facilities require continuous monitoring during transitional care phases before patient discharge to home environments.
Hospitals retain volume leadership; home care providers hold the steepest expansion curve.
Application:
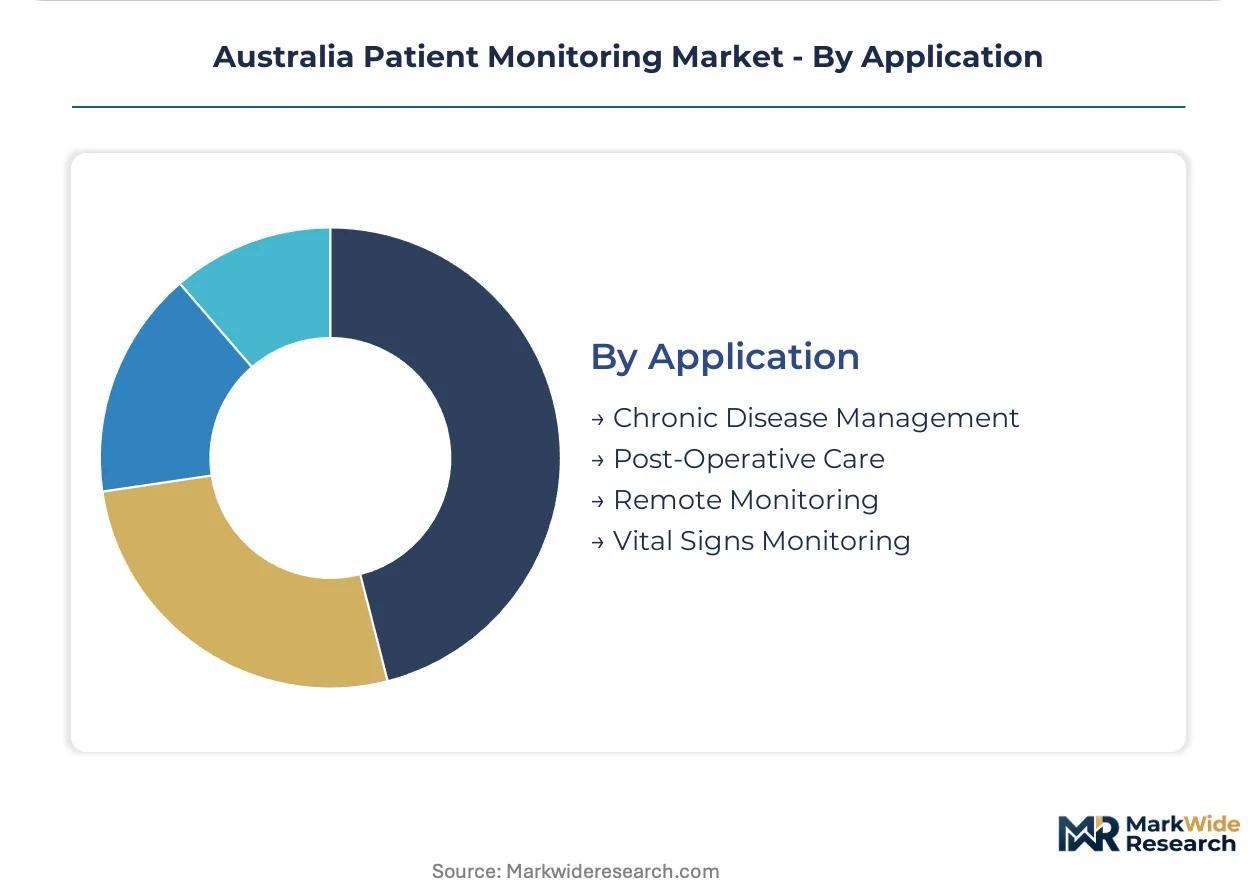
Application maturity varies by clinical evidence requirements and reimbursement granularity, with outcome-based validation forcing technology roadmaps toward demonstrable metrics rather than feature accumulation.
- Chronic Disease Management:Longitudinal surveillance of cardiac, respiratory, and metabolic conditions requires integration between implantable device data streams and external monitoring platforms. Subscription-based revenue models are opening through cardiac implantable ecosystem convergence.
- Remote Monitoring:Real-time clinician oversight of patients outside acute settings depends on telehealth infrastructure and cloud-based data aggregation. TGA software-as-a-medical-device framework mandates clinical evidence packages for algorithm updates that modify diagnostic thresholds.
- Post-Operative Care:Transitional monitoring from surgical wards through rehabilitation to home recovery requires interoperability across bedside, handheld, and wearable device categories.
- Vital Signs Monitoring:Continuous or intermittent acquisition of core physiological parameters serves as the foundational application across all product types and end-user channels.
Vital signs monitoring retains volume leadership; remote monitoring holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The National Health Reform Agreement's maturing reimbursement pathways for remote patient management are redistributing procurement authority from centralized hospital networks toward regional health districts and home care providers across Australian states.
New South Wales
Metropolitan public hospital networks in Sydney and Newcastle are accelerating capital deployment for connected perioperative monitoring systems. TGA conformity assessment procedures for software-as-a-medical-device platforms create procurement preference for vendors with established local regulatory affairs capabilities. The Sydney Local Health District anchors demand concentration through its critical care ward expansion program.
Victoria
Home care provider networks in Melbourne and Geelong are displacing traditional hospital-centric procurement through equipment-as-a-service contracts. The Australian Commission on Safety and Quality in Health Care mandates minimum monitoring capabilities through National Safety and Quality Health Service Standards compliance. Victoria's aged care sector leads national adoption of wearable form factors with battery longevity exceeding 14 days.
Queensland
Regional health districts outside Brisbane present underpenetrated whitespace for centralized patient monitoring infrastructure. TGA Essential Principles enforcement elevates barriers for unvalidated imports into remote installation environments. The Gold Coast University Hospital cluster drives tertiary referral network demand for longitudinal cardiac monitoring platforms.
Western Australia
Perth metropolitan health networks consolidate demand around vendors with remote biomedical engineering service coverage across dispersed geographic footprints. The Therapeutic Goods Administration's updated software-as-a-medical-device framework reshapes market entry for algorithm-driven diagnostic platforms. Pilbara and Kimberley regional districts require portable monitoring architectures suited to fly-in-fly-out clinical workforce models.
South Australia
Adelaide's metropolitan health network procurement committees favor vendors with demonstrated interoperability against proprietary legacy bedside monitor protocols. The National Health Reform Agreement's decentralized care incentives pull capital toward distributed monitoring architectures in Barossa Valley and Fleurieu Peninsula aged care facilities. Biomedical engineering talent scarcity constrains vendor service coverage expansion into remote regional districts.
Australia Patient Monitoring Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with established hospital contracting relationships, compressing margin availability for mid-tier specialists. Market structure concentrates around three archetypes: hardware-incumbent systems integrators leveraging installed-base lock-in, algorithm-native software platforms pursuing TGA software-as-a-medical-device clearance, and cardiac implantable ecosystem anchors feeding device data into longitudinal monitoring platforms. Dominant competitive moves include strategic partnerships for cloud-based data aggregation capabilities and portfolio diversification into subscription-based remote monitoring contracts.
Among diversified medical technology conglomerates, Koninklijke Philips N.V. and Siemens Healthineers occupy positions exemplifying hardware-incumbent systems integration strategies, while Medtronic Plc anchors the cardiac implantable ecosystem convergence archetype. These three entities represent contrasting pathways for market positioning: established hospital network relationships, mid-tier clinic price-performance competition, and deep device-to-platform integration respectively. Their collective presence shapes procurement committee preferences across New South Wales and Victoria metropolitan health networks.
| Leading Market Players |
|---|
| Koninklijke Philips N.V |
| Mindray Medical International Co. Ltd. |
| Nihon Kohden Corporation |
| Baxter International Inc. |
| Siemens Healthineers |
| Medtronic Plc |
| GE Healthcare |
| Abbott Laboratories |
| Masimo Corporation |
| Others |
Value Chain & Pricing Dynamics
TGA Essential Principles certification gates both supplier qualification and price differentiation in the Australia patient monitoring market, forcing vendors to absorb compliance costs that stratify offerings across clinical-grade tiers while locking out uncertified imports from competing on cost.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate procurement between major health networks and device manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade bedside systems with full integration services from mid-tier clinic deployments and budget spot-check devices. Price differentiation rests on TGA software-as-a-medical-device clearance tier and local biomedical engineering service coverage. Pricing pressure stems from disposable electrode and sensor consumables compressing margins in high-volume clinic segments. Home care providers exhibit highest price sensitivity due to occupancy pressures favoring operational expenditure models, while tertiary hospital networks prioritize integration capabilities over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites semiconductor component flows from Taiwan, South Korea, and Japan into Australian manufacturing and assembly operations. Diagnostic-grade patient monitoring devices draw from specialized ASIC suppliers for high-frequency physiological signal processing, lithium-ion cell producers for extended battery architectures, and medical-grade sensor foundries for pulse oximetry and ECG acquisition modules. Single-source vulnerability concentrates in algorithm-native chipsets for AI-enabled arrhythmia detection. Distribution runs through hospital procurement committees in New South Wales and Victoria, direct-to-provider channels for home care networks, and regional health district tenders in Queensland and Western Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's patient monitoring market rewards vendors who control scarce biomedical engineering talent capable of servicing networked architectures across dispersed geographic footprints, while penalizing those dependent on offshore algorithm development without local clinical validation infrastructure.
For Market Incumbents: Shield installed-base positions in New South Wales and Victoria metropolitan health networks by deepening captive biomedical engineering service coverage and accelerating TGA software-as-a-medical-device clearance for algorithm-driven features before mid-tier competitors achieve regulatory parity. Prioritize backward integration into cloud-based data aggregation capabilities to capture recurring subscription revenue as equipment-as-a-service models displace capital sales. For New Entrants and Emerging Players: Remote installation and training capabilities for Queensland and Western Australia regional health districts represent the most penetrable whitespace, where incumbent service coverage gaps create procurement friction for centralized monitoring infrastructure. Target direct-to-provider distribution bypassing hospital procurement committees in Victoria's aged care sector, where per-patient-per-month fee structures favor agile entrants over capital-heavy conglomerates. For Investors and Strategic Acquirers: TGA's updated software-as-a-medical-device framework reshapes the acquisition landscape toward algorithm-native platforms with established Australian clinical validation operations rather than hardware-incumbent retrofit strategies. Long-term viability over the coming decade hinges on subscription-based revenue model maturity and cardiac implantable ecosystem integration depth. Watch for National Health Reform Agreement reimbursement pathway expansions as the critical inflection signal for remote monitoring platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Software-as-a-Medical-Device Clearance | Establishes market entry legitimacy for algorithm-driven diagnostic platforms under Essential Principles enforcement. |
| Hospital System Partnership | Locks in multi-year procurement commitments across Sydney and Melbourne metropolitan health networks. |
| Biomedical Engineering Service Expansion | Addresses talent scarcity constraining vendor coverage in Pilbara and Kimberley regional districts. |
| Software Companion Development | Enables overnight telemetry substitution pilots in tertiary hospital cardiology departments. |
| Reimbursement Strategy | Aligns equipment-as-a-service contracts with National Health Reform Agreement remote patient management pathways. |
Study Parameters
A standing panel of hospital procurement managers, biomedical engineers, home care provider operations directors, and TGA regulatory affairs specialists provided ongoing calibration across the research process. Primary interviews with these stakeholders combined with secondary validation against TGA device registration databases, National Health Reform Agreement policy documents, hospital procurement committee minutes, and Australian Commission on Safety and Quality in Health Care standards. Bottom-up demand modeling across product types, technologies, and end-user channels triangulated against top-down market sizing from health expenditure flows.
Consistency checks validated volume and value outputs against external benchmarks including state health department capital equipment budgets, aged care provider technology expenditure disclosures, and cardiac implantable device registry data. The analytical framework segmented the market across product architecture, connectivity technology, end-user channel, and clinical application dimensions throughout the projection horizon. CAGRs were derived from trend extrapolation of public hospital procurement cycles, wearable device battery longevity improvement curves, and telehealth reimbursement pathway maturation trajectories.
Forecasts assume regulatory continuity in TGA Essential Principles and software-as-a-medical-device guidance; material policy shifts would require re-modeling of algorithm-driven platform entry timelines and compliance cost structures. Scenario risks include semiconductor supply disruption, biomedical engineering talent migration, and National Health Reform Agreement reimbursement rate revisions. Practitioners should keep alternative scenarios live as post-acute care decentralization velocity and wearable form factor miniaturization trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
France Patient Monitoring Market
Patient Monitoring
Pain Monitoring Devices Market
Patient Monitoring
Asthma Monitoring Devices Market
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market
Patient Monitoring
Neonatal and Fetal Monitors Market
Patient Monitoring
Smart Medication Adherence Sensors Market
Patient Monitoring
Healthcare Biosensors IoT Market
Patient Monitoring
Cardiopulmonary Exercise Testing Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
Global Arrhythmia Monitoring Devices Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market
Patient Monitoring
Neuro-Monitoring System Market
Patient Monitoring
North America Hemodynamic Monitoring Market
Patient Monitoring
Patient Monitoring Accessories Market
Patient Monitoring
Global Heart Rate Monitor Market
Patient Monitoring
Latin America Self -Monitoring Blood Glucose Market