
 Europe Hemodynamic Monitoring Market | 2026-2036
Europe Hemodynamic Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hemodynamic Monitoring Market Foresight
Critical care departments across European hospitals is expanding their use of continuous hemodynamic monitoring to manage septic shock and post-surgical recovery. Edwards Lifesciences Corporation leverages its transcatheter valve heritage to anchor premium positioning in invasive pressure monitoring. Baxter International competes through integrated fluid management systems that pair with hemodynamic parameters. Siemens Healthineers sustains technology leadership in ultrasound-based hemodynamic assessment across German and Benelux hospital networks.
Europe Hemodynamic Monitoring encompasses devices that measure cardiac output, blood pressure, and vascular resistance through invasive catheters, non-invasive sensors, or hybrid continuous platforms, typically operating with precision thresholds of plus-or-minus ten percent for cardiac output calibration. These systems serve primarily to guide fluid therapy, vasoactive drug titration, and early detection of hemodynamic instability in perioperative and intensive care settings. Non-invasive monitors are capturing share fastest among technology segments as anesthesia departments seek to reduce catheter-related complications. Invasive monitors retain the deepest margin pools in cardiac surgery applications where thermodilution remains the reference standard. Emergency medicine represents an underdeveloped application channel where handheld monitors could displace traditional ward-based assessment workflows.
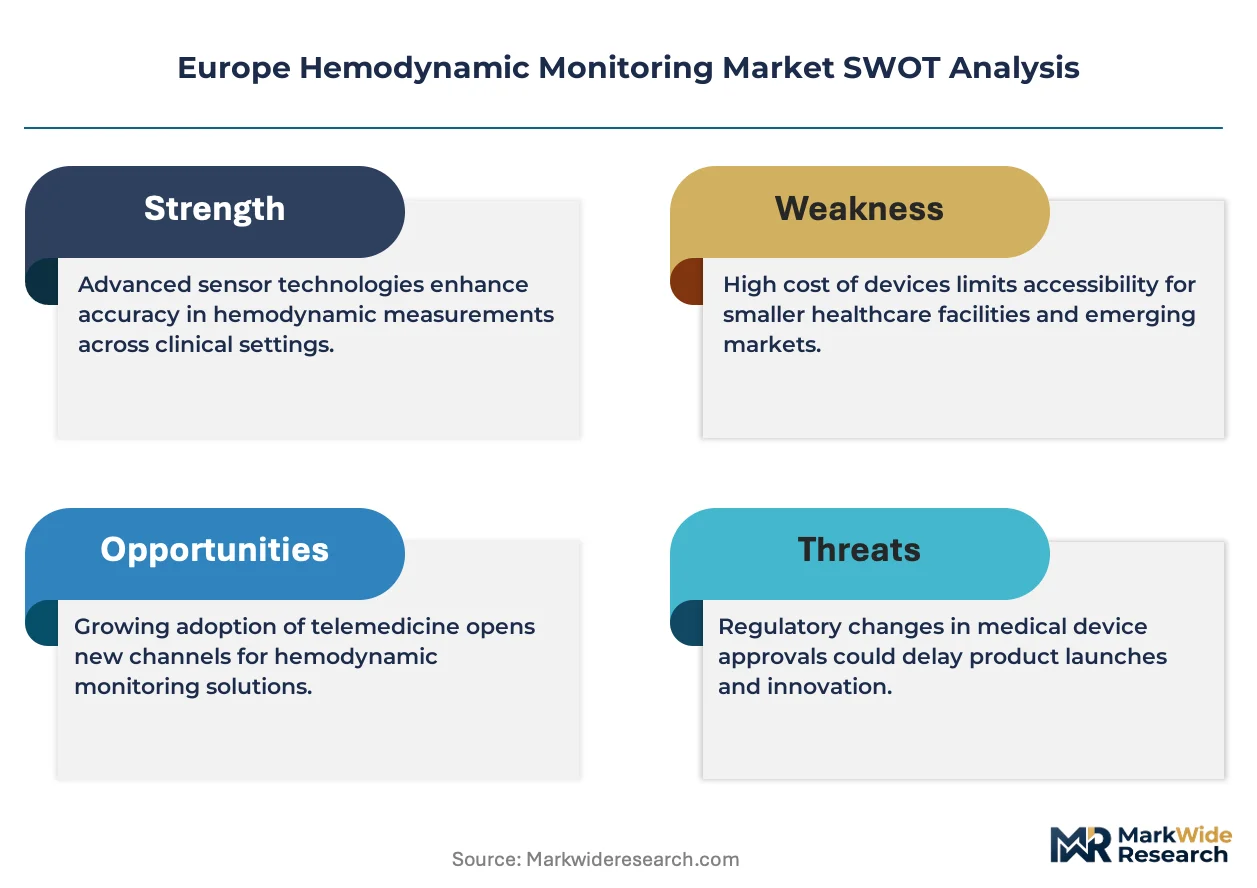
EMA's Medical Device Regulation imposes stricter clinical evaluation and post-market surveillance obligations on hemodynamic device manufacturers, elevating compliance costs but also consolidating market access around established players with robust quality management systems. The EU Green Deal and national hospital sustainability mandates are pushing procurement toward energy-efficient monitor platforms with reduced disposable waste profiles. Stakeholders must weigh MDR transition timelines against the pace of non-invasive technology maturation when allocating R&D and commercial resources across European markets.
Market Dynamics
EMA's Medical Device Regulation (MDR) is compressing market access timelines while simultaneously elevating clinical evidence burdens, forcing manufacturers to reallocate resources from innovation pipelines toward regulatory compliance infrastructure.
Growth Catalysts
- Cardiac surgery volume expansion:German university hospitals are scaling continuous monitoring deployments across hybrid operating theaters, creating procurement anchors for high-acuity systems.
- EU Green Deal procurement mandates:Hospital sustainability frameworks are redirecting capital toward energy-efficient platforms with reduced disposable waste profiles.
- Non-invasive sensor maturation:Photoplethysmography and bioimpedance technologies are achieving precision parity with thermodilution in select anesthesia applications.
Market Restraints
- MDR compliance cost escalation:Clinical evaluation report requirements and notified body capacity constraints are extending time-to-market for Class III invasive devices.
- Single-source component dependencies:Pressure transducer and fiber-optic cable supply concentrates among specialized German and Swiss component manufacturers.
- Thermodilution reference standard entrenchment:Cardiac surgery protocols maintain invasive catheter requirements despite non-invasive alternatives, limiting addressable market expansion.
Strategic Opportunities
- Emergency medicine workflow displacement:Handheld hemodynamic monitors could replace traditional ward-based assessment in French and Italian triage networks.
- MDR transition window consolidation:Established players with robust quality management systems capture share from smaller manufacturers exiting due to compliance burden.
- Ultrasound-hemodynamic convergence:Integration of transthoracic echocardiography with continuous monitoring platforms creates hybrid diagnostic-therapeutic workstations.
Industry Challenges
- Notified body bottleneck:MDR certificate issuance delays are compressing revenue recognition timelines for device manufacturers.
- Legacy system integration friction:Hospital IT networks require costly middleware development to interface new hemodynamic platforms with existing electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hemodynamic Monitoring Market |
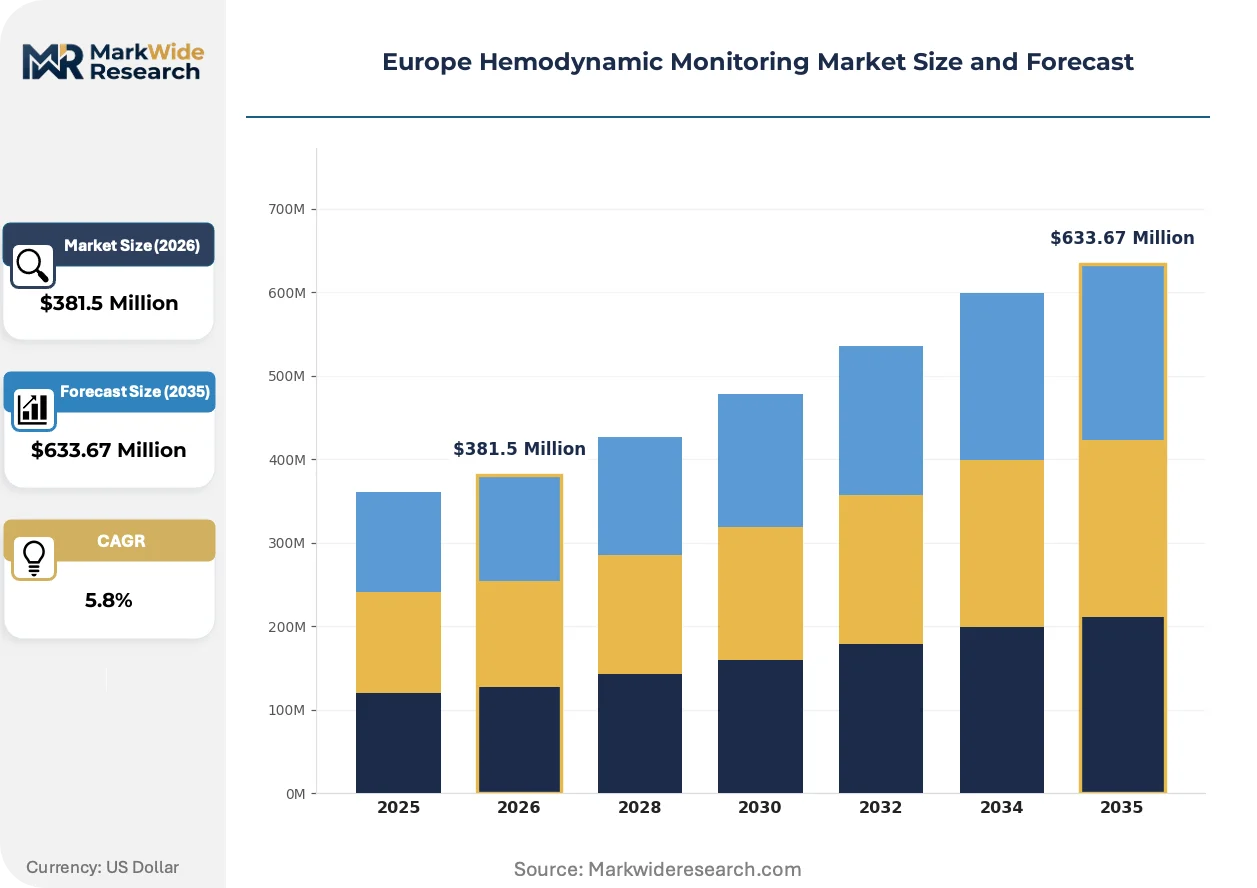
| Market Size in 2026 | $381.5 Million |
| Market Size in 2035 | $633.67 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Monitors, Non-invasive Monitors, Continuous Monitors, Handheld Monitors End User: Hospitals, Clinics, Ambulatory Surgical Centers, Emergency Departments Technology: Ultrasound, Electrical Impedance, Thermodilution, Bioimpedance Application: Surgery, Critical Care, Cardiology, Emergency Medicine |
| Companies Covered | ICU Medical Inc., Baxter International, Edwards Lifesciences Corporation, Cheetah Medical Inc., Deltex Medical Group plc., Koninklijke Philips NV, LiDCO Group plc., Siemens Healthineers, Getinge AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hemodynamic Monitoring Market Shifts & Advancements
Artificial intelligence inference at the point of care is reconfiguring how hemodynamic data translates into clinical decisions, compressing the gap between signal acquisition and therapeutic intervention.
Machine learning algorithms embedded in monitoring platforms are automating pattern recognition for impending circulatory collapse. Intensive care units in German tertiary centers are deploying these systems for early sepsis detection. The technology is automating alert prioritization that previously required continuous specialist attention, reducing cognitive load on nursing staff.
EMA's MDR post-market surveillance requirements are mandating real-world performance registries for invasive hemodynamic devices. Manufacturers must now submit periodic safety update reports with clinical follow-up data. Cardiac surgery applications face the steepest documentation burdens, driving consolidation toward firms with dedicated regulatory affairs infrastructure.
Anesthesia departments are unbundling monitor procurement from disposable supply contracts that historically locked hospitals into single-vendor ecosystems. Independent purchasing cooperatives in Benelux markets are negotiating hardware and consumables separately. France exhibits the fastest contract restructuring, with university hospitals leading the shift toward modular, multi-source supply arrangements.
Europe Hemodynamic Monitoring Market Segmentation
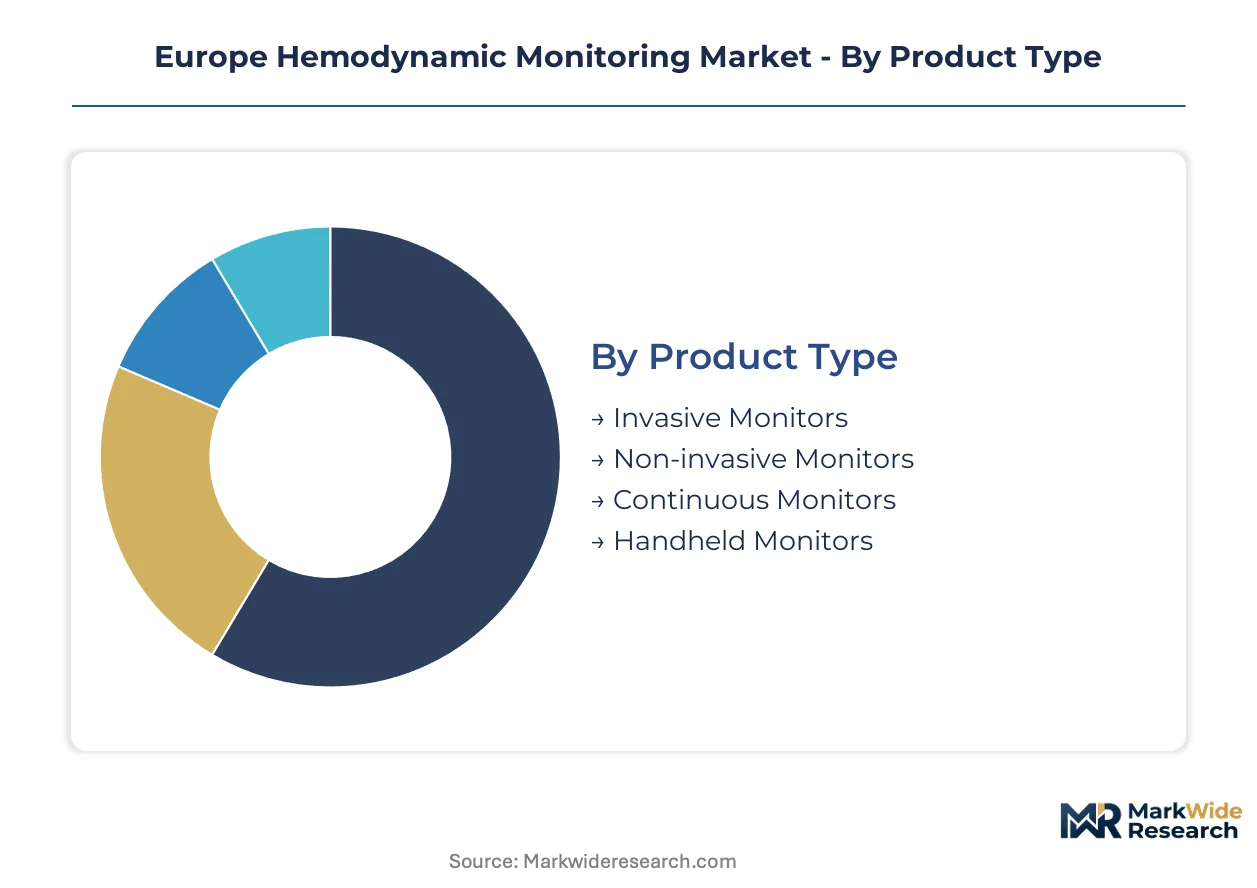
Segmentation in Europe hemodynamic monitoring reveals how procurement priorities diverge across care settings. Technology choices and product configurations align with specific clinical workflows rather than universal deployment.
Product Type:
Customization intensity varies from fully configurable modular platforms to standardized bedside units, with invasive systems demanding the highest calibration precision.
- Invasive Monitors:These systems employ arterial catheters and pulmonary artery lines to deliver continuous pressure readings and intermittent thermodilution cardiac output measurements. German university hospitals anchor procurement for these high-acuity platforms, driven by cardiac surgery volume expansion and EMA MDR compliance requirements that favor established manufacturers with robust quality systems.
- Non-invasive Monitors:Photoplethysmography and bioimpedance sensors eliminate catheter-related complications while maintaining precision thresholds acceptable for anesthesia monitoring. French and Benelux anesthesia departments concentrate demand here, seeking to reduce infection risks and shorten recovery times in perioperative settings.
- Continuous Monitors:Hybrid platforms integrate multiple sensing modalities for uninterrupted hemodynamic tracking across ICU stays.
- Handheld Monitors:Portable battery-powered units enable point-of-care assessment in ward environments and pre-hospital transport.
Leading the category by volume: Invasive Monitors. Growing fastest: Non-invasive Monitors.
End User:
Capital intensity and patient acuity determine procurement authority across institutional tiers.
- Hospitals:Tertiary centers command the largest installed base, with hybrid operating theaters and dedicated cardiac surgery units driving replacement cycles. German university hospitals set technical specifications that cascade through regional procurement networks, particularly for Class III invasive devices subject to EMA MDR clinical evaluation requirements.
- Clinics:Outpatient surgical facilities prioritize compact non-invasive systems for pre-operative screening and post-operative monitoring. Italian and Spanish private clinic chains concentrate demand here, constrained by reimbursement frameworks that limit capital expenditure per bed.
- Ambulatory Surgical Centers:Same-day procedure volumes favor streamlined monitoring with rapid setup protocols.
- Emergency Departments:Triage workflows in French and Italian networks create openings for handheld and portable continuous platforms.
Highest procurement authority: Hospitals. Fastest contract restructuring: Emergency Departments.
Technology:
Maturity gradients separate reference-standard methods from emerging sensor modalities.
- Thermodilution:The established reference method for cardiac output measurement uses cold saline injectate or thermal filament heating through pulmonary artery catheters. Cardiac surgery protocols across European centers maintain this as mandatory for high-risk procedures, entrenching demand despite catheter complication risks and EMA MDR documentation burdens.
- Ultrasound:Transthoracic and transesophageal echocardiography platforms deliver real-time anatomical and hemodynamic assessment without invasive instrumentation. Siemens Healthineers sustains technology leadership across German and Benelux networks, integrating probe technology with continuous monitoring workstations.
- Electrical Impedance:Thoracic bioimpedance measures stroke volume through skin electrode arrays for non-invasive trending.
- Bioimpedance:Whole-body and segmental impedance analysis supports fluid status assessment in critical care and dialysis settings.
Deepest margin pool: Thermodilution. Steepest adoption curve: Ultrasound.
Application:
Clinical setting determines performance requirements and reimbursement pathways.
- Surgery:Perioperative hemodynamic management demands precision calibration for fluid therapy and vasoactive drug titration. Cardiac, vascular, and major abdominal procedures across European centers drive demand for invasive and hybrid monitoring platforms, with German university hospitals anchoring procurement for integrated anesthesia workstations.
- Critical Care:Sepsis detection and hemodynamic optimization in ICU settings favor continuous multi-parameter platforms with automated alert systems. German tertiary centers deploy machine learning-embedded monitors for early circulatory collapse recognition, reducing nursing cognitive load.
- Cardiology:Cath lab and electrophysiology procedures require specialized pressure monitoring with high-frequency sampling.
- Emergency Medicine:Triage and resuscitation workflows in French and Italian emergency departments favor rapid-deployment handheld and portable systems.
Largest addressable base: Surgery. Fastest workflow transformation: Emergency Medicine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MedTech innovation zones in southern Germany and the Benelux corridor concentrate hemodynamic monitoring R&D, with EMA MDR compliance infrastructure anchoring manufacturing investment decisions.
Germany
University hospitals in Bavaria and Baden-Württemberg anchor procurement for invasive cardiac surgery platforms, with Charité Berlin and Heidelberg University Hospital setting technical specifications that cascade through regional networks. EMA MDR clinical evaluation requirements favor established manufacturers with dedicated regulatory affairs infrastructure. The Stuttgart-Mannheim medical technology cluster hosts specialized pressure transducer and fiber-optic component suppliers serving pan-European device assembly.
France
Parisian university hospitals and the Lyon-Grenoble medical corridor drive demand for non-invasive anesthesia monitoring as perioperative safety protocols tighten. ANSM post-market surveillance obligations align with EMA MDR periodic safety update requirements, elevating documentation burdens for invasive device entrants. The Île-de-France region concentrates procurement authority for hybrid operating theater installations across the national hospital network.
United Kingdom
NHS England's specialized commissioning frameworks concentrate high-acuity hemodynamic system procurement in London and Manchester tertiary centers. MHRA recognition of EMA MDR certificates streamlines market access for CE-marked devices post-Brexit transition. The Oxford-Cambridge life sciences arc hosts ultrasound-hemodynamic convergence research programs linking academic medical centers with device developers.
Italy
Milan and Rome university hospitals drive cardiac surgery volume expansion, with Lombardy region procurement frameworks influencing device selection across northern networks. National hospital sustainability mandates under EU Green Deal implementation redirect capital toward energy-efficient monitoring platforms. The Emilia-Romagna medical device manufacturing belt supplies pressure monitoring components to German and Swiss assemblers.
Netherlands
Amsterdam and Rotterdam academic medical centers anchor Benelux demand for integrated fluid management-hemodynamic systems. Independent purchasing cooperatives negotiate hardware and consumables separately, unbundling historical single-vendor lock-in arrangements. The Eindhoven health technology cluster supports photoplethysmography sensor development for non-invasive monitoring applications.
Europe Hemodynamic Monitoring Market Competitive Landscape
Top-tier vendors anchor premium invasive monitoring, while mid-scale specialists compete on non-invasive sensor modularity and anesthesia department workflow integration. The vendor base stratifies across three archetypes: integrated critical care platform providers, hemodynamic-focused pure-plays, and diversified MedTech conglomerates with monitoring divisions. M&A activity concentrates on regulatory capability acquisition and ultrasound-hemodynamic technology convergence. Geographic expansion through notified body relationship transfers dominates European market access strategy.
Within the diversified MedTech tier, ICU Medical Inc., Baxter International, and Edwards Lifesciences Corporation exemplify scale-driven competitive positioning. These California-based, Illinois-based, and California-based entities respectively occupy positions spanning disposable supply integration, fluid management system pairing, and transcatheter valve heritage anchoring. Their collective presence illustrates how North American headquarters with European regulatory infrastructure capture MDR transition consolidation benefits. Koninklijke Philips NV and Siemens Healthineers represent Dutch and German technology conglomerate archetypes, with imaging heritage translating into ultrasound-hemodynamic workstation development. Deltex Medical Group plc. and LiDCO Group plc. exemplify UK-based hemodynamic pure-plays navigating specialty market dynamics.
| Leading Market Players |
|---|
| ICU Medical Inc. |
| Baxter International |
| Edwards Lifesciences Corporation |
| Cheetah Medical Inc. |
| Deltex Medical Group plc. |
| Koninklijke Philips NV |
| LiDCO Group plc. |
| Siemens Healthineers |
| Getinge AB |
| Others |
Supply & Pricing Matrix
German university hospital procurement committees concentrate demand authority for invasive hemodynamic platforms, anchoring contract-based pricing with multi-year consumable bundling that favors established manufacturers with MDR compliance infrastructure.
Pricing Analysis
Short lead-time premiums for pressure transducer and fiber-optic cable components compress margins for device assemblers facing notified body bottlenecks. Pricing stratifies across premium, standard, and economy tiers based on calibration precision thresholds and EMA MDR certification status. Cost compression in non-invasive sensor tiers intensifies because photoplethysmography module commoditization accelerates. Ambulatory surgical centers exhibit highest price sensitivity; cardiac surgery units demonstrate lowest sensitivity due to protocol-mandated thermodilution requirements.
Supply Chain Analysis
Dual-sourcing requirements for critical pressure sensing elements mandate multi-supplier qualification across German, Swiss, and Austrian component manufacturers. Specialized fiber-optic cable production draws from Stuttgart-Mannheim and Zurich corridor facilities. Single-source vulnerability concentrates in pulmonary artery catheter thermistor assemblies. Distribution runs through regional hospital purchasing cooperatives in Benelux and direct tender frameworks in France and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into sensor component manufacturing represents the decisive vertical-integration race, with control over pressure transducer supply separating sustainable margin structures from procurement-dependent vulnerability.
For Market Incumbents: Lock in exclusive supply agreements with Stuttgart-Mannheim fiber-optic component manufacturers before MDR transition consolidates access around compliant assemblers. Expand captive production of thermistor elements to offset single-source vulnerability in pulmonary artery catheter assemblies. Prioritize notified body relationship transfers into German and Dutch conformity assessment bodies to compress certificate issuance timelines. For New Entrants and Emerging Players: Begin with emergency medicine handheld platforms in French and Italian triage networks where procurement authority fragments across departmental budgets and MDR documentation burdens deter invasive device entrants. Target photoplethysmography sensor modularity for anesthesia departments unbundling from historical single-vendor disposable contracts. Pursue independent purchasing cooperative certification in Netherlands and Belgium to bypass incumbent hospital system lock-in. For Investors and Strategic Acquirers: The window for entry favors hemodynamic pure-plays with dedicated regulatory affairs infrastructure and existing EMA MDR technical documentation. Acquisition candidates should demonstrate notified body relationship depth and ultrasound-hemodynamic convergence capability. Watch for consolidation signals when smaller manufacturers exit due to post-market surveillance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDR certificate issuance compression captures share from compliance-lagged competitors. |
| Hospital System Partnership | Charité Berlin and Heidelberg procurement anchoring cascades specifications regionally. |
| Software Companion Development | Machine learning-embedded sepsis detection reduces nursing cognitive load in German ICUs. |
| Backward Integration into Sensors | Captive pressure transducer supply insulates margin from component spot market volatility. |
| Reimbursement Strategy | ANSM and NHS specialized commissioning alignment unlocks French and UK hospital access. |
Research Methodology
EMA MDR guidance documents, hospital procurement databases, and GPO contract repositories formed the secondary backbone, supplemented by primary interviews with cardiac surgery department heads, biomedical engineers, anesthesia directors, and hospital purchasing committee chairs across German, French, and Benelux tertiary centers. Bottom-up and top-down triangulation validated installed base estimates against replacement cycle assumptions.
Bottom-up modeling anchored volume projections to cardiac surgery procedural volumes and ICU bed expansion trajectories, while top-down checks calibrated penetration rates against healthcare expenditure patterns across the projection horizon. Segmentation dimensions included product type, end-user institution tier, technology modality, and application setting. CAGRs derived from weighted average of procedural growth and technology substitution elasticities, with EMA MDR transition timelines and EU Green Deal procurement mandates as scenario inputs.
Underlying measurement precision varies by segment; invasive monitor revenue estimates carry tighter precision than handheld device projections due to concentrated procurement transparency. Forecasts reflect assumptions about notified body capacity expansion and cardiac surgery volume trajectory. Deviation in MDR certificate issuance timelines or German university hospital capital budget allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Patient Monitoring Accessories Market
Patient Monitoring
Japan Patient Care Monitoring Equipment Market
Patient Monitoring
Hemoglobin Monitor Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Saudi Arabia Patient Monitoring Market
Patient Monitoring
Pain Monitoring Devices Market
Patient Monitoring
Europe Wireless Healthcare Market
Patient Monitoring
China Patient Monitoring Market
Patient Monitoring
Pre-Mature Baby Monitoring Equipment Market
Patient Monitoring
Global Patient Temperature Monitoring Market
Patient Monitoring
Wearable ECG Monitors Market
Patient Monitoring
Fetal and Neonatal Heart Monitor Market
Patient Monitoring
Global Vital Sign Monitoring Market
Patient Monitoring
Asia-Pacific Respiratory Monitoring Market
Patient Monitoring
Wearable Cardiac Monitors Market
Patient Monitoring
Global Home Blood Pressure Monitoring Devices Market