
 Cardiac Rhythm Management Market | 2026-2036
Cardiac Rhythm Management Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Rhythm Management Market Intelligence
Hospital purchasing power is decoupling from legacy group purchasing organizations as ambulatory surgical centers and specialized electrophysiology labs fragment the buyer landscape. Medtronic leverages its integrated cath-lab ecosystem to sustain channel control across implant and monitoring workflows. Boston Scientific Corporation anchors its position through deep specialization in subcutaneous defibrillator platforms. Abbott differentiates via leadless pacemaker miniaturization that reduces complication profiles in elderly cohorts.
Cardiac rhythm management encompasses implantable and external devices that detect, monitor, and correct abnormal heart rhythms through electrical stimulation, anti-tachycardia pacing, or defibrillation shocks delivered at 25–40 joules. These systems combine lithium-iodine or lithium-silver vanadium oxide power cells with hermetically sealed titanium housings to ensure decade-long biocompatibility in vivo. Pacemakers and defibrillators dominate current revenue pools, though leadless pacemakers and remote monitoring systems represent the fastest-expanding margin segments as hospitals seek to reduce lead-extraction morbidity and shift follow-up care outside traditional clinic walls. Electrophysiology equipment retains structural importance in procedural throughput but faces longer capital replacement cycles than implantables.
FDA premarket notification and premarket approval pathways govern US market access, while the EU MDR and CE marking requirements under notified body oversight tighten clinical evidence standards for implantable active devices. Japan's PMDA enforces QMS ministerial ordinances that add localization complexity for foreign manufacturers. Stakeholders must monitor regulatory divergence between FDA breakthrough device designations and EU MDR clinical investigation mandates when prioritizing geographic launch sequencing.
Market Dynamics
Hospital procurement of cardiac rhythm devices is decoupling from legacy group purchasing organizations as ambulatory surgical centers build independent electrophysiology capabilities and demand direct manufacturer relationships.
Growth Catalysts
- Aging demographics in Germany and Japan:Expanding elderly populations with atrial fibrillation burden drive replacement device volumes and premium-tier uptake.
- EU MDR clinical investigation mandates:Stricter evidence requirements for implantable active devices accelerate consolidation toward manufacturers with robust trial infrastructure.
- Leadless pacemaker miniaturization:Reduced lead-extraction morbidity in elderly cohorts shifts physician preference away from transvenous systems.
Market Restraints
- Lithium-silver vanadium oxide supply concentration:Battery chemistry dependency on limited specialty chemical suppliers creates input cost volatility.
- FDA premarket approval timelines:Extended review cycles for novel defibrillator algorithms delay commercialization and compress effective patent life.
- Substitute monitoring modalities:Wearable ECG patches and smartphone-based arrhythmia detection erode demand for traditional event recorders.
Strategic Opportunities
- Underpenetrated ambulatory surgical centers:United States outpatient facilities expanding electrophysiology suites seek turnkey device-and-service bundles.
- Japan PMDA QMS localization:Ministerial ordinance compliance creates partnership opportunities for domestic distributors with regulatory expertise.
- Remote monitoring convergence with telehealth platforms:Integration of device data streams into virtual care workflows opens subscription revenue models.
Industry Challenges
- Electrophysiologist training pipeline:Procedural complexity of leadless implantation and subcutaneous defibrillator placement outpaces fellowship program expansion.
- Legacy device interoperability:Proprietary communication protocols between pacemakers and monitoring systems complicate hospital IT integration and data aggregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Rhythm Management Market |
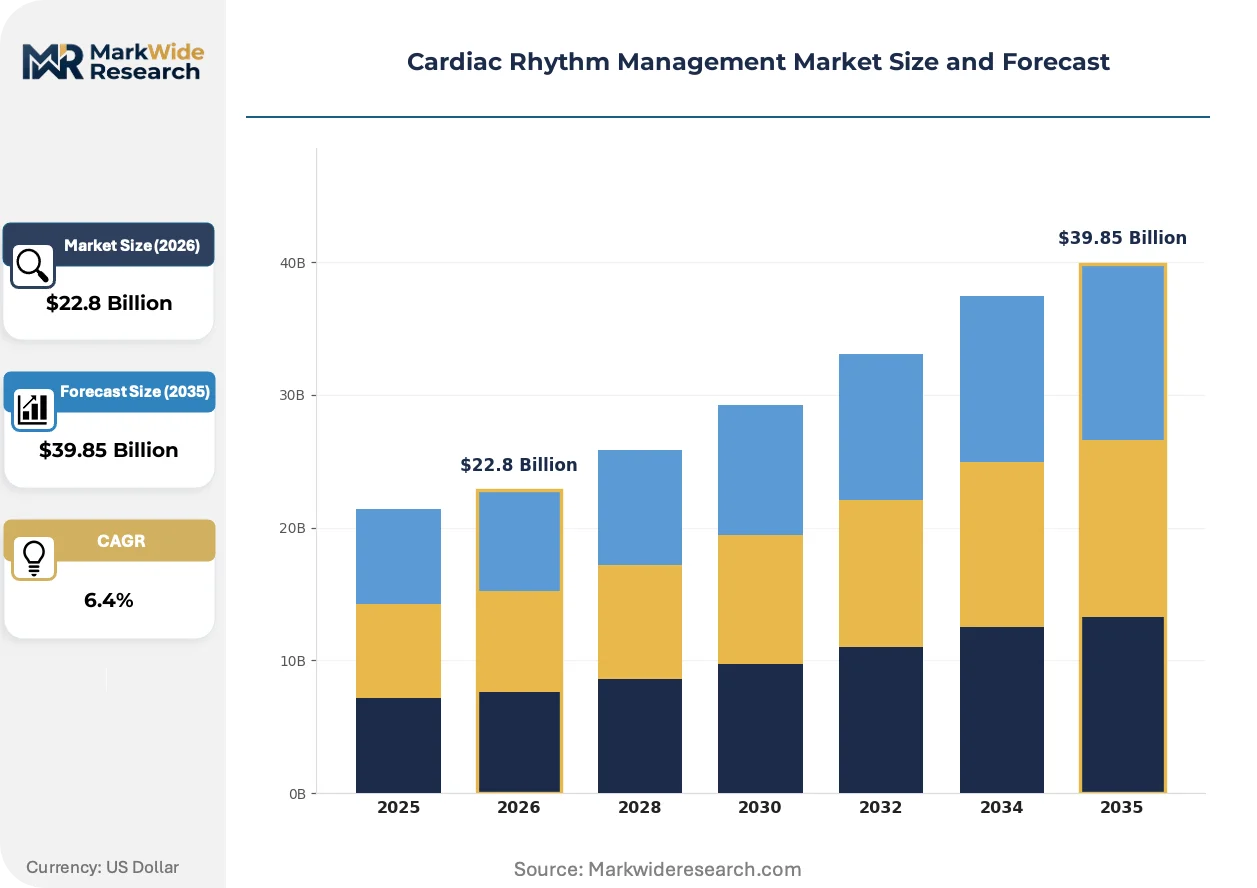
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Pacemakers, Defibrillators, Monitoring Devices, Electrophysiology Equipment End User: Hospitals, Cardiology Clinics, Home Care Settings, Diagnostic Centers Technology: Leadless Pacemakers, Bi-Ventricular Devices, Subcutaneous Defibrillators, Remote Monitoring Systems Application: Atrial Fibrillation, Heart Failure, Ventricular Tachycardia, Arrhythmia |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, Biotronik, Koninklijke Philips N.V., Stryker, Zoll Medical Corporation, MicroPort Scientific Corporation, LivaNova PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Rhythm Management Market Strategic Shifts & Innovations
Device miniaturization and battery chemistry advances are compressing form factors while extending longevity, enabling migration of complex procedures into lower-acuity settings and reshaping competitive differentiation around biocompatibility metrics.
Leadless pacemaker technology is expanding into broader patient indications previously reserved for transvenous systems. Electrophysiology labs in the United States and Germany are adopting these devices for septal implantation in patients with compromised venous access. The technology is expanding into the conventional pacemaker market by eliminating lead-related complications that drive long-term healthcare utilization.
EU MDR transition requirements for implantable active devices are compressing notified body capacity and extending certification timelines. Manufacturers must generate additional clinical evidence under stricter biocompatibility and electrical safety standards. High-risk device categories face the most severe bottlenecks, forcing prioritization of core product lines over pipeline extensions.
Hospital purchasing committees are fragmenting device procurement across specialized electrophysiology labs and ambulatory surgical centers. Traditional cath-lab bundled contracts are yielding to site-specific agreements with distinct service-level requirements. This pattern is most visible in the United States where Medicare reimbursement differentials between inpatient and outpatient settings accelerate site-of-care migration.
Cardiac Rhythm Management Market Segmentation
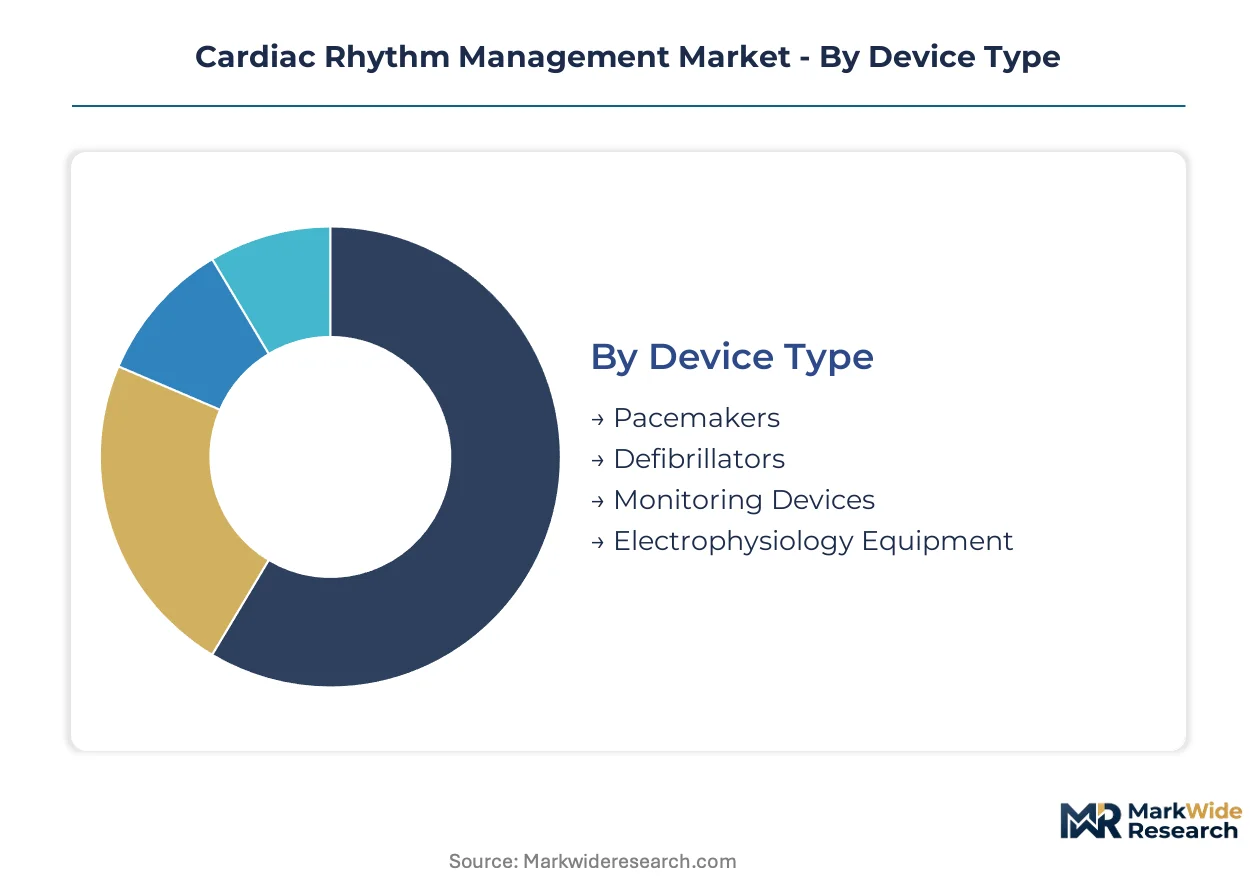
Device taxonomy in cardiac rhythm management determines reimbursement pathways, regulatory classification, and procurement workflows. Segmentation by implantable versus external systems, acute versus ambulatory settings, and transvenous versus leadless architectures shapes manufacturer R&D allocation and hospital capital planning.
Device Type:
Hospital capital committees weight replacement cycles against complication rates when allocating budgets across implantable and external systems.
- Pacemakers:Lithium-iodine powered units with titanium housings deliver electrical impulses at 2.5–5 volts to maintain heart rate. Demand concentrates in Germany and Japan where aging populations drive dual-chamber device uptake for sinus node dysfunction.
- Defibrillators:These systems combine bradycardia pacing with high-voltage capacitors delivering 25–40 joule shocks for ventricular arrhythmia termination. Transvenous ICDs dominate hospital procurement in the United States, though subcutaneous alternatives gain traction in patients with compromised vascular access.
- Monitoring Devices:External event recorders and implantable loop diagnostics capture episodic arrhythmias for ambulatory diagnosis.
- Electrophysiology Equipment:Three-dimensional mapping systems and radiofrequency ablation generators support catheter-based rhythm correction procedures.
Pacemakers lead on scale; leadless variants within this category lead on momentum.
End User:
Site-of-care migration toward lower-acuity settings is fragmenting purchasing authority and service-level expectations.
- Hospitals:Tertiary centers with electrophysiology labs manage complex device implants and lead extractions. Academic medical centers in the United States anchor high-volume implant programs and fellowship training pipelines.
- Cardiology Clinics:Specialized outpatient facilities perform generator replacements and device interrogations. These sites in Germany are expanding independent electrophysiology capabilities to capture outpatient reimbursement differentials.
- Home Care Settings:Remote monitoring infrastructure enables transtelephonic follow-up and arrhythmia surveillance outside clinical walls.
- Diagnostic Centers:Standalone facilities provide Holter monitoring and event recorder analysis for primary care referral networks.
Hospitals retain volume concentration; cardiology clinics are expanding most quickly.
Technology:
Miniaturization and wireless communication architectures differentiate premium tiers from standard-of-care alternatives.
- Leadless Pacemakers:Self-contained units deploy directly into the right ventricle via femoral catheter, eliminating lead-related endocarditis and extraction risks. Septal implantation techniques are expanding indications in the United States for patients with venous occlusion.
- Bi-Ventricular Devices:Cardiac resynchronization therapy coordinates left and right ventricular contraction through coronary sinus lead placement. Heart failure programs in Japan prioritize these systems for NYHA Class III patients with left bundle branch block.
- Subcutaneous Defibrillators:Lead-free shock delivery via parasternal electrode array reduces vascular complications in younger patients with inherited channelopathies.
- Remote Monitoring Systems:Cellular and Bluetooth-enabled transmitters automate device data transmission to cloud-based surveillance platforms.
Bi-ventricular devices lead on scale; leadless pacemakers gain share fastest.
Application:
Clinical indication drives device selection between rate control, rhythm restoration, and sudden death prevention strategies.
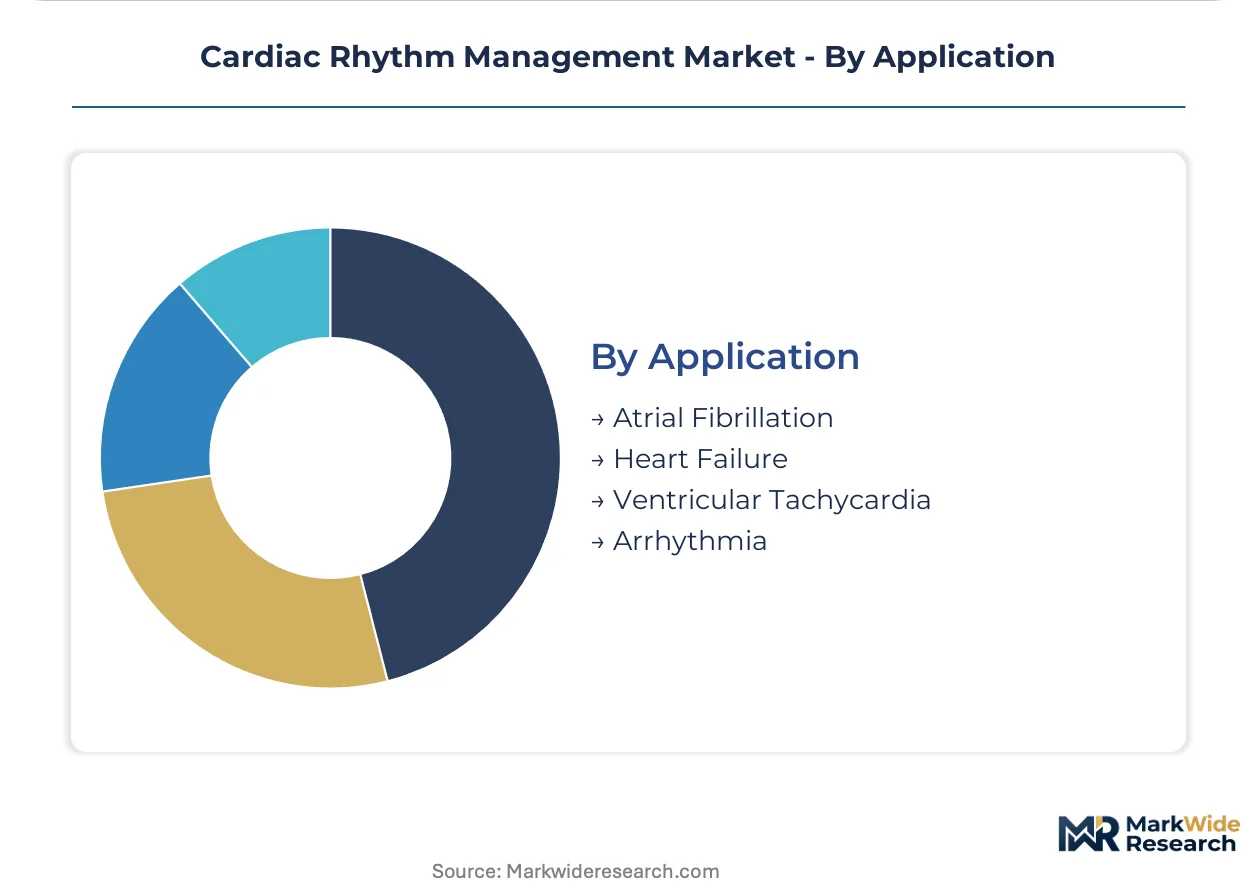
- Atrial Fibrillation:The most prevalent sustained arrhythmia drives demand for anticoagulation-integrated monitoring and ablation support systems. Stroke prevention protocols in the United States mandate rhythm surveillance in anticoagulated patients.
- Heart Failure:Reduced ejection fraction patients require resynchronization therapy and defibrillator backup. German heart failure networks coordinate device therapy with guideline-directed medical therapy.
- Ventricular Tachycardia:Life-threatening arrhythmias mandate ICD therapy with anti-tachycardia pacing algorithms.
- Arrhythmia:General diagnostic category encompasses bradyarrhythmias, conduction disorders, and unexplained syncope evaluations.
Atrial fibrillation leads on scale; heart failure applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States sustains higher reimbursement rates for complex electrophysiology procedures than Germany, yet both markets prioritize leadless pacemaker adoption as aging populations expand device-eligible cohorts.
United States
Medicare reimbursement differentials between inpatient and outpatient settings accelerate site-of-care migration toward ambulatory surgical centers. FDA premarket approval pathways govern novel defibrillator algorithm submissions, extending review timelines for breakthrough device designations. The Cleveland Clinic and Mayo Clinic anchor high-volume implant programs that train electrophysiology fellows in leadless septal implantation techniques.
Germany
Heart failure networks coordinate cardiac resynchronization therapy with guideline-directed medical therapy across statutory health insurance panels. EU MDR clinical investigation mandates tighten biocompatibility standards for implantable active devices, compressing notified body capacity. The Rhine-Ruhr metropolitan region concentrates university hospital electrophysiology labs that drive dual-chamber pacemaker uptake for sinus node dysfunction.
Japan
NYHA Class III patients with left bundle branch block drive bi-ventricular device prioritization within integrated heart failure pathways. PMDA QMS ministerial ordinances enforce localization requirements that add regulatory complexity for foreign manufacturers. Tokyo and Osaka medical centers anchor premium-tier device procurement as aging demographics expand atrial fibrillation burden.
China
Domestic manufacturers expand electrophysiology equipment production to capture catheter ablation procedure growth in tier-one hospitals. NMPA medical device registration pathways require in-country clinical trials for Class III implantable devices. The Yangtze River Delta clusters medical device innovation zones that attract joint ventures for leadless pacemaker technology transfer.
Cardiac Rhythm Management Market Key Industry Players
United States producers anchor the premium implantable tier; German and Swiss specialists hold positions in electrophysiology equipment and biocompatible materials. The vendor base concentrates around integrated cath-lab ecosystems, subcutaneous defibrillator platforms, and leadless miniaturization architectures. Three archetypes dominate: diversified medtech conglomerates with full cardiac portfolios, pure-play electrophysiology device specialists, and emerging Asia-Pacific manufacturers with cost-optimized production. Consolidation through strategic acquisitions and technology licensing agreements reshapes competitive positioning as EU MDR compliance costs escalate.
Among diversified medtech conglomerates, Medtronic and Boston Scientific Corporation exemplify integrated ecosystem strategies that span implantable devices through procedural monitoring workflows. Abbott occupies a position within the miniaturization-focused tier, representing leadless pacemaker specialization that reduces complication profiles. These three companies anchor the competitive structure as hospital procurement fragments across ambulatory surgical centers and specialized electrophysiology labs.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| Biotronik |
| Koninklijke Philips N.V. |
| Stryker |
| Zoll Medical Corporation |
| MicroPort Scientific Corporation |
| LivaNova PLC |
| Others |
Cost & Logistics Intelligence
Lithium-silver vanadium oxide feedstock from specialty chemical suppliers in Japan and the United States flows through battery cell manufacturers into tiered implantable device pricing, with raw material concentration amplifying cost volatility at the premium tier.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for lithium-iodine battery cells used in standard pacemaker tiers. Three-tier pricing structure across premium, standard, and economy levels separates leadless miniaturized systems from transvenous dual-chamber devices and basic single-chamber units. Pricing pressure stems from EU MDR compliance investments compressing margins on legacy product lines. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement differentials, while academic medical centers absorb premium tiers for complex implantation training value.
Supply Chain Analysis
Single-source vulnerability sits with Japanese suppliers of high-purity titanium for hermetic device housings. Manufacturing concentrates in Ireland, Switzerland, and Costa Rica for FDA-registered implantable production. Raw material dependencies span lithium-iodine cathode materials, tantalum capacitors, and medical-grade silicone lead insulation. Tariff exposure on Chinese-sourced electronic components creates input cost uncertainty. Distribution runs through specialized cardiac device distributors with cath-lab inventory management contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cardiac rhythm management market functions as a stable compounder anchored by aging demographics in developed economies that sustain replacement device volumes across economic cycles.
For Market Incumbents: To counter ambulatory surgical center procurement fragmentation, anchor hospital system partnerships through integrated remote monitoring platforms. Backward integration into battery cell manufacturing mitigates lithium-silver vanadium oxide supply concentration. Prioritize EU MDR clinical investigation infrastructure to compress certification timelines relative to competitors. For New Entrants and Emerging Players: Underserved cardiology clinics in Germany seeking independent electrophysiology capabilities represent the most penetrable buyer archetype. White-space targets include turnkey device-and-service bundles for outpatient settings and Japan PMDA QMS localization partnerships. A reimbursement strategy aligned with site-of-care migration accelerates initial traction. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs exceed mid-tier revenue bases. Long-term viability favors manufacturers with integrated cath-lab ecosystems spanning implant through monitoring workflows. Acquisition target archetype: electrophysiology equipment specialists with 3D mapping software assets. Signal to watch: notified body capacity constraints extending CE marking timelines beyond viable commercialization windows.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review for leadless pacemaker algorithms compresses time-to-revenue for novel miniaturization platforms. |
| CE Marking Pathway under EU MDR | Notified body clinical investigation mandates reshape competitive positioning toward trial-capable manufacturers. |
| Hospital System Partnership | Integrated cath-lab contracts with Mayo Clinic or Cleveland Clinic anchor high-volume implant training pipelines. |
| Software Companion Development | Remote monitoring platforms with Bluetooth-enabled transmitters open subscription revenue outside clinic walls. |
| Reimbursement Strategy | Medicare outpatient procedure codes for ambulatory surgical centers capture site-of-care migration value. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down battery chemistry supply tracking forms the analytical core. Primary interviews with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified body registers, CMS Medicare reimbursement databases, and hospital procurement contract repositories. Triangulation across stakeholder inputs and regulatory filings anchors volume estimates.
Historical trendline analysis of implant procedure volumes, device replacement cycles, and regulatory approval timelines informed projection frameworks across the analysis window. Segmentation dimensions modeled include device architecture, site-of-care setting, technology tier, and clinical indication. CAGRs derived from fitted growth curves applied to procedure volume forecasts and average selling price trajectories. Industry-specific inputs incorporate electrophysiologist training pipeline expansion rates and lead-extraction morbidity trend data.
Underlying measurement precision varies by segment; leadless pacemaker volumes carry tighter precision than external monitoring device estimates given concentrated manufacturer disclosure. Forecasts reflect assumptions around regulatory timeline stability, reimbursement rate continuity, and raw material supply availability. Device substitution risk from wearable ECG technologies and electrophysiologist workforce constraints represent primary revision factors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Left Atrial Appendage (LAA) Closure Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Asia-Pacific Cardiac Monitoring Market
Cardiology Equipment
Cardiac Catheterization Market
Cardiology Equipment
Global Cardiac Mapping Market
Cardiology Equipment
Cardiopulmonary Auto-Transfusion System Market
Cardiology Equipment
Cardiac Marker Analyzer Market
Cardiology Equipment
Global Cardiac Restoration Systems Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Global Cardiology Electrodes Market
Cardiology Equipment
Medical Smart Stethoscopes Market
Cardiology Equipment
Global Coronary Artery Bypass Grafting Market
Cardiology Equipment
Heart Scan Market
Cardiology Equipment
Intracardiac Imaging Market
Cardiology Equipment
Europe Cardiac Arrhythmia Monitoring Devices Market